
 Hydrographic Equipment Market | 2026-2036
Hydrographic Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrographic Equipment Market Outlook
Subscription-based data processing and cloud-hosted bathymetric analytics is restructuring how hydrographic equipment vendors monetize hardware deployments. Kongsberg Gruppen ASA leverages its integrated software stack to anchor long-term service contracts alongside sonar system sales. Teledyne Technologies Inc. competes through vertical integration across acoustic sensors and autonomous underwater vehicle platforms. EdgeTech specializes in high-frequency side-scan sonar modules that sustain premium positioning in shallow-water survey niches.
Hydrographic equipment encompasses sonar-based instruments, positioning systems, and data acquisition platforms engineered to measure water depth, seabed topography, and submerged object detection with sub-meter accuracy; multibeam echo sounders transmit acoustic pulses across wide swaths and process return signals through beam-forming algorithms to generate three-dimensional bathymetric maps for port construction, cable routing, and habitat assessment. Multibeam Systems command the largest installed base among product categories due to their throughput advantage over single-beam alternatives in commercial surveying. Environmental Monitoring applications are expanding fastest within the application dimension as coastal zone management agencies mandate pre- and post-dredging seabed surveys. Research Institutions represent a concentrated margin pool within end users because their procurement cycles prioritize calibration precision and vendor technical support over unit cost minimization.
The International Hydrographic Organization maintains standards for nautical chart accuracy that directly shape equipment calibration requirements and product certification pathways. The EU Marine Strategy Framework Directive and national implementations by France's CNIL-aligned environmental agencies and Germany's Federal Maritime and Hydrographic Agency compel member states to map seabed habitats with standardized acoustic methodologies. China's Ministry of Ecology and Environment enforces marine spatial planning surveys that dictate domestic procurement specifications for domestic and imported systems. Stakeholders must monitor how evolving autonomous vessel regulations in Norway, the United Kingdom, and China reshape deployment protocols for unmanned surface vehicles carrying hydrographic payloads.
Market Dynamics
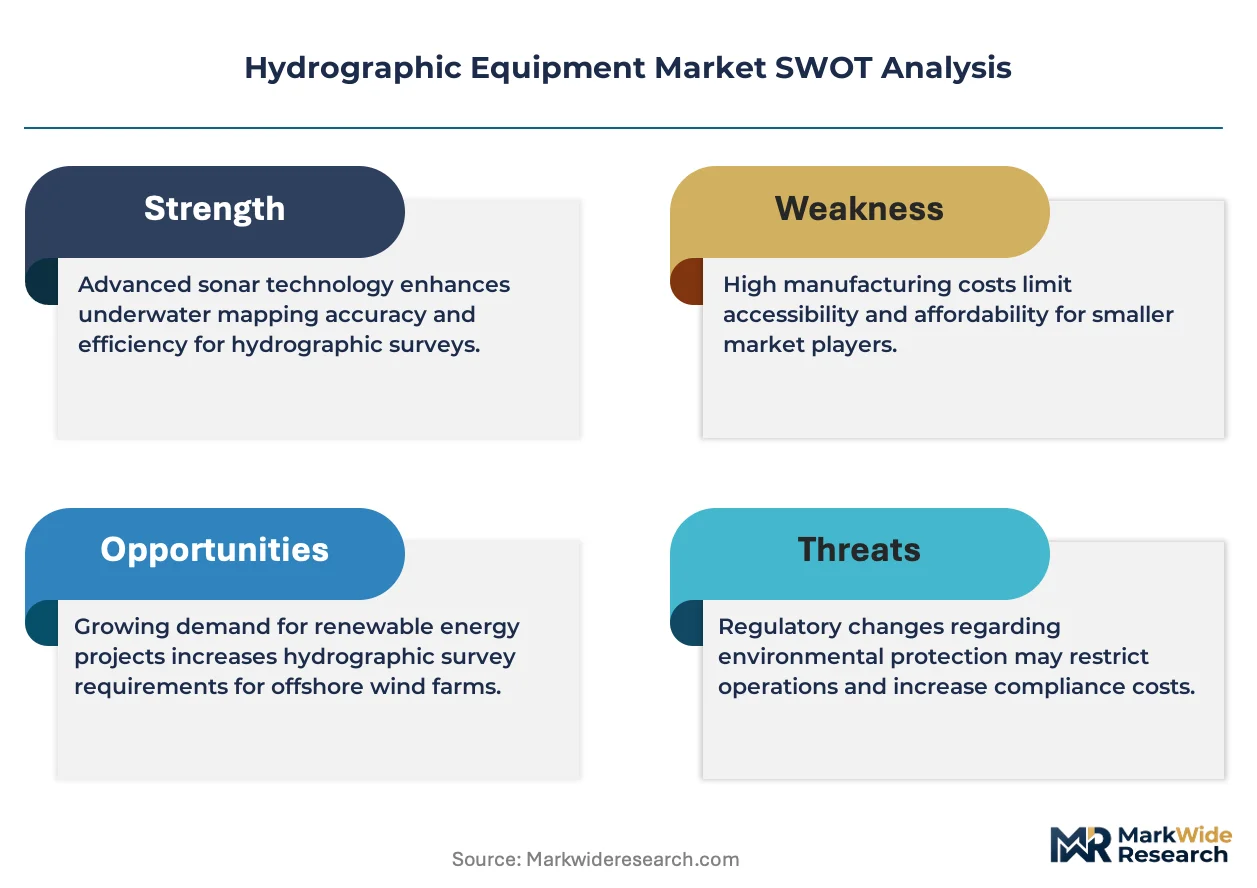
Subscription-based data processing is restructuring how hydrographic equipment vendors monetize hardware deployments, anchoring long-term service contracts alongside sonar system sales and compressing traditional transactional revenue models.
Growth Catalysts
- EU Marine Strategy Framework Directive:Member states must map seabed habitats with standardized acoustic methodologies, compelling systematic multibeam sonar procurement across coastal zone management agencies.
- Offshore wind farm lease obligations:Developers in the North Sea and Baltic are expanding survey fleets to meet pre-construction seabed assessment requirements under national implementations of marine spatial planning directives.
- Autonomous underwater vehicle integration:Unmanned platforms carrying hydrographic payloads are displacing crewed vessels in hazardous shallow-water survey niches, reducing operational costs and deployment timelines.
Market Restraints
- Specialized sensor supply concentration:High-frequency transducer manufacturing concentrates among a limited set of acoustic engineering facilities in Northern Europe and East Asia, creating input bottlenecks during demand surges.
- Calibration infrastructure scarcity:Sub-meter accuracy requirements demand scarce test tank facilities and certified reference standards, extending lead times for system commissioning.
- Skilled hydrographer shortages:Beam-forming algorithm expertise and acoustic data interpretation skills remain concentrated within aging specialist workforces, constraining fleet expansion velocity.
Strategic Opportunities
- Brazil's pre-salt basin mapping:Petrobras and international operators require extensive bathymetric surveys for subsea infrastructure routing, creating demand for deep-water multibeam systems.
- Cloud-hosted bathymetric analytics:Vendors can unbundle processing software from hardware sales, capturing recurring revenue through SaaS models targeting research institutions with limited capital budgets.
- Environmental Monitoring mandates:Pre- and post-dredging seabed surveys are expanding fastest within coastal zone management, driven by habitat protection requirements under France's CNIL-aligned environmental agencies.
Industry Challenges
- IHO certification timelines:The International Hydrographic Organization's equipment standards and nautical chart accuracy requirements create extended product validation cycles before commercial deployment.
- Legacy system integration friction:Existing single-beam echo sounder fleets and proprietary data formats complicate multibeam upgrade paths for port authorities with constrained modernization budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrographic Equipment Market |
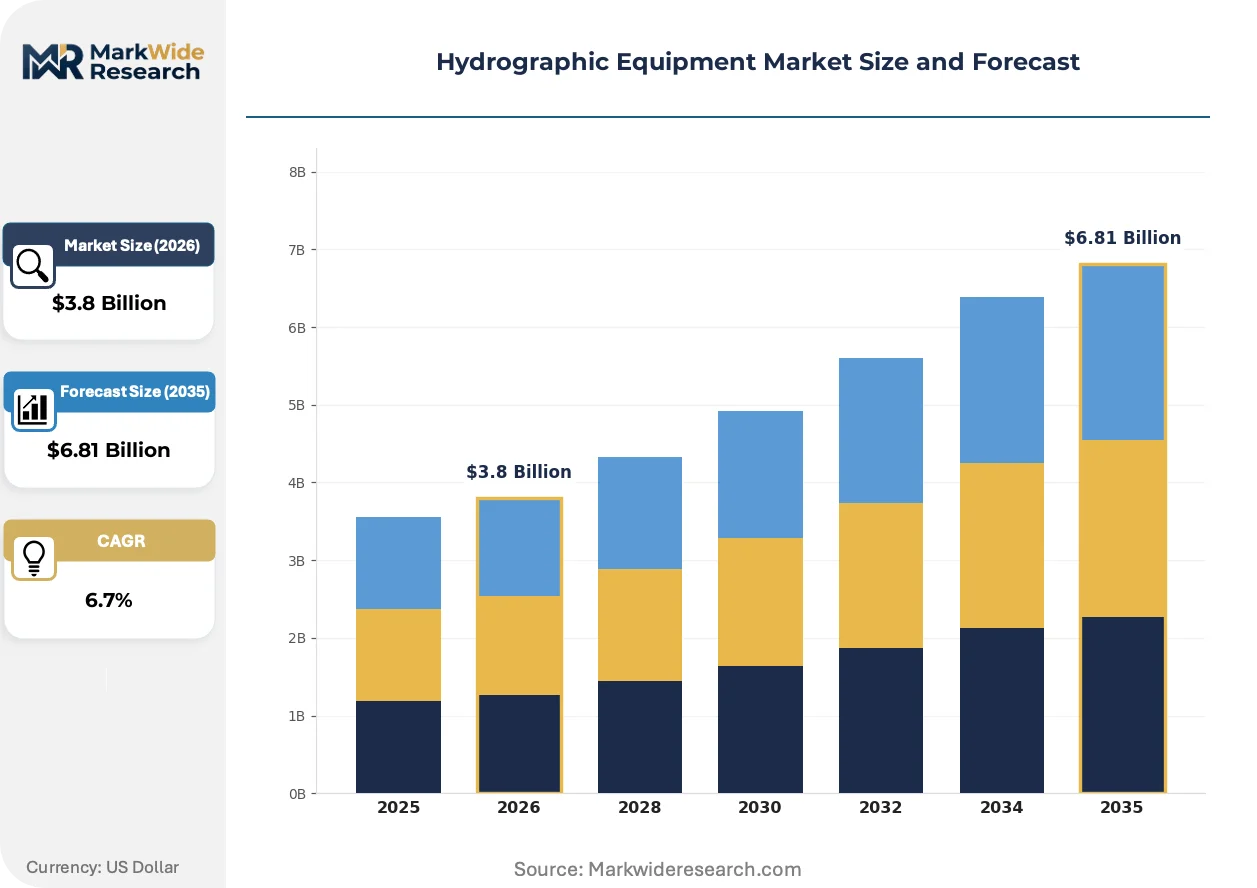
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Echo Sounders, Multibeam Systems, Single-beam Systems, Portable Equipment Application: Marine Surveying, Environmental Monitoring, Dredging, Navigation End User: Government Agencies, Research Institutions, Commercial Companies, Environmental Consultants Technology: Sonar Technology, GPS Technology, Data Processing, Optical Systems |
| Companies Covered | Kongsberg Gruppen ASA, Teledyne Technologies Inc., EdgeTech, iXblue SAS, Innomar Technologie GmbH, Sonardyne International Ltd., Raytheon Technologies Corporation, SyQwest Inc., Tritech International Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrographic Equipment Market Strategic Shifts
Acoustic sensing hardware is converging with autonomous platform architectures and cloud-native processing stacks, compressing survey timelines while fragmenting traditional equipment bundling strategies.
Multibeam echo sounders are expanding into unmanned surface vehicle deployments as beam-forming algorithms enable real-time 3D bathymetric mapping from compact payloads. Offshore wind developers in the North Sea are adopting these configurations for rapid lease site characterization. The technology is expanding into shallow-water niches previously served by crewed vessels, displacing day-rate contracting models with capital-light autonomous operations.
China's Ministry of Ecology and Environment enforces marine spatial planning surveys that dictate domestic procurement specifications for seabed mapping programs. Domestic manufacturers must align with GB standards and MEE technical guidelines to qualify for state-funded coastal infrastructure projects. Foreign suppliers face compliance complexity as certification pathways diverge from IEC and IHO frameworks, favoring local system integrators with established regulatory relationships.
Research institutions are unbundling after-sales technical support from hardware acquisition, negotiating standalone calibration contracts and software maintenance agreements. This behavioral shift compresses upfront capital commitments while extending vendor revenue visibility through multi-year service engagements. The pattern is most visible in Norway and the United Kingdom, where university consortia pool resources for shared beam-forming expertise and reference standard access.
Hydrographic Equipment Market Segmentation
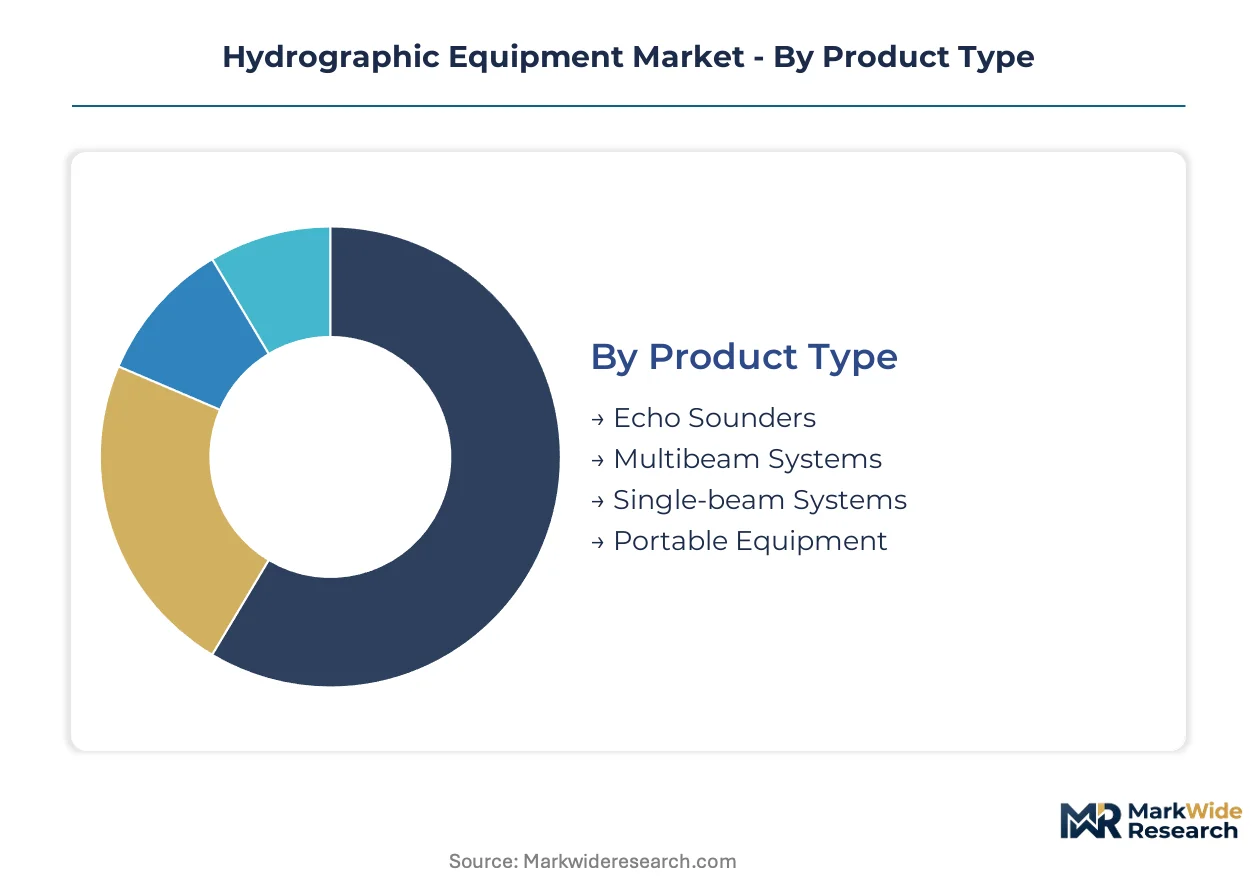
Hydrographic equipment segmentation reflects divergent certification burdens across product categories and end-use contexts. IHO standards, national maritime regulations, and environmental compliance frameworks reshape procurement specifications for each segment.
Product Type:
IHO certification timelines vary substantially across product categories, with multibeam systems facing the most rigorous beam-forming validation protocols while portable equipment navigates streamlined self-certification pathways.
- Multibeam Systems:These transmit acoustic pulses across wide swaths and process returns through beam-forming algorithms to generate three-dimensional bathymetric maps. Norway, the United Kingdom, and China absorb the largest procurement volumes for seabed mapping programs under the EU Marine Strategy Framework Directive and comparable national mandates. Calibration infrastructure scarcity extends commissioning lead times for these systems.
- Echo Sounders:Single-frequency and dual-frequency variants measure water depth through acoustic pulse timing, serving as the foundational instrumentation for nautical charting. Port authorities in France and Germany prioritize these units for routine channel maintenance surveys under BSH and CNIL-aligned environmental oversight, though legacy system integration friction complicates upgrade paths.
- Single-beam Systems:Narrow-beam depth sensors remain prevalent in inland waterway and small-craft navigation applications where swath coverage requirements are minimal.
- Portable Equipment:Compact, battery-operated units enable rapid deployment for reconnaissance surveys and emergency response operations without vessel-mounted installation.
Leading the category by volume: Multibeam Systems. Growing fastest: Portable Equipment.
Application:
Cost tier differentiation separates capital-intensive offshore survey contracts from recurring coastal monitoring services, with environmental compliance mandates reshaping budget allocation across application segments.
- Environmental Monitoring:Pre- and post-dredging seabed assessments, habitat mapping, and coastal zone management surveys dominate procurement from France's CNIL-aligned agencies and Germany's Federal Maritime and Hydrographic Agency. These applications are expanding most quickly within the segment as marine spatial planning directives harden enforcement timelines.
- Marine Surveying:Systematic bathymetric data collection for nautical chart production, cable route planning, and offshore infrastructure siting commands sustained investment from hydrographic offices and energy developers. Norway and the United Kingdom anchor demand through North Sea wind farm lease obligations.
- Dredging:Volume verification and seabed condition monitoring support port maintenance and coastal engineering projects with recurring survey requirements.
- Navigation:Real-time depth monitoring and obstacle detection serve commercial shipping lanes and recreational boating corridors with standardized accuracy thresholds.
Environmental Monitoring claims the steepest expansion trajectory. Marine Surveying retains the largest revenue base.
End User:
Customer type determines procurement rhythm, with research institutions negotiating multi-year calibration contracts while government agencies follow rigid budget cycles and commercial operators prioritize fleet utilization rates.
- Government Agencies:National hydrographic services, maritime administrations, and coastal management authorities mandate IHO-compliant equipment for official nautical chart production. China's Ministry of Ecology and Environment enforces marine spatial planning surveys that dictate domestic procurement specifications.
- Research Institutions:University consortia and oceanographic institutes prioritize calibration precision and vendor technical support over unit cost minimization. Norway and the United Kingdom host concentrated margin pools where shared beam-forming expertise and reference standard access reduce individual capital burdens.
- Commercial Companies:Offshore energy developers, survey contractors, and port operators balance equipment performance against day-rate economics and fleet turnover schedules.
- Environmental Consultants:Specialized service providers deliver compliance-driven surveys for infrastructure projects and habitat assessments under contracted scopes.
Government Agencies dominate installed base. Research Institutions concentrate premium pricing.
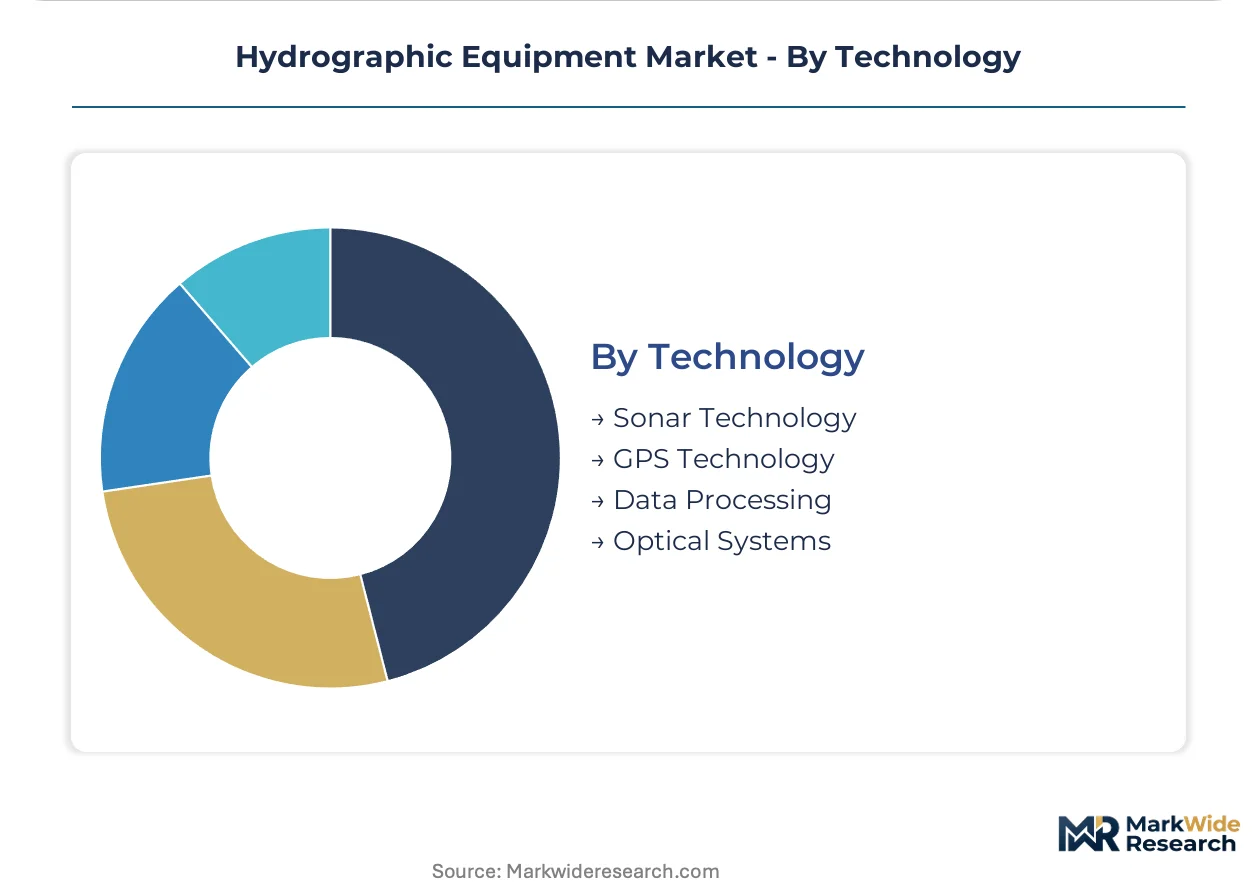
Technology:
Supply concentration for high-frequency transducer manufacturing in Northern Europe and East Asia creates input bottlenecks that reshape technology segment dynamics during demand surges.
- Sonar Technology:Acoustic sensing hardware including multibeam, single-beam, and side-scan configurations generates the core bathymetric and seabed imagery data streams. EdgeTech maintains premium positioning in shallow-water survey niches through high-frequency side-scan modules.
- Data Processing:Beam-forming algorithms, point cloud manipulation, and cloud-hosted bathymetric analytics enable subscription-based monetization models that restructure vendor revenue streams. Kongsberg Gruppen ASA leverages integrated software stacks to anchor long-term service contracts.
- GPS Technology:Differential and RTK positioning systems provide geodetic reference frames for survey data integration with terrestrial coordinate systems.
- Optical Systems:Laser-based bathymetry and photogrammetric methods complement acoustic techniques in clear-water and very-shallow environments.
Sonar Technology anchors hardware revenue. Data Processing is gaining share fastest through SaaS unbundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stavanger anchors European hydrographic equipment procurement through its concentration of offshore survey contractors serving North Sea energy infrastructure. The city's survey fleet operators source multibeam systems under Norway's implementation of the EU Marine Strategy Framework Directive.
Norway
Offshore wind lease obligations and subsea infrastructure expansion drive systematic multibeam sonar procurement from Stavanger-based survey contractors. The Norwegian Maritime Authority enforces IHO-compliant equipment standards for official nautical chart production. Bergen hosts specialized calibration facilities serving research consortia with shared beam-forming expertise.
United Kingdom
North Sea wind farm developers in Aberdeen and Great Yarmouth expand autonomous survey vessel fleets to meet pre-construction seabed assessment timelines. The UK Hydrographic Office mandates specific acoustic methodologies under national marine spatial planning frameworks. Southampton concentrates university-linked oceanographic institutes negotiating multi-year calibration contracts.
China
State-funded coastal infrastructure projects in Qingdao and Shanghai absorb substantial procurement volumes for domestic seabed mapping programs. The Ministry of Ecology and Environment enforces GB standards and technical guidelines that diverge from IEC frameworks. Dalian hosts system integrators with established regulatory relationships qualifying for MEE-directed contracts.
Germany
The Federal Maritime and Hydrographic Agency compels standardized acoustic methodologies for Baltic Sea habitat mapping and port maintenance surveys. Hamburg anchors demand through its channel deepening projects requiring recurring bathymetric verification. Rostock concentrates environmental consultants delivering compliance-driven surveys under contracted scopes.
France
CNIL-aligned environmental agencies mandate pre- and post-dredging seabed assessments for coastal zone management projects. Brest hosts research institutions prioritizing calibration precision over unit cost minimization in procurement cycles. Marseille concentrates commercial survey operators serving Mediterranean cable routing and offshore infrastructure siting.
Hydrographic Equipment Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the hydrographic equipment landscape, with integrated system houses maintaining captive transducer manufacturing while specialized software vendors unbundle processing capabilities. The vendor base concentrates among Northern European and East Asian acoustic engineering facilities, creating tiered supply dynamics around calibration infrastructure access. Three archetypes dominate: vertically integrated platform providers, high-frequency sensor specialists, and cloud-native analytics unbundlers. Strategic moves center on backward integration into transducer supply and geographic expansion through regulatory certification stacking.
Within the integrated platform tier, Kongsberg Gruppen ASA anchors long-term service contract structures alongside hardware deployment. Teledyne Technologies Inc. exemplifies diversification across acoustic sensing and autonomous underwater vehicle architectures. EdgeTech occupies a specialist position in high-frequency shallow-water survey configurations. These three represent distinct competitive vectors: software-anchored recurring revenue, cross-platform technology integration, and premium niche positioning.
| Leading Market Players |
|---|
| Kongsberg Gruppen ASA |
| Teledyne Technologies Inc. |
| EdgeTech |
| iXblue SAS |
| Innomar Technologie GmbH |
| Sonardyne International Ltd. |
| Raytheon Technologies Corporation |
| SyQwest Inc. |
| Tritech International Limited |
| Others |
Value Chain & Pricing Dynamics
Beam-forming algorithm expertise concentrated in aging specialist workforces across Northern Europe and East Asia feeds directly into labor-cost differentials that widen pricing-tier spreads between premium multibeam systems and economy-grade single-beam alternatives. Hydrographic equipment vendors calibrate hardware margins against the scarcity of acoustic data interpretation skills, compressing entry-level pricing while sustaining premium positioning through bundled calibration contracts.
Pricing Analysis
Throughput-based value pricing anchors multibeam system quotations, with vendors tying hardware costs to swath-coverage efficiency metrics and post-sale data-processing commitments. Three-tier pricing structure across premium, standard, and economy levels separates IHO-certified multibeam configurations from port-authority single-beam units and portable reconnaissance equipment. Cost compression in the standard tier is intensifying because research institutions are unbundling after-sales technical support from hardware acquisition. Government agencies exhibit the least price sensitivity due to rigid IHO compliance mandates, while environmental consultants face acute budget constraints that favor economy-tier procurement.
Supply Chain Analysis
Direct-to-OEM channels handle fleet-operator demand from Stavanger-based survey contractors and Aberdeen wind farm developers, while system integrators in Dalian and Hamburg manage state-funded coastal infrastructure procurement. High-frequency transducer manufacturing concentrates in Norway, the United Kingdom, and China, with ceramic element supply and precision-machined acoustic housings serving as critical input dependencies. Single-source vulnerability in certified reference standard production creates commissioning bottlenecks that extend lead times during demand surges. Distribution runs through authorized service centers that bundle installation supervision with IHO validation protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Autonomous underwater vehicle payloads are displacing crewed vessel configurations across shallow-water survey niches, compressing capital deployment timelines and fragmenting traditional equipment bundling strategies.
For Market Incumbents: Hedge against SaaS unbundling by anchoring long-term service contracts through integrated software stacks that process beam-forming algorithms in cloud-hosted environments. Deepen backward integration into high-frequency transducer manufacturing to reduce exposure to Northern European and East Asian supply concentration. Prioritize calibration infrastructure investments in Bergen and Southampton to capture research institution procurement cycles that prioritize precision over unit cost. For New Entrants and Emerging Players: The EU Marine Strategy Framework Directive in member states opens a window for specialized environmental monitoring configurations targeting France's CNIL-aligned agencies and Germany's Federal Maritime and Hydrographic Agency. Portable equipment represents the most penetrable product category given streamlined self-certification pathways and rapid deployment demand from emergency response operators. Pursue channel partnerships with Stavanger-based survey fleet operators to establish credibility before scaling into multibeam system competition. For Investors and Strategic Acquirers: Re-rating potential sits with cloud-native analytics unbundlers given the shift toward subscription-based bathymetric processing and recurring revenue visibility. Target firms with established regulatory relationships in China qualifying for Ministry of Ecology and Environment-directed contracts. Monitor autonomous vessel regulation finalization in Norway, the United Kingdom, and China as the primary inflection indicator for unmanned platform deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Analytics Platform Launch | Kongsberg Gruppen ASA leverages integrated software stacks to anchor recurring service contracts alongside hardware sales. |
| Autonomous Vessel Certification Investment | Teledyne Technologies Inc. competes through cross-platform integration across acoustic sensors and unmanned underwater architectures. |
| High-Frequency Transducer Backward Integration | EdgeTech maintains premium positioning in shallow-water survey niches through specialized side-scan module manufacturing. |
| Research Institution Calibration Infrastructure Partnership | University consortia in Norway and the United Kingdom pool resources for shared beam-forming expertise and reference standard access. |
| Regulatory Certification Stacking in China | Dalian-based system integrators qualify for state-funded coastal infrastructure projects through GB standards alignment with MEE technical guidelines. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with hydrographic survey fleet operators, port authority procurement managers, research institution calibration specialists, and autonomous platform engineering leads. Bottom-up triangulation against top-down macroeconomic indicators validated equipment shipment volumes across Norway, the United Kingdom, China, Germany, and France. International Hydrographic Organization certification databases and national maritime administration procurement disclosures provided product-category segmentation benchmarks.
Data-stream reconciliation across multibeam system installations, echo sounder fleet replacements, and portable equipment deployments enabled projection modeling across the analysis window. Segmentation dimensions included product type, application context, end-user procurement rhythm, and technology architecture. CAGRs were derived from equipment replacement cycles, regulatory mandate enforcement timelines, and offshore wind lease obligation schedules. Autonomous platform adoption curves and cloud-hosted processing penetration served as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for unmanned surface vehicle deployment would alter the outlook if regulatory finalization delays persist or crewed vessel economics shift materially. Forecasts reflect assumptions about IHO certification timeline stability, transducer manufacturing capacity expansion, and skilled hydrographer workforce replenishment. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Surveillance
Early Warning Radar Market
Military Surveillance
Global Airborne Warning and Control System Market
Military Surveillance
Anti-Sniper Detection System Market
Military Surveillance
Maritime Surveillance Market
Military Surveillance
Target Acquisition Systems Market
Military Surveillance
Europe Intelligence Surveillance and Reconnaissance Market
Military Surveillance
Military Jammer Market
Military Surveillance
Global Radar Market
Military Surveillance
UXO Detection Market
Military Surveillance
Global Military Man-Portable Radar System Market
Military Surveillance
Asia-Pacific Hydrographic Survey Equipment Market
Military Surveillance
Maritime Situational Awareness Systems Market
Military Surveillance
Electronically Scanned Array Radar Market
Military Surveillance
Global Airborne Surveillance Market
Military Surveillance
EO/IR Gimbal Market
Military Surveillance
Defense Geospatial Market