
 Drone Surveillance Platform Market | 2026-2036
Drone Surveillance Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Drone Surveillance Platform Market Insights
The divergence between premium and commodity tiers in drone surveillance is hardening around sensor fidelity, flight endurance, and real-time data processing capabilities. BAE Systems leverages its defense heritage to anchor high-assurance military contracts across European and Middle Eastern ministries. Aerodyne Group competes through scaled drone-as-a-service operations spanning Southeast Asian infrastructure corridors. Cyberhawk Innovations Limited specializes in confined-space industrial inspection, sustaining premium pricing through proprietary analytics software.
A drone surveillance platform integrates unmanned aerial vehicles with stabilized sensor payloads, encrypted datalinks, and ground control stations to acquire, process, and distribute visual or signals intelligence across distributed networks. These systems typically operate at altitudes below 400 feet with endurance ranging from 30 minutes to 12 hours depending on propulsion architecture, serving commercial security operators and government agencies requiring persistent aerial monitoring without manned aviation costs. Multi-rotor configurations dominate urban law enforcement deployment due to vertical takeoff flexibility and hover stability, while fixed-wing systems capture expanding share in maritime patrol applications where range and endurance outweigh maneuverability requirements. Synthetic aperture radar penetration through cloud cover and foliage is displacing electro-optical dominance in all-weather border monitoring contracts across equatorial regions.
The FAA governs civil airspace access through Part 107 and emerging beyond-visual-line-of-sight rulemaking, directly conditioning commercial operator certification timelines and insurance requirements. EASA's drone regulation framework and the EU AI Act's automated decision-making provisions are reshaping product liability and algorithmic transparency standards for European deployments. Stakeholders must monitor accelerating regulatory fragmentation between permissive experimental corridors and restrictive controlled-airspace regimes when allocating platform development budgets.
Market Dynamics
Defense procurement cycles across NATO ministries are compressing platform qualification timelines while demanding sovereign datalink encryption standards, forcing suppliers to bifurcate R&D budgets between military-hardened and commercial-grade architectures.
Growth Catalysts
- Beyond-Visual-Line-of-Sight Rulemaking:FAA Part 107 refinements in the United States are unlocking corridor-based commercial surveillance contracts for infrastructure operators previously restricted to visual-range operations.
- Synthetic Aperture Radar Penetration:SAR payloads are displacing electro-optical dominance in equatorial border monitoring where persistent cloud cover degrades optical sensor utility.
- Critical Infrastructure Protection Mandates:Saudi Arabia and the UAE are deploying fleet-scale drone surveillance across energy facilities, creating concentrated demand for hardened platforms with 12-hour endurance specifications.
Market Restraints
- Lithium-Ion Supply Concentration:Battery cell production concentrates in East Asian manufacturing clusters, exposing Western platform integrators to raw material price volatility and export control risk.
- Regulatory Fragmentation:Divergent airspace certification timelines between FAA experimental corridors and EASA controlled-airspace regimes inflate compliance costs for multi-jurisdictional operators.
- Manned Aviation Substitution:Crewed helicopter services retain cost advantages for rapid-response law enforcement scenarios requiring immediate human judgment under 30-minute deployment windows.
Strategic Opportunities
- Drone-as-a-Service Penetration:Southeast Asian infrastructure corridors present underdeveloped markets where capital-constrained utilities prefer operational expenditure models over platform ownership.
- EU AI Act Automated Decision-Making:Algorithmic transparency mandates are creating first-mover advantage for European vendors with pre-certified analytics software stacks.
- Confined-Space Industrial Inspection:Chemical processing facilities and offshore platforms require specialized platforms with collision-avoidance sensors, sustaining premium pricing unavailable in commodity surveillance tiers.
Industry Challenges
- Embedded Systems Engineering Talent:Flight control firmware development requires rare expertise combining aerospace control theory with real-time operating systems, constraining platform iteration velocity.
- Cross-Border Frequency Allocation:C-band datalink harmonization delays between national telecommunications regulators fragment encrypted communications architectures.
- Legacy Security System Integration:Municipal law enforcement agencies operate decade-old video management software requiring costly middleware development for drone feed ingestion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drone Surveillance Platform Market |
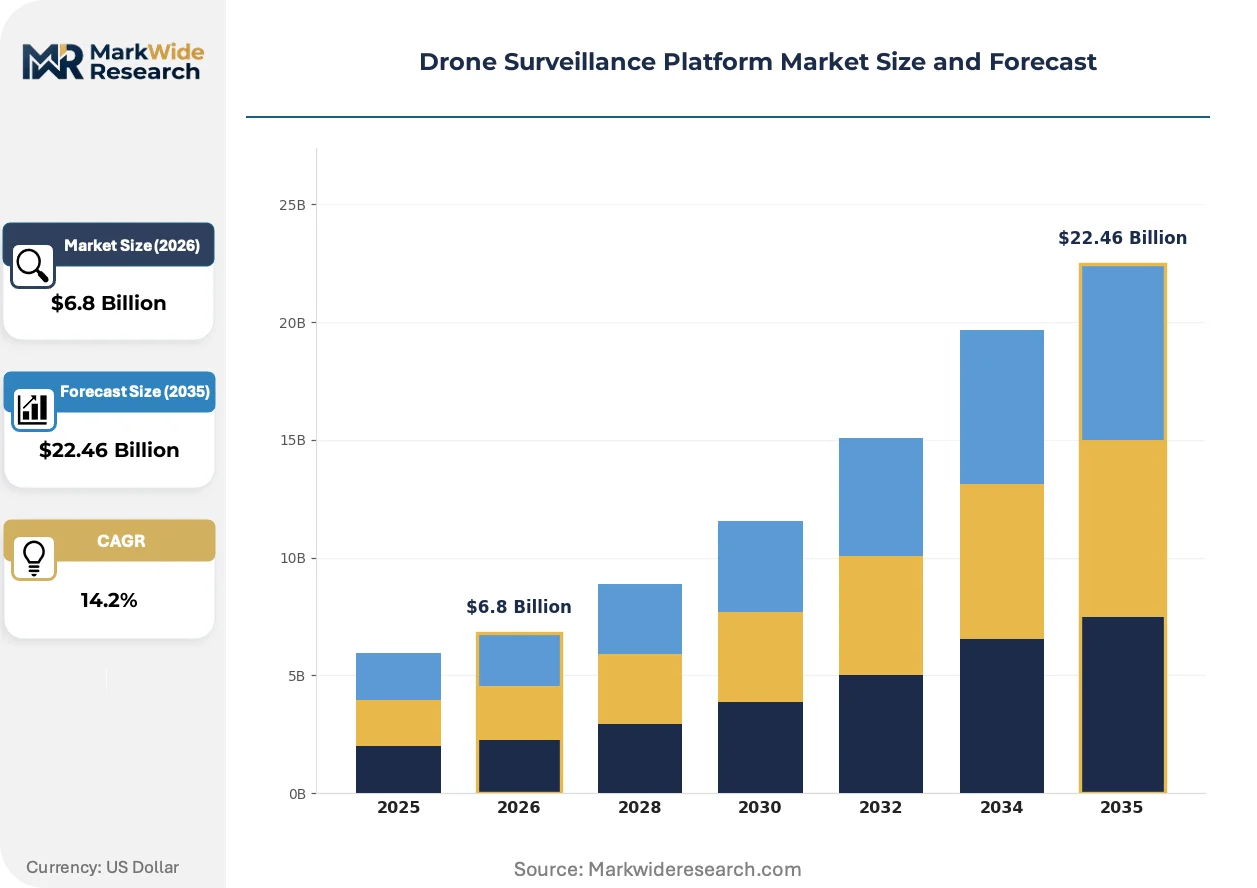
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drone Type: Fixed-Wing, Multi-Rotor, Hybrid VTOL, Nano Drones Technology: LiDAR, Infrared Imaging, Electro-Optical Sensors, Synthetic Aperture Radar, Hyperspectral Sensors Application: Border Monitoring, Critical Infrastructure Security, Wildlife Protection, Maritime Patrol, Disaster Management End User: Law Enforcement Agencies, Environmental Agencies, Oil & Gas Sector, Maritime Authorities, Mining Operations |
| Companies Covered | Aerodyne Group, BAE Systems, Cyberhawk Innovations Limited, Airobotics Ltd., Terra Drone Corp., Sky-Futures Ltd, Mistras Group, Australian UAV Pty Ltd, Percepto, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drone Surveillance Platform Market Trends and Innovations
Edge computing architectures are relocating real-time analytics from ground stations to onboard processors, compressing decision latency for time-critical surveillance scenarios while reducing datalink bandwidth requirements.
Swarm coordination protocols are decentralizing mission execution across distributed multi-rotor formations. Maritime security operators in the Persian Gulf are deploying autonomous vehicle networks for harbor perimeter monitoring, eliminating single-point-of-failure risks inherent in solo-platform architectures while reducing per-square-kilometer coverage costs.
EASA's drone regulation framework and EU AI Act provisions are mandating algorithmic audit trails for automated threat detection systems. European border agencies now require explainable AI documentation for procurement qualification, advantaging vendors with pre-established compliance documentation over competitors relying on black-box neural architectures.
Utility procurement departments are unbundling hardware acquisition from analytics subscriptions, treating drone surveillance as an operational technology category rather than capital equipment. This pattern concentrates most visible in German and French energy distribution networks, where platform-as-a-service contracts now outnumber direct purchase orders for routine inspection workflows.
Drone Surveillance Platform Market Segmentation
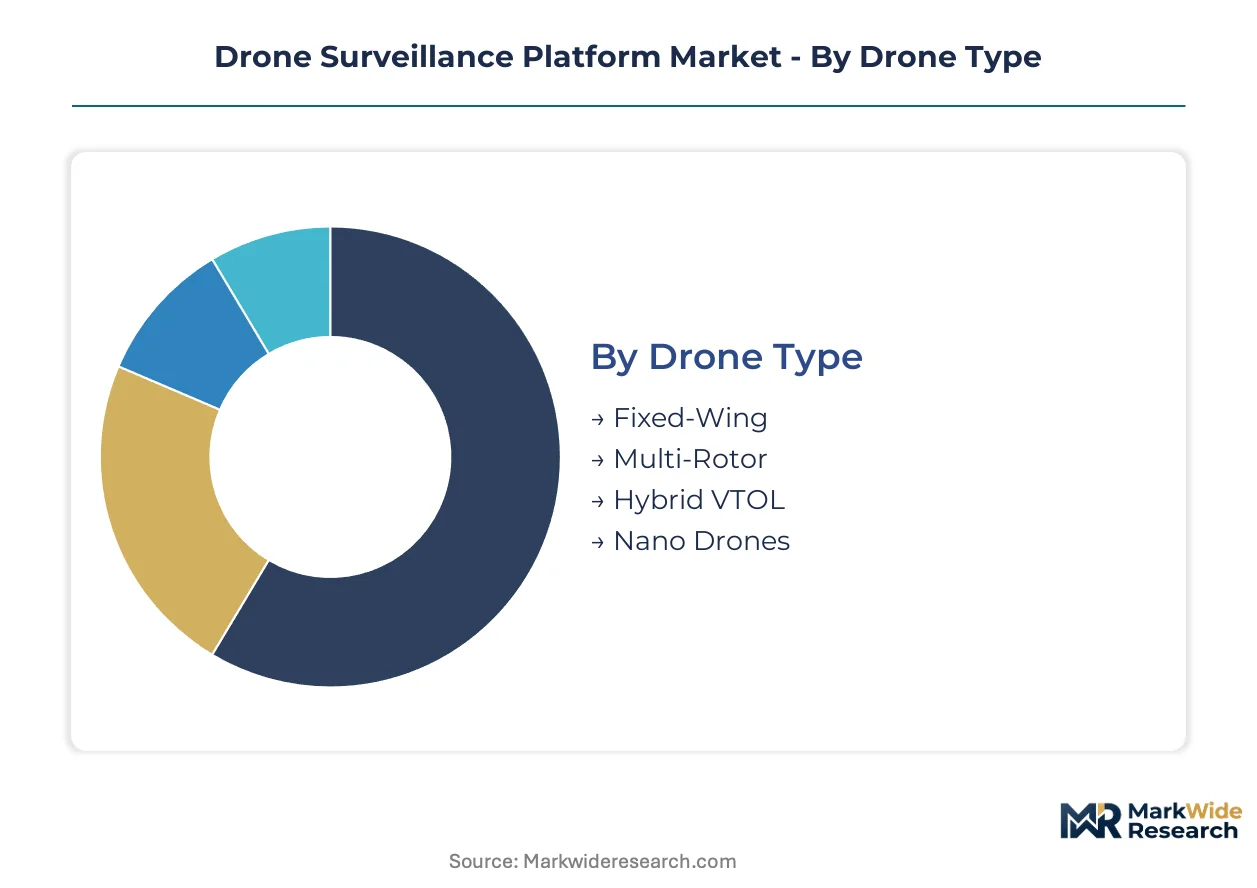
Platform selection in drone surveillance hinges on endurance requirements, sensor payload capacity, and airspace constraints that vary sharply across deployment scenarios. Procurement patterns reveal divergent upgrade cycles between defense-grade systems and commercial service fleets.
Drone Type:
Replacement cycles accelerate where battery chemistry improvements and airframe durability create measurable operational cost deltas.
- Fixed-Wing:Extended endurance platforms with pusher-prop or twin-boom configurations dominate maritime patrol corridors and desert border surveillance where range exceeds 100 kilometers. Saudi Aramco procurement specifications favor 12-hour loiter capacity for pipeline monitoring across the Empty Quarter.
- Multi-Rotor:Quadcopter and hexacopter architectures provide vertical takeoff precision for urban law enforcement and confined industrial inspection. Dubai Police deploy battery-swappable fleets for rapid-response deployment across metropolitan districts.
- Hybrid VTOL:Tilt-rotor and tail-sitter designs combine runway independence with fixed-wing efficiency for offshore platform logistics.
- Nano Drones:Sub-250 gram platforms exploit regulatory weight exemptions for covert indoor reconnaissance and tunnel system mapping.
Volume placements concentrate in Multi-Rotor; the faster expansion belongs to Hybrid VTOL.
Technology:
Sensor procurement prioritizes all-weather reliability and automated detection throughput over raw resolution specifications.
- Synthetic Aperture Radar:Active microwave imaging penetrates cloud cover, precipitation, and canopy foliage for persistent equatorial border monitoring where optical systems face 200+ annual overcast days. Indonesian and Malaysian frontier agencies mandate SAR for rainforest perimeter surveillance.
- Electro-Optical Sensors:Stabilized visible-spectrum and near-infrared cameras with 30x+ optical zoom remain the default for law enforcement evidence collection and real-time tactical response. EASA certification requirements now specify minimum ground sample distance thresholds for facial recognition admissibility.
- LiDAR:Pulsed laser ranging generates centimeter-accurate digital elevation models for infrastructure deformation monitoring.
- Infrared Imaging:Thermal cameras detect heat signatures for night operations and search-and-rescue missions.
- Hyperspectral Sensors:Narrow-band spectral analysis identifies vegetation stress and mineral composition for environmental and exploration applications.
Procurement volume clusters around Electro-Optical Sensors; Synthetic Aperture Radar claims the steepest expansion trajectory.
Application:
Contract values scale with mission criticality and regulatory compliance burden rather than flight hours alone.
- Border Monitoring:Sovereign perimeter defense programs integrate drone corridors with ground radar and satellite feeds for multi-layer domain awareness. UAE's Al Dhafra Air Base hosts integrated command centers coordinating fixed-wing patrols across 1,300 kilometers of coastline.
- Critical Infrastructure Security:Energy facilities, telecommunications nodes, and transportation hubs require encrypted datalinks and collision-avoidance systems for beyond-visual-line-of-sight authorization. ADNOC's drone program covers 5,000+ kilometers of pipeline with automated threat response protocols.
- Maritime Patrol:Harbor security and exclusive economic zone monitoring demand corrosion-resistant platforms with satellite communications relay.
- Disaster Management:Rapid damage assessment and search coordination prioritize deployability over sensor sophistication.
- Wildlife Protection:Anti-poaching patrols leverage acoustic detection and thermal tracking for reserve perimeter enforcement.
Revenue concentration sits with Critical Infrastructure Security; Border Monitoring is climbing the fastest.
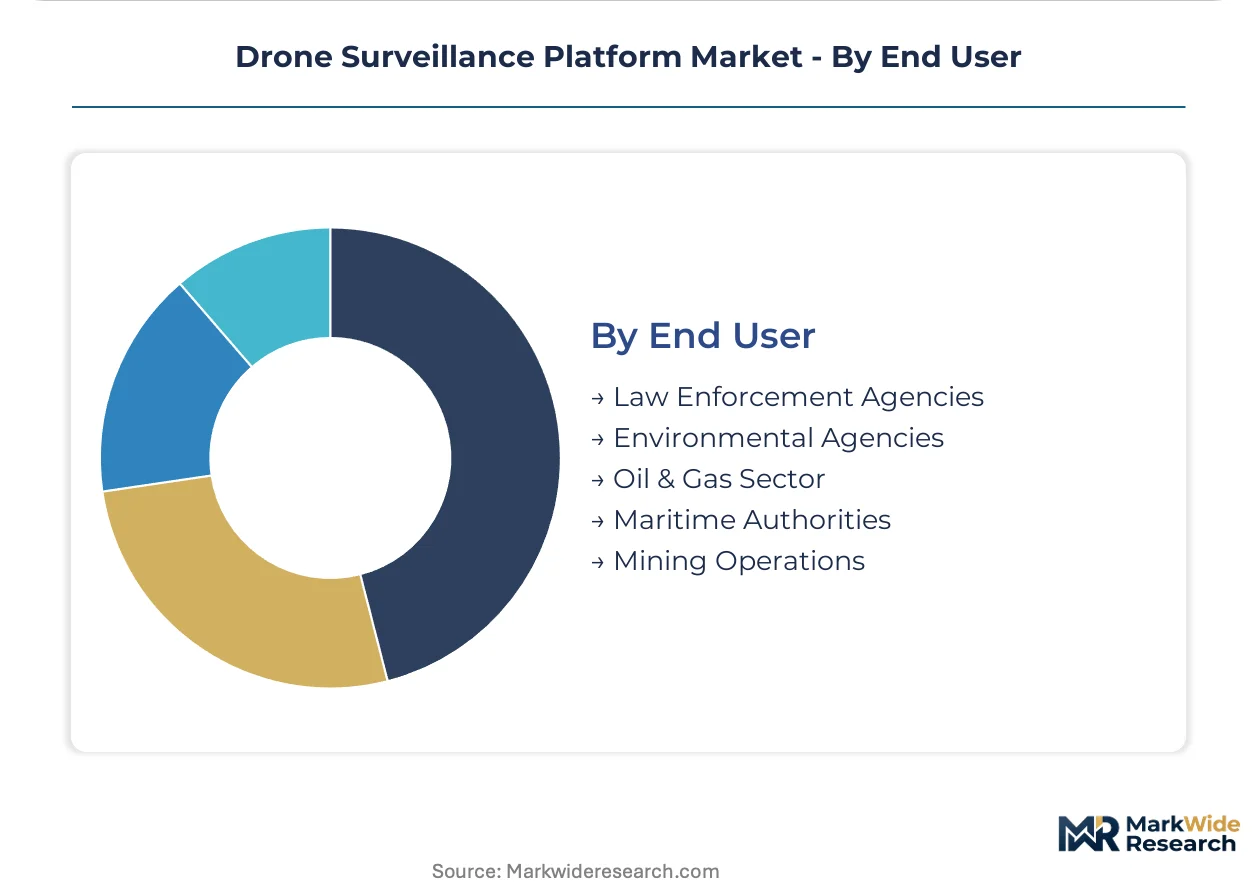
End User:
Budget authority and procurement velocity separate defense-integrated programs from commercial operator leasing models.
- Law Enforcement Agencies:Municipal and national police forces deploy multi-rotor fleets for crowd monitoring, crime scene documentation, and tactical support. FAA Part 107 waivers for night operations and over-human flight now standardize across major US metropolitan departments.
- Oil & Gas Sector:Upstream and midstream operators commission long-endurance platforms for flare stack inspection, methane leak detection, and seismic survey support. Saudi Aramco's drone-as-a-service contracts with Aerodyne Group span 50+ facilities.
- Maritime Authorities:Coast guard and port authorities require ship-launched recovery systems and maritime-band communications.
- Mining Operations:Open-pit and underground extraction sites utilize LiDAR mapping and stockpile volumetrics for operational planning.
- Environmental Agencies:Conservation departments monitor deforestation, wetland health, and pollution incidents with standardized data collection protocols.
Spending dominance rests with Oil & Gas Sector; Law Enforcement Agencies show the fastest budget growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai's integrated drone command infrastructure anchors Middle Eastern demand for persistent aerial monitoring systems across energy corridors and urban security networks.
United States
FAA Part 107 refinements are unlocking corridor-based commercial surveillance contracts for infrastructure operators previously restricted to visual-range operations. The FAA's beyond-visual-line-of-sight rulemaking compresses certification timelines for energy sector deployments. Houston's petrochemical corridor hosts concentrated drone-as-a-service operations for flare stack inspection and methane leak detection.
Saudi Arabia
ADNOC's fleet-scale procurement mandates 12-hour endurance specifications for pipeline monitoring across the Empty Quarter desert expanse. The General Authority of Civil Aviation issues operating permits under harmonized Gulf standards for critical infrastructure protection. Dhahran's energy technology cluster concentrates platform integration facilities serving Aramco's 5,000-kilometer pipeline network.
United Arab Emirates
Dubai Police deploy battery-swappable multi-rotor fleets for rapid-response deployment across metropolitan districts. The General Civil Aviation Authority coordinates with MOHAP on healthcare logistics corridors while enabling commercial surveillance waivers. Al Dhafra Air Base hosts integrated command centers coordinating fixed-wing patrols across 1,300 kilometers of coastline.
Germany
EASA's drone regulation framework and EU AI Act provisions mandate algorithmic audit trails for automated threat detection systems in border agency procurement. The Bundesnetzagentur manages C-band datalink harmonization for encrypted communications architectures. Munich's aerospace engineering cluster concentrates flight control firmware development combining aerospace control theory with real-time operating systems.
Indonesia
Frontier agencies mandate synthetic aperture radar payloads for rainforest perimeter surveillance where optical systems face 200+ annual overcast days. The national telecommunications regulator coordinates cross-border frequency allocation for maritime patrol datalinks. Batam's industrial zone hosts platform assembly operations serving Southeast Asian infrastructure corridors.
Drone Surveillance Platform Market Competitive Landscape
Premium-margin players sit above commodity-margin players across sensor fidelity, flight endurance, and sovereign datalink encryption standards. Defense procurement cycles across NATO ministries compress platform qualification timelines while demanding hardened architectures, forcing suppliers to bifurcate R&D budgets. Three archetypes dominate: defense heritage integrators anchoring military contracts, scaled drone-as-a-service operators penetrating capital-constrained utilities, and specialized analytics vendors sustaining premium pricing through proprietary software. Competitive moves concentrate on M&A for embedded systems engineering talent and strategic partnerships for battery cell supply security.
Within the defense heritage tier, BAE Systems represents high-assurance military contracting across European and Middle Eastern ministries. Aerodyne Group exemplifies scaled drone-as-a-service operations spanning Southeast Asian infrastructure corridors. Cyberhawk Innovations Limited occupies a position in confined-space industrial inspection, sustaining premium pricing unavailable in commodity surveillance tiers through proprietary analytics software.
| Leading Market Players |
|---|
| Aerodyne Group |
| BAE Systems |
| Cyberhawk Innovations Limited |
| Airobotics Ltd. |
| Terra Drone Corp. |
| Sky-Futures Ltd |
| Mistras Group |
| Australian UAV Pty Ltd |
| Percepto |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed defense integrators and private-equity-rolled-up drone-as-a-service operators anchor divergent pricing disciplines across the value chain. State-funded procurement programs in Saudi Arabia and the UAE absorb premium-tier platforms with 12-hour endurance specifications, while Aerodyne Group's scaled Southeast Asian operations compress margins through operational expenditure models that shift risk from capital-constrained utilities to fleet operators.
Pricing Analysis
Outcome-based pricing tied to surveillance uptime and threat-detection throughput dominates critical infrastructure contracts, displacing per-unit hardware transactions. Three-tier pricing structure across military-hardened, commercial-grade, and commodity inspection tiers separates BAE Systems' sovereign encryption premiums from Cyberhawk's confined-space analytics subscriptions. Cost compression in battery-swappable multi-rotor fleets is intensifying because East Asian cell manufacturers face export control scrutiny. Municipal law enforcement agencies exhibit acute price sensitivity, while oil and gas operators prioritize mission assurance over unit economics.
Supply Chain Analysis
Reverse-logistics flows for flight control firmware updates and sensor payload refurbishment concentrate in Munich's aerospace engineering cluster and Shenzhen's electronics manufacturing corridors. Battery cell production draws from China, South Korea, and Japan, with lithium-ion cathode chemistry tethered to cobalt and nickel extraction networks in the Democratic Republic of Congo and Indonesia. Single-source vulnerability in C-band datalink chipsets exposes Western integrators to telecommunications regulator harmonization delays. Distribution runs through defense ministry procurement offices and energy sector drone-as-a-service aggregators rather than retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market structure favors a vertical-integration race into sovereign datalink encryption standards and embedded systems engineering talent. Players capturing upstream control over flight control firmware development or downstream drone-as-a-service operations command durable margin positions.
For Market Incumbents: Deploy sovereign encryption certification as the primary defensive lever. BAE Systems and defense heritage integrators should deepen backward integration into hardened ground control station manufacturing to isolate procurement cycles from East Asian electronics supply volatility. Aerodyne Group must secure long-term battery cell offtake agreements before export control tightening disrupts fleet scaling across Southeast Asian infrastructure corridors.
For New Entrants and Emerging Players: Regional drone-as-a-service aggregators in Indonesia and Malaysia represent the most penetrable channel partner type for specialized analytics vendors. Confined-space industrial inspection in chemical processing facilities offers white-space entry with collision-avoidance sensor differentiation. A go-to-market angle anchored to EU AI Act algorithmic audit trail pre-certification unlocks European border agency procurement.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap drone-as-a-service operators with contracted utility revenue streams in Germany and France. Long-term viability hinges on platform-as-a-service contract renewal rates exceeding hardware depreciation cycles. Watch for FAA beyond-visual-line-of-sight rulemaking acceleration as the inflection signal for commercial surveillance market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Datalink Encryption Investment | BAE Systems anchors NATO ministry contracts through hardened communications architectures. |
| Drone-as-a-Service Platform Expansion | Aerodyne Group captures Southeast Asian utility expenditure shifts away from capital ownership. |
| EU AI Act Compliance Pre-Certification | European vendors with explainable AI documentation secure border agency procurement advantages. |
| Battery Supply Security Partnerships | Long-term cell offtake agreements isolate fleet operators from East Asian export control risk. |
| Confined-Space Analytics Specialization | Cyberhawk sustains premium pricing through proprietary software for industrial inspection workflows. |
Research Methodology
Multi-period observation of defense procurement cycles, FAA Part 107 waiver issuance rates, and EASA certification timelines anchored the trend analysis, supplemented by interviews with flight control firmware engineers, critical infrastructure security directors, drone-as-a-service operations managers, and energy sector procurement leads. Secondary validation drew from FAA regulatory filings, EASA drone regulation framework documents, SEC 10-K disclosures of defense integrators, and customs trade data for battery cell imports. Bottom-up platform shipment estimates triangulated against top-down surveillance contract value aggregation.
Input-output matrices mapped drone type, sensor technology, application, and end-user dimensions across the projection horizon. CAGRs derived from segment-level volume and value trajectories, with cross-validation against sovereign defense budget allocations and commercial operator fleet expansion plans. Industry-specific forecast inputs incorporated lithium-ion supply concentration indices and regulatory harmonization velocity between FAA and EASA regimes.
Caveats apply where FAA beyond-visual-line-of-sight rulemaking delays, East Asian battery export controls, or EU AI Act enforcement variability could materially shift the outlook. Practitioners should monitor C-band frequency allocation harmonization progress and embedded systems engineering salary inflation for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Surveillance
Target Acquisition Systems Market
Military Surveillance
Global Mine Detection System Market
Military Surveillance
Military Jammer Market
Military Surveillance
North America Passive Radar Market
Military Surveillance
Drone Surveillance Market
Military Surveillance
Global Airport Surveillance Radar Market
Military Surveillance
Tactical Scope Market
Military Surveillance
North America Hydrographic Survey Equipment Market
Military Surveillance
Defense Geospatial Market
Military Surveillance
Global Airborne Warning and Control System Market
Military Surveillance
Global Military Thermal Imaging Market
Military Surveillance
Infrared Anti-Sniper Detection Software Market
Military Surveillance
Sea-Based Military Electro-Optical and Infrared Systems Market
Military Surveillance
Global Military Man-Portable Radar System Market
Military Surveillance
UXO Detection Market
Military Surveillance
Hydrographic Survey Equipment Market