
 Mmwave Radar Market | 2026-2036
Mmwave Radar Market Size, Share, and Industry Trends Forecast 2026-2036
Mmwave Radar Market Insights
Automotive-grade resolution tiers above 76 GHz is reorganizing procurement priorities across the Mmwave Radar Market. Texas Instruments leverages its integrated CMOS radar chipset portfolio to anchor design wins with tier-one automotive suppliers. Infineon Technologies sustains its position through SiGe-based transceiver expertise and backward integration into GaN-on-Si processes. Robert Bosch GmbH dominates industrial automation deployments with its 60 GHz presence-detection modules.
Mmwave radar denotes radio detection and ranging systems operating in the 30-300 GHz band, where wavelength compression enables centimeter-scale resolution, sub-degree angular accuracy, and Doppler velocity extraction for collision avoidance and occupancy sensing. Short Range Radar captures the largest volume share in passenger vehicle cabin monitoring and blind-spot detection, while MIMO Radar technology is expanding fastest in security surveillance and drone navigation where spatial multiplexing reduces hardware count. Long Range Radar retains premium margin pools in highway-speed autonomous braking systems where FCC and ETSI spectrum allocations constrain supplier qualification.
NHTSA mandates on automatic emergency braking are accelerating 77 GHz module qualification timelines for Automotive OEMs. The EU's F-Gas Regulation and REACH chemical restrictions are reshaping substrate material selection and hermetic sealing standards for European defense contractors. Stakeholders must monitor spectrum reallocation proceedings at the FCC and MIIT, as 60 GHz unlicensed expansion and 79-81 GHz automotive harmonization decisions will determine next-generation architecture investments.
Market Dynamics
Spectrum harmonization between 77-81 GHz automotive radar and 60 GHz unlicensed industrial bands is compressing module qualification timelines while fragmenting supplier certification pathways across multiple regulatory jurisdictions.
Growth Catalysts
- NHTSA Automatic Emergency Braking Mandates:US vehicle safety rules now require forward collision warning systems on all passenger vehicles, forcing tier-one suppliers to accelerate 77 GHz module validation cycles.
- GaN-on-Si Process Maturation:Gallium nitride on silicon substrates delivers higher power density at lower thermal profiles, enabling longer detection ranges without increasing antenna array size.
- Stuttgart-Munich Supplier Corridor:Germany's automotive electronics cluster concentrates radar module assembly, testing, and OEM integration within a 200-kilometer radius, reducing logistics friction for European vehicle programs.
Market Restraints
- Raw Gallium Nitride Wafer Supply:Six-inch GaN substrates remain concentrated among three specialty foundries, creating input bottlenecks for high-performance transceiver production.
- REACH Chemical Restrictions:EU substrate material rules limit lead-based solder and certain epoxy formulations, forcing redesign of hermetic sealing processes for defense-grade modules.
- Lidar Cost Compression:Solid-state optical ranging systems below $500 per unit threaten premium positioning of 4D imaging radar in robotaxi and last-mile delivery applications.
Strategic Opportunities
- India PLI Scheme for Automotive Electronics:Production-linked incentives for advanced driver assistance sensors are attracting module assembly investments to Tamil Nadu and Gujarat manufacturing zones.
- MIMO-Doppler Fusion for Drone Navigation:Spatial multiplexing combined with micro-Doppler signature extraction enables single-chip obstacle detection for commercial unmanned aerial systems below 400 feet.
- 60 GHz Unlicensed Expansion:FCC proceedings on additional unlicensed spectrum around 57-71 GHz could unlock smart building occupancy sensing without spectrum licensing fees.
Industry Challenges
- RFIC-Antenna Co-Design Expertise:The scarcity of engineers proficient in millimeter-wave electromagnetic simulation and CMOS process constraints delays product tape-outs by 4-6 months.
- Multi-Domain Certification Overlap:Modules must simultaneously satisfy automotive ISO 26262 functional safety, FCC Part 15 emissions, and ETSI EN 302 858 radar standards, multiplying test cycle duration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mmwave Radar Market |
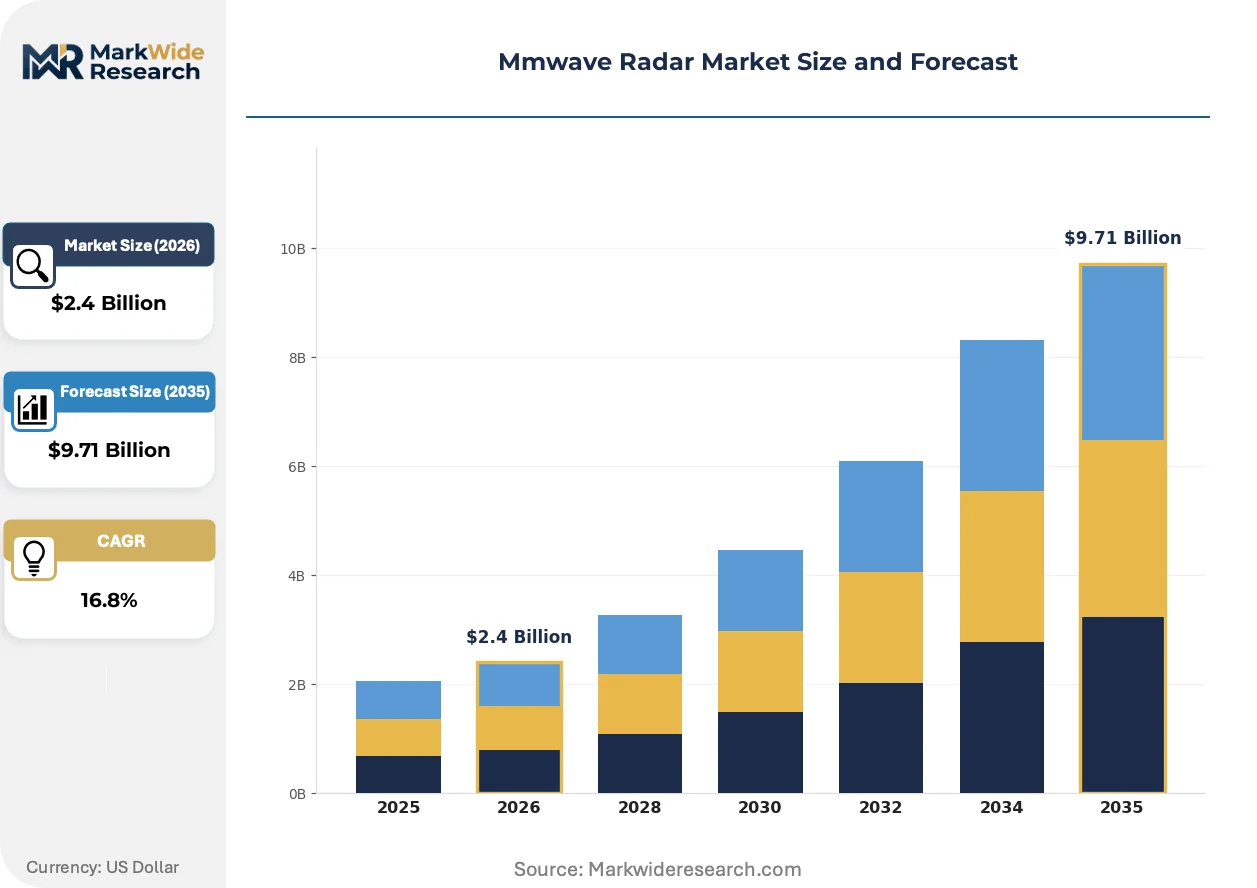
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $9.71 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Short Range Radar, Long Range Radar, Ultra-Wideband Radar, Phased Array Radar, Synthetic Aperture Radar Technology: Frequency Modulated Continuous Wave, Pulse Doppler, Digital Beamforming, MIMO Radar, FMCW Beamforming Application: Advanced Driver Assistance Systems, Traffic Monitoring, Industrial Automation, Security Surveillance, Unmanned Aerial Vehicles End User: Automotive OEMs, Aerospace Manufacturers, Defense Contractors, Consumer Electronics Firms, Agriculture Equipment Producers |
| Companies Covered | Texas Instruments, Infineon Technologies, Robert Bosch GmbH, Continental AG, Denso Corporation, Analog Devices, NXP Semiconductors, STMicroelectronics, Aptiv, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mmwave Radar Market Trends and Innovations
Silicon integration and software-defined waveforms are collapsing the traditional separation between radar hardware tiers, enabling tier-one suppliers to reprogram single platforms across multiple vehicle classes.
CMOS-based radar-on-chip architectures are displacing discrete SiGe transceiver assemblies in mid-range automotive applications. Volkswagen Group and Hyundai Motor have qualified integrated 77 GHz devices for 2026 model year volume programs. This integration compresses bill-of-materials cost by eliminating external PLLs and ADCs while reducing PCB footprint for cabin-mounted sensors.
The EU F-Gas Regulation's phase-down of hydrofluorocarbon-based cooling agents is forcing substrate attachment process changes for high-power radar modules. Hermetic sealing vendors are shifting to nitrogen backfill and silver-sinter die-attach to maintain thermal performance without restricted materials. German defense contractors face the tightest compliance deadlines, with full conversion required by 2027 for export-controlled systems.
Automotive OEMs are unbundling radar hardware from perception software licenses, enabling tier-one suppliers to sell sensor modules without embedded object classification algorithms. This decoupling allows Chinese electric vehicle manufacturers to source hardware from European suppliers while deploying domestic AI stacks for environmental modeling. The pattern is most pronounced in NIO and XPeng vehicle programs, where sensor fusion processing runs on centralized domain controllers rather than edge radar chipsets.
Mmwave Radar Market Segmentation
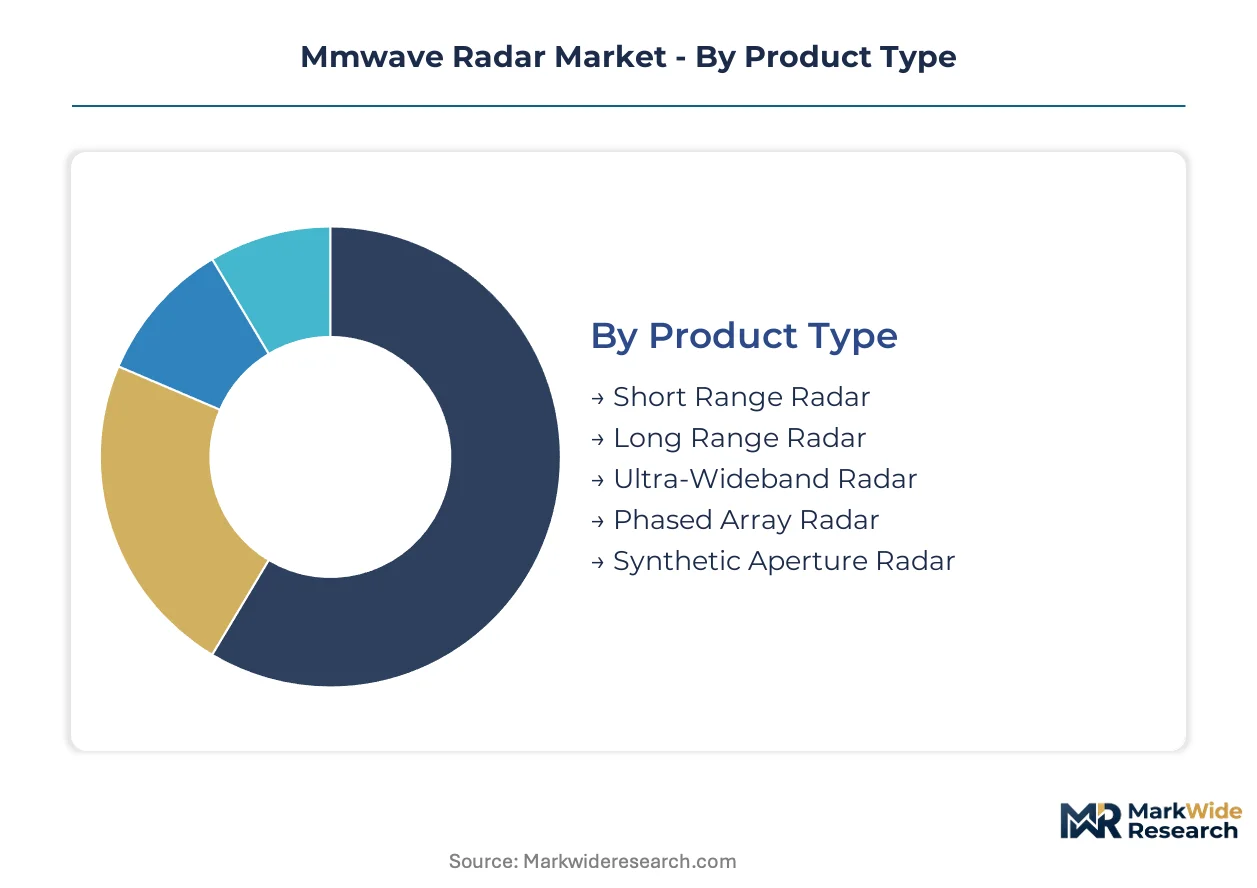
Millimeter-wave radar architectures fragment across frequency bands, waveform techniques, and integration levels that determine cost structures and qualification pathways. Each segmentation axis carries distinct regulatory footprints and supply chain concentration patterns that shape procurement strategies.
Product Type:
Domestic vehicle programs in Germany and the United States drive demand for short-range variants, while export-led defense contracts concentrate on ultra-wideband and phased array systems.
- Short Range Radar:Operating in 60-64 GHz and 77-81 GHz bands, these modules deliver sub-30 meter detection for blind-spot monitoring and cabin occupancy sensing. German automotive OEMs anchor procurement volumes around Stuttgart and Munich assembly corridors, with NHTSA mandates accelerating US qualification timelines.
- Long Range Radar:77 GHz forward-looking systems achieve 200+ meter detection ranges for highway-speed autonomous braking. FCC and ETSI spectrum harmonization efforts constrain supplier certification, concentrating premium module production among established tier-one vendors with multi-domain test facilities.
- Ultra-Wideband Radar:GHz-scale bandwidth enables centimeter-resolution imaging for through-wall sensing and ground-penetrating applications.
- Phased Array Radar:Electronically steered beams support rapid beam agility for military fire-control and satellite communication terminals.
- Synthetic Aperture Radar:Coherent processing of platform motion generates high-resolution terrain maps for aerial surveillance and environmental monitoring.
Short Range Radar holds the largest share; momentum sits with Ultra-Wideband Radar in defense export markets.
Technology:
Cost tiers separate discrete transceiver assemblies from single-chip CMOS integration, with premium positioning reserved for adaptive beamforming architectures.
- Frequency Modulated Continuous Wave:Linear chirp modulation separates target range and velocity through beat frequency analysis. Volkswagen Group and Hyundai Motor have qualified integrated 77 GHz FMCW devices for volume automotive programs, displacing legacy SiGe assemblies.
- MIMO Radar:Spatial multiplexing across multiple transmit-receive channels reduces hardware count while preserving angular resolution. Commercial drone manufacturers below 400 feet altitude deploy single-chip MIMO-Doppler fusion for obstacle avoidance without mechanical scanning.
- Pulse Doppler:Coherent pulse trains enable unambiguous velocity measurement in high-clutter environments.
- Digital Beamforming:Baseband processing of array element outputs supports adaptive nulling and multi-target tracking.
- FMCW Beamforming:Hybrid architectures combine chirp modulation with spatial filtering for automotive imaging radar.
Frequency Modulated Continuous Wave dominates automotive volume; MIMO Radar climbs the fastest in security and unmanned systems.
Application:
Customer type differentiation separates fleet-scale automotive procurement from project-based industrial and defense contracts.
- Advanced Driver Assistance Systems:Forward collision warning and automatic emergency braking systems mandate 77-81 GHz radar under NHTSA rules. Tier-one suppliers accelerate module validation cycles to meet US vehicle safety deadlines.
- Security Surveillance:Perimeter detection and through-wall sensing applications exploit 60 GHz unlicensed bands and 77 GHz licensed allocations. FCC proceedings on 57-71 GHz expansion could unlock smart building occupancy sensing without spectrum fees.
- Traffic Monitoring:Intersection-mounted sensors enable vehicle counting and speed enforcement.
- Industrial Automation:Presence detection and collision avoidance systems deploy 60 GHz modules for factory robotics.
- Unmanned Aerial Vehicles:Beyond-visual-line-of-sight navigation requires lightweight radar for detect-and-avoid compliance.
Advanced Driver Assistance Systems commands the largest revenue pool; Security Surveillance gains share fastest on unlicensed spectrum expansion.
End User:
Supply concentration varies by certification burden, with automotive and aerospace demanding ISO 26262 and DO-178C compliance that excludes consumer-grade suppliers.
- Automotive OEMs:Centralized domain controllers now host sensor fusion processing, enabling hardware-software decoupling. Chinese electric vehicle manufacturers source European radar modules while deploying domestic AI stacks for environmental modeling.
- Defense Contractors:Export-controlled systems face EU F-Gas Regulation deadlines requiring hermetic sealing process conversion by 2027. German contractors shift to nitrogen backfill and silver-sinter die-attach to maintain thermal performance.
- Aerospace Manufacturers:Airborne weather radar and terrain avoidance systems demand high-reliability qualification.
- Consumer Electronics Firms:Gesture recognition and presence sensing applications drive 60 GHz integration into laptops and displays.
- Agriculture Equipment Producers:Autonomous tractors and harvesters deploy radar for obstacle detection in dusty environments.
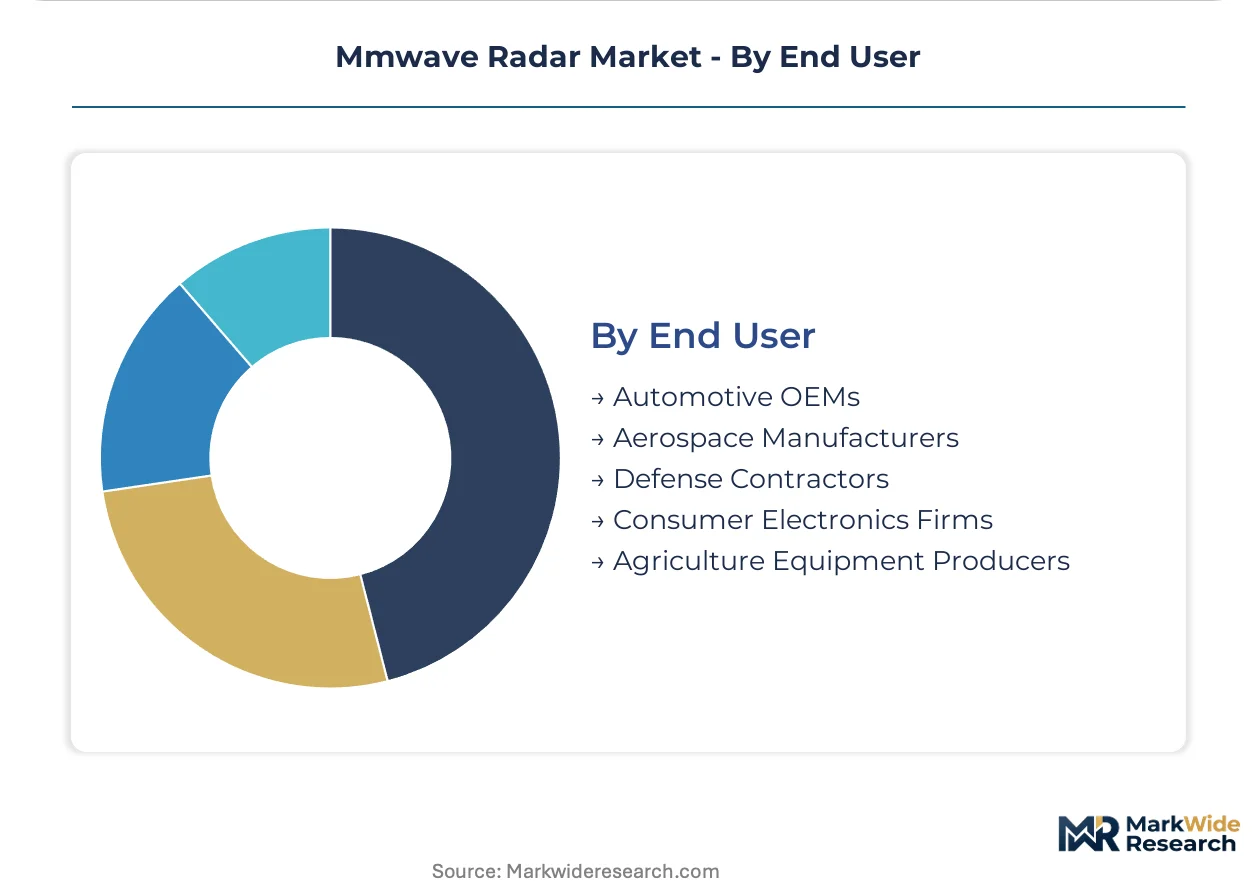
Automotive OEMs hold the largest share; Defense Contractors show steepest expansion trajectory on modernization budgets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty foundries in Germany, the United States, and South Korea supply six-inch GaN substrates that constrain transceiver production worldwide. Tier-one automotive suppliers cluster within 200 kilometers of Stuttgart and Munich for OEM integration efficiency. Defense contractors in Israel and Japan face divergent regulatory timelines for hermetic sealing compliance.
United States
NHTSA automatic emergency braking mandates accelerate 77 GHz module validation cycles for Detroit-based automotive suppliers. FCC spectrum proceedings on 57-71 GHz unlicensed expansion could unlock smart building applications without licensing fees. Module testing concentrates in Michigan and California corridors where multi-domain certification facilities handle ISO 26262, FCC Part 15, and ETSI EN 302 858 standards simultaneously.
Germany
EU F-Gas Regulation deadlines force hermetic sealing process conversion by 2027 for export-controlled defense systems. REACH chemical restrictions limit lead-based solder and certain epoxy formulations, pushing substrate attachment toward nitrogen backfill and silver-sinter die-attach. The Stuttgart-Munich supplier corridor anchors radar module assembly, testing, and Volkswagen Group integration within a tight logistics radius.
China
MIIT spectrum harmonization decisions on 79-81 GHz automotive bands determine next-generation architecture investments for domestic electric vehicle manufacturers. NIO and XPeng source European radar hardware while deploying domestic AI stacks on centralized domain controllers. Yangtze River Delta fabs concentrate CMOS radar-on-chip production for cost-sensitive passenger vehicle programs.
Japan
METI industrial automation standards drive 60 GHz presence-detection module adoption for factory robotics and warehouse logistics. Domestic automotive OEMs qualify integrated 77 GHz devices for 2026 model year exports to European and North American markets. Kyushu-based semiconductor packaging houses specialize in thermal management for high-power transceiver assemblies.
South Korea
Hyundai Motor Group qualification of integrated 77 GHz FMCW devices for volume automotive programs displaces legacy SiGe assemblies. Seoul Capital Area design houses specialize in RFIC-antenna co-design for MIMO-Doppler fusion in commercial drone navigation. Memory fab infrastructure supports GaN-on-Si process maturation for longer detection range without antenna array expansion.
Mmwave Radar Market Competitive Landscape
Concentration sits with diversified semiconductor conglomerates and specialized automotive tier-one suppliers. Three to four integrated circuit manufacturers control CMOS radar-on-chip architectures, while discrete SiGe transceiver vendors defend premium positioning in defense-grade applications. Strategic archetypes include silicon-integrated platform providers, GaN-on-Si process specialists, and software-decoupled sensor module vendors. Competitive moves center on backward integration into GaN substrate supply and geographic expansion toward India's PLI scheme zones.
Among diversified semiconductor conglomerates, Texas Instruments and Infineon Technologies exemplify the silicon-integrated platform archetype, occupying positions that span automotive qualification and industrial automation. Robert Bosch GmbH represents the tier-one automotive supplier model, anchoring industrial presence-detection deployments. These three entities sit within distinct competitive tiers: CMOS integration for cost compression, SiGe expertise for premium defense margins, and 60 GHz module dominance for factory robotics.
| Leading Market Players |
|---|
| Texas Instruments |
| Infineon Technologies |
| Robert Bosch GmbH |
| Continental AG |
| Denso Corporation |
| Analog Devices |
| NXP Semiconductors |
| STMicroelectronics |
| Aptiv |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation contracts with six-inch GaN substrate foundries lock in both supply access and forward price visibility for tier-one automotive radar suppliers, insulating qualified vendors from spot-market volatility while concentrating procurement leverage among German and South Korean manufacturing clusters.
Pricing Analysis
NHTSA mandates dictate the pricing tier structure across automotive radar modules, separating ISO 26262-certified premium tiers from uncertified economy alternatives. Three-tier pricing stratifies across defense-grade GaN-on-Si assemblies, automotive-qualified CMOS chipsets, and consumer-grade 60 GHz presence sensors. Cost compression in solid-state lidar alternatives is intensifying pricing pressure on 4D imaging radar tiers. Chinese electric vehicle manufacturers exhibit highest price sensitivity, while German defense contractors absorb premium positioning for hermetic-sealed export-controlled systems.
Supply Chain Analysis
Inventory buffers for six-inch GaN wafers stretch 16-20 weeks, constraining module assembly throughput during demand spikes. Supply concentrates among specialty foundries in Germany, the United States, and South Korea, with raw material dependencies spanning high-purity gallium, silicon carbide substrates, and silver-sinter paste formulations. Single-source vulnerability sits with three substrate suppliers controlling GaN-on-Si process maturation. Distribution runs through tier-one automotive suppliers clustered within 200 kilometers of Stuttgart and Munich for Volkswagen Group and BMW integration programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
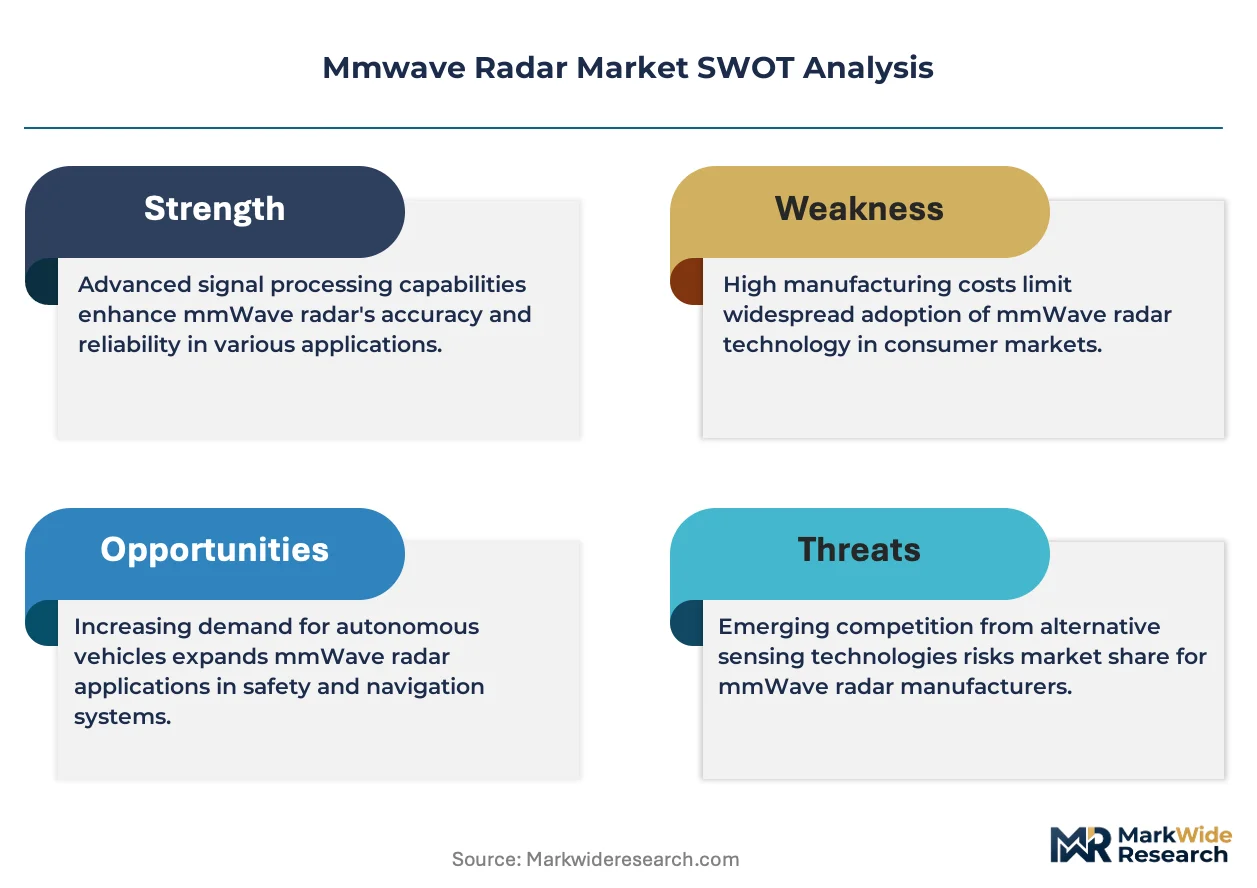
Fragmentation opportunity sits with unbundled hardware-software procurement patterns, as automotive OEMs decouple radar sensor modules from perception algorithm licenses and create niche entry points for specialized RFIC designers.
For Market Incumbents: Fortify GaN-on-Si substrate supply through backward integration or captive offtake agreements with six-inch foundries, while accelerating CMOS radar-on-chip roadmap execution to defend against solid-state lidar substitution in robotaxi applications. Prioritize certification investment for FCC Part 15 and ETSI EN 302 858 multi-domain test facilities to maintain qualification barriers. For New Entrants and Emerging Players: Differentiate on MIMO-Doppler fusion architectures for commercial drone navigation below 400 feet, where spatial multiplexing reduces hardware count against incumbent mechanical-scanning alternatives. Target India's PLI scheme zones for automotive electronics assembly, leveraging production-linked incentives in Tamil Nadu and Gujarat to bypass established European supply chain concentration. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among software-decoupled sensor module vendors supplying hardware to Chinese electric vehicle manufacturers deploying domestic AI stacks. Long-term viability favors acquisition targets with RFIC-antenna co-design expertise and existing automotive qualification timelines. Monitor FCC spectrum reallocation proceedings on 57-71 GHz unlicensed expansion as inflection signal for smart building occupancy sensing addressability.| Strategic Initiative | Industry Significance |
|---|---|
| GaN-on-Si Process Maturation | Higher power density enables longer detection ranges without antenna array expansion for highway-speed autonomous braking. |
| CMOS Radar-on-Chip Integration | Single-chip architectures displace discrete SiGe assemblies and compress bill-of-materials cost for Volkswagen Group volume programs. |
| Hermetic Sealing Process Conversion | Nitrogen backfill and silver-sinter die-attach maintain thermal performance under EU F-Gas Regulation compliance deadlines. |
| MIMO-Doppler Fusion Development | Spatial multiplexing with micro-Doppler extraction enables single-chip obstacle detection for commercial drone navigation. |
| PLI Scheme Zone Expansion | Production-linked incentives attract module assembly investments to Tamil Nadu and Gujarat manufacturing corridors. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across tier-one automotive supplier procurement teams, RFIC design house engineering leads, OEM platform integration specialists, and defense contractor program managers. Primary interview insights were validated against secondary sources including FCC spectrum allocation dockets, ETSI EN 302 858 certification registries, NHTSA vehicle safety rulemaking filings, and MIIT standardization notices. Bottom-up module shipment tallies were triangulated with top-down semiconductor foundry capacity disclosures.
Across the analysis window, forecasts were constructed by modeling frequency band segmentation, waveform technique differentiation, integration level tiers, and end-use certification requirements. CAGRs were derived from elasticity-adjusted adoption curves across automotive ADAS penetration, industrial automation deployment rates, and defense modernization budget trajectories. Industry-specific inputs included GaN substrate supply constraints, spectrum harmonization timelines, and REACH chemical restriction compliance costs.
Material uncertainties — spectrum reallocation decisions, foundry capacity expansion delays, and lidar cost compression trajectories — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory enforcement timing and substrate process yield maturation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Surveillance
North America Passive Radar Market
Military Surveillance
Drone Surveillance Platform Market
Military Surveillance
Surveillance Radar System Market
Military Surveillance
Tactical Optics Market
Military Surveillance
Airborne Target Acquisition Systems Market
Military Surveillance
Military Body-Worn Camera Market
Military Surveillance
Laser Telemetry Binoculars Market
Military Surveillance
Manportable Radar Market
Military Surveillance
Anti-Sniper Detection System Market
Military Surveillance
Military Electro-Optics/Infrared (EO/IR) Systems Market
Military Surveillance
Infrared Anti-Sniper Detection System Market
Military Surveillance
Global Military Man-Portable Radar System Market
Military Surveillance
Global Airborne Surveillance Market
Military Surveillance
Global Military Thermal Imaging Market
Military Surveillance
Land Based Military Electro Optical & IR Systems Market
Military Surveillance
Military Radar Market