
 Anti-Sniper Detection System Market | 2026-2036
Anti-Sniper Detection System Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Sniper Detection System Market Analysis
Subscription-based software-defined threat libraries is pivoting how anti-sniper detection capabilities are delivered, shifting capital expenditure toward recurring revenue models that bundle algorithm updates with hardware deployments. Rheinmetall AG leverages its acoustic sensor manufacturing scale to anchor European military contracts. Raytheon Technologies Corporation sustains technology leadership in radar-based detection through intensive R&D allocation. Thales Group competes across fusion system integration, combining multiple sensor modalities into unified threat-response architectures.
An anti-sniper detection system comprises networked sensor arrays that process acoustic signatures, infrared laser reflections, and millimeter-wave radar returns to calculate projectile origin within sub-second response windows, primarily serving military force protection and critical infrastructure security missions. Acoustic sensors dominate installed volume due to lower unit cost and mature supply chains, while fusion systems capture expanding procurement budgets as end users prioritize multi-spectral confirmation to reduce false alarms in dense urban acoustic environments. Fixed installations anchor revenue stability through perimeter defense contracts, though mobile installation demand accelerates with mechanized infantry modernization programs.
The U.S. Department of Defense mandates MIL-STD-810 environmental compliance and JITC interoperability certification for battlefield sensor networks, while NATO STANAG standards harmonize cross-border system compatibility among allied forces. The EU AI Act and GDPR frameworks increasingly shape algorithm transparency requirements for automated threat classification deployed in civilian protection scenarios. Stakeholders must monitor evolving export control classifications under the Wassenaar Arrangement, which governs cross-border transfer of acoustic-optical targeting technologies and constrains vendor market access decisions.
Market Dynamics
Sensor fusion architectures are compressing procurement cycles as defense buyers prioritize multi-spectral confirmation over single-modality systems, forcing vendors to restructure R&D allocation toward algorithmic integration rather than hardware specialization.
Growth Catalysts
- NATO STANAG harmonization:Cross-border interoperability mandates are accelerating networked shooter detection deployments across allied European forces, reducing integration friction for multinational operations.
- Acoustic-laser sensor convergence:Millimeter-wave radar returns fused with infrared laser reflections enable sub-second projectile origin calculation in dense urban acoustic environments.
- Critical infrastructure hardening:Power generation facilities and transportation hubs are expanding perimeter defense contracts beyond traditional military end-uses.
Market Restraints
- Export control fragmentation:Wassenaar Arrangement classifications on acoustic-optical targeting technologies constrain vendor market access decisions across multiple jurisdictions.
- Algorithm transparency mandates:EU AI Act requirements for automated threat classification in civilian protection scenarios impose compliance burdens on software-defined threat libraries.
- Acoustic sensor commoditization:Mature supply chains for standalone acoustic arrays are compressing margins on basic detection hardware.
Strategic Opportunities
- Mechanized infantry modernization:Mobile installation demand accelerates as vehicle-mounted detection systems replace fixed perimeter arrays in expeditionary force structures.
- Subscription-based threat libraries:Recurring revenue models bundling algorithm updates with hardware deployments are displacing capital-intensive procurement cycles.
- GDPR-compliant edge processing:On-device classification architectures enable civilian deployment in European smart city security frameworks without centralized data transmission.
Industry Challenges
- MIL-STD-810 environmental certification:Battlefield sensor networks require extended qualification timelines that delay revenue recognition for new platform introductions.
- Legacy system integration:Existing command-and-control infrastructure in deployed forces creates interoperability friction for fusion system architectures.
- JITC interoperability validation:Department of Defense certification requirements for networked sensor arrays demand specialized testing protocols that strain vendor engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Sniper Detection System Market |
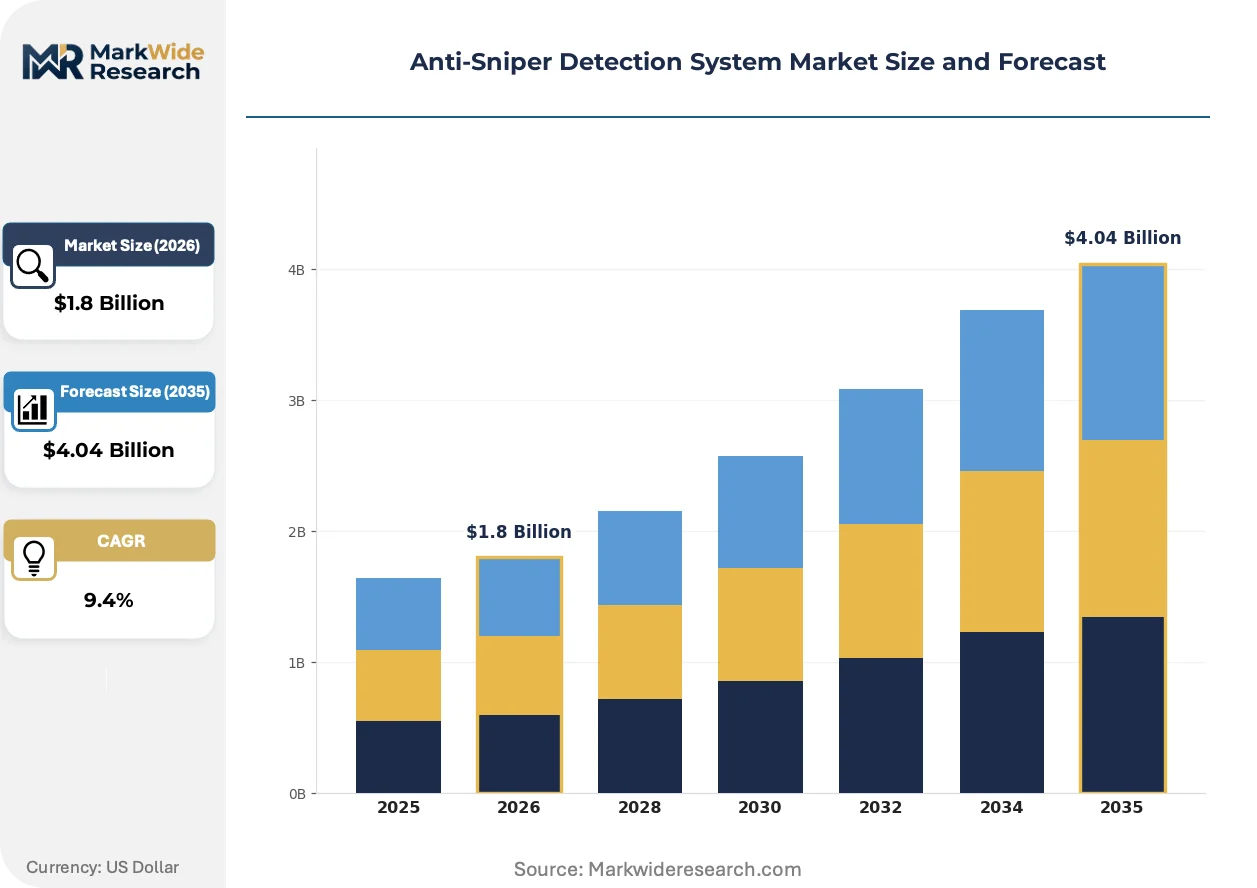
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acoustic Sensors, Radar Systems, Video Surveillance, Laser Detection Technology: Active Detection, Passive Detection, Fusion Systems, Networked Solutions End User: Military, Law Enforcement, Security Agencies, Government Installation: Fixed Installation, Mobile Installation, Temporary Setups, Permanent Structures |
| Companies Covered | Rheinmetall AG, Shooter Detection Systems LLC, Raytheon Technologies Corporation, CILAS, Newcon Optik, Thales Group, Battelle Memorial Institute, ShotSpotter Inc., Rafael Advanced Defense Systems Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Sniper Detection System Market Emerging Trajectories
Algorithmic unification of disparate sensor modalities is restructuring competitive advantage away from hardware performance toward software integration depth, compressing the window for single-technology specialists to establish sustainable positioning.
Multi-spectral fusion platforms are unifying acoustic signatures, infrared laser reflections, and millimeter-wave radar returns into coherent threat-response architectures. Mechanized infantry units across NATO forces are adopting these systems at accelerated procurement cycles. This unification is compressing the addressable market for standalone acoustic sensors while elevating vendor R&D thresholds.
EU AI Act algorithmic transparency requirements are mandating explainable classification logic for automated threat detection deployed in civilian protection scenarios. Industrial consequence includes mandatory documentation of training data provenance and decision boundary parameters. Fusion system vendors serving European critical infrastructure are responding by restructuring development workflows around auditable machine learning pipelines.
Defense buyers are consolidating procurement authority under program offices emphasizing life-cycle cost over unit acquisition price. System integrators and prime contractors are capturing expanded margin pools through bundled sustainment contracts. This concentration is most visible in United States Department of Defense force protection program structures, where multi-year algorithm update subscriptions now accompany initial hardware awards.
Anti-Sniper Detection System Market Segmentation
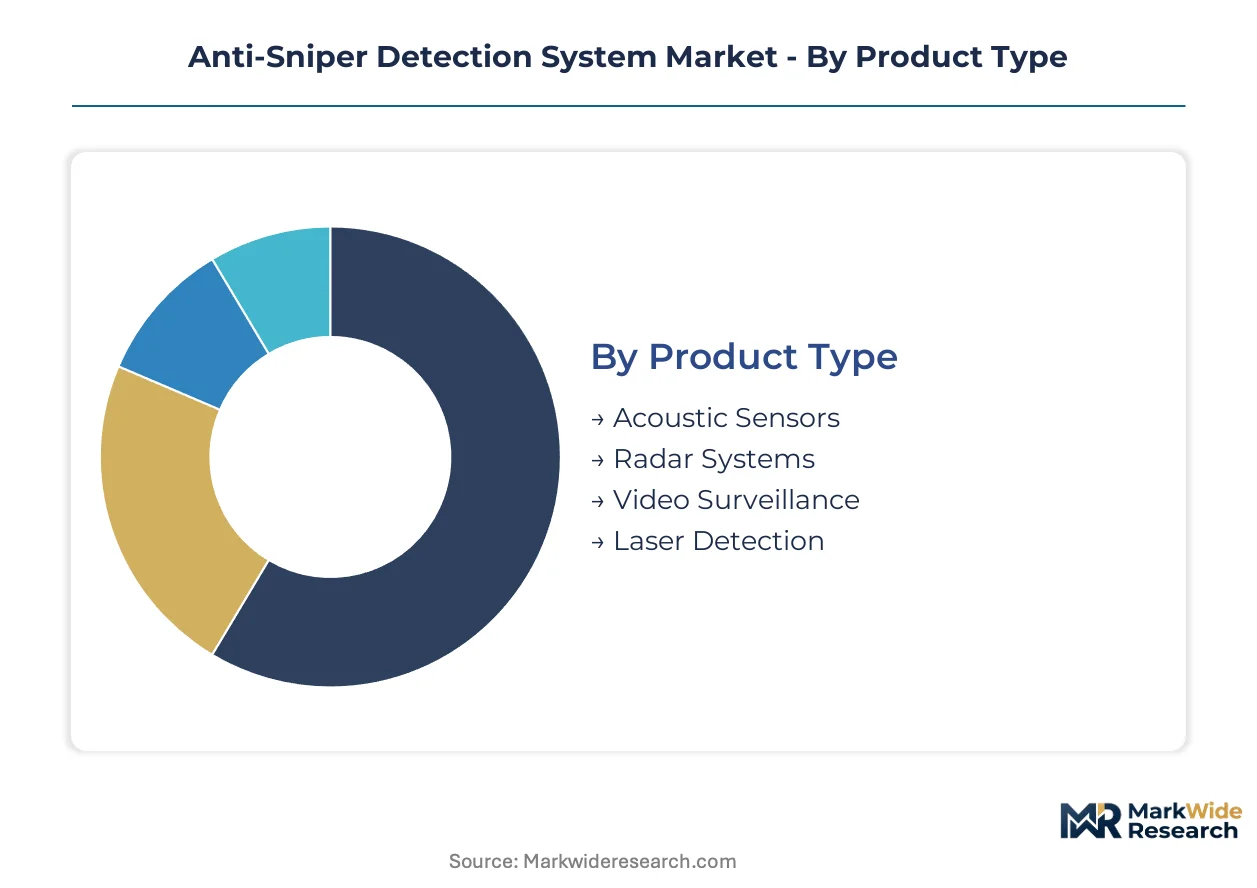
Segmentation in anti-sniper detection reveals distinct procurement patterns between standalone acoustic arrays and integrated fusion architectures. Military buyers prioritize interoperability depth while critical infrastructure operators favor modular upgrade paths. Understanding these divides clarifies where R&D investments concentrate versus where commoditization pressures dominate.
Product Type:
Acoustic sensors operate as standalone perimeter arrays or feed into centralized fusion nodes, with integration depth determining procurement value capture.
- Acoustic Sensors:Microphone arrays triangulate muzzle blast signatures through time-difference-of-arrival algorithms. Demand concentrates in fixed perimeter defense contracts across United States military installations, constrained by false-positive rates in dense urban acoustic environments.
- Radar Systems:Millimeter-wave Doppler radar tracks projectile trajectory through doppler shift analysis. Procurement accelerates in mechanized infantry vehicle integrations across NATO expeditionary forces, driven by all-weather operational requirements.
- Video Surveillance:Optical tracking systems correlate thermal signatures with projectile flash detection.
- Laser Detection:Infrared laser reflection sensors identify optical sight glint for preemptive threat warning.
Acoustic sensors lead volumes today; fusion-integrated radar systems are gaining share fastest.
Technology:
Technology segmentation tracks the shift from single-modality detection toward algorithmic unification, with cost tiers separating legacy deployments from next-generation architectures.
- Active Detection:Systems emit energy pulses and analyze returns to identify sniper positions. Premium pricing applies to radar-based active systems deployed in forward operating bases across Germany and France, where NATO STANAG interoperability mandates drive standardization.
- Fusion Systems:Multi-sensor correlation engines weight acoustic, radar, and laser inputs through Bayesian probability models. United States Department of Defense force protection programs prioritize these architectures, displacing standalone sensor procurement cycles with bundled algorithm subscriptions.
- Passive Detection:Sensors rely exclusively on ambient energy signatures without emission.
- Networked Solutions:Distributed sensor nodes share threat data across command-and-control infrastructure.
Passive detection dominates installed base economics; fusion systems command the steepest expansion trajectory.
End User:
End-user segmentation reflects divergent certification requirements, with military specifications cascading into adjacent security markets through technology transfer programs.
- Military:Battlefield sensor networks require MIL-STD-810 environmental qualification and JITC interoperability validation. Procurement concentrates in United States Army force protection modernization, where multi-year sustainment contracts bundle hardware with algorithm update subscriptions.
- Law Enforcement:Urban SWAT deployment scenarios prioritize rapid setup and civilian-minimized false positives. European adoption accelerates under EU AI Act transparency mandates for automated threat classification in populated areas.
- Security Agencies:Intelligence community deployments emphasize covert installation and minimal electromagnetic signature.
- Government:Critical infrastructure protection spans power generation and transportation hub perimeters.
Military end-users anchor revenue stability; law enforcement represents the fastest-climbing demand segment.
Installation:
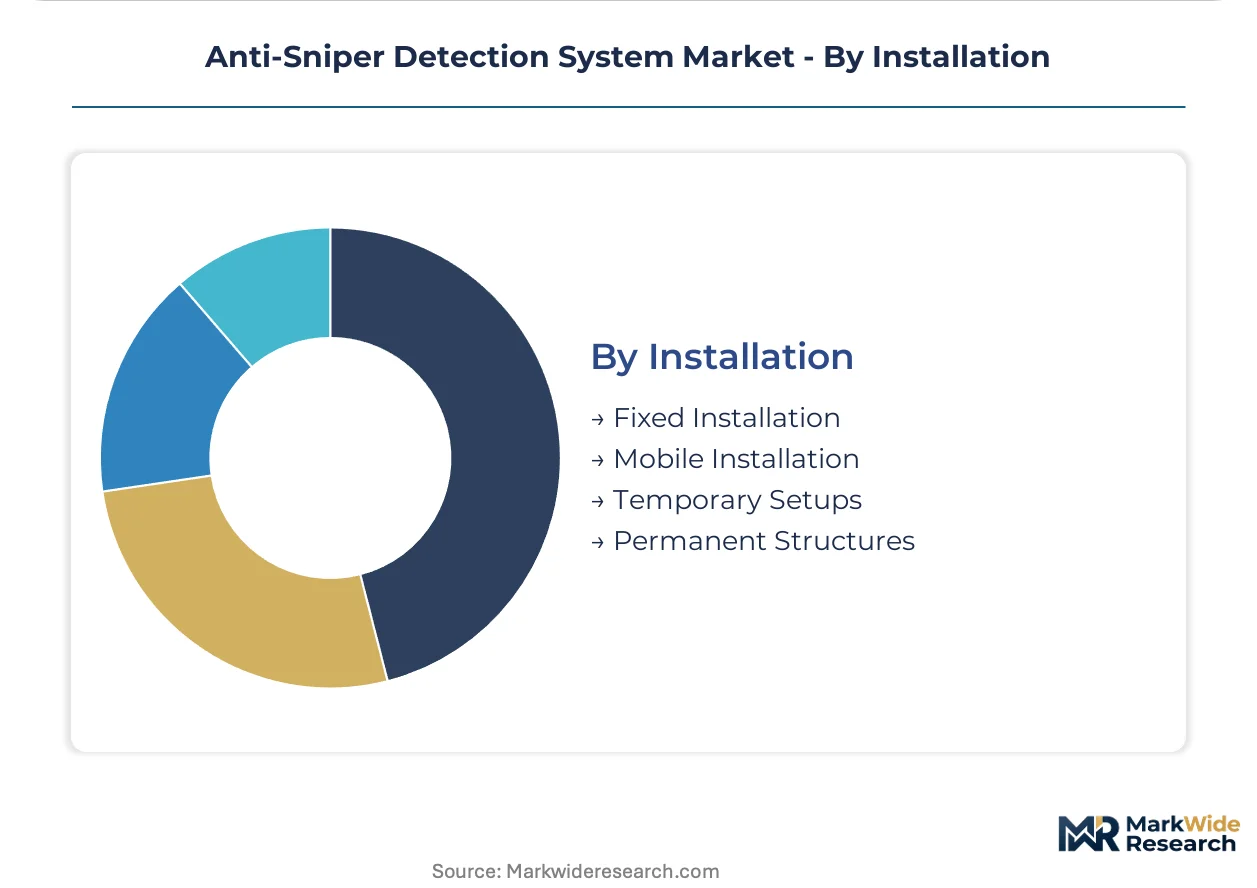
Installation type determines supply chain configuration, with fixed structures leveraging civil engineering contractors while mobile systems integrate with vehicle OEM qualification timelines.
- Fixed Installation:Permanent sensor towers and building-integrated arrays anchor long-term perimeter defense contracts. Revenue concentrates in United States power generation facility hardening programs, where twenty-year service agreements lock in vendor relationships.
- Mobile Installation:Vehicle-mounted and man-portable systems support expeditionary force structures. NATO mechanized infantry modernization across Poland and Romania drives procurement acceleration, with platform integration requirements extending vendor engineering obligations.
- Temporary Setups:Rapidly deployable tripods and vehicle-hitch mounts serve rotating security details.
- Permanent Structures:Hardened shelters and buried cable networks support critical infrastructure.
Fixed installations maintain volume leadership; mobile systems are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting production investment toward jurisdictions with streamlined defense export frameworks and aligned certification reciprocity. Vendors now site final assembly where Wassenaar Arrangement compliance costs least constrain cross-border system transfer.
United States
Department of Defense force protection modernization drives procurement concentration through multi-year sustainment contracts bundling hardware with algorithm subscriptions. JITC interoperability validation and MIL-STD-810 environmental certification create steep vendor qualification barriers. Defense industrial clusters in Virginia and Texas anchor system integration and field testing infrastructure.
Germany
Rheinmetall AG's acoustic sensor manufacturing scale anchors European military contract capture across NATO STANAG harmonization mandates. KBA export licensing frameworks and Bundeswehr technical specifications shape procurement timelines. Industrial concentration in Bavaria and North Rhine-Westphalia supports sensor fabrication and system integration capacity.
France
Thales Group competes across fusion system integration combining multiple sensor modalities into unified threat-response architectures. ANSM and CNIL oversight of AI-enabled classification systems imposes algorithm transparency documentation requirements. Paris-Saclay and Toulouse aerospace clusters concentrate R&D for multi-spectral detection algorithms.
Israel
Rafael Advanced Defense Systems Ltd. occupies a specialized position in active protection and threat detection technology development. Israeli defense export licensing under the Defense Export Control Agency governs system transfer to allied forces. Tel Aviv and Haifa metropolitan areas concentrate startup and mid-tier sensor technology development.
United Kingdom
Raytheon Technologies Corporation sustains technology leadership positioning through intensive R&D allocation directed at radar-based detection architectures. UK Ministry of Defence procurement through the Defence Equipment and Support organization shapes contract structures. Defense technology clusters in Greater London and the Midlands support subsystem integration and testing.
Anti-Sniper Detection System Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with system integrators capturing expanded margin pools through bundled sustainment contracts while component suppliers face commoditization pressure. Market structure tilts toward consolidation under prime contractor concentration, particularly in United States Department of Defense program offices emphasizing life-cycle cost over unit acquisition price. Three archetypes dominate: diversified defense conglomerates with sensor fusion platforms, acoustic sensor specialists leveraging manufacturing scale, and software-defined threat library vendors pivoting toward subscription revenue models. Competitive moves concentrate on strategic partnerships for algorithm development and geographic expansion through defense export licensing.
Among diversified defense conglomerates, Raytheon Technologies Corporation and Thales Group exemplify the fusion system integrator archetype, anchoring positions through multi-spectral platform development. Rheinmetall AG represents the manufacturing-scale specialist model, leveraging acoustic sensor production capacity to secure NATO European contracts. These three entities occupy distinct competitive spaces—Raytheon through radar-based detection leadership, Thales through multi-sensor correlation engines, and Rheinmetall through cost-optimized acoustic array deployment—each representing a viable path to vendor sustainability under shifting procurement authority structures.
| Leading Market Players |
|---|
| Rheinmetall AG |
| Shooter Detection Systems LLC |
| Raytheon Technologies Corporation |
| CILAS |
| Newcon Optik |
| Thales Group |
| Battelle Memorial Institute |
| ShotSpotter Inc. |
| Rafael Advanced Defense Systems Ltd. |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between MIL-STD-810 qualified fusion systems and commercial acoustic arrays manifests in pricing spreads exceeding three-to-one, with the former commanding bundled algorithm subscriptions while the latter faces commoditization pressure from mature microphone supply chains concentrated in East Asian manufacturing hubs.
Pricing Analysis
Direct-to-OEM discounts compress distributor margins for vehicle-mounted detection systems serving NATO mechanized infantry programs, while standalone acoustic arrays flow through defense integrators capturing markup on JITC-certified configurations. Three-tier pricing structure across premium fusion platforms, standard networked arrays, and economy standalone sensors reflects certification depth and algorithm update bundling. Cost compression in acoustic hardware intensifies as Chinese microphone manufacturers expand capacity, eroding European specialist margins. Law enforcement buyers exhibit highest price sensitivity, prioritizing rapid deployment over multi-spectral confirmation, while United States Department of Defense program offices emphasize life-cycle cost minimization through multi-year sustainment contracts.
Supply Chain Analysis
Single-source vulnerability sits with Taiwanese millimeter-wave radar component suppliers serving fusion system integrators, where foundry capacity constraints ripple through NATO procurement timelines. German acoustic sensor fabrication and Israeli laser detection module production anchor tier-one supply, while Chinese gallium arsenide substrate processing feeds infrared sensor arrays. Supply chain risk centers on Wassenaar Arrangement licensing delays for acoustic-optical targeting technologies crossing multiple jurisdictions. Distribution runs through prime contractor integration facilities in Virginia, Bavaria, and Greater London before final military acceptance testing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities concentrate where EU AI Act compliance costs deter European algorithm development, enabling United States-based software-defined threat library vendors to capture premium positioning through regulatory-differential pricing.
For Market Incumbents: Anticipate margin compression from subscription-based revenue models displacing capital-intensive hardware procurement cycles. Rheinmetall AG and Raytheon Technologies Corporation should deepen backward integration into acoustic sensor fabrication and radar component supply respectively, locking in cost positions against Chinese manufacturing scale. Priority lever rests on algorithm update bundling to sustain recurring revenue attachment rates.
For New Entrants and Emerging Players: European critical infrastructure operators underserved by GDPR-compliant edge processing architectures represent the most penetrable buyer archetype. White-space targets include Polish and Romanian mechanized infantry modernization programs seeking vehicle-mounted detection without NATO prime contractor markup, plus civilian smart city security frameworks requiring on-device classification. Go-to-market angle emphasizes algorithm transparency documentation satisfying EU AI Act mandates.
For Investors and Strategic Acquirers: Consolidation pressure builds where standalone acoustic sensor vendors face commoditization without fusion platform integration capabilities. Long-term viability favors acquisition targets possessing MIL-STD-810 certification infrastructure and JITC validation relationships, enabling rapid entry into United States Department of Defense program offices. Signal to watch is subscription revenue ratio crossing threshold majority against hardware-only bookings.
| Strategic Initiative | Industry Significance |
|---|---|
| Algorithm Subscription Bundling | Recurring revenue models displace capital-intensive procurement cycles in United States DoD programs. |
| GDPR-Compliant Edge Processing | On-device classification enables European smart city security without centralized data transmission. |
| Backward Integration into Acoustic Sensors | Captive microphone array production secures margin against Chinese manufacturing scale expansion. |
| NATO STANAG Harmonization Certification | Cross-border interoperability mandates accelerate networked shooter detection deployment across allied forces. |
| Mechanized Infantry Platform Integration | Vehicle-mounted detection systems replace fixed perimeter arrays in expeditionary force structures. |
Methodological Framework
Bottom-up military procurement modeling reconciled against top-down defense industrial base tracking forms the analytical core, combining primary interviews with program office acquisition leads, system integration engineers, and algorithm development directors alongside secondary validation through Department of Defense budget justification documents, NATO procurement databases, and Wassenaar Arrangement classification records. Triangulation across stakeholder inputs and regulatory filings ensures segmentation integrity across product type, technology, end user, and installation dimensions.
Historical trendline analysis of force protection modernization cycles and critical infrastructure hardening programs informs projection frameworks across the modeling period, with growth trajectories derived from procurement authority concentration patterns and algorithm update subscription attachment rates. Segmentation dimensions modeled include sensor modality, fusion integration depth, military versus civilian end use, and fixed versus mobile installation type. Industry-specific forecast inputs incorporate JITC interoperability validation timelines and EU AI Act compliance burden assessments.
Underlying measurement precision varies by segment; fusion system revenue carries tighter precision than commoditized acoustic array volumes due to concentrated prime contractor disclosure. Forecasts reflect assumptions regarding NATO STANAG harmonization continuity and Wassenaar Arrangement classification stability, with revision risk concentrated in export control policy shifts and algorithm transparency mandate evolution. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Surveillance
Asia-Pacific Hydrographic Survey Equipment Market
Military Surveillance
Military Electro-Optics/Infrared (EO/IR) Systems Market
Military Surveillance
Global Mine Detection System Market
Military Surveillance
Global Military Electro-Optical and Infrared Systems Market
Military Surveillance
Military Jammer Market
Military Surveillance
Airborne Target Acquisition Systems Market
Military Surveillance
Passive Radar Market
Military Surveillance
Military Radar Market
Military Surveillance
Military Imaging System Market
Military Surveillance
Tactical Optics Market
Military Surveillance
Early Warning Radar Market
Military Surveillance
Tactical Scope Market
Military Surveillance
Drone Surveillance Platform Market
Military Surveillance
Global Radar Market
Military Surveillance
Drone Surveillance Market
Military Surveillance
Europe Hydrographic Survey Equipment Market