
 Aviation Carpet Market | 2026-2036
Aviation Carpet Market Size, Share, and Industry Trends Forecast 2026-2036
Aviation Carpet Market Analytics
Market Context
Aftermarket service contracts for cabin refresh cycles is decoupling carpet procurement from original equipment manufacturer bundles, allowing airlines to source directly from specialized textile suppliers. Mohawk Carpet LLC leverages its broad manufacturing footprint to compete on scale across North American carrier programs. Desso Aviation anchors its position through advanced dyeing technologies that reduce weight while meeting strict burn-test requirements. Lantal Textiles AG specializes in custom patterning capabilities that differentiate its offerings for premium cabin configurations.
Technical Definition and Segment Structure
Aviation carpet refers to flame-resistant floor coverings engineered from synthetic or natural fibers, typically meeting 12-second vertical burn tests and smoke density limits under FAR 25.853, designed to provide durable, lightweight surfacing for aircraft interiors. Nylon dominates product type volumes due to its resilience and ease of maintenance, while wool commands premium positioning in first-class and private jet segments where tactile quality outweighs cost sensitivity. Passenger cabins represent the largest application pool, though cargo area retrofits are gaining traction as e-commerce operators convert passenger aircraft to freighter configurations.
Regulatory Frame and Outlook
FAA certification under 14 CFR 25.853 and EASA CS-25 standards govern flammability, smoke emission, and toxicity thresholds, creating compliance barriers that favor established suppliers with testing infrastructure. The EU REACH regulation and evolving MEE environmental standards in China are restricting certain chemical treatments historically used for stain resistance and flame retardancy. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance with multiple certification regimes will determine supplier eligibility for international fleet operators.
Market Dynamics
Retrofit-driven procurement cycles are decoupling aviation carpet purchasing from OEM bundles, forcing specialized textile suppliers to compete directly on certification speed and pattern customization rather than scale economies alone.
Growth Catalysts
- Narrow-body fleet modernization:US carriers are accelerating cabin refresh programs on aging domestic aircraft, creating sustained replacement demand independent of new aircraft deliveries.
- EASA CS-25 harmonization:Alignment between European and FAA flammability testing protocols is reducing dual-certification burdens for cross-border fleet operators.
- Freighter conversion surge:E-commerce logistics operators are stripping passenger cabins for cargo configurations, requiring specialized carpet solutions for modified floor structures.
Market Restraints
- Petrochemical feedstock volatility:Nylon 6,6 polymer prices fluctuate with crude oil derivatives, compressing margins for manufacturers locked into long-term airline contracts.
- Testing infrastructure concentration:Burn-test certification facilities cluster in Ohio, Texas, and Hamburg, creating geographic bottlenecks for new market entrants.
- Wool substitution ceiling:Premium tactile requirements in private aviation face hard limits from sheep fiber availability and dye-lot consistency challenges.
Strategic Opportunities
- India domestic aviation expansion:IndiGo and Air India fleet growth under DGCA oversight creates demand for locally certified suppliers with faster turnaround than European imports.
- Digital dye-sublimation patterning:On-demand customization technology enables micro-batch production for airline livery refreshes without minimum order penalties.
- EU REACH regulatory tailwind:Phased restrictions on legacy flame retardants are opening qualification slots for bio-based alternatives meeting ECHA safety thresholds.
Industry Challenges
- Certification timeline compression:FAA 14 CFR 25.853 test scheduling delays of 8-14 weeks are misaligning with airline cabin retrofit windows.
- Legacy ERP integration:Specialized carpet suppliers struggle to interface with Boeing and Airbus supplier portals for real-time order visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aviation Carpet Market |
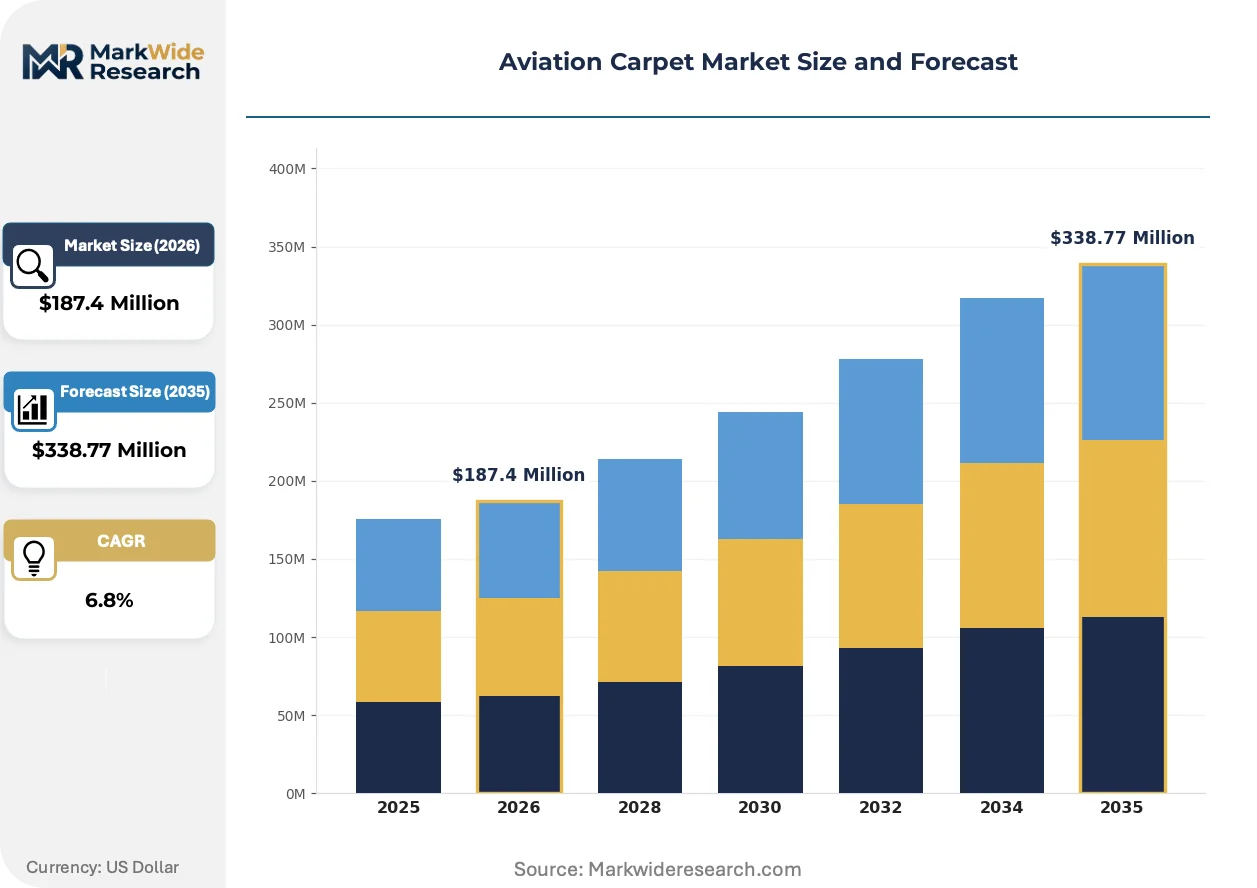
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nylon, Polyester, Polypropylene, Wool Application: Cargo Areas, Passenger Cabins, Lavatories, Galleys End User: Commercial Airlines, Private Jets, Helicopter Operators, Charter Services Installation Type: Direct Glue, Stretch-in, Carpet Tiles, Loose Lay |
| Companies Covered | Mohawk Carpet LLC, Desso Aviation, Lantal Textiles AG, Botany Weaving, SCS Interiors, Anker Gebr. Schoeller GmbH + Co. KG, BIC Carpets, Haeco Cabin Solutions, Aircraft Interior Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aviation Carpet Market Evolving Landscape
Material science advances and regulatory chemistry restrictions are converging to redefine performance benchmarks, while procurement digitization is collapsing traditional channel structures between mills and fleet operators.
Solution-dyed nylon with embedded conductive fibers is rewriting durability standards for high-traffic galleys and entryways. Low-cost carriers operating 200-plus aircraft fleets are specifying these materials for 36-month replacement cycles rather than 18-month traditional intervals. The technology is compressing total cost-of-ownership calculations and shifting supplier selection criteria toward lifecycle performance metrics.
EU REACH Annex XVII restrictions on halogenated flame retardants are forcing reformulation of stain-resistant treatments across European-registered fleets. Manufacturers serving Lufthansa, Air France-KLM, and International Airlines Group must now qualify phosphorus-based alternatives through ECHA notification procedures. First-class and business cabin segments are absorbing premium pricing for compliant materials while economy configurations face specification downgrades.
Direct mill-to-airline contracting is displacing tier-one seat integrators as the primary procurement channel for carpet refresh programs. American Airlines, Delta, and United have established dedicated textile sourcing teams that bypass traditional OEM supply agreements. This pattern is most visible in the United States, where aftermarket service unbundling has progressed furthest among major network carriers.
Aviation Carpet Market Segmentation
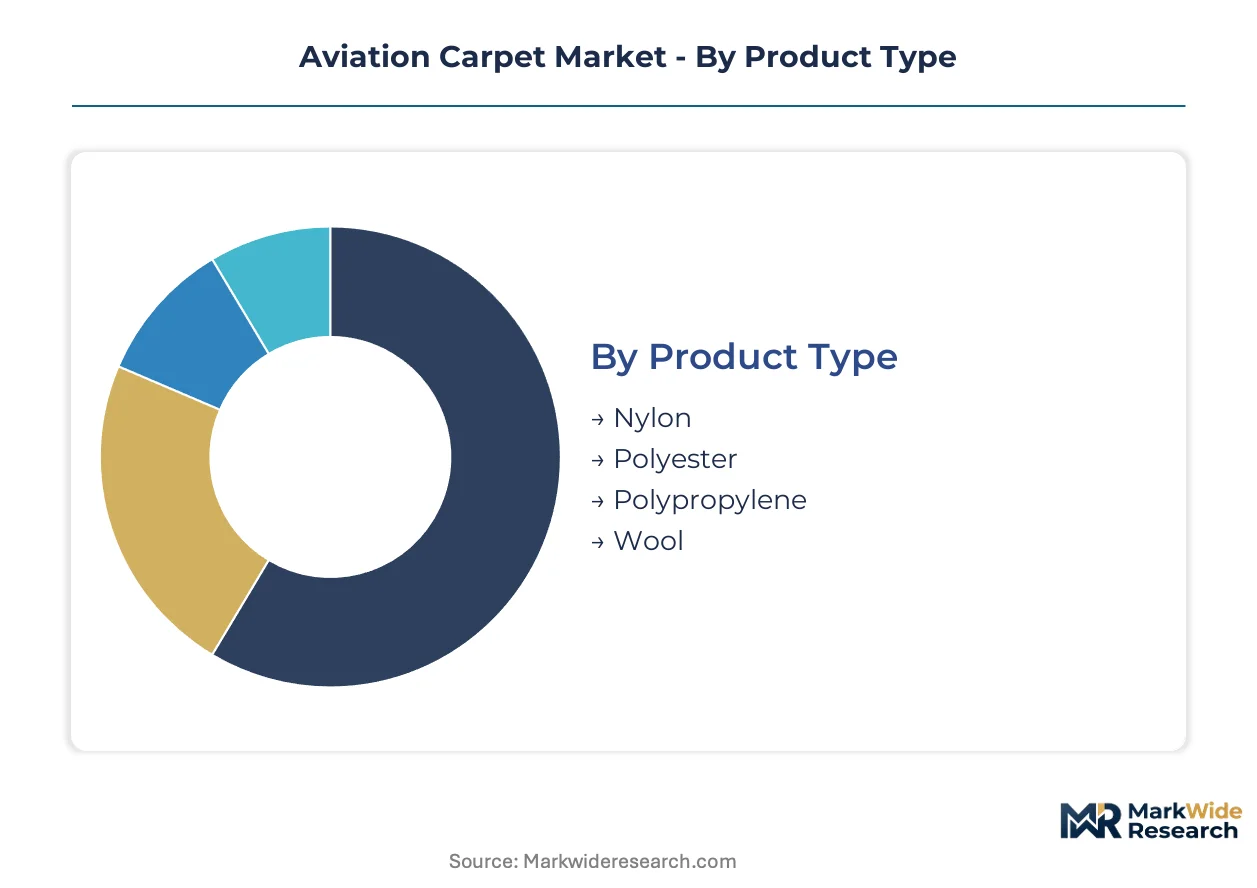
Aviation carpet procurement patterns diverge sharply across material chemistry, installation method, and end-use environment. Each segment carries distinct certification burdens and replacement cycles that reshape supplier economics.
Product Type:
Polymer feedstock sourcing clusters in Texas, Belgium, and Zhejiang province, concentrating resin supply chains for synthetic fiber producers.
- Nylon:Solution-dyed nylon 6,6 dominates high-traffic zones with embedded conductive fibers for static dissipation. US narrow-body retrofit programs specify this material for 36-month replacement cycles in entryways and galleys.
- Wool:Natural fiber retains premium positioning in private jet and first-class configurations where tactile warmth outweighs maintenance burden. Sheep fiber dye-lot consistency limits batch scalability, constraining volume expansion.
- Polyester:Lower-cost synthetic alternative gaining share in regional turboprop fleets operating under less stringent wear requirements.
- Polypropylene:Lightweight olefin fiber specified for cargo conversion programs where weight reduction supersedes durability metrics.
Nylon absorbs the bulk of installed capacity; polypropylene is expanding most quickly.
Application:
Functional zones impose divergent flammability and wear specifications that fragment manufacturing tooling requirements.
- Passenger Cabins:Main deck surfacing accounts for the largest addressable volume, with FAA 14 CFR 25.853 certification mandatory for all materials. Pattern customization demands are highest here, driving digital dye-sublimation investment.
- Galleys:High-moisture, high-impact zones require solution-dyed fibers with enhanced stain resistance. EU REACH restrictions on halogenated flame retardants are forcing reformulation of treatments for European-registered fleets.
- Cargo Areas:Freighter conversions from passenger aircraft require specialized floor surfacing for modified load-bearing structures. E-commerce logistics operators are stripping cabins and installing industrial-grade alternatives.
- Lavatories:Confined wet environments demand antimicrobial treatments and rapid-drainage backing systems.
Passenger cabins command the majority of procurement spend; cargo area retrofits are climbing the fastest.
End User:
Customer procurement sophistication varies from centralized fleet management to single-aircraft owner decisions.
- Commercial Airlines:Network carriers with 200-plus aircraft fleets unbundle carpet procurement from OEM seat integrators. American Airlines, Delta, and United operate dedicated textile sourcing teams.
- Private Jets:Ultra-high-net-worth owners prioritize bespoke patterning and natural fiber content over lifecycle cost.
- Helicopter Operators:Rotary-wing platforms require lighter-weight materials due to payload sensitivity.
- Charter Services:Fractional ownership fleets balance refresh frequency against utilization rates.
Commercial airlines generate the dominant revenue base; private jets maintain the steepest margin premiums.
Installation Type:
Attachment methodology determines labor cost structure and aircraft downtime during retrofit events.
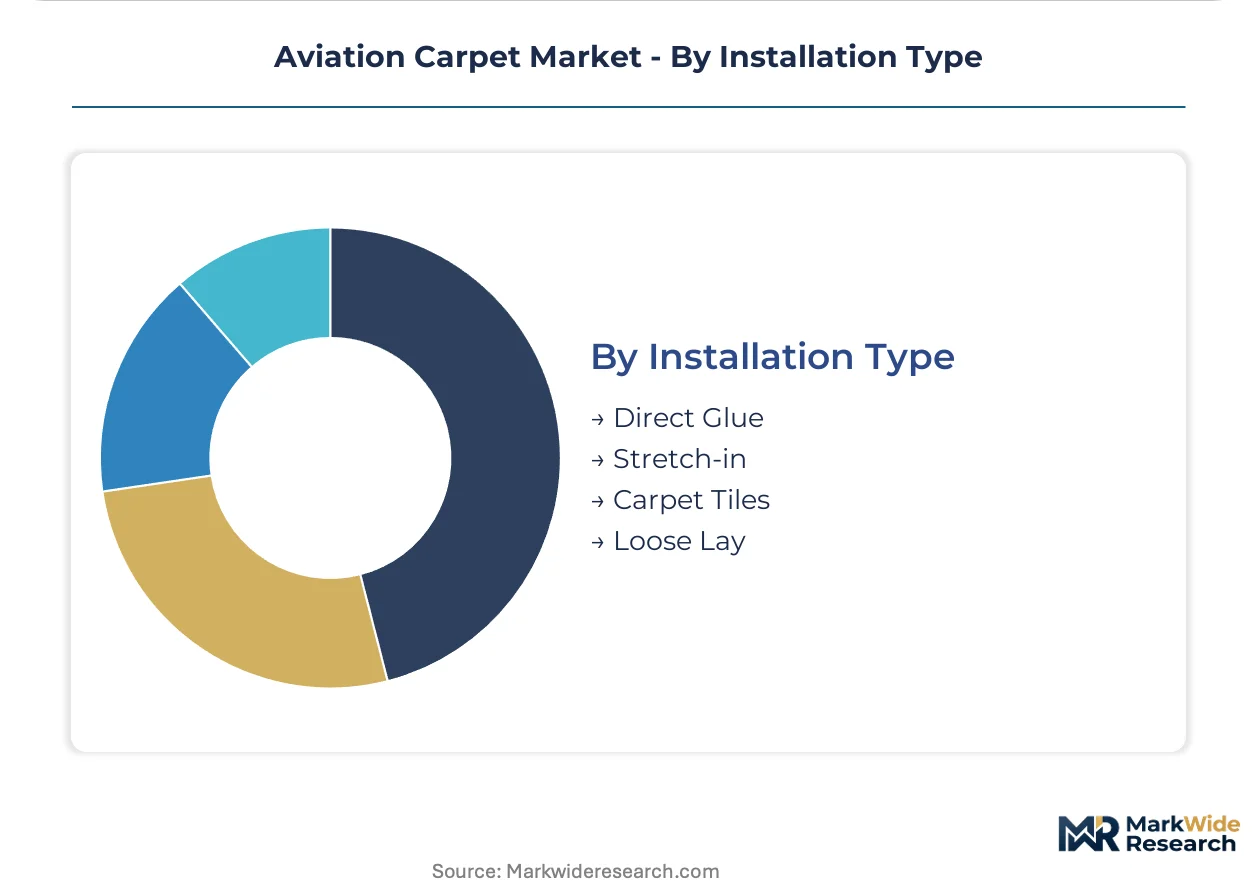
- Direct Glue:Permanent adhesive bonding specified for long-haul wide-body configurations where carpet remains in place for 5-7 years.
- Carpet Tiles:Modular systems enable spot replacement in high-wear zones without full cabin removal.
- Stretch-in:Tension-mounted installation allows rapid swap-out during overnight maintenance windows.
- Loose Lay:Temporary surfacing for cargo conversions and short-term lease transitions.
Direct glue retains the largest installed base; carpet tiles are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in Belgium, the United States, and Germany, while fleet renewal demand concentrates in North America and Asia-Pacific. This geographic split creates logistics complexity for specialized textile suppliers managing certification across multiple jurisdictions.
United States
American Airlines, Delta, and United operate dedicated textile sourcing teams that bypass traditional OEM supply agreements. FAA 14 CFR 25.853 certification requirements govern all cabin materials. Burn-test facilities in Ohio and Texas create geographic bottlenecks for new market entrants seeking qualification.
China
Domestic carriers under CAAC oversight are expanding narrow-body fleets at double-digit rates. MEE environmental standards are restricting certain chemical treatments historically used for stain resistance. Manufacturing clusters in Zhejiang province concentrate resin supply chains for synthetic fiber producers.
Germany
Lufthansa Group's fleet standardization programs drive specification harmonization across European-registered aircraft. EASA CS-25 flammability protocols align with FAA testing, reducing dual-certification burdens. Hamburg hosts concentrated burn-test infrastructure serving continental airlines.
India
IndiGo and Air India fleet growth under DGCA oversight creates demand for locally certified suppliers. PLI scheme incentives for aerospace manufacturing are attracting textile investments. Maharashtra and Karnataka are emerging as maintenance hub locations with carpet refurbishment capabilities.
United Arab Emirates
Emirates and Etihad operate superjumbo fleets requiring specialized premium cabin materials. GCAA regulations mirror EASA standards with additional local notification requirements. Dubai's logistics infrastructure supports rapid turnaround for Middle East and African carrier programs.
Aviation Carpet Market Competitive Landscape
Top-tier vendors anchor certification-heavy supply relationships with major network carriers, while mid-scale specialists compete on pattern customization speed and micro-batch flexibility. The vendor base separates into three strategic archetypes: integrated textile conglomerates with broad manufacturing footprints, aviation-specialized mills with dedicated burn-test infrastructure, and regional fabricators serving niche retrofit programs. Capacity expansion and direct airline contracting represent the dominant competitive moves reshaping channel structures.
Among the integrated conglomerates, Mohawk Carpet LLC anchors scale-driven positioning across North American programs, while Desso Aviation exemplifies technology-focused specialization through advanced dyeing capabilities. Lantal Textiles AG occupies the custom-patterning tier for premium cabin configurations. These three entities represent distinct strategic postures: manufacturing breadth, technical differentiation, and bespoke design capability.
| Leading Market Players |
|---|
| Mohawk Carpet LLC |
| Desso Aviation |
| Lantal Textiles AG |
| Botany Weaving |
| SCS Interiors |
| Anker Gebr. Schoeller GmbH + Co. KG |
| BIC Carpets |
| Haeco Cabin Solutions |
| Aircraft Interior Products |
| Others |
Value Network & Pricing Analysis
Network carrier procurement teams at American Airlines, Delta, and United command substantial leverage over specialized textile mills, compressing supplier margins through direct mill-to-airline contracting that bypasses traditional OEM intermediaries. This buyer concentration forces pricing discipline across certification-heavy material tiers while rewarding scale-backed manufacturers with volume guarantees.
Pricing Analysis
Margin tightening in economy cabin specifications reflects petrochemical feedstock volatility and compressed airline refresh budgets. Three-tier pricing structure across premium, standard, and economy levels separates wool-first-class configurations from solution-dyed nylon mid-tier offerings and polypropylene cargo alternatives. Cost-down pressure accelerates because EASA-FAA harmonization enables dual-certification sourcing that pits European mills against North American competitors. Charter operators and regional turboprop fleets exhibit highest price sensitivity; private jet owners absorb premium positioning with minimal negotiation.
Supply Chain Analysis
Technical textile workforce availability in Belgium, Germany, and the United States anchors manufacturing capacity for burn-test-qualified production. Resin supply chains draw from Texas and Zhejiang province for nylon 6,6 polymer feedstock, while wool fiber sourcing rests on Australian and New Zealand sheep farming regions. Single-source vulnerability concentrates in Ohio and Hamburg burn-test facilities, creating qualification bottlenecks for new market entrants. Distribution runs through dedicated aerospace logistics channels serving fleet operator maintenance hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aviation carpet manufacturing is consolidating around certification infrastructure owners as EU REACH compliance costs and FAA test scheduling delays eliminate marginal competitors without laboratory assets.
For Market Incumbents: Cement supply relationships through captive burn-test capacity expansion in Ohio or Hamburg, insulating against qualification timeline compression that disrupts retrofit windows. Deepen backward integration into solution-dyed nylon polymer production to offset petrochemical price volatility threatening long-term contract profitability.
For New Entrants and Emerging Players: Begin with digital dye-sublimation patterning capabilities targeting Indian domestic carriers under DGCA oversight, where PLI scheme incentives and fleet growth outpace European import turnaround times. Pursue cargo conversion specialization for e-commerce logistics operators stripping passenger cabins, a segment with lower certification barriers and faster procurement cycles.
For Investors and Strategic Acquirers: The window for entry favors aviation-specialized mills with existing FAA-EASA dual certification and established airline direct contracts. Watch for inflection when freighter conversion volumes trigger capacity constraints at incumbent testing facilities, forcing carriers to qualify secondary suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Burn-Test Infrastructure Expansion | Captive FAA 14 CFR 25.853 certification capacity secures retrofit program eligibility against scheduling bottlenecks. |
| Backward Integration into Polymer Production | In-house nylon 6,6 resin manufacturing insulates margins from crude oil derivative price swings. |
| Digital Dye-Sublimation Technology Deployment | On-demand patterning enables micro-batch airline livery refreshes without minimum order penalties. |
| India Manufacturing Footprint Establishment | DGCA-certified local production captures IndiGo and Air India fleet expansion with faster turnaround than imports. |
| Bio-Based Flame Retardant Formulation | ECHA-compliant phosphorus alternatives open qualification slots as EU REACH restricts legacy halogenated treatments. |
Research Methodology
Multi-period observation of narrow-body retrofit cycle frequency, burn-test facility queue lengths, and airline procurement team formation anchored the trend analysis, supplemented by interviews with cabin engineering directors, fleet procurement managers, textile mill technical directors, and aftermarket service contract administrators. Secondary validation drew from FAA certification databases, EASA CS-25 regulatory filings, EU REACH Annex XVII restriction timelines, and carrier fleet planning disclosures. Bottom-up airline program sizing and top-down synthetic fiber demand estimates were triangulated for cross-verification.
An input-output matrix structured the analytical framework across the projection horizon, modeling passenger cabin, galley, cargo area, and lavatory application segments alongside nylon, wool, polyester, and polypropylene material chemistry tiers. CAGRs were derived from replacement cycle compression rates and fleet expansion trajectories. Forecast inputs incorporated petrochemical price correlation coefficients and EASA-FAA harmonization implementation schedules.
Underlying measurement precision varies by segment; narrow-body retrofit volumes and US carrier procurement patterns carry tighter precision than private jet wool specification trends. Forecasts reflect assumptions regarding certification timeline normalization and REACH regulatory phase-in adherence. Material deviation in crude oil derivative pricing or burn-test facility capacity expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Cabin Interior
Middle East Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Aerospace Interior Market
Aircraft Cabin Interior
Aircraft Amenities and Auxiliaries Market
Aircraft Cabin Interior
Aerospace Lavatory System Market
Aircraft Cabin Interior
Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Europe Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Emergency Exit Hatch Lightweight Composite Structures Market
Aircraft Cabin Interior
Commercial Aircraft Upholstery Market
Aircraft Cabin Interior
Commercial Aircraft Floor Panels Market
Aircraft Cabin Interior
Europe Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
Middle-East and Africa Commercial Aircraft Cabin Interior Market
Aircraft Cabin Interior
North America Commercial Aircraft Cabin Seating Market
Aircraft Cabin Interior
Autonomy-Ready eVTOL Cabin HMI Systems Market
Aircraft Cabin Interior
Aircraft Seating Market
Aircraft Cabin Interior
Aircraft Curtains Market
Aircraft Cabin Interior
Global Aircraft Cabin Upgrades Market