
 Global Military Man-Portable Radar System Market | 2026-2036
Global Military Man-Portable Radar System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Military Man-Portable Radar System Market Foresight
Defense procurement channels across NATO and Indo-Pacific alliance structures are reshaping vendor access and contract bundling for man-portable radar systems. Thales Group leverages its European manufacturing footprint to sustain national preference clauses in French and British tenders. Saab AB anchors Nordic interoperability requirements through its Giraffe product architecture. Elbit Systems Ltd. competes in asymmetric warfare segments where force protection and counter-drone missions dominate procurement specifications.
A military man-portable radar system comprises lightweight, battery-operated or man-transportable sensor platforms operating in X-band, Ku-band, or millimeter-wave frequencies, typically weighing under 45 kilograms and designed for rapid deployment by dismounted soldiers or small tactical units. These systems generate real-time situational awareness for ground commanders through doppler processing, synthetic aperture imaging, or electronically scanned arrays, with primary purposes spanning perimeter security, drone detection, and battlefield reconnaissance. Counter-drone system types command premium positioning as swarm threats proliferate across operational theaters, while phased array technology segments attract R&D concentration due to beam agility advantages in cluttered electromagnetic environments. Ground surveillance applications retain mature volume bases, though force protection missions show accelerated growth trajectories reflecting urban warfare doctrine shifts.
US DoD Joint Staff interoperability mandates, NATO STANAG 4671 for unmanned systems, and EU Defense Fund certification pathways collectively shape product development roadmaps and cross-border sales eligibility for man-portable radar manufacturers. FCC spectrum allocations in the United States and EASA emerging drone regulations in Europe further constrain transmit power and frequency agility parameters that define competitive technical specifications. Stakeholders must monitor evolving counter-UAS doctrine integration across allied defense ministries to anticipate procurement cycle timing and technical requirement migrations.
Market Dynamics
Interoperability mandates from the US Department of Defense's Joint Counter-Small Unmanned Aircraft Systems Office are compressing procurement cycles and forcing architecture standardization across allied defense ministries, fundamentally restructuring vendor qualification pathways.
Growth Catalysts
- Counter-drone mission expansion:NATO Special Operations units are accelerating procurement of man-portable variants optimized for swarm detection and tracking in contested electromagnetic environments.
- STANAG 4671 harmonization:NATO's unmanned systems standardization framework is creating cross-border sales eligibility for compliant radar manufacturers serving allied defense ministries.
- Indo-Pacific littoral surveillance:Maritime perimeter security requirements across Philippines, Japan, and Australia are driving force protection radar deployments in coastal defense architectures.
Market Restraints
- Gallium nitride supply concentration:Critical semiconductor substrate for phased array transmitters faces sourcing bottlenecks from limited high-purity foundry capacity in East Asia.
- Export control friction:US International Traffic in Arms Regulations and EU dual-use export licensing create multi-month approval delays for cross-border system transfers.
- Battery energy density ceiling:Lithium-ion pack limitations constrain continuous operation duration below mission requirements for extended dismounted patrols.
Strategic Opportunities
- Urban warfare doctrine pivot:Asymmetric force protection missions in dense terrain are opening procurement channels for compact through-wall detection and short-range perimeter systems.
- AI-enabled signal processing:Machine learning classification algorithms are converging with software-defined radio architectures to reduce false-alarm rates in cluttered environments.
- EU Defense Fund certification:European Peace Facility financing mechanisms are creating preferential access for qualified vendors in member state rapid procurement frameworks.
Industry Challenges
- RF engineer scarcity:Specialized microwave circuit design expertise pools concentrate in legacy defense contractors, constraining agile supplier scaling.
- Legacy system integration:Battlefield management software from dismounted soldier programs requires custom protocol bridges for man-portable radar data feeds.
- Environmental qualification timelines:MIL-STD-810H testing for temperature, shock, and humidity extends product validation cycles beyond procurement urgency windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Military Man-Portable Radar System Market |
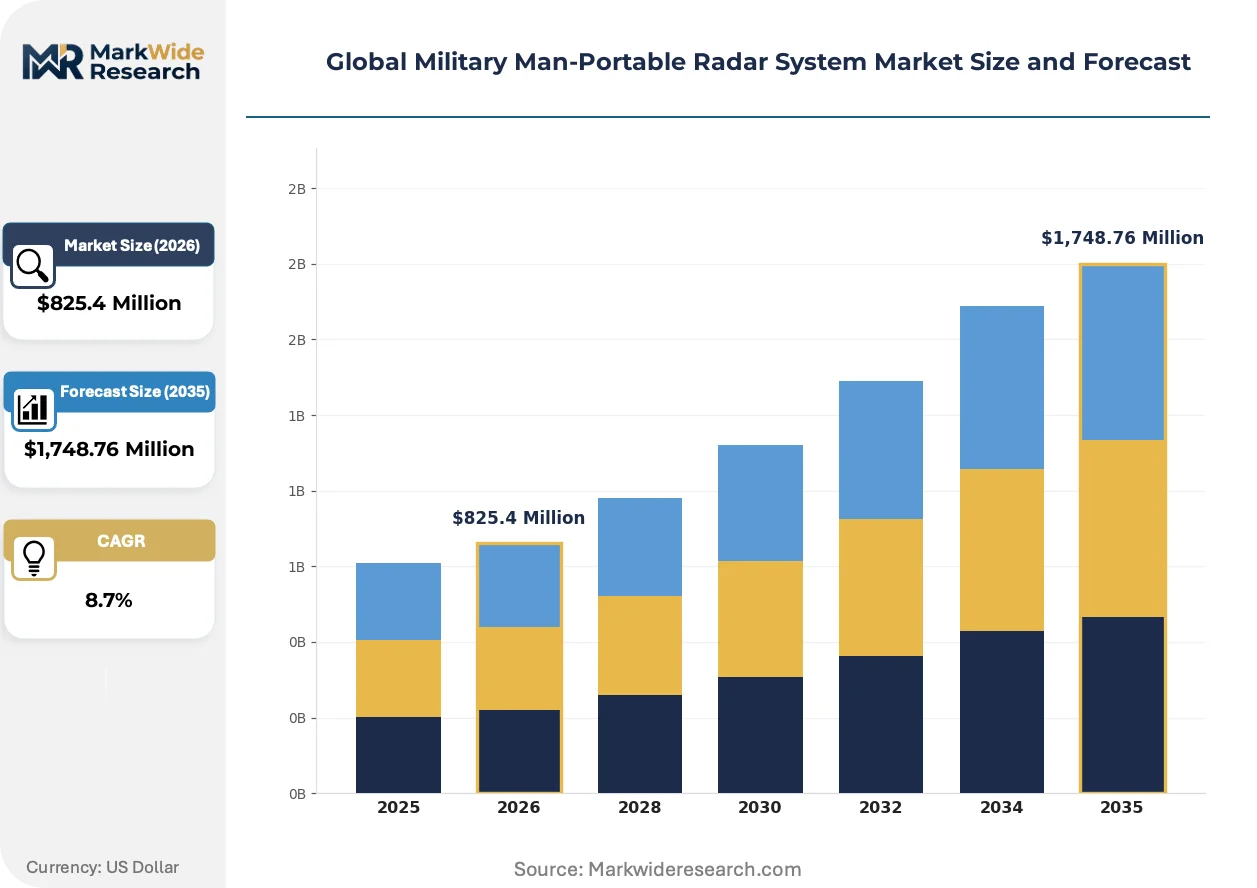
| Market Size in 2026 | $825.4 Million |
| Market Size in 2035 | $1,748.76 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Ground Surveillance, Airborne Surveillance, Counter-Drone, Maritime Patrol, Border Security Technology: Pulse-Doppler, Synthetic Aperture, Phased Array, FMCW, MIMO Application: Combat Reconnaissance, UAV Control, Coastal Monitoring, Force Protection, Search & Rescue End User: Defense Forces, Special Operations, Border Agencies, Intelligence Units, Peacekeeping Groups |
| Companies Covered | Thales Group, Leonardo S.p.A, Saab AB, BAE Systems, Elbit Systems Ltd., ASELSAN A.S, Northrop Grumman, Raytheon Technologies, Blighter Surveillance Systems Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Military Man-Portable Radar System Market Shifts & Advancements
Active electronically scanned array miniaturization is compressing form factors while expanding beam agility, enabling dismounted soldiers to deploy capabilities previously restricted to vehicle-mounted platforms.
Gallium nitride monolithic microwave integrated circuits are digitizing transmit-receive module performance, replacing legacy gallium arsenide substrates with higher power efficiency and thermal tolerance. Special Operations acquisition programs are fielding these components in reduced-signature configurations for contested logistics environments. The technology is digitizing competitive specifications around size-weight-power constraints that previously favored larger platform-mounted alternatives.
FCC spectrum allocations in the United States are constraining X-band and Ku-band transmit power thresholds for domestic training and security applications, forcing manufacturers to architect frequency-agile systems capable of operating across multiple authorized bands without hardware modification. European EASA emerging drone regulations are creating parallel pressure for frequency coordination protocols in civilian-military shared environments. Counter-UAS procurement specifications in both jurisdictions now prioritize software-defined frequency hopping over fixed-band hardware.
Consolidated platform procurement by NATO joint capability development offices is displacing national bilateral contracting for man-portable radar systems. Allied defense ministries are pooling requirements through NATO Support and Procurement Agency frameworks rather than issuing standalone national tenders. This concentration is most visible in Nordic and Baltic states, where interoperability mandates now override national industrial preference clauses in evaluation scoring.
Global Military Man-Portable Radar System Market Segmentation
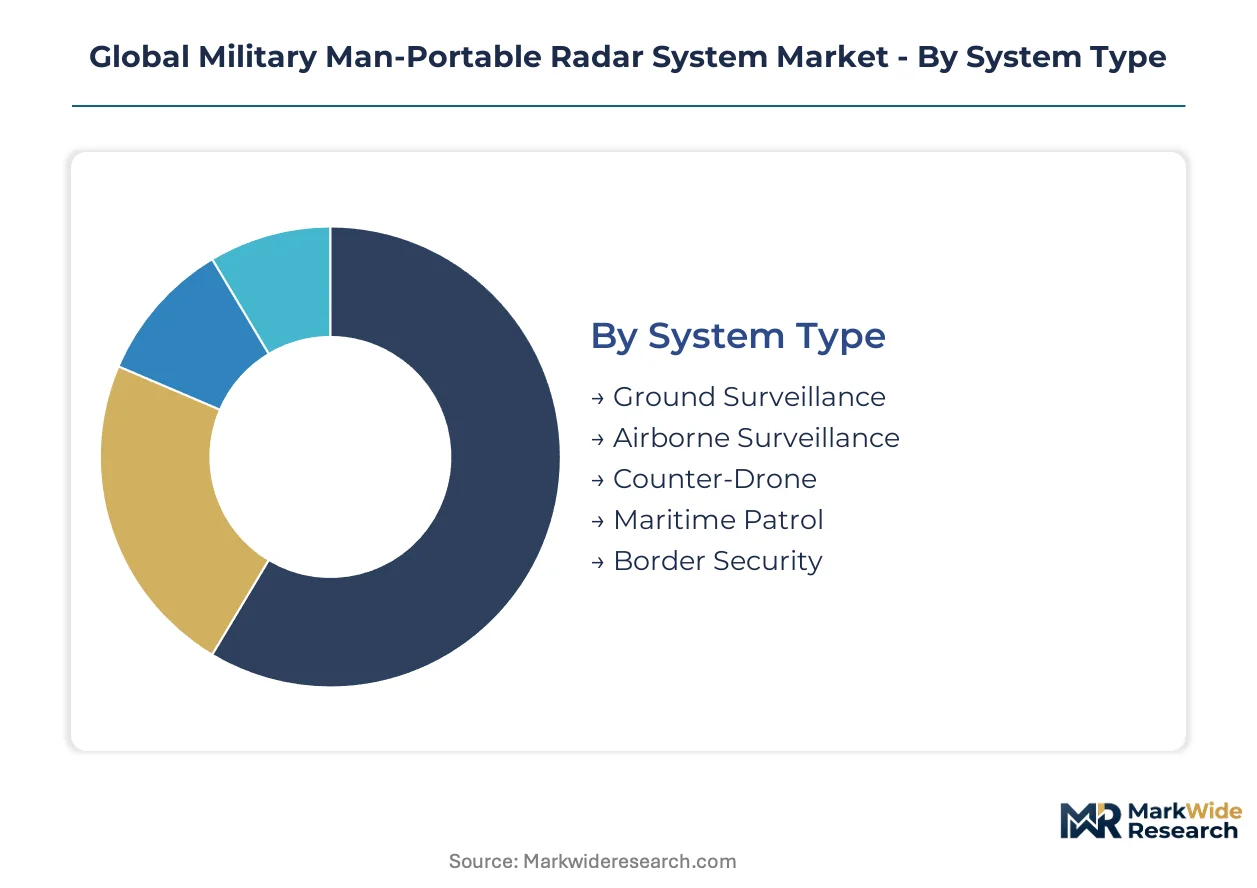
Segmentation of military man-portable radar systems reveals how procurement priorities diverge across mission profiles and technological readiness. Cycle times vary dramatically: counter-drone variants turn over in 18-24 months as swarm threats evolve, while ground surveillance platforms sustain decade-long service lives. Understanding these velocity differentials shapes vendor R&D allocation and inventory positioning.
System Type:
Counter-drone systems compress procurement cycles to match threat evolution velocity, while maritime patrol configurations extend development timelines due to salt-corrosion qualification requirements.
- Counter-Drone:Active electronically scanned arrays operating in Ku-band and millimeter-wave frequencies detect micro-UAV signatures at 5-10 kilometer ranges. NATO Special Operations units in Poland and Romania are accelerating fielding as Russian swarm tactics proliferate in Eastern Europe. Battery thermal management limits continuous operation to 4-6 hours in dismounted configurations.
- Ground Surveillance:Pulse-Doppler architectures dominate this mature segment, with synthetic aperture processing for moving target indication. Australian and Philippine defense forces are expanding coastal perimeter deployments under Indo-Pacific force protection doctrines. Platform weight constraints below 35 kilograms sustain competitive differentiation.
- Airborne Surveillance:Helicopter-portable variants for forward air controller support.
- Maritime Patrol:Corrosion-resistant packaging for littoral interdiction missions.
- Border Security:Fixed-site adaptations with solar power integration for remote outposts.
Ground Surveillance anchors the volume base while Counter-Drone gains share at the steepest rate.
Technology:
Cost tiers separate legacy procurement from premium positioning, with GaN-based phased array modules commanding 3-4x unit economics against established pulse-Doppler alternatives.
- Phased Array:Gallium nitride transmit-receive modules enable beam agility without mechanical steering, reducing detection latency against maneuvering drones. US DoD Joint Counter-Small Unmanned Aircraft Systems Office mandates are standardizing AESA architectures across allied procurement. Thermal dissipation requirements constrain packaging density in man-portable form factors.
- Synthetic Aperture:Coherent processing of radar returns generates high-resolution terrain imagery for route reconnaissance. Japanese Ground Self-Defense Force units are fielding compact SAR variants for island defense scenarios in the Ryukyu chain. Processing load demands trade-offs between resolution and real-time refresh rates.
- Pulse-Doppler:Mature magnetron-based systems for basic moving target detection.
- FMCW:Frequency-modulated continuous wave for short-range perimeter applications.
- MIMO:Multiple-input multiple-output arrays for angular resolution enhancement.
Pulse-Doppler sustains the widest installed base while Phased Array expands most quickly in new procurement.
Application:
Customer mission profiles concentrate demand in force protection and combat reconnaissance, with search and rescue representing intermittent supplemental procurement.
- Force Protection:Perimeter surveillance for forward operating bases and convoy halts, integrating with soldier-worn alert systems. French and British forces in Estonia are deploying man-portable radars for base defense under NATO enhanced forward presence. Urban warfare doctrine shifts in Israel and Ukraine are accelerating through-wall detection requirements.
- Combat Reconnaissance:Dismounted soldier situational awareness in denied environments, with silent operation modes to prevent electromagnetic detection. Australian Special Operations Command prioritizes lightweight variants for jungle warfare in Papua New Guinea and Solomon Islands terrain. Signature management competes with detection range in design trade-offs.
- UAV Control:Beyond-line-of-sight relay for tactical drone operations.
- Coastal Monitoring:Small-craft detection for amphibious threat warning.
- Search & Rescue:Distress beacon detection and personnel location.
Combat Reconnaissance dominates unit volume while Force Protection climbs the fastest in procurement priority.
End User:
Defense ministries concentrate volume procurement through consolidated platforms, while Special Operations and intelligence units drive specification innovation through rapid fielding authorities.
- Special Operations:Reduced-signature configurations with software-defined frequency agility for contested logistics. US Army Special Forces and Navy SEAL procurement through the Special Operations Research, Development and Acquisition Center bypasses standard acquisition timelines. Interoperability with allied SOF units requires NATO STANAG 4671 compliance.
- Defense Forces:Conventional army and marine corps units operating through standard defense procurement channels. South Korean and Taiwanese forces are expanding man-portable radar inventories for coastal defense and counter-infiltration missions. Budget cycles and foreign military financing shape procurement pacing.
- Border Agencies:Customs and immigration enforcement with civilian-military coordination requirements.
- Intelligence Units:Technical surveillance for signals intelligence support.
- Peacekeeping Groups:United Nations and regional organization deployments with restricted rules of engagement.
Defense Forces anchor the volume base while Special Operations gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Department of Defense's Joint Counter-Small Unmanned Aircraft Systems Office anchors procurement volume through interoperability mandates that cascade to allied defense ministries. National procurement patterns diverge sharply between NATO standardization frameworks and Indo-Pacific littoral surveillance requirements.
United States
Special Operations Command and conventional Army units drive demand for reduced-signature counter-drone configurations. FCC spectrum allocations constrain X-band and Ku-band transmit power thresholds for domestic training applications. Arizona and Texas host integration facilities where software-defined frequency-hopping architectures undergo field validation against swarm threat simulations.
United Kingdom
Enhanced forward presence deployments in Estonia and Poland accelerate force protection radar procurement for base perimeter defense. Ministry of Defence interoperability requirements align with NATO STANAG 4671 unmanned systems frameworks. Bristol and southern England sustain radar subsystem engineering clusters serving both domestic and export programs.
France
Special Operations units prioritize compact through-wall detection systems for urban warfare doctrine implementation. National preference clauses in defense tenders sustain domestic manufacturing footprints through EU Defense Fund certification pathways. Paris-Saclay and Toulouse aerospace corridors concentrate phased array miniaturization research.
Australia
Indo-Pacific littoral surveillance requirements drive coastal perimeter deployments across northern territories and island chains. Australian Defence Force procurement channels prioritize lightweight variants for jungle warfare in Papua New Guinea terrain. Adelaide and Melbourne sustain systems integration capabilities aligned with AUKUS technology-sharing frameworks.
Japan
Ground Self-Defense Force island defense scenarios in the Ryukyu chain demand compact synthetic aperture radar for route reconnaissance. METI industrial policy supports gallium nitride substrate development for transmit-receive module production. Nagoya and Tokyo-Yokohama corridors host microwave circuit design expertise pools for AESA miniaturization.
Global Military Man-Portable Radar System Market Competitive Landscape
European defense primes and US aerospace conglomerates split the market through divergent access pathways to national procurement channels. National industrial preference clauses sustain geographic clustering of vendor relationships. Three archetypes dominate: vertically integrated defense conglomerates with captive radar divisions; specialized sensor houses focused on man-portable form factors; and state-affiliated enterprises serving protected domestic markets. Competitive moves concentrate on interoperability certification racing and GaN supply chain locking.
Within the European prime tier, Thales Group and Saab AB exemplify archetype positioning through national preference leverage and Nordic interoperability anchoring respectively. BAE Systems occupies a position bridging transatlantic procurement frameworks. Elbit Systems Ltd. represents the specialist archetype in asymmetric warfare segments where force protection specifications dominate. Leonardo S.p.A. and ASELSAN A.S. sit within state-affiliated structures serving protected domestic and allied export channels.
| Leading Market Players |
|---|
| Thales Group |
| Leonardo S.p.A |
| Saab AB |
| BAE Systems |
| Elbit Systems Ltd. |
| ASELSAN A.S |
| Northrop Grumman |
| Raytheon Technologies |
| Blighter Surveillance Systems Ltd. |
| Others |
Supply & Pricing Matrix
Foundry undercapacity in East Asian gallium nitride substrate production is compressing supplier margins and amplifying pricing power for qualified vendors serving NATO procurement channels. This utilization squeeze propagates through transmit-receive module costs, forcing tiered pricing stratification between GaN-based phased array systems and legacy pulse-Doppler alternatives.
Pricing Analysis
Transatlantic price spreads of 15-25 percent separate US domestic training configurations from export-grade counter-drone variants subject to ITAR compliance overhead. Three-tier pricing structure across premium AESA, standard SAR, and economy pulse-Doppler levels reflects certification grade and volume scale differentiation. Cost compression in the economy tier is intensifying because South Korean and Taiwanese foundries are prioritizing automotive GaN demand. Defense ministries exhibit lowest price sensitivity, while border agencies and peacekeeping groups face hard procurement ceilings.
Supply Chain Analysis
High-purity GaN substrate fabrication draws from concentrated foundry capacity in Japan, South Korea, and Taiwan, with epitaxial wafer processing anchored in Nagoya and Seoul corridors. Monolithic microwave integrated circuits, precision machined aluminum enclosures, and lithium-ion battery packs constitute critical component dependencies. Single-source vulnerability in 6-inch GaN-on-SiC wafer supply creates exposure to export licensing delays. Distribution runs through prime contractor integration facilities in Arizona, Texas, and Bristol before final delivery to defense procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized microwave circuit design expertise pools are thinning across Western defense industrial bases, constraining vendor scaling and amplifying acquisition premiums for qualified engineering teams. This capability gap is reshaping competitive entry economics and consolidation trajectories.
For Market Incumbents: Entrench GaN supply chain locking through long-term offtake agreements with Japanese and South Korean foundries, insulating against emerging Chinese substrate entrants. Accelerate NATO STANAG 4671 certification racing to disqualify non-compliant rivals from allied procurement pools. Prioritize in-house production of transmit-receive modules to defend margin position against specialty sensor houses. For New Entrants and Emerging Players: Pursue urban warfare through-wall detection segments where Israeli and Ukrainian doctrine shifts are opening rapid procurement channels outside legacy defense prime relationships. Target Australian and Philippine coastal defense architectures for force protection radar deployments, leveraging AUKUS technology-sharing frameworks as market entry protocol. Lead with software-defined frequency agility as differentiation against hardware-locked incumbents. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across GaN-based phased array sub-segments as foundry equipment costs escalate and qualification timelines extend. Five-to-ten year viability favors acquisition of specialized sensor houses with captive microwave circuit design expertise and existing NATO interoperability certifications. Monitor US DoD Joint Counter-Small UAS Office mandate velocity as signal for procurement cycle timing inflection.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Supply Chain Locking | Long-term offtake agreements with METI-supported Japanese foundries secure substrate access against export control friction. |
| NATO Interoperability Certification | STANAG 4671 compliance opens cross-border sales eligibility across allied defense ministry procurement channels. |
| Software-Defined Architecture Migration | Frequency-agile systems bypass FCC and EASA spectrum constraints that handicap fixed-band hardware competitors. |
| Urban Warfare Segment Entry | Through-wall detection capabilities address French and Israeli force protection procurement priorities in dense terrain. |
| Indo-Pacific Littoral Positioning | Coastal perimeter deployments align with Australian and Philippine maritime surveillance doctrine shifts. |
Research Methodology
A spread of perspectives from radar systems program managers, GaN foundry operations directors, NATO procurement officers, and Special Operations acquisition leads converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through US DoD budget justification documents, EU Defense Fund award disclosures, and Japanese METI industrial policy filings. Bottom-up unit economics triangulated against top-down defense expenditure forecasts across the analysis window.
Demand-supply balance modeling segmented the market by system type, technology architecture, and end-user mission profile. Analytical framework approach tracked procurement cycle velocity differentials between counter-drone variants and ground surveillance platforms throughout the forecast period. CAGRs were derived from defense ministry budget trajectory analysis and threat evolution scenario planning, with GaN substrate supply constraints and battery energy density ceilings as specific forecast inputs.
Sensitivities concentrate around export licensing delays, foundry capacity allocation shifts, and counter-UAS doctrine integration timing across allied defense ministries. Cross-checking against NATO Support and Procurement Agency contract award databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Surveillance
Tactical Scope Market
Military Surveillance
Surveillance Radar System Market
Military Surveillance
EO/IR Gimbal Market
Military Surveillance
UXO Detection Market
Military Surveillance
Hydrographic Survey Equipment Market
Military Surveillance
Global Airport Surveillance Radar Market
Military Surveillance
Military Imaging System Market
Military Surveillance
Europe Hydrographic Survey Equipment Market
Military Surveillance
Drone Surveillance Platform Market
Military Surveillance
Asia-Pacific Hydrographic Survey Equipment Market
Military Surveillance
Maritime Surveillance Market
Military Surveillance
Early Warning Radar Market
Military Surveillance
Laser Telemetry Binoculars Market
Military Surveillance
Military Manportable Surveillance Radar Market
Military Surveillance
Land Based Military Electro Optical & IR Systems Market
Military Surveillance
Anti-Sniper Detection System Market