
 Infrared Anti-Sniper Detection System Market | 2026-2036
Infrared Anti-Sniper Detection System Market Size, Share, and Industry Trends Forecast 2026-2036
Infrared Anti-Sniper Detection System Market Foresight
The capital-intensity divergence between full-system integrators and component suppliers is rotating competitive advantage toward vertically integrated defense primes. Rheinmetall AG leverages its electro-optics foundry in Germany to sustain captive supply of infrared detectors. BAE Systems anchors its position through classified integration contracts with UK and US military end users. Teledyne FLIR competes on sensor volume, dominating the uncooled microbolometer segment that feeds multiple platform integrators.
Infrared anti-sniper detection systems employ thermal imaging sensors operating in the 8-14 μm long-wave infrared spectrum to detect muzzle flash and projectile trajectory through passive signature analysis, serving military and security forces requiring immediate threat localization in complex environments. Fixed systems command the largest installed base due to permanent perimeter defense contracts, while portable units represent the fastest-expanding category as dismounted soldier programs prioritize reduced size, weight, and power constraints. Integrated solutions concentrate margin pools where sensor fusion combines optical, acoustic, and radar modalities into unified threat displays.
The US Department of Defense and Israel's Ministry of Defense shape procurement standards through MIL-STD-810 environmental testing and specific operational requirements for desert and urban combat theaters. NATO STANAG agreements harmonize interoperability benchmarks across member nation acquisitions, creating regulatory pull toward common data formats and interface specifications. Stakeholders must monitor how export control frameworks under the US ITAR regime and EU dual-use regulations constrain technology transfer paths for infrared focal plane arrays.
Market Dynamics
Uncooled microbolometer focal plane arrays are collapsing unit costs while extending detection ranges, redistributing margin pools from cryogenically cooled sensor suppliers toward system integrators with captive electro-optics fabrication.
Growth Catalysts
- NATO STANAG interoperability mandates:Common data format requirements across member states are standardizing procurement specifications, enabling single-source qualification for multi-national defense contracts.
- Urban warfare doctrine evolution:Military end-users in Israel and the United States are mandating dismounted soldier protection suites that incorporate portable infrared threat detection for asymmetric combat environments.
- Uncooled detector manufacturing scale-up:Wafer-level packaging advances are reducing microbolometer production costs, expanding addressable budgets for fixed-site perimeter defense installations.
Market Restraints
- Indium antimonide supply concentration:Cryogenic detector materials depend on limited foundry capacity in Germany and the United States, creating single-source vulnerability for cooled-system manufacturers.
- US ITAR export licensing friction:State Department jurisdiction over infrared focal plane arrays constrains technology transfer to allied nations, elongating sales cycles for foreign military customers.
- Acoustic sensor substitution threat:Lower-cost projectile trajectory detection systems using microphone arrays compete for perimeter defense budgets where immediate threat localization requirements are less stringent.
Strategic Opportunities
- India defense modernization procurement:The Ministry of Defence's indigenization push under the Make in India framework creates offset partnership requirements for foreign system integrators.
- Sensor fusion convergence:Integration of infrared, acoustic, and radar modalities into unified threat displays commands premium pricing from military end-users requiring reduced cognitive load.
- Commercial security vertical expansion:Critical infrastructure operators in Saudi Arabia and the UAE are adopting military-derived detection systems for oil facility perimeter protection.
Industry Challenges
- MIL-STD-810G environmental qualification timelines:Extended vibration, thermal shock, and sand/dust testing protocols compress product development schedules for new platform integrations.
- Electro-optics engineering talent scarcity:Specialized expertise in long-wave infrared optical design concentrates among legacy defense contractors, constraining workforce mobility for emerging competitors.
- Legacy vehicle architecture integration complexity:Retrofitting detection systems into existing armored vehicle electronic buses requires custom interface development for each platform variant.
Report Scope
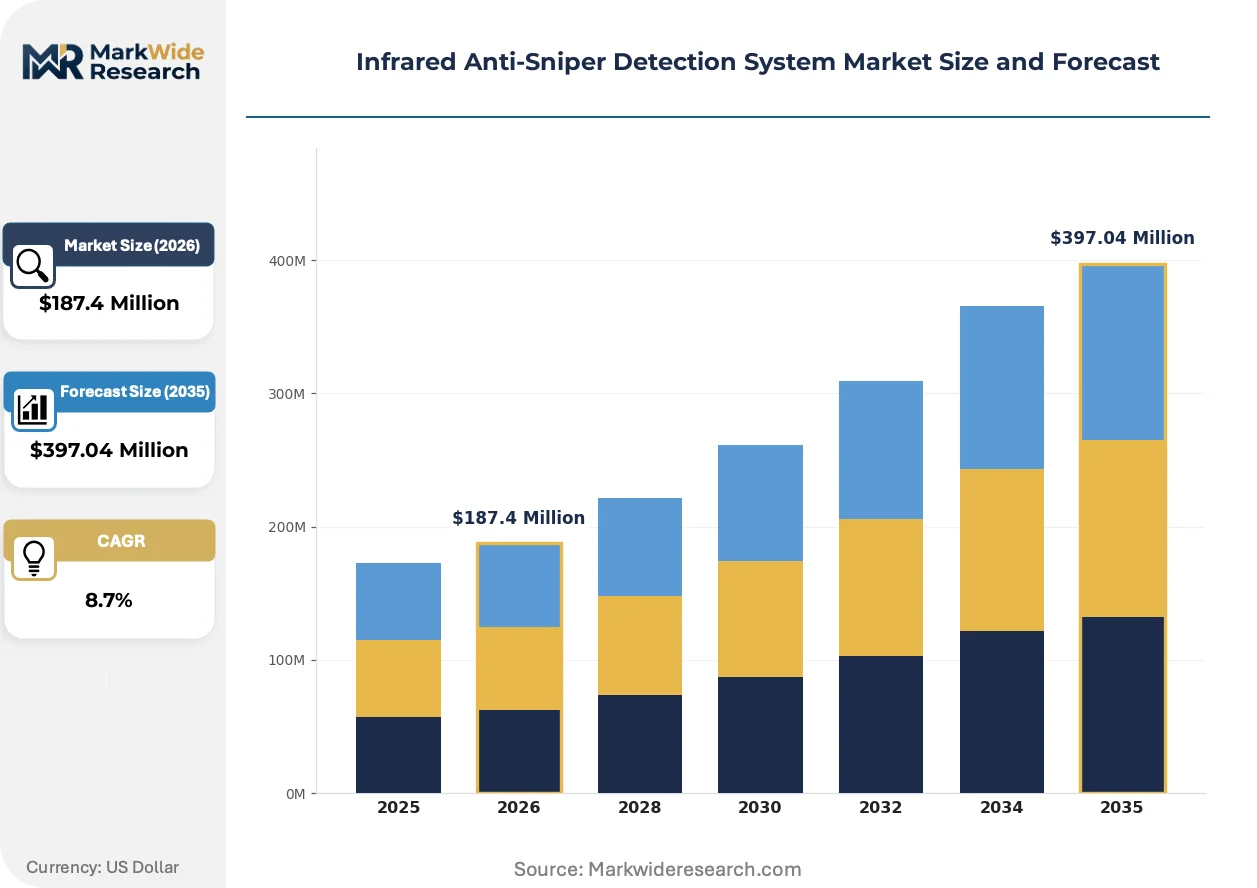
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infrared Anti-Sniper Detection System Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Systems, Portable Units, Integrated Solutions, Networked Systems Technology: Optical Sensors, Radar Systems, Acoustic Sensors, Laser Systems End User: Military, Law Enforcement, Private Security, Government Agencies Installation Type: Onshore, Offshore, Urban Environments, Remote Locations |
| Companies Covered | Rheinmetall AG, BAE Systems, Teledyne FLIR, Leonardo, L3Harris Technologies, Raytheon Technologies, Thales Group, Textron Systems, Rafael Advanced Defense Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infrared Anti-Sniper Detection System Market Shifts & Advancements
Passive signature analysis algorithms are advancing detection probability while reducing false alarm rates, compressing the performance gap between military-grade and commercial-security deployments.
Vanadium oxide microbolometers are displacing amorphous silicon detectors in portable system designs due to superior thermal sensitivity and reduced power consumption. Infantry modernization programs in the United States and Israel are specifying uncooled sensors for dismounted soldier kits. This technology shift is displacing legacy cryogenic cooler maintenance requirements and enabling 24-hour continuous operation without logistical support.
EU dual-use export control harmonization under Regulation 2021/821 is tightening licensing thresholds for infrared imaging components above specific resolution and frame-rate thresholds. Component suppliers must now obtain individual licenses for shipments to non-EU NATO partners, adding administrative burden. German and French electro-optics manufacturers are responding by segmenting product lines into ITAR-free and ITAR-controlled variants.
Defense agencies are consolidating vendor qualification lists, reducing the number of approved infrared system suppliers through multi-year framework agreements. Small and mid-tier integrators face exclusion from prime contractor supply chains without proven track records in classified programs. This concentration is most visible in United Kingdom Ministry of Defence procurement, where BAE Systems and Thales dominate soldier protection system awards through established security clearance hierarchies.
Infrared Anti-Sniper Detection System Market Segmentation
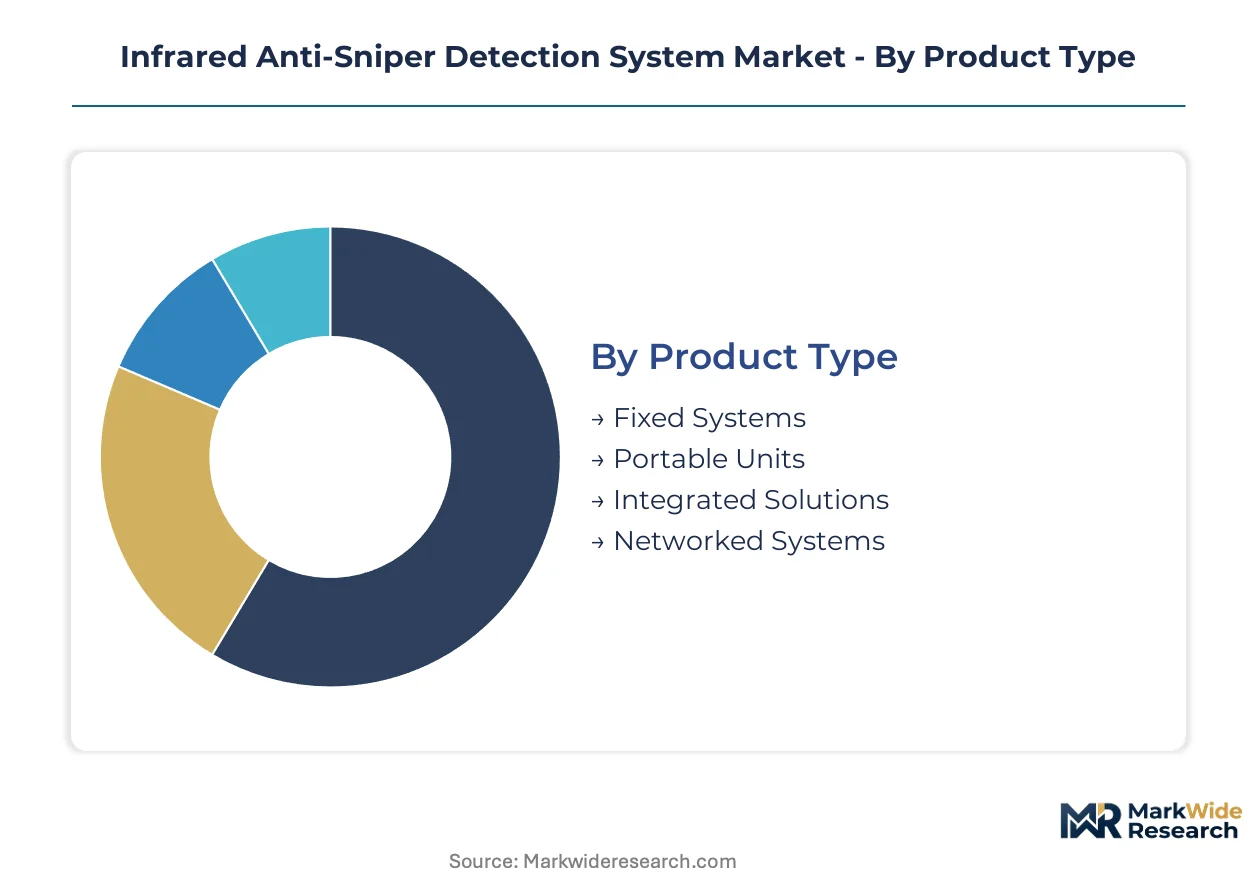
Segmentation in the infrared anti-sniper detection market reveals distinct procurement patterns across defense modernization programs and security infrastructure investments. Understanding these divisions exposes where technology premiums concentrate and which configurations face cost compression from competing detection modalities.
Product Type:
Fixed systems anchor domestic procurement in permanent perimeter defense contracts across Israel, Germany, and the United States, while portable units drive export-led demand from NATO partner nations modernizing dismounted soldier capabilities.
- Fixed Systems:Permanent installations employing mast-mounted thermal imagers and distributed sensor networks protect military bases and critical infrastructure. Demand concentrates in Saudi Arabia and the UAE where oil facility operators adopt military-derived perimeter protection following asymmetric threat incidents.
- Portable Units:Battery-operated systems weighing under five kilograms enable dismounted soldier threat detection without vehicle support. Israeli and US infantry modernization programs mandate these configurations for urban combat theaters, compressing development timelines around size, weight, and power constraints.
- Integrated Solutions:Multi-modal platforms combining infrared, acoustic, and radar sensors into unified command displays.
- Networked Systems:Distributed architectures enabling cross-platform threat data sharing across tactical formations.
Fixed systems command the established base. The steepest expansion runs through portable units.
Technology:
Cost tiers separate mature infrared focal plane arrays from emerging sensor modalities, with uncooled microbolometers collapsing unit economics while acoustic arrays compete on budget-constrained perimeter contracts.
- Optical Sensors:Long-wave infrared imagers operating in the 8-14 μm spectrum detect muzzle flash through passive thermal signature analysis. Military end-users in the United States prioritize these for immediate threat localization in complex urban environments where electromagnetic signature control matters.
- Acoustic Sensors:Microphone arrays triangulate projectile trajectory through shockwave detection at substantially lower unit cost. Law enforcement agencies in Germany specify these for fixed-site protection where rapid deployment outweighs all-weather detection requirements.
- Radar Systems:Active millimeter-wave detection tracking bullet trajectory through Doppler signature processing.
- Laser Systems:LIDAR-based detection measuring atmospheric disturbance from projectile passage.
Optical sensors dominate military-grade procurement. Acoustic configurations are gaining share fastest in commercial security verticals.
End User:
Customer type determines certification requirements and sales cycle duration, with classified military programs demanding multi-year qualification timelines while private security contracts prioritize rapid field deployment.
- Military:Armed forces procurement adhering to MIL-STD-810 environmental testing and NATO STANAG interoperability mandates. The US Department of Defense and Israel's Ministry of Defense shape technical specifications that cascade through allied nation acquisitions.
- Law Enforcement:Police tactical units and border security agencies requiring portable threat detection for hostage rescue and high-risk warrant service. German federal police units specify reduced-weight configurations for extended officer carriage.
- Private Security:Critical infrastructure operators and corporate protection details adopting military-derivative systems.
- Government Agencies:Diplomatic security services and correctional facilities with specialized perimeter monitoring requirements.
Military end-users anchor technology development investment. Private security represents the fastest-climbing customer category as commercial adoption accelerates.
Installation Type:
Environmental exposure severity dictates sensor packaging requirements and maintenance protocols, with desert and maritime installations demanding hardened enclosures that urban deployments can relax.
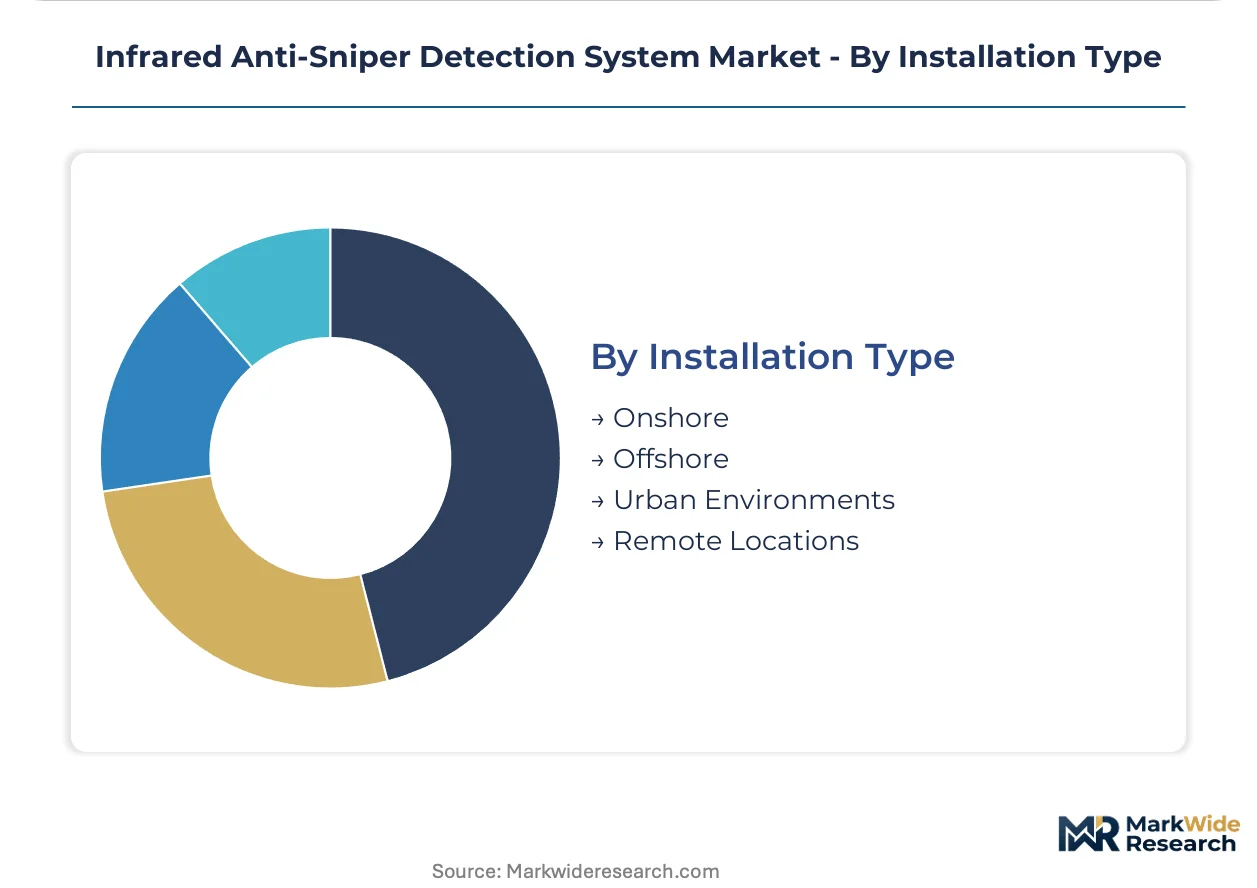
- Urban Environments:Dense electromagnetic and thermal clutter from buildings, vehicles, and civilian populations demands advanced false-alarm rejection algorithms. Israeli defense procurement prioritizes these configurations for Gaza border settlements and West Bank security corridors.
- Remote Locations:Extended logistics tails and limited technical support infrastructure require 24-hour autonomous operation without cryogenic cooler maintenance. US forward operating base contracts specify uncooled microbolometers exclusively for these deployments.
- Onshore:Continental installations with established power and communications infrastructure.
- Offshore:Maritime platforms and coastal facilities exposed to salt corrosion and vibration extremes.
Urban installations command the dominant share of current procurement. Remote location specifications are expanding most quickly as expeditionary warfare doctrine evolves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Israeli and German defense procurement where electro-optics engineering scarcity sustains premium contract terms. Budget-constrained NATO partners in Eastern Europe face elongated qualification timelines and compressed margins.
United States
The US Department of Defense drives demand through dismounted soldier modernization and forward operating base perimeter contracts. MIL-STD-810G environmental testing mandates shape technical specifications that cascade to allied acquisitions. Boston and Dallas defense clusters host system integrators supplying uncooled microbolometer platforms for urban combat theaters.
Germany
Rheinmetall's electro-optics foundry in Unterlüß anchors European supply of infrared focal plane arrays for NATO STANAG-compliant systems. The country's Federal Office for Economic Affairs and Export Control enforces EU dual-use regulations that constrain technology transfer paths. Bavaria's defense manufacturing corridor concentrates precision optics fabrication for vehicle-integrated detection suites.
Israel
The Ministry of Defense mandates portable threat detection for Gaza border settlements and West Bank security corridors, compressing development timelines around size and power constraints. Israeli procurement standards emphasize 24-hour autonomous operation without cryogenic support. Haifa's defense technology cluster hosts specialists in passive signature analysis algorithms for dense urban environments.
India
The Ministry of Defence's Make in India framework creates offset partnership requirements for foreign system integrators seeking infantry protection contracts. Indigenization mandates prioritize local assembly of sensor components under technology transfer agreements. Bangalore and Hyderabad emerging as production hubs for military electro-optics under defense public sector unit joint ventures.
Saudi Arabia
Critical infrastructure operators adopt military-derived detection systems for oil facility perimeter protection following asymmetric threat incidents. The General Authority for Military Industries enforces local content requirements for security system procurement. Eastern Province industrial zones concentrate deployment of mast-mounted thermal imagers for petrochemical complex defense.
Infrared Anti-Sniper Detection System Market Competitive Landscape
Concentration sits with vertically integrated defense primes possessing captive electro-optics fabrication and classified program clearances. The vendor base stratifies between full-system integrators capturing margin pools through sensor fusion and component suppliers feeding multiple platform architectures. Two strategic archetypes dominate: German and US-based primes with in-house foundry capacity, and sensor specialists competing on uncooled microbolometer volume. Competitive dynamics revolve around multi-year framework agreements consolidating approved supplier lists and backward integration into infrared detector manufacturing.
Within the integrated-system tier, Rheinmetall AG and BAE Systems exemplify primes leveraging classified integration contracts and captive supply chains. Teledyne FLIR occupies a position as the volume anchor in uncooled microbolometer production, feeding multiple platform integrators without competing directly on full-system awards. These three entities represent the structural fault lines where margin pools concentrate: foundry-controlled supply, security-cleared integration, and sensor-scale manufacturing.
| Leading Market Players |
|---|
| Rheinmetall AG |
| BAE Systems |
| Teledyne FLIR |
| Leonardo |
| L3Harris Technologies |
| Raytheon Technologies |
| Thales Group |
| Textron Systems |
| Rafael Advanced Defense Systems |
| Others |
Supply & Pricing Matrix
Wafer-level packaging scale economies in uncooled microbolometer production are compressing unit costs while concentrating margin capture among foundry-integrated system houses, establishing price floors that exclude pure-play integrators without captive detector supply.
Pricing Analysis
Configured-to-order pricing for vehicle-integrated detection suites commands substantial premiums over standard portable unit configurations. Three-tier pricing structure across premium, standard, and economy levels separates MIL-STD-810G-qualified military systems from law enforcement-grade units and commercial security derivatives. Price differentiation hinges on certification level and customization depth, with NATO STANAG-compliant systems sustaining margins while acoustic sensor substitution intensifies cost compression in perimeter defense budgets. Military end-users exhibit lowest price sensitivity; private security operators in Saudi Arabia and the UAE demonstrate highest elasticity.
Supply Chain Analysis
Germany and the United States anchor cryogenic detector fabrication, while Taiwan and South Korea feed wafer-level packaging for uncooled microbolometer arrays. Indium antimonide and vanadium oxide draw from limited foundry capacity, creating single-source vulnerability for cooled-system manufacturers. Tariff exposure through US ITAR licensing friction constrains technology transfer paths. Distribution runs through prime contractor framework agreements consolidating approved supplier lists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflection centers on NATO STANAG interoperability mandates creating winner-take-most dynamics where sensor-fusion architectures capture ecosystem rents from modular component suppliers.
For Market Incumbents: Compound defensive positioning through backward integration into infrared detector manufacturing and exclusive framework agreements with classified program offices. Rheinmetall's electro-optics foundry model demonstrates how captive supply chains neutralize acoustic sensor substitution threats. Prioritize MIL-STD-810G qualification maintenance as barrier to mid-tier challengers.
For New Entrants and Emerging Players: Differentiate on ITAR-free product architectures targeting Indian Make in India offset partnerships and EU dual-use regulatory arbitrage. Private security verticals in Saudi Arabia and the UAE present most penetrable demand pools. Pursue sensor-fusion white-label supply to established primes lacking acoustic or radar integration expertise.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors uncooled microbolometer specialists with wafer-scale manufacturing assets over cryogenic cooler-dependent legacy architectures. Long-term viability rests on electro-optics engineering talent concentration and classified security clearance hierarchies. Monitor EU dual-use licensing threshold adjustments as inflection signal for component supplier margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Detector Fabrication | Captive supply of vanadium oxide microbolometers secures margin pools from Teledyne FLIR volume dominance. |
| Sensor Fusion Platform Development | Unified threat displays combining infrared, acoustic, and radar modalities command premium pricing from US and Israeli military procurement. |
| ITAR-Free Product Line Segmentation | EU dual-use compliance enables faster sales cycles to NATO partners facing US State Department licensing friction. |
| Make in India Joint Venture Formation | Offset partnerships satisfy Ministry of Defence indigenization mandates for infantry protection system contracts. |
| Commercial Security Vertical Expansion | Petrochemical facility operators in Saudi Arabia adopt military-derived perimeter protection following asymmetric incidents. |
Research Methodology
Desk research of defense procurement databases, EU dual-use export control filings, and NATO STANAG technical specifications preceded structured interviews with electro-optics engineering directors, military program office procurement leads, and critical infrastructure security managers. Primary fieldwork with uncooled microbolometer foundry operators and vehicle integration specialists validated secondary estimates. Bottom-up unit economics and top-down defense budget allocation triangulation anchored market sizing.
Variance decomposition across product type, technology tier, end-user category, and installation environment shaped analytical framework outputs over the projection horizon. CAGRs derived from defense modernization budget trajectories and unit cost curves for infrared focal plane arrays. Modeled inputs included US Department of Defense dismounted soldier program spend profiles and Israeli Ministry of Defense Gaza border settlement protection mandates.
Decision-makers should treat outputs as directional under assumptions of sustained NATO STANAG harmonization and uncooled detector manufacturing scale-up; material deviation in US ITAR licensing posture or indium antimonide supply disruption would warrant model refresh. Recalibration cycles align with material shifts in defense procurement standard-setting and export control threshold adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Surveillance
Maritime Situational Awareness Systems Market
Military Surveillance
Mmwave Radar Market
Military Surveillance
EO/IR Gimbal Market
Military Surveillance
Drone Surveillance Platform Market
Military Surveillance
Military Jammer Market
Military Surveillance
Europe Hydrographic Survey Equipment Market
Military Surveillance
Military Manportable Surveillance Radar Market
Military Surveillance
UXO Detection Market
Military Surveillance
Early Warning Radar Market
Military Surveillance
Global Airborne Warning and Control System Market
Military Surveillance
Manportable Surveillance and Target Acquisition Radar Market
Military Surveillance
Hydrographic Equipment Market
Military Surveillance
Asia-Pacific Hydrographic Survey Equipment Market
Military Surveillance
Long Range Radar Systems Market
Military Surveillance
Land-Based Military Electro-Optical and Infrared Systems Market
Military Surveillance
Global Radar Market