
 Maritime Situational Awareness Systems Market | 2026-2036
Maritime Situational Awareness Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Maritime Situational Awareness Systems Market Analysis
Silicon carbide is decoupling maritime radar arrays from legacy gallium arsenide substrates, cutting thermal load and extending sensor duty cycles in harsh ocean environments. Northrop Grumman Corporation leverages in-house semiconductor foundries to control gallium nitride supply chains for next-generation naval radars. Lockheed Martin Corporation anchors its Aegis Combat System integration portfolio with proprietary sensor fusion architectures. Thales Group specializes in dual-use optical-electronic suites that bridge coast guard and naval mission profiles.
Maritime situational awareness systems integrate multisensor data streams—radar, automatic identification system transponders, sonar, and electro-optical imagers—into unified operational pictures for vessel commanders and shore-based authorities. These systems process returns across X-band and S-band frequencies with refresh rates under two seconds to track surface contacts in cluttered littoral zones. Radar systems and AIS dominate technology procurement budgets, though sonar systems represent the fastest-expanding segment as anti-submarine warfare priorities resurface in the Pacific. Government agencies and naval forces anchor end-user demand, while satellite-based deployment modes capture widening margins as low-earth-orbit constellations proliferate.
The International Maritime Organization's SOLAS Chapter V mandates govern carriage requirements for automatic identification systems and voyage data recorders, directly shaping equipment certification pathways. The U.S. Coast Guard's Navigation Center enforces AIS performance standards that filter market access for non-compliant hardware vendors. The EU Maritime Safety Agency coordinates cross-border vessel traffic monitoring under Directive 2002/59/EC, creating harmonized procurement specifications for member state coast guards. Stakeholders must monitor convergence between civilian port security frameworks and classified naval sensor specifications, as dual-use ambiguity reshapes export control classifications and partnership eligibility.
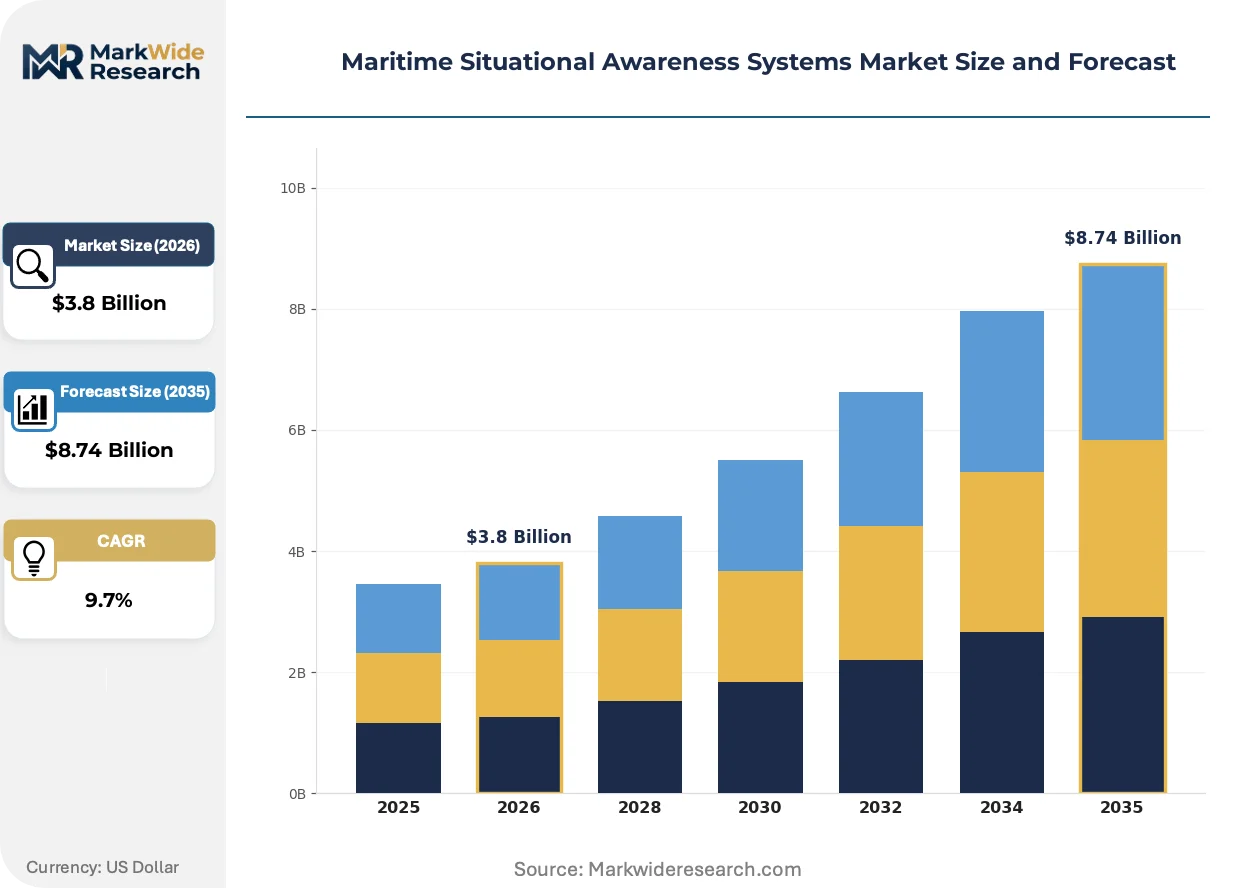
Market Dynamics
Sensor fusion architectures are compressing procurement cycles as naval forces demand unified threat detection platforms rather than discrete radar, sonar, and electro-optical subsystems from separate vendors.
Growth Catalysts
- SOLAS Chapter V Mandates:The International Maritime Organization's updated navigation safety requirements compel commercial fleet operators to upgrade automatic identification systems and voyage data recorders, expanding addressable hardware demand across international shipping lanes.
- Gallium Nitride Substrate Adoption:Naval radar manufacturers are transitioning from legacy gallium arsenide to gallium nitride semiconductors, cutting thermal loads and extending sensor duty cycles in harsh maritime environments.
- South Korean Shipbuilding Clusters:Smart-ship integration contracts are multiplying around Ulsan and Geoje shipyards as domestic yards compete for dual-use naval-commercial platform orders.
Market Restraints
- Rare Earth Magnet Supply Concentration:Permanent magnet dependencies for precision radar positioning systems create vulnerability to export quota disruptions from dominant Asian processors.
- Dual-Use Export Control Friction:Ambiguity between civilian port security frameworks and classified naval sensor specifications complicates cross-border equipment transfers under multilateral regime guidelines.
- Legacy System Integration Costs:Existing vessel combat management systems built on proprietary data buses require expensive middleware development to accommodate open-architecture sensor fusion standards.
Strategic Opportunities
- Low-Earth-Orbit Constellation Proliferation:Satellite-based maritime awareness deployment modes capture widening margins as commercial space operators expand coverage gaps beyond coastal radar horizons.
- Anti-Submarine Warfare Resurgence:Pacific theater priorities are accelerating sonar system procurement faster than surface radar segments, creating specialized vendor opportunities in towed array and hull-mounted acoustic technologies.
- EU Maritime Safety Agency Harmonization:Directive 2002/59/EC coordination of cross-border vessel traffic monitoring creates standardized procurement specifications that reduce vendor certification burden across member state coast guards.
Industry Challenges
- Multisensor Calibration Expertise Scarcity:Unified operational picture development requires rare cross-functional engineers capable of integrating radar, AIS, sonar, and electro-optical data streams with sub-two-second refresh rates.
- Classification Society Certification Timelines:Type approval processes for safety-critical navigation equipment under Bureau Veritas, Lloyd's Register, and DNV standards extend product launch windows by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Maritime Situational Awareness Systems Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Radar Systems, AIS, Sonar Systems, Optical Sensors Application: Search and Rescue, Navigation, Surveillance, Traffic Management End User: Government Agencies, Commercial Shipping, Naval Forces, Coast Guards Deployment: Land-Based, Shipborne, Airborne, Satellite-Based |
| Companies Covered | Northrop Grumman Corporation, Lockheed Martin Corporation, L3Harris Technologies, Thales Group, BAE Systems plc, Raytheon Technologies Corporation, General Dynamics Corporation, SAAB AB, Leidos Holdings, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Maritime Situational Awareness Systems Market Emerging Trajectories
Maritime awareness architectures are pivoting from hardware-centric sensor procurement to software-defined fusion layers that decouple detection hardware from display and decision systems.
Silicon carbide power electronics are replacing silicon insulated-gate bipolar transistors in radar transmit-receive modules. Naval procurement offices in Australia and Japan are specifying wide-bandgap semiconductors for next-generation frigate programs. This substrate transition is converging with solid-state active electronically scanned array designs to eliminate mechanical antenna rotation and reduce maintenance intervals.
The U.S. Coast Guard's Navigation Center is tightening automatic identification system performance standards that filter market access for non-compliant hardware vendors. Equipment manufacturers must now demonstrate spoofing resistance and cybersecurity hardening to receive type approval. Commercial shipping operators plying U.S. waters are accelerating replacement cycles to avoid port state control detention risks.
Integrated logistics support contracts are displacing discrete equipment purchases in naval procurement. European and Asia-Pacific fleet operators now demand ten-year availability guarantees bundling spares, training, and software updates. South Korean and Australian naval modernization programs are most visible in this service-model transition, with prime contractors absorbing operational risk for sensor uptime metrics.
Maritime Situational Awareness Systems Market Segmentation
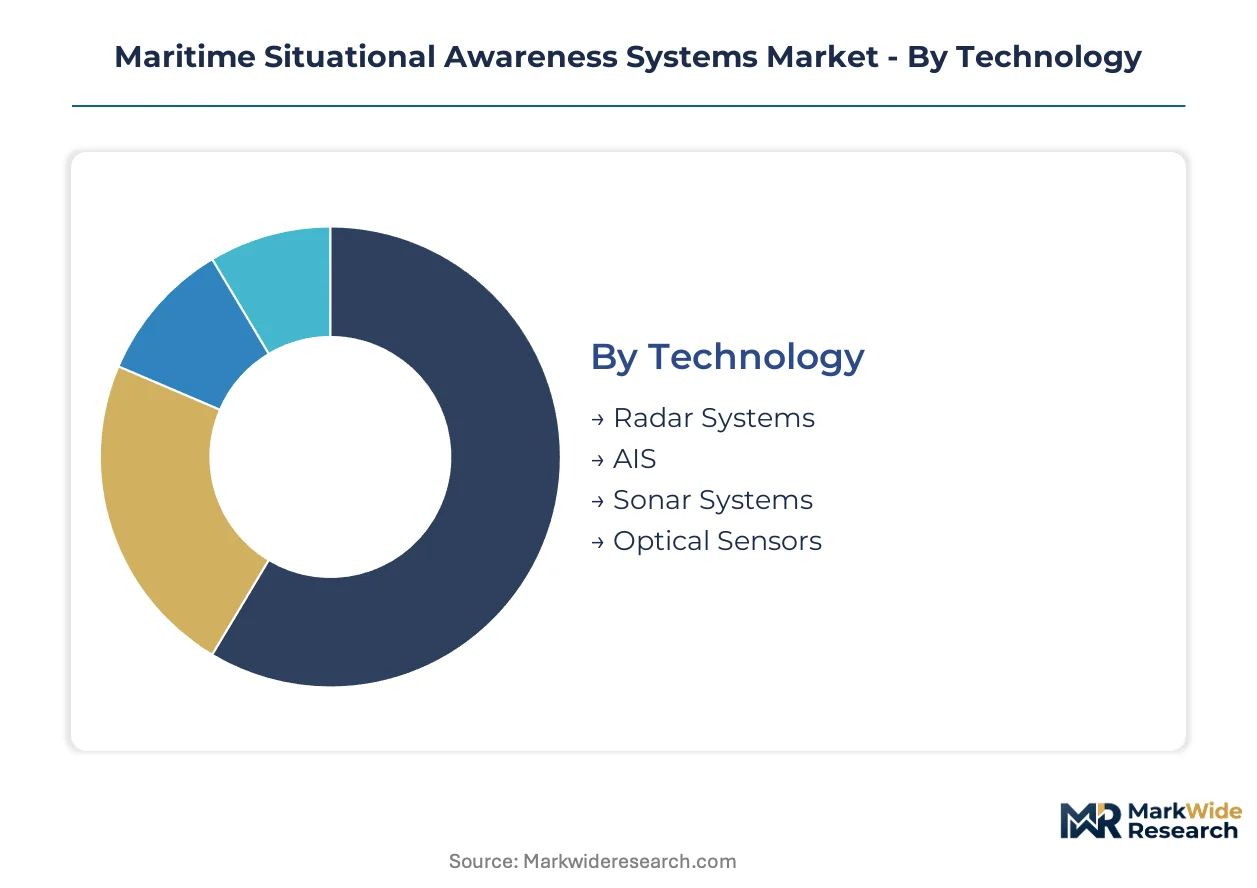
Segmentation in maritime situational awareness systems reveals distinct certification pathways and procurement cycles across technology types and deployment modes. Each category carries unique regulatory burdens that reshape vendor positioning and customer acquisition strategies.
Technology:
Certification requirements diverge sharply across sensor modalities, with radar systems facing FCC and ITU spectrum compliance, AIS hardware bound to SOLAS Chapter V type approval, sonar systems navigating ITAR and dual-use export controls, and optical sensors requiring CE marking for EU port access.
- Radar Systems:Active electronically scanned arrays and magnetron-based systems process X-band and S-band returns for surface contact tracking. South Korean shipbuilding clusters around Ulsan and Geoje drive procurement of solid-state designs with gallium nitride transmit-receive modules for reduced thermal footprint. Classification society timelines from Lloyd's Register and DNV extend certification windows by 18-24 months for safety-critical radar installations.
- Sonar Systems:Hull-mounted and towed array acoustic processors detect submerged contacts through active and passive listening modes. Pacific theater naval modernization programs in Australia and Japan accelerate demand for wide-bandwidth digital signal processing architectures. Anti-submarine warfare priorities resurface procurement faster than surface radar segments, though ITAR restrictions constrain vendor eligibility for cross-border transfers.
- AIS:Automatic identification system transponders broadcast vessel identity, position, and voyage data across VHF maritime channels. U.S. Coast Guard Navigation Center performance standards now mandate spoofing resistance and cybersecurity hardening for type approval.
- Optical Sensors:Electro-optical and infrared imagers provide visual identification in degraded radar environments. Thales Group and similar vendors bridge coast guard and naval mission profiles through dual-use optical-electronic suites.
Leading the category by volume: Radar Systems. Growing fastest: Sonar Systems.
Application:
Application segments map to distinct operational tempos and budget authorities, with search and rescue tied to coast guard operational expenditures, navigation to commercial fleet capital budgets, surveillance to naval procurement offices, and traffic management to port authority infrastructure programs.
- Surveillance:Persistent area monitoring for threat detection and maritime domain awareness integrates multisensor fusion architectures into unified operational pictures. Government agencies and naval forces anchor end-user demand with classified sensor specifications that complicate civilian technology transfer.
- Navigation:Collision avoidance and route optimization systems process radar, AIS, and electronic chart data for vessel command decision support. Commercial shipping operators face port state control detention risks that accelerate replacement cycles for non-compliant hardware.
- Traffic Management:Vessel traffic service coordination in congested waterways and port approaches demands real-time data fusion with refresh rates under two seconds. EU Maritime Safety Agency harmonization under Directive 2002/59/EC reduces vendor certification burden across member state coast guards.
- Search and Rescue:Emergency response coordination requires interoperable communications and position reporting across dispersed assets. Satellite-based deployment modes capture widening margins as low-earth-orbit constellations extend coverage beyond coastal radar horizons.
Dominating procurement budgets: Surveillance. Expanding most quickly: Traffic Management.
End User:
End user categories present divergent contract structures, with government agencies demanding integrated logistics support, commercial shipping favoring equipment-only purchases, naval forces requiring security-cleared engineering support, and coast guards seeking dual-use technology bridges.
- Naval Forces:Fleet modernization programs specify proprietary sensor fusion architectures and classified data bus integration for combat management systems. Asia-Pacific expansion drives demand for unified threat detection platforms rather than discrete subsystems.
- Government Agencies:National maritime authorities coordinate cross-border vessel monitoring and enforce carriage requirements for safety-critical equipment. Ten-year availability guarantees bundling spares, training, and software updates displace discrete equipment purchases.
- Coast Guards:Dual-use mission profiles bridge civilian port security frameworks and naval interoperability requirements. EU Maritime Safety Agency coordination creates standardized procurement specifications across member states.
- Commercial Shipping:Fleet operators upgrade automatic identification systems and voyage data recorders to comply with SOLAS Chapter V mandates. Spoofing resistance and cybersecurity hardening filter market access for hardware vendors.
Commanding the largest addressable spend: Naval Forces. Gaining share fastest: Government Agencies.
Deployment:
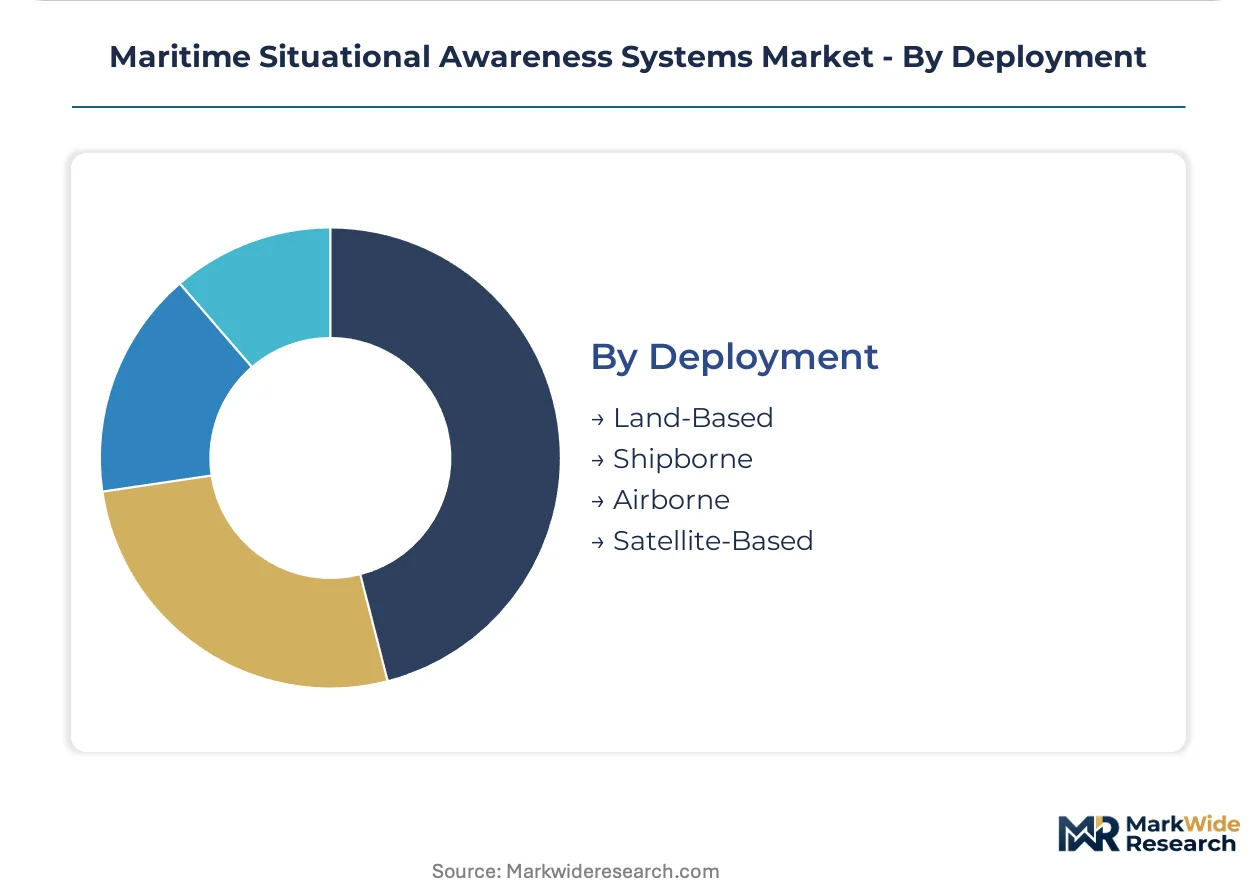
Deployment modes determine infrastructure intensity and operational reach, with land-based installations requiring coastal real estate, shipborne systems integrating with vessel combat management architectures, airborne platforms demanding airframe certification, and satellite-based services proliferating through commercial space operator expansion.
- Satellite-Based:Low-earth-orbit constellations deliver beyond-horizon coverage for vessel tracking in open ocean environments. Commercial space operators proliferate coverage gaps that coastal radar networks cannot address.
- Shipborne:Integrated bridge systems and combat management architectures host multisensor processing with proprietary data bus middleware. Legacy system integration costs constrain open-architecture sensor fusion adoption.
- Land-Based:Coastal radar chains and vessel traffic service centers provide harbor approach and waterway monitoring. South Korean and Australian programs exemplify service-model transitions with prime contractors absorbing operational risk.
- Airborne:Maritime patrol aircraft and unmanned aerial systems extend detection range through elevated sensor platforms. Wide-bandgap semiconductor specifications from Australian and Japanese naval procurement offices converge with solid-state array designs.
Claiming the steepest expansion trajectory: Satellite-Based. Retaining the installed base: Shipborne.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's free economic zones around Ulsan and Geoje drive maritime electronics concentration through shipbuilding tax incentives and naval procurement co-location.
United States
The U.S. Coast Guard's Navigation Center enforces automatic identification system performance standards that mandate spoofing resistance and cybersecurity hardening. FCC spectrum compliance requirements filter market access for radar equipment vendors. Naval modernization programs in Virginia and California sustain demand for integrated combat management architectures.
South Korea
Smart-ship integration contracts multiply around Ulsan and Geoje shipyards as domestic yards compete for dual-use naval-commercial platform orders. Ministry of Trade, Industry and Energy directives accelerate wide-bandgap semiconductor adoption in next-generation frigate programs. Daegu-Gyeongbuk electronics clusters supply precision radar positioning systems for export.
Japan
METI specifications for solid-state active electronically scanned arrays drive gallium nitride substrate procurement for maritime patrol aircraft. Naval procurement offices specify wide-bandgap semiconductors for next-generation destroyer programs. Nagoya-based defense contractors integrate sensor fusion layers for unified threat detection platforms.
Australia
Hunter-class frigate programs anchor demand for towed array sonar systems as anti-submarine warfare priorities resurface in the Pacific. Defence export control regulations complicate cross-border equipment transfers for acoustic technologies. Perth and Adelaide shipyards absorb operational risk through ten-year availability guarantee contracts.
Germany
KBA maritime safety coordination aligns with EU Maritime Safety Agency harmonization under Directive 2002/59/EC. Lloyd's Register certification timelines extend product launch windows for safety-critical navigation equipment. Hamburg and Bremen port authorities drive vessel traffic service modernization with real-time data fusion requirements.
Maritime Situational Awareness Systems Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with defense primes controlling naval procurement and commercial sensor vendors capturing fleet modernization cycles. The vendor base concentrates around semiconductor-integrated system houses and software-defined fusion specialists. Three archetypes dominate: vertically integrated defense contractors with captive foundry capacity, dual-use technology bridges spanning coast guard and naval missions, and satellite-based service operators exploiting low-earth-orbit coverage gaps. Competitive moves center on integrated logistics support contract capture and open-architecture middleware development for legacy system integration.
Within the defense prime tier, Northrop Grumman Corporation and Lockheed Martin Corporation exemplify vertically integrated architectures with in-house semiconductor foundry control. Thales Group occupies a position bridging coast guard and naval mission profiles through dual-use optical-electronic suites. These three anchors represent distinct strategic postures: captive supply chain security, proprietary sensor fusion integration, and civilian-military technology convergence.
| Leading Market Players |
|---|
| Northrop Grumman Corporation |
| Lockheed Martin Corporation |
| L3Harris Technologies |
| Thales Group |
| BAE Systems plc |
| Raytheon Technologies Corporation |
| General Dynamics Corporation |
| SAAB AB |
| Leidos Holdings, Inc. |
| Others |
Supply Flow & Price Mechanics
IMO SOLAS Chapter V cybersecurity hardening mandates gate qualified supply for automatic identification system transponders, reserving premium-tier pricing access for vendors with U.S. Coast Guard Navigation Center type approval and spoofing-resistant architectures.
Pricing Analysis
Short lead-time premiums command pricing power as naval procurement offices accelerate frigate modernization schedules, while spot inventory of legacy gallium arsenide radar modules trades at discounts. Three-tier pricing structure across mission-certified, commercial-grade, and refurbished equipment levels separates naval forces from coast guards and commercial shipping operators. Price differentiation rests on ITAR compliance tier and integrated logistics support bundling. Cost compression in commercial AIS hardware is intensifying because South Korean shipbuilding clusters consolidate vendor panels. Commercial shipping operators exhibit highest price sensitivity; naval forces accept premiums for security-cleared engineering support.
Supply Chain Analysis
Single-source vulnerability sits with Chinese rare earth magnet processors dominating permanent magnet supply for precision radar positioning systems. Gallium nitride substrates draw from U.S. in-house foundries at Northrop Grumman and Lockheed Martin, plus Japanese METI-subsidized wafer production. Silicon carbide power electronics sources from European semiconductor specialists and South Korean Daegu-Gyeongbuk electronics clusters. Tariff exposure constrains cross-border transfers of ITAR-classified sonar components. Distribution runs through prime contractor integrated logistics support contracts displacing discrete equipment purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gallium nitride foundry capacity constraints prop pricing power for naval radar manufacturers, as in-house substrate production remains limited to vertically integrated defense primes.
For Market Incumbents: Hedge against rare earth magnet supply disruption by securing alternative sourcing agreements with Australian and Vietnamese processors outside Chinese quota influence. Expand captive gallium nitride foundry capacity to maintain cost position against emerging wide-bandgap semiconductor specialists. Reinforce sensor fusion software layers as the priority defensive moat against open-architecture middleware competitors. For New Entrants and Emerging Players: Satellite service operators represent the most penetrable channel partner type for maritime awareness data delivery, bypassing capital-intensive hardware certification barriers. Target EU Maritime Safety Agency harmonized procurement specifications under Directive 2002/59/EC for standardized coast guard contracts with reduced vendor qualification burden. Pursue white-space opportunities in towed array sonar signal processing for Pacific theater anti-submarine warfare priorities. For Investors and Strategic Acquirers: South Korean smart-ship integration contract awards to non-traditional primes is the leading indicator that dual-use naval-commercial platform competition is opening to new entrants. Five-to-ten year viability favors acquisition targets with software-defined sensor fusion architectures decoupled from proprietary hardware lock-in. Monitor U.S. Coast Guard Navigation Center cybersecurity hardening rulemakings as the inflection signal for compliance-driven replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Gallium Nitride Foundry Expansion | In-house substrate production at defense primes secures supply chain autonomy for naval radar programs. |
| Integrated Logistics Support Contract Capture | Ten-year availability guarantees bundle spares and software updates, displacing discrete equipment purchases. |
| Satellite-Based Service Layer Development | Low-earth-orbit constellation partnerships extend coverage beyond coastal radar horizons for commercial operators. |
| Open-Architecture Middleware Investment | Software-defined fusion layers decouple detection hardware from proprietary combat management system integration. |
| Dual-Use Optical-Electronic Suite Certification | Thales Group bridging model enables coast guard and naval procurement specification convergence. |
Methodological Framework
Document review covered U.S. Coast Guard Navigation Center type approval records, EU Maritime Safety Agency directive implementation reports, and Lloyd's Register certification timelines, complemented by interviews with naval procurement officers, shipyard integration engineers, and maritime electronics distributors. Secondary validation drew from FCC spectrum compliance filings, ITAR export control classifications, and South Korean Ministry of Trade, Industry and Energy semiconductor adoption directives. Bottom-up equipment procurement tracking and top-down fleet modernization budget analysis provided triangulation.
Cross-referencing historical gallium nitride adoption curves against panel input from radar system program managers shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include sensor modality, deployment architecture, end-user budget authority, and regional regulatory cluster. CAGRs were derived from equipment replacement cycle analysis and satellite constellation coverage expansion trajectories. Anti-submarine warfare priority resurfacing and SOLAS mandate compliance deadlines served as industry-specific forecast inputs.
Caveats apply where rare earth export quota disruptions, ITAR restriction tightening, or low-earth-orbit constellation bankruptcy cascades could materially shift the outlook. Forecasts reflect documented assumptions about naval fleet modernization pacing and commercial shipping regulatory enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Surveillance
Hydrographic Survey Equipment Market
Military Surveillance
Global Airborne Surveillance Market
Military Surveillance
Passive Radar Market
Military Surveillance
Mmwave Radar Market
Military Surveillance
Tactical Optics Market
Military Surveillance
Drone Surveillance Platform Market
Military Surveillance
Global Radar Market
Military Surveillance
Europe Intelligence Surveillance and Reconnaissance Market
Military Surveillance
EO/IR Gimbal Market
Military Surveillance
Missile Seeker Detector Market
Military Surveillance
Electronically Scanned Array Radar Market
Military Surveillance
Target Acquisition Systems Market
Military Surveillance
Manportable Radar Market
Military Surveillance
North America Hydrographic Survey Equipment Market
Military Surveillance
Military Imaging System Market
Military Surveillance
Land-Based Military Electro-Optical and Infrared Systems Market