
 Global Airborne Warning and Control System Market | 2026-2036
Global Airborne Warning and Control System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Airborne Warning and Control System Market Foresight
CSRD disclosure mandates from the European Union are hardening the cost-of-entry calculus for defense electronics suppliers seeking public contracts. Raytheon Technologies leverages its captive semiconductor foundry capacity to insulate phased array production from supply volatility. L3Harris Technologies anchors its position through mission system integration contracts spanning multiple NATO airborne platforms. Northrop Grumman dominates the unmanned aerial vehicle segment with its persistent surveillance architectures.
An Airborne Warning and Control System integrates radar, identification friend-or-foe interrogators, and battle management computers aboard modified airframes to detect, track, and vector interceptors against airborne threats at ranges exceeding 400 kilometers. Fixed-wing aircraft configurations sustain the largest revenue share due to their endurance and payload capacity for large-aperture radars, while unmanned aerial vehicles represent the fastest-expanding platform category as operators seek reduced crew risk and extended orbit times. AESA radar technology commands the steepest procurement premiums because its solid-state transmit-receive modules eliminate mechanical scan latency and enable simultaneous multi-mode operations.
The FAA coordinates airspace deconfliction standards that shape military flight test corridors for new AWACS derivatives, while the EU AI Act imposes algorithmic transparency requirements on autonomous threat-classification subsystems deployed in European airspace. NATO's STANAG interoperability protocols dictate sensor data formatting, effectively creating a technical moat around incumbent integrators. Stakeholders must monitor how export control expansions under the Wassenaar Arrangement reshape component sourcing for non-allied customers.
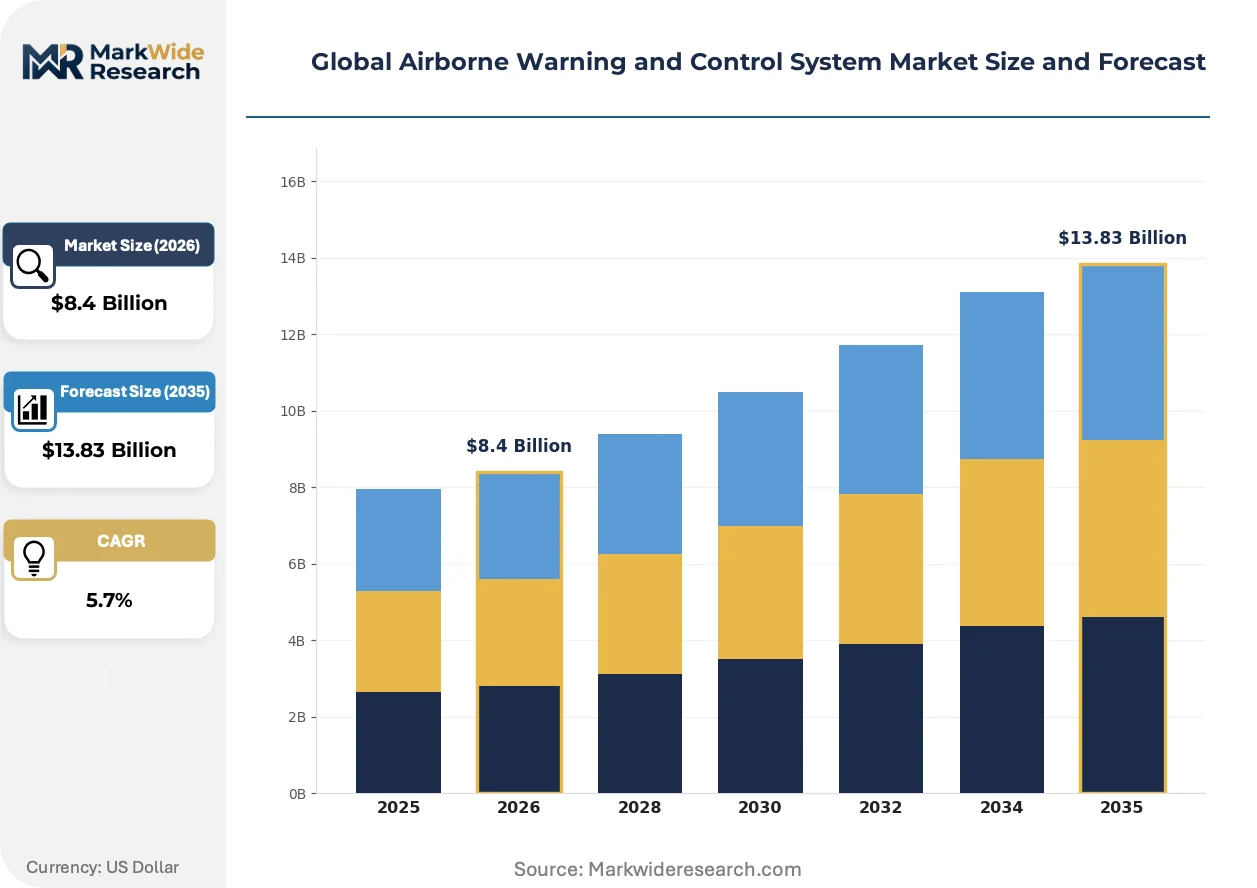
Market Dynamics
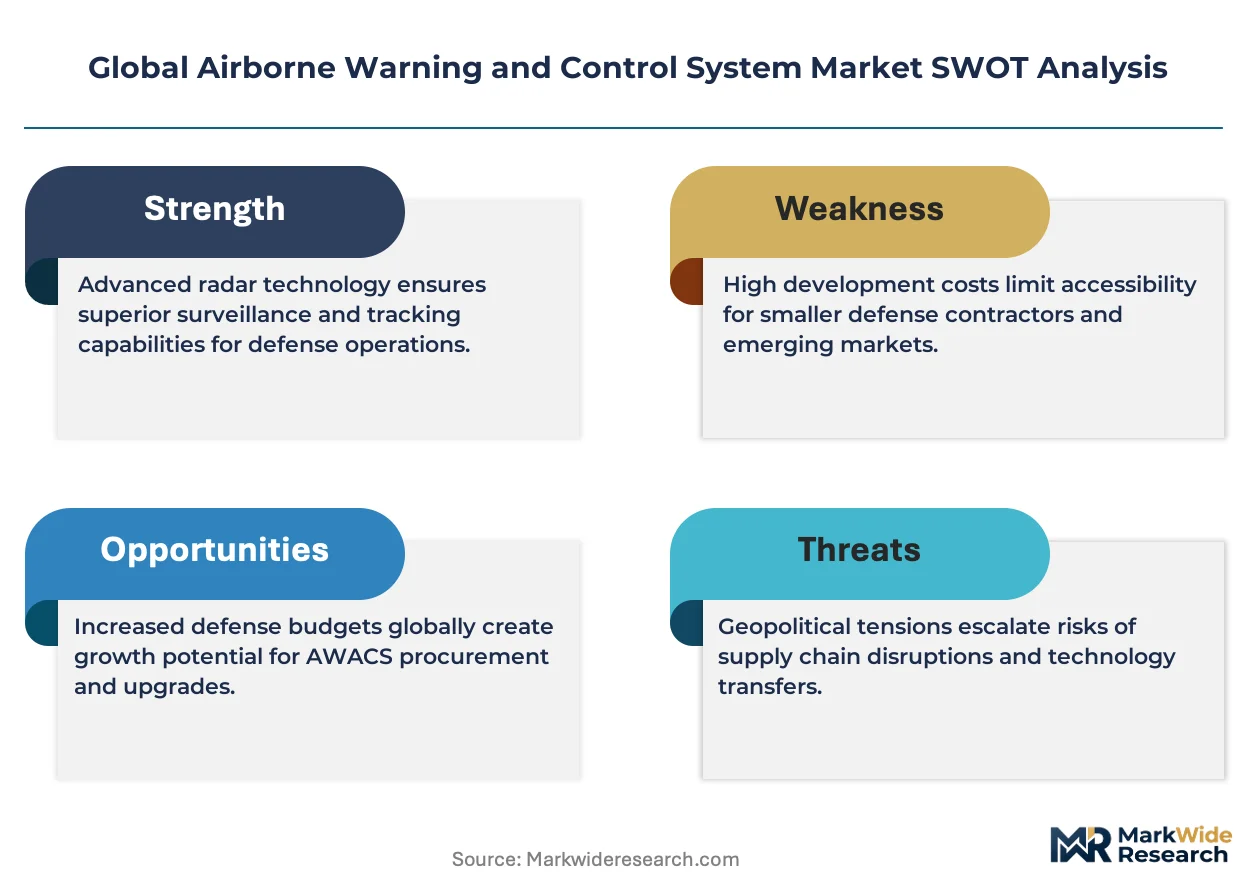
AESA radar migration is compressing development timelines and forcing incumbent suppliers to retool manufacturing lines for solid-state transmit-receive modules, fundamentally altering competitive positioning in airborne early warning platforms.
Growth Catalysts
- NATO STANAG protocols:Interoperability mandates for sensor data formatting lock in multi-platform integration contracts and sustain upgrade cycles across allied air forces.
- Saudi Arabia's fleet recapitalization:Riyadh's prioritization of airborne early warning capabilities amid regional security pressures generates sustained procurement demand for new-build platforms.
- AESA solid-state architecture:Elimination of mechanical scan latency enables simultaneous multi-mode operations, compelling operators to accelerate legacy platform replacement schedules.
Market Restraints
- Gallium nitride substrate scarcity:Concentrated supply of high-purity GaN wafers from specialized foundries creates input cost volatility for phased array manufacturers.
- CSRD disclosure mandates:European Union sustainability reporting requirements harden cost-of-entry calculus for defense electronics suppliers seeking public contracts in member states.
- Crewed platform endurance limits:Human factors constraints on mission duration cap operational availability relative to unmanned alternatives, creating substitution pressure.
Strategic Opportunities
- Unmanned aerial vehicle expansion:Persistent surveillance architectures enable extended orbit times without crew risk, opening new mission profiles for intelligence, surveillance, and reconnaissance operators.
- United Kingdom E-7 Wedgetail procurement:RAF fleet modernization creates anchor demand for integrated mission systems and training infrastructure through 2030.
- EU AI Act algorithmic transparency:Regulatory requirements for autonomous threat-classification subsystems create compliance service opportunities for European integrators.
Industry Challenges
- Phased array thermal management:Solid-state module density generates heat dissipation requirements that strain airframe cooling capacity and drive subsystem redesign cycles.
- Wassenaar Arrangement export controls:Component sourcing restrictions for non-allied customers complicate supply chain configuration and contract fulfillment timelines.
- Legacy E-3 Sentry interoperability:Fielding new platforms alongside aging aircraft with incompatible data links forces expensive gateway system development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Airborne Warning and Control System Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.83 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Fixed-Wing Aircraft, Rotary-Wing Aircraft, Unmanned Aerial Vehicles, Airships Radar Technology: Pulse-Doppler, Synthetic Aperture, Phased Array, Over-the-Horizon, AESA Mission Scope: Early Warning, Surveillance, Command & Control, Electronic Warfare, Maritime Patrol End User: Air Forces, Naval Aviation, Border Security, Homeland Defense |
| Companies Covered | Raytheon Technologies, L3Harris Technologies, Lockheed Martin, General Atomics Aeronautical Systems, Saab AB, Northrop Grumman, Thales Group, Israel Aerospace Industries, Boeing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Airborne Warning and Control System Market Shifts & Advancements
Battle management automation and regulatory algorithmic mandates are converging to reshape how airborne warning platforms classify threats and coordinate interceptor vectors across contested airspace.
Machine learning inference engines embedded in radar signal processors are automating target classification and track correlation tasks previously requiring operator interpretation. United States Air Force and Royal Air Force procurement specifications now mandate autonomous threat prioritization for next-generation platforms. This compression of human-in-the-loop latency is automating intercept geometry calculations and enabling faster engagement timelines against hypersonic threats.
The EU AI Act imposes explainability requirements on autonomous decision subsystems deployed in European airspace, forcing integrators to document algorithmic training data provenance and decision logic. Defense electronics suppliers must now maintain audit trails for threat-classification model versions deployed operationally. NATO airborne platforms operating from European bases face the steepest compliance burden, with certification timelines extending by twelve to eighteen months for systems lacking pre-positioned transparency documentation.
Performance-based logistics contracts are displacing traditional spares-and-maintenance agreements for large-aperture radar sustainment. United States and United Kingdom operators now contract for availability metrics rather than component deliveries, transferring subsystem reliability risk to prime integrators. This reconfiguration concentrates aftermarket revenue with platform-original manufacturers possessing integrated diagnostics and predictive maintenance data architectures.
Global Airborne Warning and Control System Market Segmentation
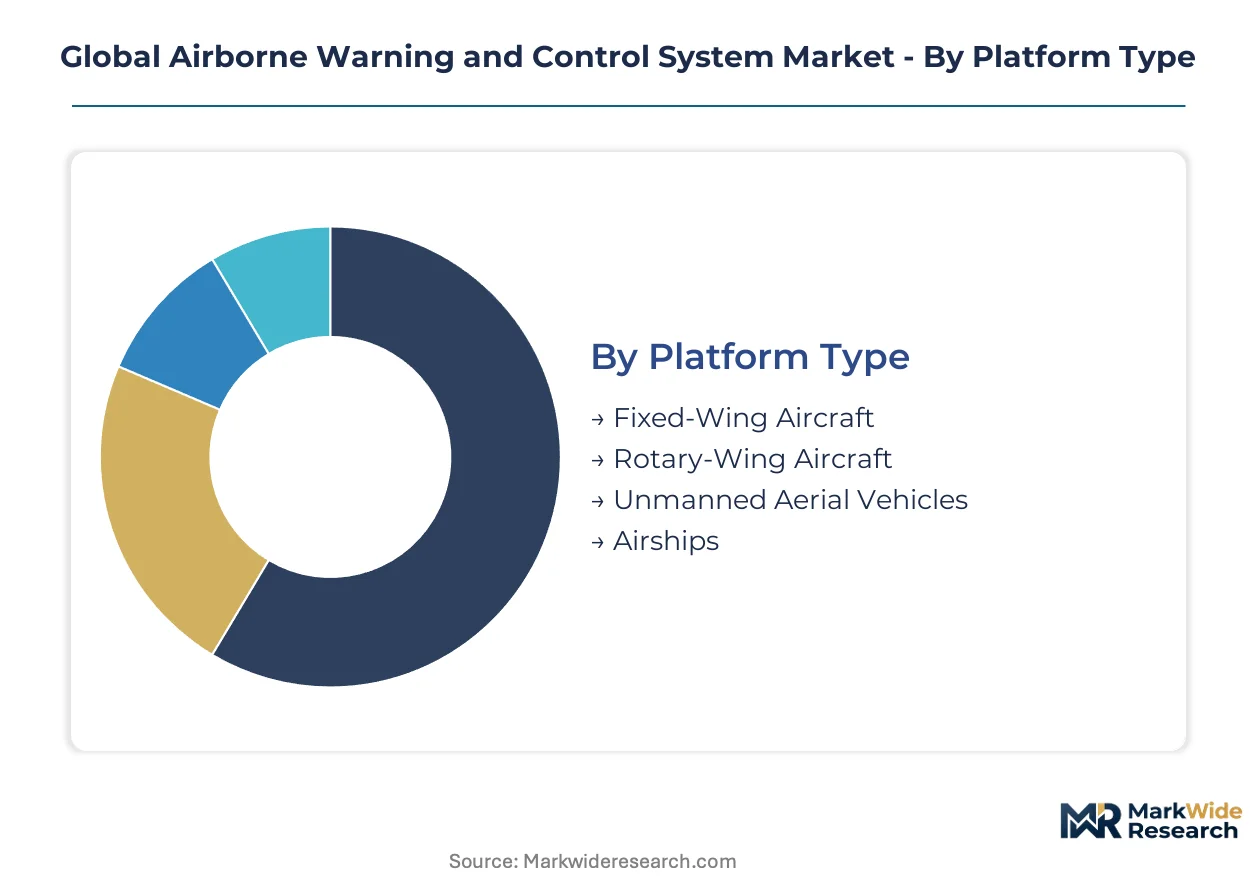
AWACS procurement decisions fragment across platform endurance requirements, radar aperture constraints, and mission system interoperability mandates. Each segmentation dimension carries distinct certification burdens from military airworthiness authorities and spectrum regulators.
Platform Type:
Fixed-Wing Aircraft and Unmanned Aerial Vehicles face divergent certification pathways under FAA airworthiness standards and NATO STANAG interoperability protocols, while Rotary-Wing Aircraft and Airships navigate additional vertical lift and buoyancy system approvals.
- Fixed-Wing Aircraft:Modified commercial or military airframes carry large-aperture radars with 400-kilometer detection ranges and 12-hour mission endurance. Demand concentrates in the United States, the United Kingdom, and Saudi Arabia as NATO allies and Gulf partners prioritize fleet recapitalization over legacy E-3 Sentry platforms.
- Unmanned Aerial Vehicles:Persistent surveillance architectures eliminate crew risk and extend orbit times beyond human endurance limits. The United States Air Force and Royal Air Force procurement specifications now mandate autonomous threat prioritization, accelerating substitution pressure against crewed alternatives.
- Rotary-Wing Aircraft:Compact rotorcraft configurations serve expeditionary basing requirements with reduced radar aperture and shorter detection ranges.
- Airships:Lighter-than-air platforms offer extended loiter at lower operating costs for homeland defense and maritime patrol missions.
Fixed-Wing Aircraft sits at the top of the volume ranking, with Unmanned Aerial Vehicles climbing the fastest.
Radar Technology:
Cost tiers separate legacy mechanical-scan systems from solid-state architectures, with GaN substrate scarcity driving steep procurement premiums for advanced transmit-receive modules.
- AESA:Active electronically scanned arrays eliminate mechanical scan latency through solid-state transmit-receive modules, enabling simultaneous multi-mode operations. Demand concentrates in NATO member states and Saudi Arabia as operators accelerate legacy platform replacement schedules amid intensified geopolitical competition.
- Phased Array:Passive electronically scanned configurations retain relevance for mid-tier operators seeking upgrade pathways without full AESA conversion costs.
- Pulse-Doppler:Mechanical scanning systems persist in legacy platform sustainment contracts and export-restricted markets.
- Synthetic Aperture:High-resolution ground mapping capabilities serve maritime patrol and border surveillance missions requiring terrain-following precision.
- Over-the-Horizon:Skywave propagation systems detect targets beyond line-of-sight for early warning applications across expansive territorial boundaries.
AESA commands the steepest procurement premiums, with Solid-State Phased Array variants gaining share fastest among mid-tier defense budgets.
Mission Scope:
Application intensity varies by threat environment, with contested airspace driving multi-mission integration and permissive regions accepting single-role configurations.
- Early Warning:Long-range threat detection and interceptor vectoring constitute the core AWACS function, requiring integration with identification friend-or-foe interrogators and battle management computers. Demand concentrates in the United States and Saudi Arabia as operators field layered defense architectures against hypersonic and cruise missile threats.
- Command & Control:Battle management automation compresses human-in-the-loop latency for engagement timeline acceleration. NATO procurement specifications now mandate autonomous intercept geometry calculations.
- Surveillance:Persistent area coverage supports intelligence collection and pattern-of-life analysis for coalition operations.
- Electronic Warfare:Emitter mapping and jamming coordination require additional spectrum allocation approvals from national communications regulators.
- Maritime Patrol:Surface vessel tracking and anti-submarine warfare integration serve naval aviation and coastal defense end users.
Early Warning sits at the top of the volume ranking, with Command & Control climbing the fastest as automation requirements harden in procurement specifications.
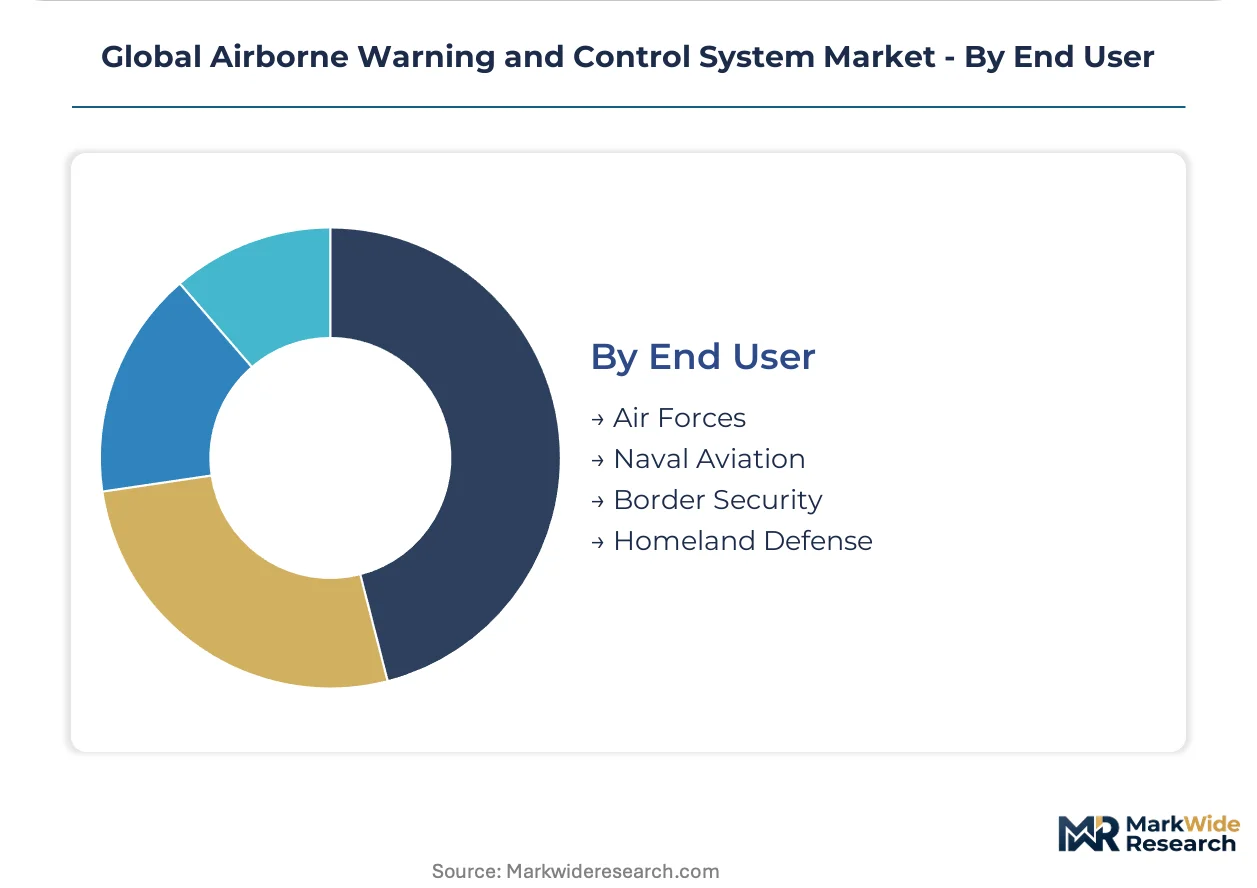
End User:
Customer type determines procurement authority structures, with air forces controlling platform acquisition and naval aviation influencing mission system specifications.
- Air Forces:Primary platform operators control fleet modernization timelines and dictate radar performance requirements. The United States Air Force, Royal Air Force, and Royal Saudi Air Force generate anchor demand through E-7 Wedgetail procurement and indigenous platform development.
- Naval Aviation:Carrier-based and shore-based maritime patrol operators require corrosion-resistant configurations and sea-state compensation algorithms.
- Border Security:Civil-military hybrid operators navigate dual-use export control restrictions under the Wassenaar Arrangement.
- Homeland Defense:Domestic air sovereignty missions require FAA airspace deconfliction certification and EU AI Act algorithmic transparency compliance for European basing.
Air Forces sits at the top of the volume ranking, with Homeland Defense climbing the fastest as CSRD disclosure mandates reshape public contract eligibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in aerospace hubs anchor procurement concentration across NATO member states and Gulf partners. Defense electronics specialists concentrate near military flight test corridors and radar integration facilities. Fleet modernization timelines diverge sharply between established operators replacing legacy platforms and emerging buyers acquiring first-generation capabilities.
United States
The United States Air Force drives E-7 Wedgetail procurement and autonomous threat prioritization mandates for next-generation platforms. FAA coordinates airspace deconfliction standards that shape military flight test corridors for new AWACS derivatives. Engineering teams in the Seattle-Tacoma aerospace cluster integrate AESA radar systems with modified commercial airframes under compressed development timelines.
United Kingdom
Royal Air Force fleet recapitalization generates anchor demand for integrated mission systems and training infrastructure through 2030. Ministry of Defence procurement specifications align with NATO STANAG interoperability protocols for sensor data formatting. Defense electronics integration activity concentrates around RAF Waddington in Lincolnshire, where Wedgetail conversion and crew training infrastructure expand operational capacity.
Saudi Arabia
Royal Saudi Air Force prioritization of airborne early warning capabilities amid regional security pressures sustains new-build platform procurement. General Authority for Military Industries localization mandates reshape offset requirements for foreign defense contractors. Industrial development clusters in Riyadh and the Eastern Province host maintenance, repair, and overhaul facilities for phased array radar sustainment.
Israel
Israel Aerospace Industries and Elbit Systems anchor indigenous platform development with persistent surveillance architectures for contested airspace operations. Israeli Ministry of Defense procurement emphasizes autonomous threat classification and intercept geometry automation. Defense electronics engineering concentrates in the Haifa metropolitan area, where radar signal processing and battle management computer integration facilities operate under strict export control protocols.
Germany
Luftwaffe participation in NATO airborne early warning force pooling arrangements sustains upgrade cycles for legacy platform interoperability. German aerospace regulators enforce EU AI Act algorithmic transparency requirements on autonomous subsystems deployed from European bases. Industrial activity clusters in Bavaria and Baden-Württemberg, where sensor integration and mission system testing facilities support multinational platform certification programs.
Global Airborne Warning and Control System Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across radar technology and mission system integration tiers. Market structure concentrates around prime integrators possessing captive semiconductor foundry capacity and NATO STANAG certification authority. Three archetypes dominate: vertically integrated defense conglomerates with in-house radar production, mission system integrators anchoring multi-platform contracts, and unmanned platform specialists with persistent surveillance architectures. Competitive dynamics center on AESA manufacturing line retooling and performance-based logistics contract capture for aftermarket sustainment.
Among diversified defense conglomerates, Raytheon Technologies and Northrop Grumman exemplify vertically integrated positioning through captive supply of solid-state transmit-receive modules. L3Harris Technologies occupies a specialist integrator role, anchoring mission system contracts across multiple NATO airborne platforms. These three companies represent distinct competitive vectors: semiconductor self-sufficiency, multi-platform integration scale, and unmanned persistent surveillance architecture dominance respectively.
| Leading Market Players |
|---|
| Raytheon Technologies |
| L3Harris Technologies |
| Lockheed Martin |
| General Atomics Aeronautical Systems |
| Saab AB |
| Northrop Grumman |
| Thales Group |
| Israel Aerospace Industries |
| Boeing |
| Others |
Supply & Pricing Matrix
AESA radar migration from mechanical to solid-state architectures simultaneously compresses unit production costs and concentrates procurement leverage among foundries with gallium nitride substrate capability. This dual transformation rewards suppliers with captive semiconductor capacity while squeezing margins for integrators dependent on external transmit-receive module sourcing.
Pricing Analysis
Platform-original manufacturers bundle performance-based logistics contracts with radar system sales, while third-party sustainment providers compete on unbundled spares pricing. Price differentiation hinges on NATO STANAG certification authority and GaN substrate purity grades. Cost compression in mid-tier phased array configurations is intensifying because Saudi Arabia and Gulf partners negotiate volume offsets against legacy E-3 replacement schedules. Air forces with established fleet infrastructure show lowest price sensitivity; border security operators face steepest budget constraints.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and German specialty foundries supplying high-purity GaN wafers for solid-state transmit-receive modules. Raw material dependencies span gallium nitride substrates, radar-grade aluminum alloys, and battle management computer chipsets. Supply chain risk centers on Wassenaar Arrangement export licensing delays for non-allied platform deliveries. Distribution runs through prime integrators with NATO STANAG certification authority and established military flight test relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU AI Act algorithmic transparency mandates extend certification timelines and concentrate aftermarket revenue with compliant platform-original manufacturers.
For Market Incumbents: Cement multi-platform integration scale by capturing Royal Air Force E-7 Wedgetail training infrastructure contracts through 2030. Deepen backward integration into GaN foundry capacity to insulate phased array production from Japanese substrate scarcity. Autonomous threat-classification subsystem standardization poses substitution risk from unmanned platform specialists.
For New Entrants and Emerging Players: The premium-to-economy price gap in AESA radar sustainment services opens white-space targets in performance-based logistics for mid-tier NATO operators with legacy platform fleets. Expeditionary rotary-wing configurations for coalition operations represent the most penetrable segment. Pursue offset partnerships with Saudi General Authority for Military Industries to satisfy localization mandates.
For Investors and Strategic Acquirers: Roll-up economics work for mission system integrators because NATO STANAG interoperability protocols create technical moats around incumbent certification authorities. Five-to-ten year viability favors specialists with persistent surveillance UAV architectures and autonomous battle management automation. Monitor Royal Saudi Air Force procurement acceleration as inflection indicator for Gulf demand expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| GaN Foundry Capacity Expansion | Captive substrate supply insulates Raytheon and Northrop Grumman from input cost volatility. |
| Performance-Based Logistics Contract Capture | Availability metrics transfer reliability risk to primes with predictive maintenance data architectures. |
| EU AI Act Compliance Certification | Algorithmic transparency documentation extends NATO platform certification timelines by twelve to eighteen months. |
| Unmanned Persistent Surveillance Development | Extended orbit times without crew risk accelerate substitution pressure against crewed E-3 replacements. |
| Saudi Offset Partnership Structuring | General Authority for Military Industries localization mandates reshape foreign contractor eligibility. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged radar system engineers at prime integrators, NATO procurement officers, Royal Air Force fleet planners, GaN foundry operations managers, and defense electronics regulatory specialists. Secondary validation drew from FAA airworthiness certification databases, EU AI Act implementation guidance, Wassenaar Arrangement control list updates, and NATO STANAG protocol documentation. Bottom-up platform delivery tallies and top-down defense budget appropriations were cross-referenced for triangulation.
Historical reference periods anchored the projection horizon through E-3 Sentry fleet retirement schedules and E-7 Wedgetail conversion timelines. Segmentation modeling spanned platform type, radar technology tier, mission scope intensity, and end-user procurement authority. CAGRs were derived from fleet modernization acceleration curves and AESA migration adoption rates. Forecast inputs incorporated gallium nitride substrate supply elasticity and autonomous threat-classification software certification delays.
Caveats apply where Wassenaar Arrangement export control expansions or GaN foundry supply disruptions could materially shift the outlook. Forecasts incorporate assumptions about NATO interoperability mandate continuity and Saudi defense budget prioritization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Surveillance
EO/IR Gimbal Market
Military Surveillance
Global Military Man-Portable Radar System Market
Military Surveillance
North America Passive Radar Market
Military Surveillance
Sea-Based Military Electro-Optical and Infrared Systems Market
Military Surveillance
Maritime Surveillance Market
Military Surveillance
Infrared Anti-Sniper Detection System Market
Military Surveillance
Hydrographic Equipment Market
Military Surveillance
Global Military Electro-Optical and Infrared Systems Market
Military Surveillance
Night Vision Devices Market
Military Surveillance
Defense Geospatial Market
Military Surveillance
Global Airport Surveillance Radar Market
Military Surveillance
Infrared Anti-Sniper Detection Software Market
Military Surveillance
Europe Intelligence Surveillance and Reconnaissance Market
Military Surveillance
Manportable Radar Market
Military Surveillance
Drone Surveillance Platform Market
Military Surveillance
Manportable Surveillance and Target Acquisition Radar Market