
 Surface Vision and Inspection Market | 2026-2036
Surface Vision and Inspection Market Size, Share, and Industry Trends Forecast 2026-2036
Surface Vision and Inspection Market Intelligence
Software-as-a-Service (SaaS) licensing for advanced analytics and algorithm updates is hardening the recurring revenue models for system providers. Cognex Corporation leverages its extensive software patent portfolio to lead in the electronics and logistics sectors. Keyence Corporation competes on the basis of its direct sales model and highly integrated hardware-software solutions. Basler AG specializes in high-performance cameras, a critical component for system integrators and custom solution developers.
Surface vision and inspection systems utilize cameras, lighting, and software algorithms to automatically analyze surfaces for defects or anomalies. These systems can detect flaws like scratches, dents, or misprints with micron-level precision. Their primary purpose is to automate quality control in high-speed manufacturing environments, replacing manual inspection. Integrated systems represent the largest solution segment, while software's value contribution is accelerating. Within applications, defect detection for the automotive and electronics end-user sectors commands the highest investment priority.
Compliance with ISO 9001 quality management standards drives adoption in many industries. In the medical device and pharmaceutical sectors, regulations from the US FDA and the European EMA mandate stringent inspection and traceability, creating specific demand for validated vision systems. The critical decision for end-users now revolves around choosing between standardized, off-the-shelf systems and highly customized solutions tailored to specific production lines.
Market Dynamics
The central force shaping the market is the mandate for zero-defect manufacturing in high-value industries. This pressure compels the integration of artificial intelligence within inspection software to achieve micron-level precision at speeds that manual inspection cannot match.
Growth Catalysts
- Regulatory Mandates:Stringent traceability and quality validation rules from the US FDA and European EMA for medical devices and pharmaceuticals create a non-discretionary need for automated, documented inspection systems.
- EV Battery Production:The global expansion of electric vehicle manufacturing creates intense demand for vision systems to inspect battery cells, modules, and packs for microscopic defects that can impact safety and performance.
- 3D Vision Adoption:The increasing use of 3D vision technology enables the precise inspection of complex geometries and assemblies, unlocking applications in aerospace component verification and consumer electronics manufacturing.
Market Restraints
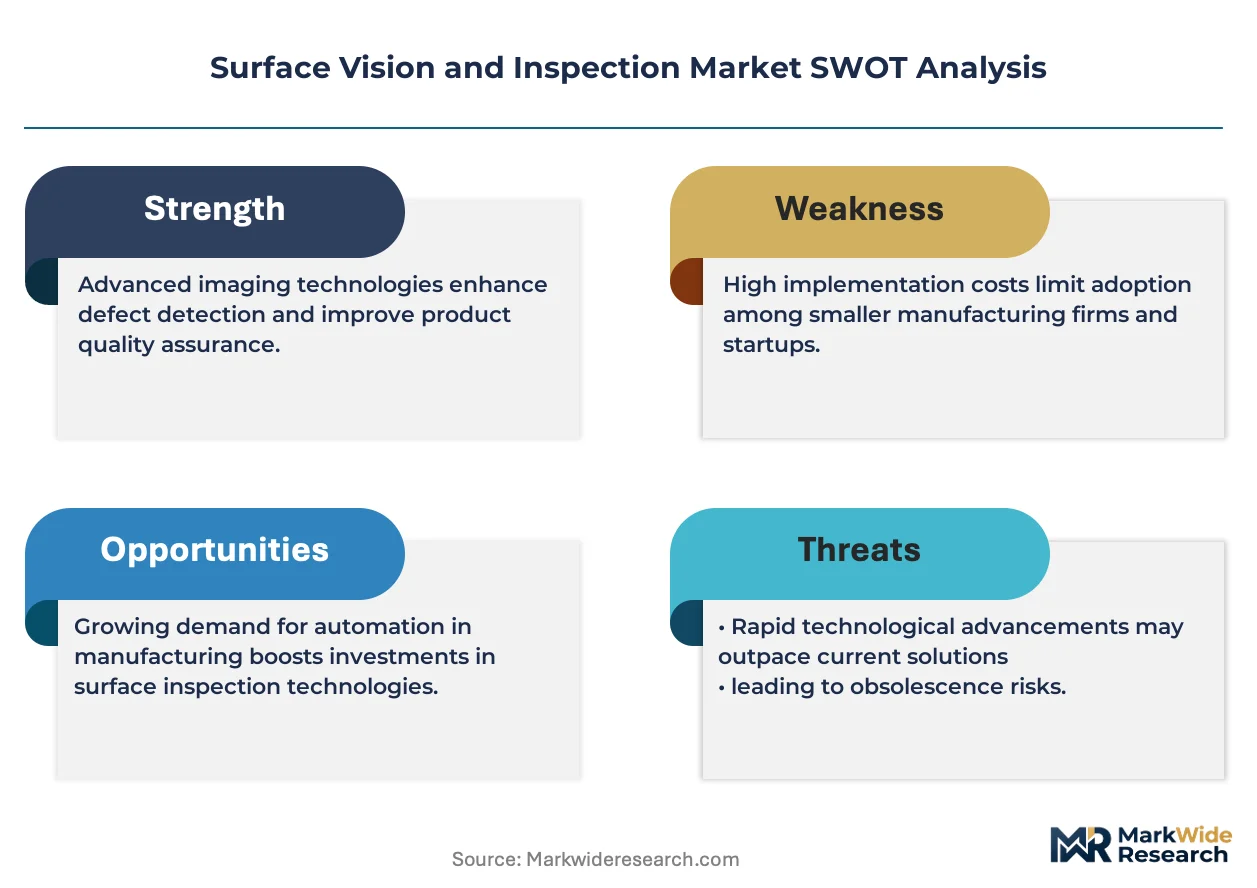
- High Capital Cost:The significant initial investment required for high-speed, fully integrated vision systems presents a substantial barrier to adoption for small and medium-sized manufacturing enterprises.
- Technical Limitations:Inspecting highly transparent or specular surfaces remains a persistent challenge, as reflections and lack of contrast can impede the accuracy of standard imaging algorithms and lighting techniques.
- Component Sourcing Risk:A high concentration of advanced CMOS sensor and specialized optics manufacturing in a few countries, particularly in East Asia, introduces supply chain vulnerability and price volatility.
Strategic Opportunities
- Food and Agriculture:Applying vision systems to automate the quality grading, sorting, and defect detection of fresh produce and processed foods represents a largely underpenetrated market vertical.
- Hyperspectral Imaging:The convergence of hyperspectral cameras with machine learning algorithms opens opportunities to detect defects based on material composition, not just visual appearance, in sectors like recycling and pharmaceuticals.
- Emerging Industrial Hubs:Expanding sales and support operations into rapidly industrializing economies in Southeast Asia, such as Vietnam and Indonesia, can capture new demand from electronics and automotive manufacturers.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of engineers and data scientists with the dual expertise in machine vision and modern AI frameworks hinders the development and deployment of custom solutions.
- Legacy System Integration:Integrating modern vision systems with older factory floor equipment and disparate Manufacturing Execution Systems (MES) often requires complex, costly, and time-consuming custom software development.
- Data Infrastructure Burden:The immense volume of high-resolution image data generated by inspection lines requires significant investment in on-premise or cloud-based storage and processing capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surface Vision and Inspection Market |
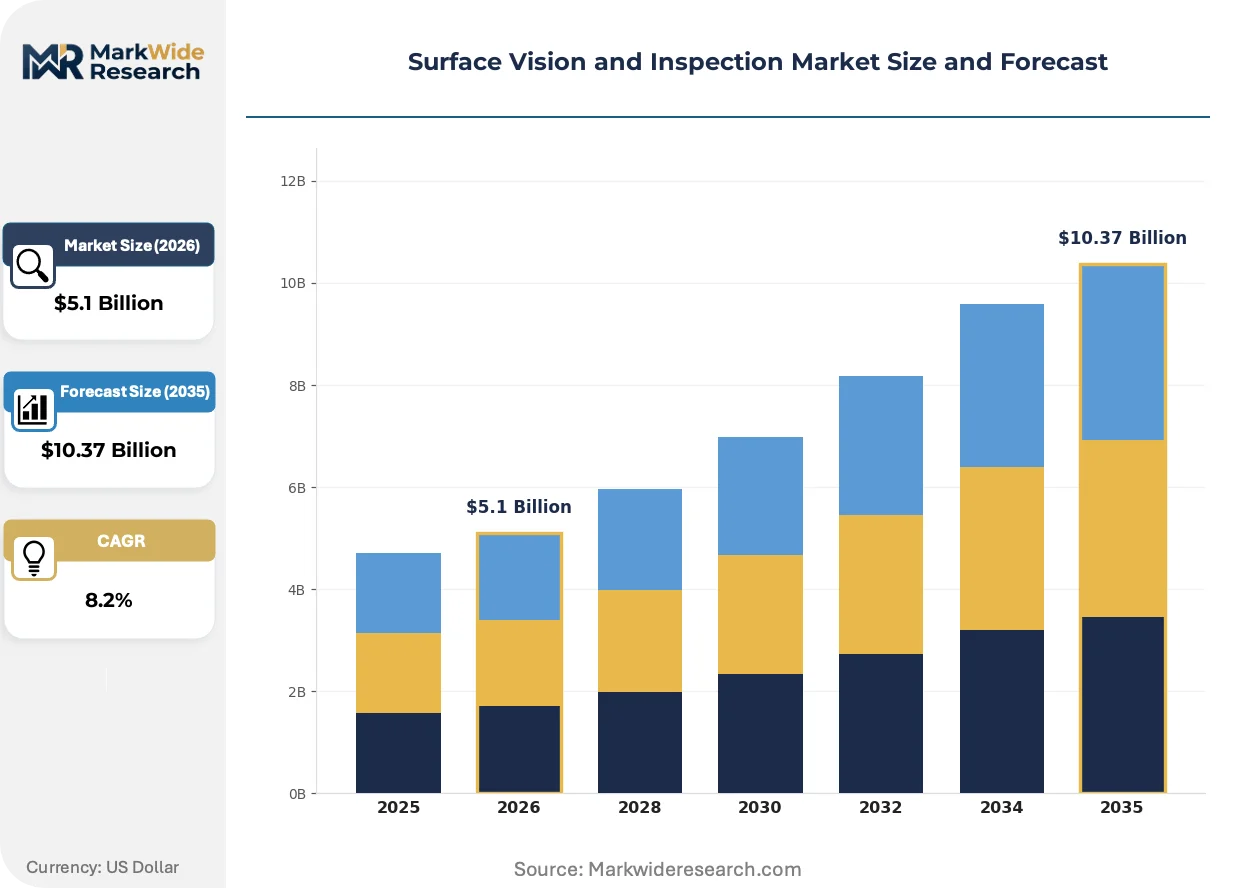
| Market Size in 2026 | $5.1 Billion |
| Market Size in 2035 | $10.37 Billion |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Vision, Image Processing, Laser Scanning, Infrared Imaging Application: Quality Control, Defect Detection, Measurement, Surface Inspection End User: Automotive, Aerospace, Electronics, Pharmaceuticals Solution: Hardware, Software, Integrated Systems, Custom Solutions |
| Companies Covered | Teledyne Technologies, Basler AG, Cognex Corporation, AMETEK Surface Vision, SICK AG, Keyence Corporation, ISRA VISION, Panasonic Holdings Corporation, Omron Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surface Vision and Inspection Market Strategic Shifts & Innovations
Software intelligence is redefining the value proposition of surface inspection, shifting focus from hardware-centric defect flagging to data-driven process control. This evolution transforms inspection systems from quality gates into sources of predictive manufacturing insights, driven by advancements in AI.
Deep learning algorithms represent a fundamental shift in image processing. These neural networks learn to identify defects from example images, eliminating the need for tedious manual programming of inspection rules. Electronics and automotive manufacturers are rapidly adopting this technology for its superior flexibility and accuracy. This software-driven capability is converging with edge computing hardware, enabling complex AI models to run directly on the camera or a local processor for immediate, on-line decision-making.
The European Union's AI Act introduces a risk-based legal framework governing the use of artificial intelligence. This regulation compels providers to ensure their algorithms are transparent, robust, and auditable, especially in high-risk applications like medical device manufacturing. Vision system developers are consequently embedding enhanced data governance and model validation features into their platforms to provide customers with the necessary documentation for compliance.
End-user procurement patterns are evolving from one-time capital expenditures toward subscription-based licensing for software and analytics. This model disrupts the traditional hardware-focused sale, placing greater emphasis on recurring revenue from continuous algorithm updates, performance monitoring, and cloud-based data services. This shift is most visible within the logistics and consumer electronics sectors, where operational agility and access to the latest software innovations are critical competitive advantages.
Surface Vision and Inspection Market Segmentation
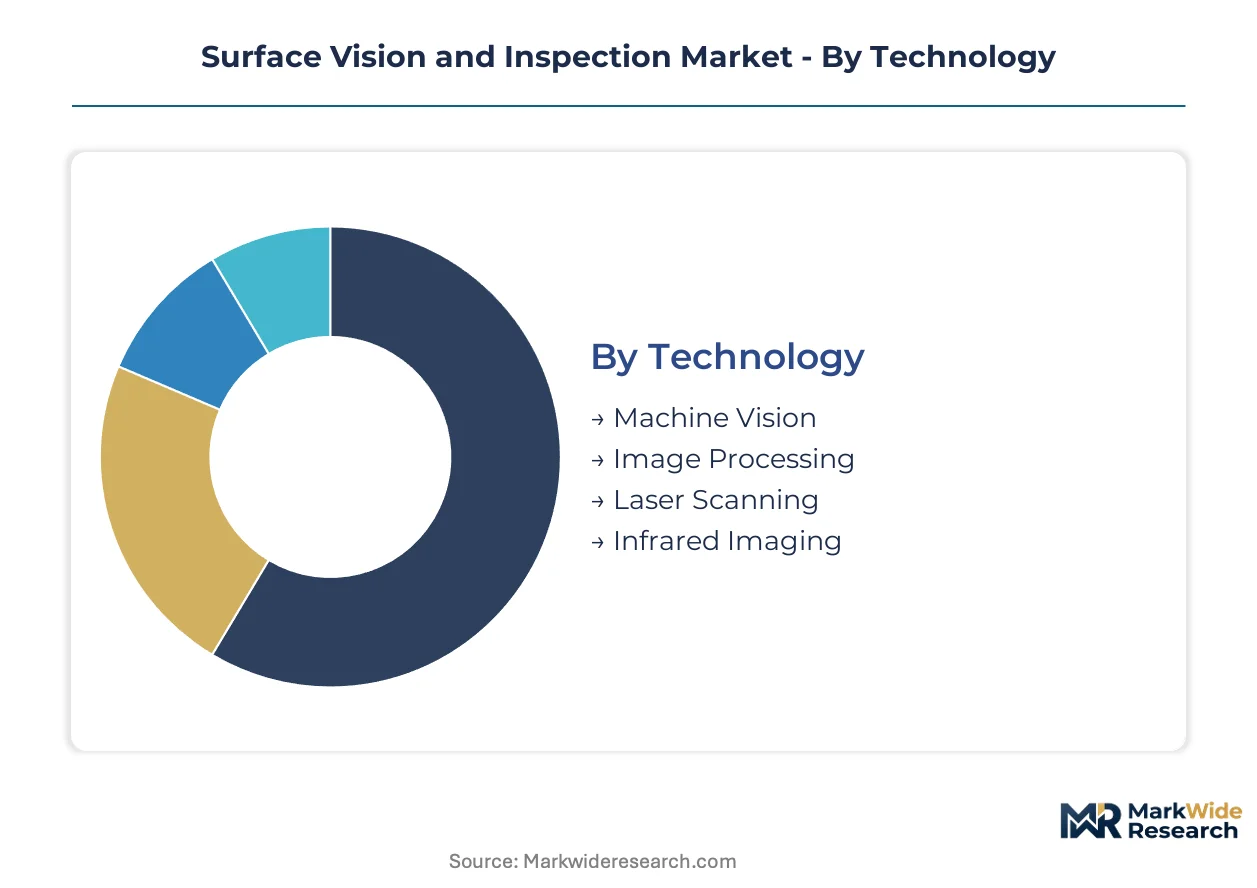
The Surface Vision and Inspection Market categorizes its diverse offerings to reflect the varied technological approaches, industrial applications, end-user requirements, and solution architectures. This segmentation provides clarity on where investment priorities lie and how different market components contribute to overall growth and innovation.
Technology:
The initial capital outlay for surface vision systems varies significantly across technology types, with advanced sensor-driven approaches often demanding higher upfront investments.
- Machine Vision:This technology employs cameras, lighting, and specialized software to capture and process images for automated analysis. Demand concentrates heavily in advanced manufacturing clusters in Germany and the United States, driven by the need for high-speed, automated quality control in electronics production.
- Image Processing:Image processing involves algorithms and software to enhance and interpret visual data captured by cameras, enabling defect identification and measurement. Its value contribution is accelerating in the automotive sector, where artificial intelligence integration enhances defect detection accuracy and speed for zero-defect component verification.
- Laser Scanning:Laser scanning systems use structured light to create 3D profiles of objects, enabling precise inspection of complex geometries in aerospace applications.
- Infrared Imaging:Infrared imaging detects thermal variations or material composition differences, useful for specialized inspection tasks in pharmaceutical manufacturing.
Machine Vision absorbs the bulk of installed capacity; Image Processing is expanding most quickly.
Application:
The cost structure associated with different surface vision applications reflects the precision requirements and regulatory compliance demands of each task.
- Defect Detection:This application identifies flaws like scratches, dents, or misprints on surfaces with micron-level precision, often replacing manual inspection processes. It commands the highest investment priority within the automotive and electronics end-user sectors, compelled by zero-defect manufacturing mandates.
- Quality Control:Quality control applications ensure products meet predefined standards through automated visual inspection, streamlining manufacturing processes. Regulatory mandates from the US FDA and European EMA for medical devices necessitate stringent quality validation, driving adoption in pharmaceutical production.
- Measurement:Measurement applications accurately determine physical dimensions and geometric properties of components, crucial for tight tolerance manufacturing.
- Surface Inspection:Surface inspection broadly encompasses automated visual assessment of material surfaces for anomalies, a foundational task in high-speed production.
Defect Detection represents the largest volume of deployed systems; Quality Control is experiencing rapid expansion.
End User:
End-user sectors drive varying volumes of vision system deployments, influenced by production scale and the criticality of quality assurance.
- Automotive:The automotive sector utilizes vision systems for zero-defect component verification and assembly inspection, critical for safety and performance. The global expansion of electric vehicle manufacturing, particularly EV battery production, creates intense demand for microscopic defect detection.
- Electronics:Electronics manufacturing relies on surface inspection for quality control of components and assemblies, ensuring product reliability and functionality. Demand is concentrating in advanced manufacturing clusters such as South Korea and the United States for high-volume production lines.
- Aerospace:Aerospace manufacturing uses vision systems for inspecting complex geometries and critical components, ensuring stringent safety and performance standards.
- Pharmaceuticals:The pharmaceutical sector requires validated vision systems for stringent inspection and traceability, mandated by regulations like those from the US FDA.
Automotive accounts for the most significant portion of end-user spend; Electronics is gaining share fastest.
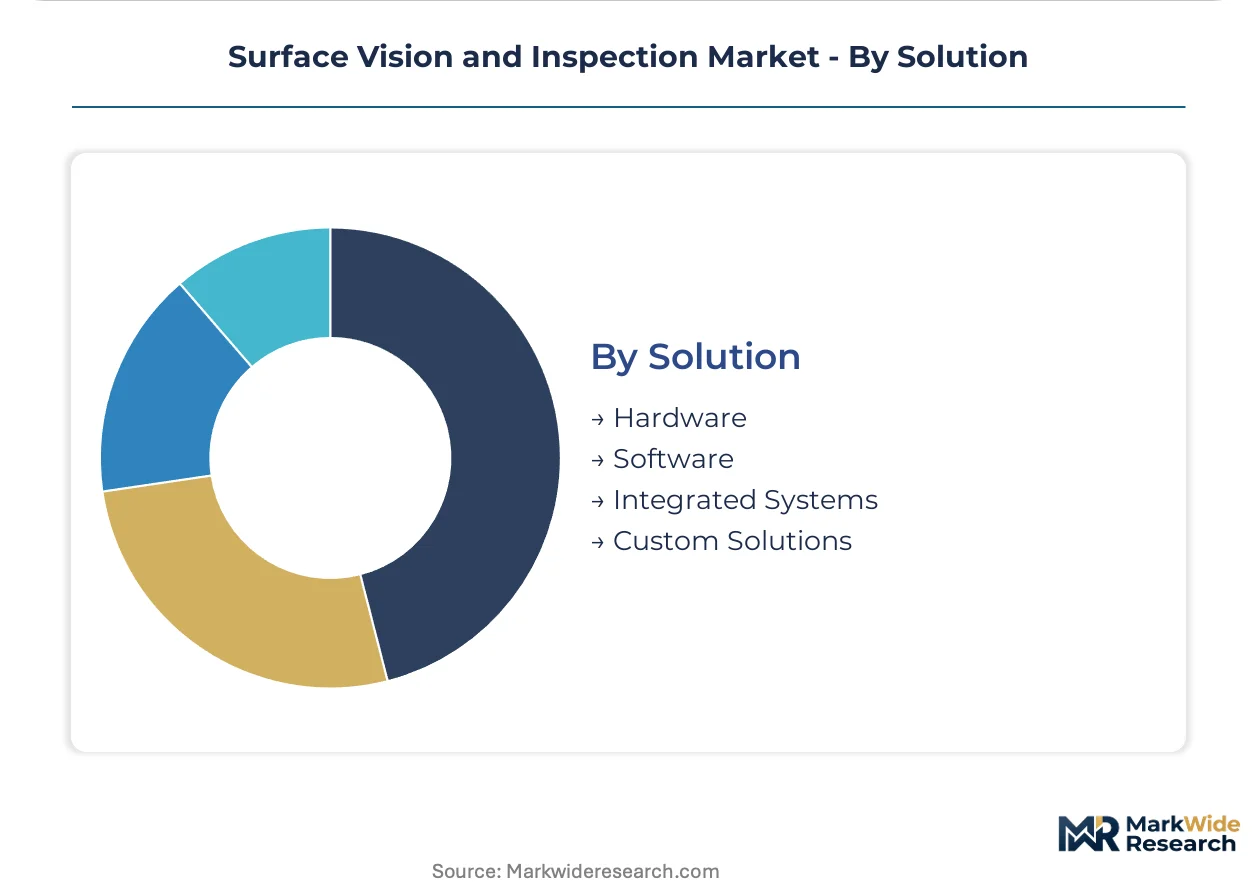
Solution:
The maturity of different solution types within the market ranges from established hardware components to evolving software-as-a-service models.
- Integrated Systems:Integrated systems combine cameras, lighting, and software into complete, ready-to-deploy inspection units, offering comprehensive solutions. This segment represents the largest solution category, providing seamless functionality for automated quality control in diverse manufacturing environments.
- Software:Software solutions encompass image processing algorithms, advanced analytics, and AI frameworks for defect detection and data interpretation. Software's value contribution is accelerating through SaaS licensing models, hardening recurring revenue for system providers in logistics and consumer electronics.
- Hardware:Hardware includes cameras, lenses, and lighting components, forming the physical foundation for vision and inspection systems.
- Custom Solutions:Custom solutions are tailored vision systems developed for specific production lines or unique inspection challenges, often involving specialized integration.
Integrated Systems remain the dominant solution type; Software exhibits the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's advanced manufacturing clusters, particularly in the automotive and electronics sectors, drive significant demand for surface vision and inspection systems. These regions prioritize precision and automation to meet stringent quality benchmarks. The market is also expanding across other key industrial nations, each with unique regulatory landscapes and technological adoption patterns.
Germany
Demand for surface vision systems in Germany stems from its robust automotive sector and high-speed electronics production lines. The EU AI Act influences system development, requiring transparency and auditability for AI-driven inspection solutions. Industrial hubs like Stuttgart and Munich focus on integrating vision systems for zero-defect manufacturing in complex assemblies.
United States
The United States market is fueled by aerospace component verification, advanced electronics manufacturing, and medical device compliance. US FDA regulations mandate stringent inspection and traceability for pharmaceutical and medical applications. Clusters in Silicon Valley and Detroit are adopting AI-enhanced vision systems for quality control and predictive maintenance.
South Korea
South Korea exhibits strong demand for surface vision in its high-volume electronics manufacturing and burgeoning EV battery production. National quality standards and industry initiatives promote the adoption of automated inspection technologies. Key industrial zones around Seoul and Ulsan are investing heavily in advanced vision systems for microscopic defect detection.
China
China's rapid expansion in electric vehicle battery production and general electronics manufacturing creates substantial demand for surface vision systems. GB standards and national industrial policies encourage the deployment of automated quality control solutions. Manufacturing centers in the Yangtze River Delta and Pearl River Delta are integrating vision systems to enhance product quality and production efficiency.
Japan
Japan's precision manufacturing industries, including automotive and consumer electronics, require highly accurate surface vision and inspection capabilities. JIS standards guide quality control practices, promoting the use of advanced optical and software solutions. Industrial areas around Tokyo and Nagoya are implementing vision systems for intricate component inspection and assembly verification.
Surface Vision and Inspection Market Key Industry Players
Capital-heavy producers of specialized hardware components compete with asset-light designers of advanced software and integrated solutions within the surface vision and inspection market. The market structure exhibits a tiered approach, with established players alongside niche innovators. Strategic archetypes include dedicated hardware manufacturers, AI-driven software developers, and comprehensive system integrators. Competitive moves often involve technology licensing to broaden market reach and direct sales models to maintain customer relationships.
Within the integrated systems tier, Keyence Corporation offers highly integrated hardware-software solutions, emphasizing a direct sales model for specialized customer engagement. Cognex Corporation leverages its extensive software patent portfolio, particularly in the electronics and logistics sectors, to provide advanced image processing capabilities. Basler AG, a specialist in high-performance cameras, anchors the hardware component segment, supplying critical imaging technology to system integrators and custom solution developers.
| Leading Market Players |
|---|
| Teledyne Technologies |
| Basler AG |
| Cognex Corporation |
| AMETEK Surface Vision |
| SICK AG |
| Keyence Corporation |
| ISRA VISION |
| Panasonic Holdings Corporation |
| Omron Corporation |
| Others |
Cost & Logistics Intelligence
The EU AI Act, a specific environmental mandate, gates both qualified system supply and premium-tier pricing access for AI-driven inspection solutions. This regulation compels providers to ensure transparent and auditable algorithms, impacting development costs and market entry.
Pricing Analysis
Value-based pricing for advanced analytics and algorithm updates anchors revenue models within the market. SaaS licensing and project-based integrated system sales represent dominant pricing structures. Price differentiation stems from customization levels for specific production lines and certification levels for regulated industries like medical devices. Pricing softness appears in hardware components due to commoditization, while software commands a premium. Small and medium-sized enterprises exhibit higher price sensitivity compared to large automotive or electronics manufacturers.
Supply Chain Analysis
Advanced CMOS sensor production rests on East Asian manufacturing clusters, including South Korea and Japan, forming a critical input dependency. Specialized optics and high-performance cameras, often sourced from Germany and Japan, also comprise vital components. Component sourcing risk arises from this geographic concentration, leading to potential supply chain vulnerability and price volatility. Distribution runs through a mix of direct sales models, particularly for integrated solutions, and extensive networks of system integrators for custom deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Surface Vision and Inspection Market is witnessing a vertical-integration race, with players actively pursuing software intelligence as a key competitive lever.
For Market Incumbents: Acquire specialized AI software firms to deepen deep learning capabilities and enhance defect detection accuracy. Invest heavily in R&D for advanced sensor technologies to overcome technical limitations with transparent or specular surfaces. Bolster regulatory compliance teams to navigate complex mandates like the EU AI Act, mitigating potential market access threats. Expand solution offerings to include predictive maintenance insights, moving beyond traditional quality gate functions.
For New Entrants and Emerging Players: Small and medium-sized manufacturing enterprises represent an underserved buyer archetype, particularly in less regulated sectors. Target the food and agriculture vertical with simplified, cost-effective vision systems for quality grading and sorting. Offer subscription-based, cloud-enabled SaaS solutions to lower upfront capital costs for new customers. Develop specialized AI algorithms for niche applications, providing a distinct go-to-market angle against broader solutions.
For Investors and Strategic Acquirers: Increased M&A activity in specialized AI vision software is the leading indicator that market consolidation around intelligent solutions is accelerating. Focus on companies developing hyperspectral imaging capabilities or those with strong intellectual property in deep learning for defect analysis. The long-term viability favors platforms that transform inspection data into actionable process control insights. Monitor the adoption rate of edge computing in vision systems as a signal for future hardware-software integration opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquire AI Software Specialists | Enhances deep learning capabilities for superior defect detection and process control insights. |
| Invest in Hyperspectral Imaging R&D | Unlocks new defect detection based on material composition, expanding application scope. |
| Expand SaaS Licensing Models | Secures recurring revenue streams and fosters closer, continuous customer engagement for software. |
| Target Emerging Industrial Hubs | Captures new demand from rapidly industrializing economies in Southeast Asia for manufacturing. |
| Develop Edge AI Solutions | Enables immediate, on-line decision-making by processing complex AI models directly at the source. |
Research Approach
Industry association reports, patent databases, and academic journals formed the secondary backbone for this analysis, providing foundational market data. Primary research involved interviews with manufacturing engineers, quality control managers, vision system developers, and regulatory compliance officers. This approach ensured a comprehensive understanding, triangulating insights from both published literature and direct industry stakeholder perspectives.
Bottom-up analysis of installed capacity and top-down validation against macroeconomic indicators informed the forecast framework across the analysis window. Segmentation dimensions modeled included technology, application, end-user, solution type, and regional adoption patterns. Compound annual growth rates were derived from historical trends and projected market drivers, notably EV battery production forecasts and AI integration rates in manufacturing.
Revisions become necessary when significant geopolitical supply chain disruptions or rapid AI regulatory changes materialize, impacting market dynamics. Forecasts reflect assumptions concerning technological advancements and industrial investment patterns. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Sound Sensor Market
Sensors and Controls
Germany Digital Thermometer Market
Sensors and Controls
Global Color Detection Sensors Market
Sensors and Controls
Millimeter Wave Sensors and Modules Market
Sensors and Controls
Pressure Sensor Market
Sensors and Controls
Home Automation Sensors Market
Sensors and Controls
Proximity Sensors Market
Sensors and Controls
Connected Sensors Market
Sensors and Controls
Air Flow Monitoring System Market
Sensors and Controls
Battery Free Sensor Market
Sensors and Controls
MEMS Energy Harvesting Devices Market
Sensors and Controls
Pressure Transmitter and Transducer Market
Sensors and Controls
Aspiration Control Systems Market
Sensors and Controls
Instrumented Load Shackle Market
Sensors and Controls
US Pressure Sensors Market
Sensors and Controls
Safety Laser Scanner Market