
 Home Automation Sensors Market | 2026-2036
Home Automation Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Home Automation Sensors Market Outlook
Edge-native processing is reconfiguring how home automation sensors handle inference workloads locally rather than routing data through cloud gateways. Bosch Sensortec leverages its MEMS fabrication depth to sustain cost leadership in motion and environmental sensing modules. Honeywell International anchors the commercial building segment with integrated fire-safety and HVAC sensor networks. Samsung Electronics competes through vertical control over semiconductor, display, and appliance channels that lock in sensor placement across smart home ecosystems.
Home automation sensors are electromechanical or solid-state transducers that convert physical environmental variables—temperature, occupancy, luminance, or relative humidity—into digital signals readable by building management systems, typically operating within voltage ranges of 3.3V to 24V DC and communicating via protocols such as Zigbee, Z-Wave, Thread, or Wi-Fi. Their primary commercial purpose is to enable automated control of lighting, climate, security, and energy systems while reducing manual intervention and operational waste. Motion detectors and temperature sensors currently occupy the largest installed base, though humidity sensors are gaining traction in wellness-oriented residential retrofits where indoor air quality monitoring drives replacement cycles. Wireless technology leads new installations, but wired configurations persist in professional integrated systems where reliability requirements override flexibility preferences.
The Federal Communications Commission governs radio frequency emissions from wireless sensor hardware in the United States, while the EU Radio Equipment Directive mandates CE marking for devices operating in European harmonized frequency bands. Energy efficiency regulations from the Department of Energy and analogous bodies in Germany and Japan directly shape demand by mandating sensor-driven automation in new construction and major renovations. Stakeholders must monitor evolving cybersecurity certification requirements for IoT devices, as upcoming framework expansions will likely determine market access before product performance does.
Market Dynamics
Matter protocol standardization by the Connectivity Standards Alliance is dissolving interoperability barriers that previously fragmented device ecosystems, forcing manufacturers to consolidate around unified communication stacks rather than proprietary silos.
Growth Catalysts
- Utility Rebate Programs:State-level energy efficiency incentives in the United States directly subsidize smart thermostat and sensor installations in residential retrofits, compressing payback periods for homeowners.
- Building Electrification Mandates:Jurisdictions across California and New York now require sensor-driven automation in new construction and major renovations, embedding hardware demand into building codes.
- MEMS Fabrication Scale:Advanced microelectromechanical systems production lines in Germany and Taiwan are driving unit cost declines in motion and environmental sensing modules, expanding addressable volume in mid-market segments.
Market Restraints
- Semiconductor Input Volatility:Silicon wafer and rare earth magnet supply disruptions from East Asian foundries create component shortage risks for magnetometer and gyroscope production.
- Cybersecurity Certification Friction:Evolving IoT security frameworks from the FCC and analogous European bodies extend product approval timelines and raise compliance costs for new market entrants.
- Legacy Wired Infrastructure Persistence:Professional integrated systems in commercial buildings continue specifying wired sensor configurations, constraining wireless technology penetration in high-reliability applications.
Strategic Opportunities
- Wellness-Oriented Residential Retrofits:Indoor air quality monitoring applications in humid continental climate zones of the United States are accelerating replacement cycles for humidity and VOC sensors.
- Edge-Native Processing Convergence:On-device inference workloads combining TinyML models with ultra-low-power microcontrollers are opening premium positioning for sensors that operate without cloud dependency.
- Commercial HVAC Network Integration:Integrated fire-safety and climate control sensor networks in multi-tenant office buildings present bundled deployment opportunities beyond standalone residential sales.
Industry Challenges
- Embedded Firmware Talent Scarcity:Shortages of engineers proficient in real-time operating systems and radio protocol stacks constrain product development velocity for mid-tier manufacturers.
- Multi-Protocol Certification Complexity:Simultaneous Zigbee, Thread, Z-Wave, and Wi-Fi compliance testing extends time-to-market and fragments engineering resources across certification bodies.
- Interoperability Testing Burden:Matter certification requirements demand extensive cross-vendor compatibility validation, raising quality assurance overhead as ecosystem participants multiply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Automation Sensors Market |
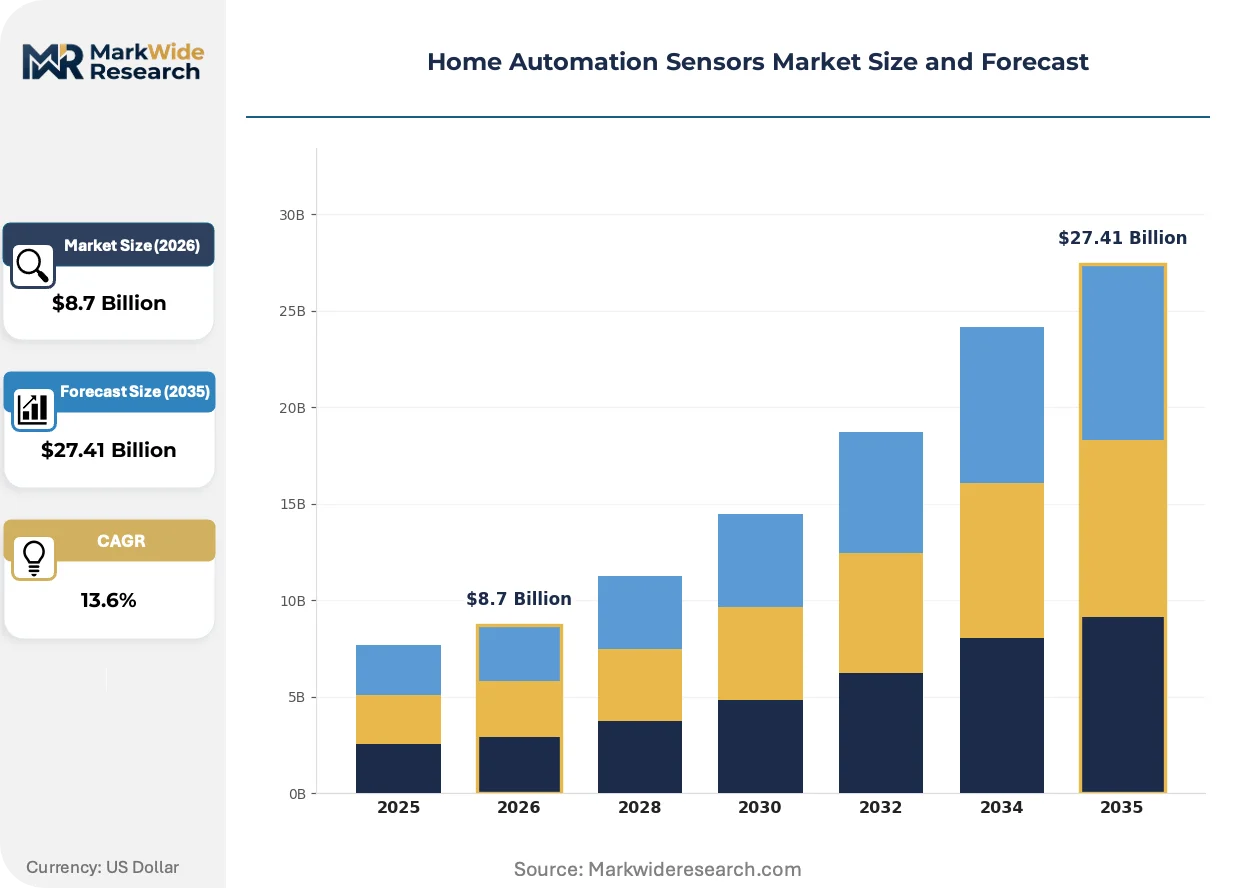
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $27.41 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Temperature Sensors, Motion Detectors, Light Sensors, Humidity Sensors Technology: Wireless, Wired, Infrared, Ultrasonic End User: Residential, Commercial, Industrial, Retail Installation: Do-It-Yourself, Professional, Integrated Systems, Standalone Devices |
| Companies Covered | Honeywell International, Sony Corp, Samsung Electronics, Schneider Electric, Siemens AG, Bosch Sensortec, Johnson Controls, Lutron Electronics, ABB Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Automation Sensors Market Strategic Shifts
Edge computing architectures are reconfiguring how inference workloads execute within home automation sensors, compressing latency and reducing cloud dependency while enabling new privacy-centric product positioning.
Ultra-wideband (UWB) ranging technology is digitizing spatial awareness in residential security and occupancy detection applications. High-end smart lock and lighting control installers in the United States are specifying UWB-enabled sensors for centimeter-precision presence detection. This capability is digitizing competitive differentiation away from basic PIR motion sensing toward fine-grained indoor positioning services.
The EU Radio Equipment Directive's expanded cybersecurity requirements are mandating encrypted firmware update channels and secure boot capabilities for all CE-marked wireless sensor hardware. Manufacturers serving European markets must redesign hardware security modules and documentation practices. Small and mid-sized vendors face disproportionate compliance burdens relative to integrated electronics conglomerates with established certification infrastructure.
Professional installer channels are consolidating procurement authority for whole-home automation systems, displacing direct-to-consumer sensor sales in premium residential segments. Custom integration firms in coastal metropolitan markets now specify sensor suites as bundled subsystems rather than discrete components. This concentration is most visible in California and Florida markets where building code stringency and hurricane resilience requirements favor professional installation over DIY deployment.
Home Automation Sensors Market Segmentation
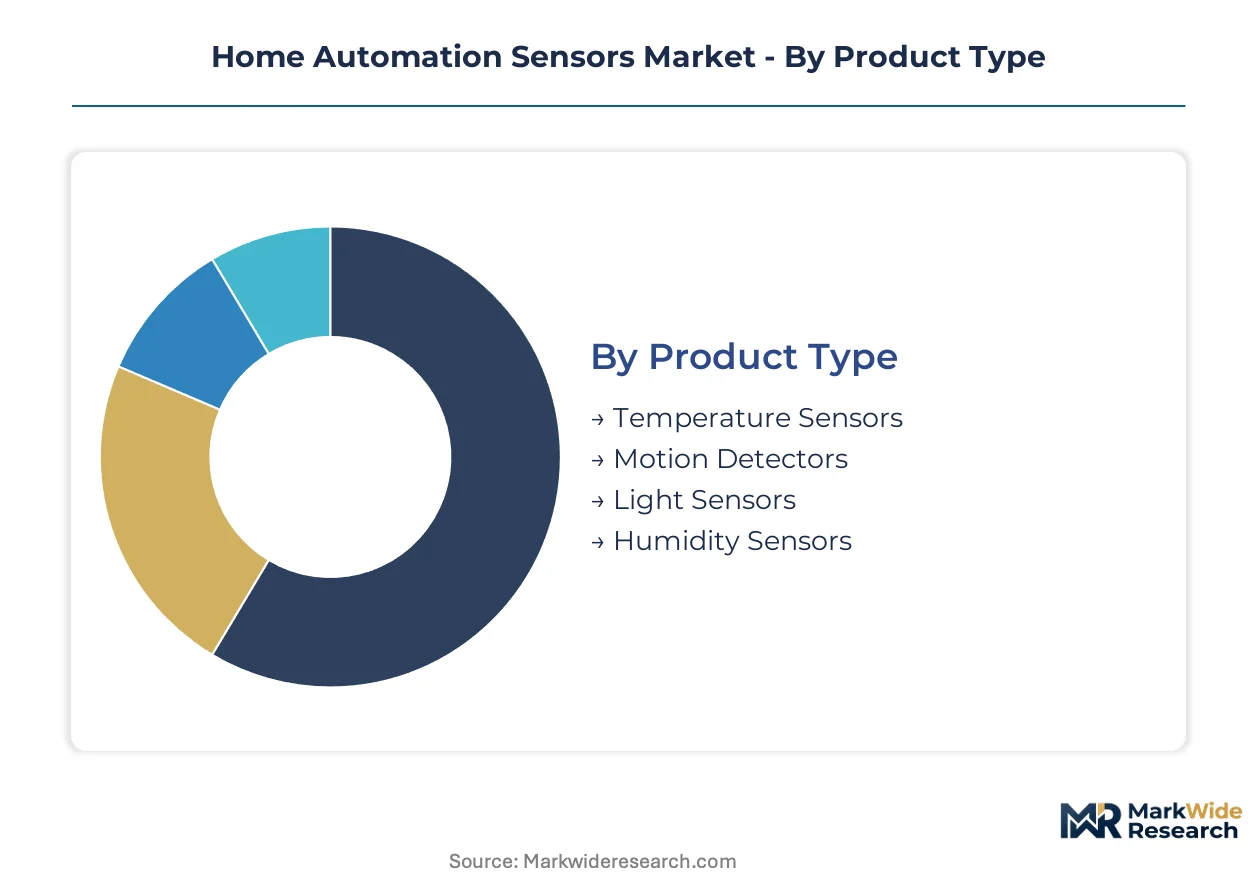
Segmentation in home automation sensors reveals how technical specifications, communication protocols, and deployment contexts reshape procurement patterns and margin structures. Understanding these divides exposes where sensor manufacturers must configure distinct service models and inventory strategies to capture value across divergent buyer requirements.
Product Type:
After-sales service intensity varies sharply across sensor categories, with environmental monitoring devices demanding calibration support and replacement programs that motion detection hardware rarely requires.
- Temperature Sensors:Thermistor and thermocouple-based units measuring thermal gradients for HVAC control systems. Demand clusters in United States residential retrofits where utility rebate programs subsidize smart thermostat bundles, compressing homeowner payback periods to under three years.
- Motion Detectors:PIR and microwave Doppler sensors detecting occupancy through infrared radiation or frequency shift analysis. Commercial building automation in Germany and Japan specifies these for energy code compliance, embedding hardware into mandatory efficiency infrastructure rather than discretionary upgrades.
- Light Sensors:Photodiode and photoresistor modules measuring ambient luminance for automated dimming control.
- Humidity Sensors:Capacitive and resistive polymer film devices tracking relative moisture levels.
Temperature sensors hold the largest share; momentum sits with humidity sensors as wellness-oriented retrofits accelerate replacement cycles.
Technology:
Cost tier stratification separates premium wireless deployments from budget wired installations, with protocol licensing fees and certification overhead driving 40-60% price differentials at equivalent sensing performance.
- Wireless:Zigbee, Z-Wave, Thread, and Wi-Fi-enabled transceivers operating in unlicensed ISM bands. New construction across California and New York mandates these for building electrification compliance, embedding protocol-specific procurement into jurisdictional codes.
- Wired:RS-485, BACnet, and proprietary bus configurations delivering deterministic latency for fire-safety and security networks. Professional integrated systems in commercial buildings specify these where FCC radio emission constraints or reliability requirements override flexibility preferences.
- Infrared:Passive thermal radiation detection for presence sensing and perimeter security.
- Ultrasonic:High-frequency acoustic ranging for occupancy detection in complex spatial geometries.
Wireless configurations dominate new installations; wired technology persists in premium commercial segments where certification friction constrains protocol migration.
End User:
Application context reshapes sensor specification, with residential buyers prioritizing aesthetic integration and commercial purchasers emphasizing API accessibility for building management system integration.
- Residential:Single-family and multi-family dwelling deployments emphasizing plug-and-play installation and mobile app control. United States coastal metropolitan markets concentrate procurement through custom integration firms bundling sensors as subsystems rather than discrete components.
- Commercial:Office, hospitality, and institutional buildings requiring centralized monitoring and multi-tenant access control. Honeywell and Siemens anchor this segment with integrated fire-safety and HVAC sensor networks spanning entire building portfolios.
- Industrial:Manufacturing and warehouse environments demanding ruggedized housings and extended temperature operating ranges.
- Retail:Point-of-sale and inventory management applications leveraging occupancy data for customer flow optimization.
Residential applications command the largest installed base; commercial deployments are expanding most quickly as building electrification mandates embed automation into renovation codes.
Installation:
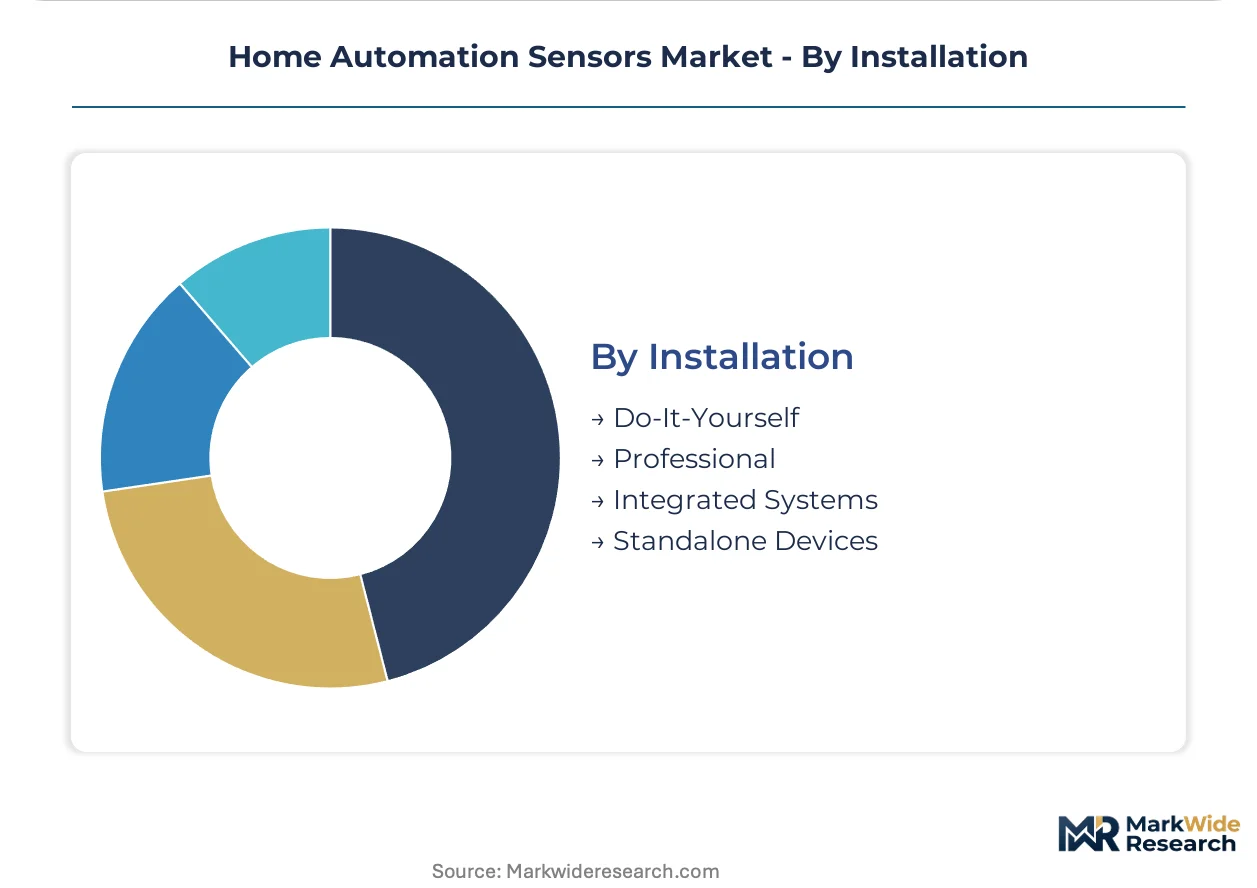
Customer type fragmentation separates DIY consumers seeking $15-40 standalone units from professional integrators specifying $200-500 sensor suites as bundled subsystems with multi-year service contracts.
- Do-It-Yourself:Consumer self-installation of battery-powered or plug-in sensors through retail and e-commerce channels. Matter protocol standardization by the Connectivity Standards Alliance is dissolving interoperability barriers that previously locked DIY buyers into proprietary ecosystems.
- Professional:Certified technician deployment with commissioning and calibration services. Florida and California markets favor this channel where hurricane resilience requirements and building code stringency exceed typical homeowner technical capacity.
- Integrated Systems:Whole-building automation incorporating sensors as embedded components within unified control architectures.
- Standalone Devices:Single-function sensors operating independently without network integration.
Professional installation captures the highest value per unit; DIY channels are gaining share fastest as protocol standardization reduces configuration complexity for non-technical buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision MEMS components to United States residential retrofit contractors, while Taiwan foundries supply silicon wafers to Japanese and Korean sensor assemblers. This trade architecture concentrates value capture in fabrication clusters while distributing finished hardware through North American and European installation channels.
United States
Utility rebate programs in California and New York compress payback periods for smart thermostat bundles below three years. The FCC governs radio frequency emissions from wireless sensor hardware, mandating certification for Zigbee and Thread protocols. Coastal metropolitan markets from Los Angeles to Miami concentrate procurement through custom integration firms bundling sensors as whole-home subsystems.
Germany
Commercial building automation mandates under the EU Energy Performance of Buildings Directive embed motion and environmental sensors into mandatory efficiency infrastructure. REACH compliance requirements shape material selection for polymer film humidity sensors. The Baden-Württemberg industrial corridor around Stuttgart anchors Bosch Sensortec's MEMS fabrication depth for motion sensing modules.
Japan
METI efficiency standards for commercial HVAC systems drive sensor deployment in office and hospitality retrofits. JIS certification requirements for fire-safety networks sustain demand for wired sensor configurations in high-reliability applications. The Chubu region around Nagoya hosts integrated electronics conglomerates controlling semiconductor through appliance manufacturing channels.
China
GB standards for smart home interoperability accelerate domestic protocol consolidation around unified communication stacks. MIIT regulations on radio equipment certification create compliance friction for wireless sensor imports. The Yangtze River Delta manufacturing cluster around Shanghai and Suzhou concentrates assembly capacity for export-oriented environmental sensing modules.
South Korea
Appliance manufacturer vertical integration creates captive demand for temperature and occupancy sensors in smart home ecosystem rollouts. MFDS cybersecurity frameworks for connected devices extend product approval timelines for new market entrants. The Seoul Capital Area anchors Samsung Electronics' control over semiconductor, display, and appliance channels that lock in sensor placement.
Home Automation Sensors Market Competitive Environment
On the supply side, the industry is consolidating around three strategic tiers: diversified electronics conglomerates with captive semiconductor fabrication, specialized MEMS foundries serving multiple end-markets, and professional building automation integrators bundling hardware with multi-year service contracts. Dominant competitive moves include strategic partnerships between sensor manufacturers and protocol standards bodies, plus geographic expansion through certified installer network development in coastal United States markets.
Within the diversified electronics tier, Honeywell International and Siemens AG exemplify integrated building automation providers anchoring commercial fire-safety and HVAC sensor networks. Bosch Sensortec occupies a distinct position as a MEMS fabrication specialist supplying motion and environmental sensing modules across multiple customer channels. Samsung Electronics represents vertical ecosystem control, leveraging in-house semiconductor, display, and appliance manufacturing to secure sensor placement in smart home deployments.
| Leading Market Players |
|---|
| Honeywell International |
| Sony Corp |
| Samsung Electronics |
| Schneider Electric |
| Siemens AG |
| Bosch Sensortec |
| Johnson Controls |
| Lutron Electronics |
| ABB Ltd |
| Others |
Value Chain & Pricing Dynamics
Taiwanese MEMS foundries and German precision component suppliers anchor upstream concentration, feeding margin pools toward professional installation channels in California and Florida where bundled subsystem pricing commands premium positioning over discrete hardware sales.
Pricing Analysis
Current-generation Matter-certified wireless sensors command substantial premiums over prior-generation Zigbee-dominant units and pre-standardization proprietary hardware, while next-generation edge-native devices with TinyML inference capabilities are entering at elevated price points. Pricing stratifies across premium, standard, and economy tiers driven by certification grade (UL/FCC tier differentiation) and after-sales service bundling. Pricing pressure stems from MEMS fabrication scale in Taiwan and Germany compressing unit costs in motion and environmental sensing modules. DIY consumers exhibit highest price sensitivity, seeking standalone units below forty dollars, while commercial building automation purchasers prioritize API accessibility and multi-year service contracts over per-unit cost.
Supply Chain Analysis
Tariff exposure between United States and China dominates supply chain risk assessment for wireless sensor hardware, particularly affecting PCB assemblies and radio frequency modules. Component sourcing draws from Taiwan (silicon wafers), Germany (MEMS fabrication), and South Korea (semiconductor packaging), with rare earth magnet dependencies for magnetometer production creating single-source vulnerability. Distribution runs through professional installer networks in coastal United States markets and custom integration firms bundling sensors as whole-home subsystems, displacing direct-to-consumer retail channels in premium residential segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation across protocol ecosystems, installation channels, and end-user applications creates multiple specialization niches as Matter standardization dissolves interoperability barriers and enables new entrant positioning.
For Market Incumbents: Harden defensive positioning through captive semiconductor fabrication investments in Taiwan or Germany, securing cost leadership against emerging fabless competitors. Deepen Matter certification infrastructure to accelerate cross-vendor compatibility validation, raising quality assurance overhead that disadvantages mid-tier challengers. Prioritize channel control through certified installer network expansion in Florida and California markets where building code stringency favors professional deployment.
For New Entrants and Emerging Players: United States humid continental climate zones present underpenetrated white-space for wellness-oriented humidity and VOC sensor retrofits, where indoor air quality monitoring accelerates replacement cycles. Edge-native processing convergence offers second entry point, combining TinyML models with ultra-low-power microcontrollers for cloud-independent premium positioning. Pursue direct-to-consumer Matter-certified launches targeting DIY buyers in utility rebate program states, compressing payback periods through subsidized smart thermostat bundles.
For Investors and Strategic Acquirers: Capital is best deployed toward MEMS fabrication specialists with established certification infrastructure and multi-protocol engineering depth, positioned to capture volume expansion as building electrification mandates embed sensor demand into jurisdictional codes. Long-term viability over the next decade hinges on cybersecurity compliance capabilities as evolving FCC and European frameworks extend approval timelines. Monitor utility rebate program expansion across additional United States states as inflection indicator for residential retrofit demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Certification | Cross-vendor compatibility validation dissolves ecosystem lock-in and enables new entrant market access. |
| Edge-Native Processing Development | On-device TinyML inference reduces cloud dependency and opens privacy-centric premium positioning. |
| Professional Installer Network Expansion | Channel consolidation in California and Florida captures bundled subsystem procurement authority. |
| MEMS Fabrication Scale Investment | Taiwan and Germany production lines drive unit cost declines in motion sensing modules. |
| Cybersecurity Compliance Infrastructure | FCC and EU Radio Equipment Directive frameworks determine market access before product performance. |
Study Parameters
Desk research of regulatory filings (FCC equipment authorization database, EU Radio Equipment Directive technical documentation), industry association publications (Connectivity Standards Alliance Matter specifications), and customs trade data preceded structured interviews with product managers at MEMS foundries, procurement leads at commercial building automation integrators, and technical directors at protocol standards bodies. Primary fieldwork with certified installation firms in California and Florida markets validated channel dynamics and pricing structures. Secondary validation drew from SEC 10-K disclosures of diversified electronics conglomerates and utility rebate program administrative records. Bottom-up sensor shipment estimates triangulated against top-down building automation market sizing.
Fixed assumptions across the modeling period include sustained Matter protocol adoption trajectory, continued utility rebate program funding in existing states, and stable MEMS fabrication capacity in Taiwan and Germany. Variable assumptions encompass cybersecurity framework expansion timelines and building electrification mandate jurisdictional spread. Segmentation dimensions modeled encompass product type (temperature, motion, humidity, light), technology (wireless protocol, wired configuration), end user (residential, commercial, industrial), and installation channel (DIY, professional, integrated systems). CAGRs derived from regression analysis of historical protocol adoption curves and regulatory mandate implementation patterns, with edge-native processing penetration and wellness-oriented retrofit acceleration as industry-specific demand drivers.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by appliance manufacturers or foundry capacity expansion by emerging Asian competitors would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
North America Pressure Sensors Market
Sensors and Controls
Robotic Sensors Market
Sensors and Controls
Sensor Data Analytics Market
Sensors and Controls
North America Bulk Acoustic Wave Sensors Market
Sensors and Controls
US Temperature Sensors Market
Sensors and Controls
Global Intelligent Flow Meter Market
Sensors and Controls
US Acoustic Sensors Market
Sensors and Controls
Non-Dispersive Infrared Sensing Market
Sensors and Controls
Magnetic Absorption Data Line Market
Sensors and Controls
Smart Hydrophone Market
Sensors and Controls
ECG Sensor Market
Sensors and Controls
Europe Fingerprint Sensor Market
Sensors and Controls
Asia-Pacific CO2 Gas Sensor Market
Sensors and Controls
Electronic Sentry Market
Sensors and Controls
Smart Glove Market
Sensors and Controls
Printed and Flexible Sensors Market