
 Semiconductor Metrology and Inspection Market | 2026-2036
Semiconductor Metrology and Inspection Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Metrology and Inspection Market Outlook
East Asian foundry capital expenditure is consolidating around metrology-intensive process nodes. KLA Corporation leverages its installed base in optical and e-beam platforms to sustain pricing power across leading-edge fabs. Applied Materials, Inc. anchors its process control portfolio through integrated metrology modules embedded in deposition and etch systems. Onto Innovation, Inc. specializes in advanced packaging inspection, differentiating its offerings as chiplet architectures multiply die-interconnect complexity.
Semiconductor metrology and inspection encompasses systems that measure critical dimensions, detect pattern defects, and characterize thin-film properties at nanometer-scale resolution using optical, electron-beam, and X-ray modalities. These tools enable yield management in integrated circuit fabrication by flagging process excursions before they propagate through multi-step manufacturing sequences. Optical inspection dominates current equipment spend due to its throughput advantage over e-beam alternatives, though laser scanning platforms face displacement pressure from multi-beam architectures as node scaling continues. Foundries represent the most concentrated end-user segment, with process control applications generating recurring metrology demand tied to wafer starts rather than one-time tool purchases.
FDA oversight of semiconductor-based medical devices and EPA hazardous substance rules for fabrication chemicals shape equipment qualification protocols in US-based facilities. ISO 9001 and IEC standards govern metrology tool calibration traceability, while REACH compliance in Europe constrains materials used in inspection consumables and cleaning chemistries. Stakeholders must monitor how export control classifications evolve for sub-7nm inspection technologies, as licensing requirements could fragment equipment availability across national fab buildouts.
Market Dynamics
Heterogeneous integration at advanced packaging nodes is forcing metrology vendors to recalibrate tool architectures for chiplets, 3D stacking, and hybrid bonding verification. This structural shift compresses development cycles while expanding addressable tool applications per fab.
Growth Catalysts
- EU Chips Act capital allocation:National semiconductor programs in Germany, France, and Spain are directing public funds toward domestic metrology infrastructure, creating localized procurement windows for equipment vendors.
- Multi-beam electron microscopy:Next-generation e-beam platforms are replacing laser scanning architectures at sub-7nm nodes, sustaining equipment refresh cycles as optical resolution limits harden.
- Medical device semiconductor content:FDA oversight of implantable electronics and diagnostic sensors is tightening wafer-level inspection requirements for US-based foundry customers.
Market Restraints
- Specialized component supply concentration:Precision motion stages and EUV-source metrology subsystems rely on a narrow German and Japanese supplier base, exposing tool builders to single-source fragility.
- Capital intensity threshold:Leading-edge inspection systems require foundry customers to commit $15-50 million per tool installation, freezing out mid-tier fabs from node-competitive yield management.
- E-beam throughput ceiling:Electron-beam modalities remain order-of-magnitude slower than optical alternatives, constraining their deployment to offline sampling despite superior resolution.
Strategic Opportunities
- India semiconductor manufacturing incentives:PLI scheme disbursements and Gujarat Dholera fab commitments are creating greenfield metrology demand without incumbent vendor lock-in.
- X-ray metrology for 3D architectures:Buried feature inspection in hybrid bonding and through-silicon via stacks is opening applications where optical and e-beam modalities fail.
- CE marking alignment with IEC standards:Harmonized calibration traceability requirements across European member states are streamlining multi-country equipment qualification for vendors.
Industry Challenges
- Multi-physics simulation expertise:Tool vendors struggle to hire engineers fluent in electron optics, computational imaging, and machine learning integration simultaneously.
- Legacy fab tool integration:New metrology platforms must communicate with 15-20 year-old MES and APC systems without disrupting running production lines.
- Export classification latency:US Bureau of Industry and Security reviews for sub-7nm inspection technologies are extending sales cycles by 6-12 months for China-bound shipments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Metrology and Inspection Market |
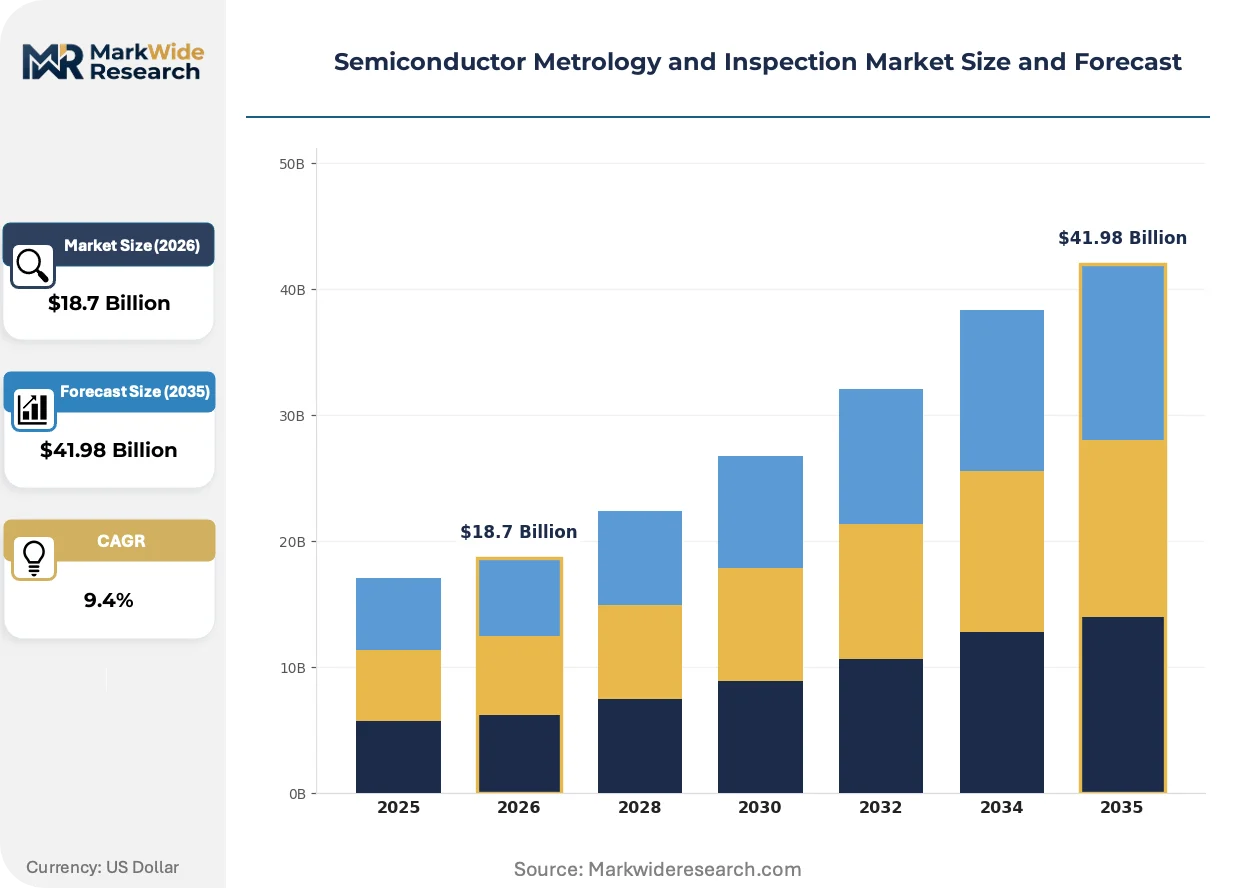
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Inspection, X-Ray Inspection, Metrology, Defect Review Technology: Laser Scanning, E-beam Inspection, QI Testing, Surface Profiling End User: Foundries, IDMs, Fabless Companies, Research Institutions Application: Wafer Inspection, Portfolio Management, Process Control, Final Inspection |
| Companies Covered | KLA Corporation, Applied Materials, Inc., Onto Innovation, Inc., Thermo Fisher Scientific Inc., Hitachi High-Tech Corporation, ASML Holding N.V., Camtek Ltd., Lasertec Corporation, Nova Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Metrology and Inspection Market Strategic Shifts
Computational metrology and AI-augmented defect classification are compressing the feedback loop between measurement and process correction. Equipment architectures are converging toward modular platforms that swap sensing modalities without full tool replacement.
Hybrid optical-electron beam systems are consolidating metrology steps previously requiring separate tools. Foundries in Taiwan and South Korea are deploying these platforms at 3nm and 2nm ramps to reduce wafer handling and cycle time. The consolidation is compressing capital intensity per inspection point while raising software complexity.
REACH compliance in Europe is constraining chemistries used in wafer cleaning and inspection consumables. ECHA substance restrictions are forcing reformulation of photoresist developers and etchant residues that contact metrology samples. German and Dutch fabs are qualifying alternative chemistries ahead of 2025 authorization deadlines, accelerating supplier switching.
Service contract unbundling is separating hardware ownership from algorithm updates and calibration labor. Memory manufacturers in Japan and Korea are piloting subscription-based defect classification models that refresh machine learning weights quarterly. This shift transfers capability risk from buyer to vendor while locking in recurring revenue streams.
Semiconductor Metrology and Inspection Market Segmentation
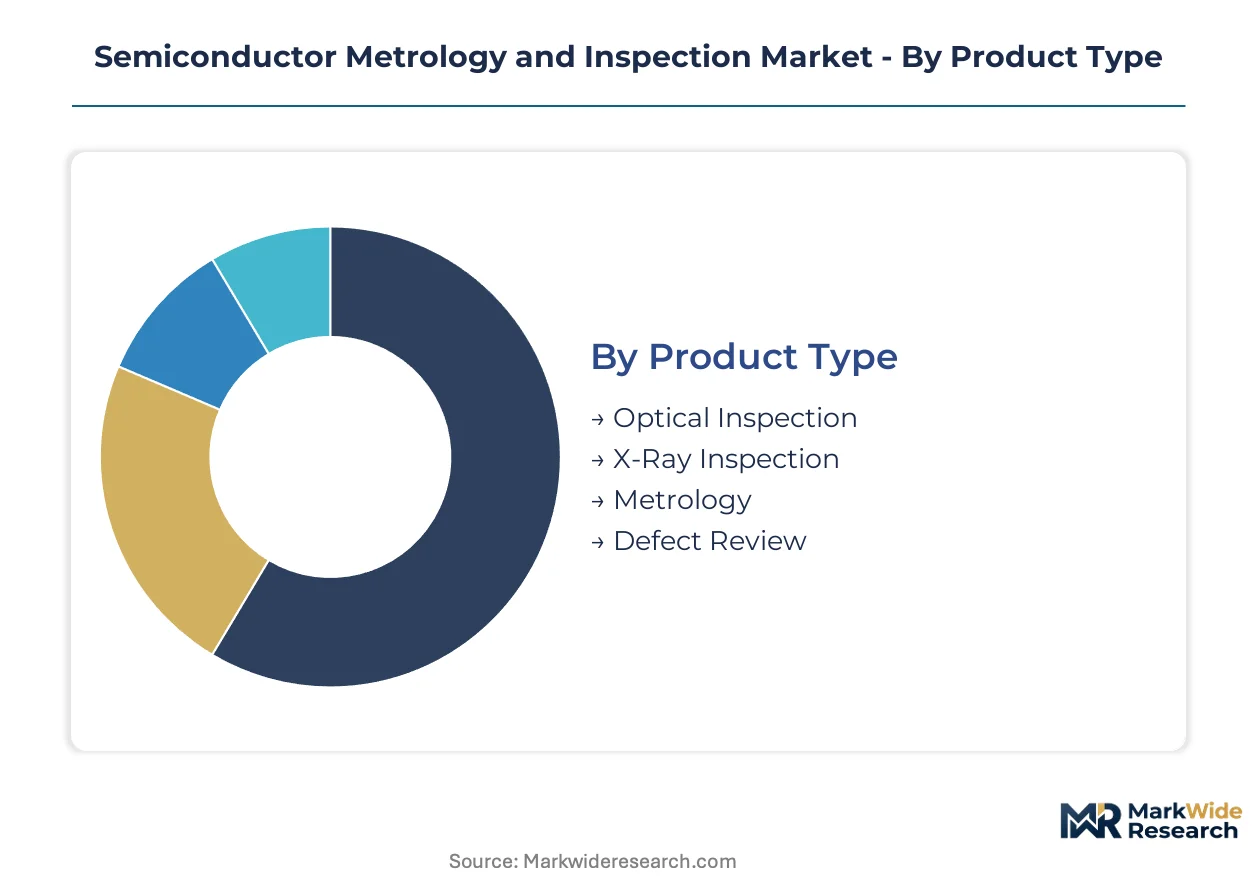
Semiconductor metrology and inspection equipment varies dramatically in capital intensity, throughput, and resolution capability. Buyers select modalities based on node requirements, yield targets, and integration complexity rather than price alone.
Product Type:
Capital allocation patterns separate memory manufacturers pursuing high-throughput optical platforms from logic foundries investing in multi-beam architectures for sub-3nm nodes.
- Optical Inspection:Bright-field and dark-field systems detect pattern defects at wafer-scale throughput using deep-ultraviolet illumination. Taiwan's Science Park corridor concentrates procurement as leading-edge foundries ramp 2nm processes requiring continuous inline monitoring.
- Metrology:Critical dimension scanning electron microscopes and optical scatterometry tools measure nanometer-scale feature geometries. South Korean memory fabs drive demand for overlay metrology as 3D NAND layer counts exceed 200 tiers.
- X-Ray Inspection:Non-destructive imaging penetrates opaque 3D stacks for void detection in hybrid bonding interfaces.
- Defect Review:High-resolution electron microscopy confirms flagged anomalies for root-cause classification.
Volume sits with Optical Inspection; growth tilts toward Metrology.
Technology:
Resolution-throughput tradeoffs dictate technology selection, with electron-beam modalities commanding premium pricing for offline sampling while laser platforms dominate inline deployment.
- E-beam Inspection:Multi-beam architectures overcome single-beam throughput limitations for sub-7nm defect detection. German and Dutch fabs are qualifying these systems ahead of EU Chips Act production targets.
- Laser Scanning:Confocal and interferometric methods map surface topography at production speeds. Japanese memory manufacturers maintain installed bases for planar process monitoring despite displacement pressure at advanced nodes.
- QI Testing:Quantum interference techniques enable picometer-scale displacement measurement for EUV mask qualification.
- Surface Profiling:Stylus and optical profilometers characterize roughness and film thickness for CMP process control.
Revenue concentrates in E-beam Inspection; adoption velocity favors Laser Scanning.
End User:
Procurement scale and technical specification intensity vary sharply between captive manufacturers and merchant foundries serving heterogeneous customer portfolios.
- Foundries:Merchant manufacturers require flexible metrology platforms accommodating diverse customer design rules. Taiwan's pure-play foundries generate recurring tool demand tied to wafer start volumes rather than node transitions alone.
- IDMs:Integrated device manufacturers combine process control with proprietary yield learning systems. Intel's Arizona and Oregon facilities anchor North American demand for advanced packaging inspection.
- Fabless Companies:Design houses rely on foundry partners for metrology access but specify incoming inspection protocols for packaged die.
- Research Institutions:Universities and national laboratories pilot pre-competitive metrology techniques for industry transfer.
Spending dominance belongs to Foundries; specification influence rests with IDMs.
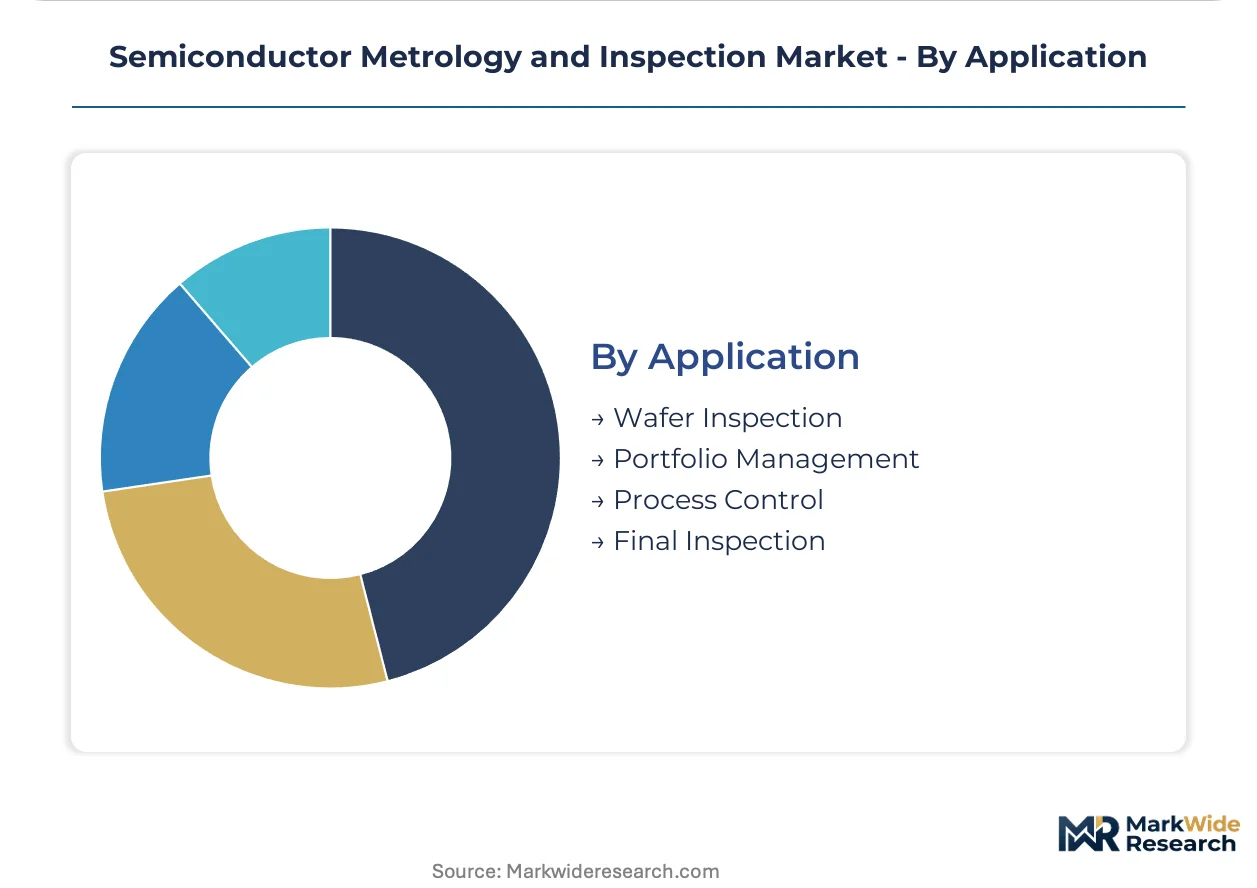
Application:
Process step integration determines whether metrology functions as inline monitoring or offline sampling, with cycle time constraints favoring non-destructive optical methods.
- Wafer Inspection:Patterned and unpatterned wafer screening intercepts defects before further processing commitment. South Korean foundries deploy these systems at every lithography layer for EUV process control.
- Process Control:Statistical process control integration enables automated excursion detection and equipment dispatch. Japanese equipment manufacturers embed metrology modules in deposition and etch chambers for integrated feedback.
- Final Inspection:Pre-ship qualification confirms outgoing wafer quality against customer specifications.
- Portfolio Management:Fleet optimization software allocates metrology capacity across production lines based on yield risk scoring.
Tool population peaks in Wafer Inspection; capability expansion targets Process Control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision optics and Japanese motion control subsystems anchor metrology equipment supply chains. Taiwan's Science Park corridor concentrates foundry demand. South Korean memory complexes and US defense-qualified fabs generate specialized procurement requirements.
Taiwan
Hsinchu Science Park and Southern Taiwan Science Park foundry clusters drive metrology procurement for 2nm and 3nm process ramps. The National Development Council's chip industry incentives under the Asia Silicon Valley Development Plan accelerate capital equipment localization. Tainan's advanced packaging corridor requires hybrid bonding inspection tools for chiplet architectures.
South Korea
Samsung Electronics and SK Hynix fabs in Pyeongtaek and Icheon generate overlay metrology demand for 200+ layer 3D NAND stacks. The K-Chips Act subsidizes domestic metrology infrastructure development through 2030. Seongnam's equipment supplier corridor supplies precision stages to global tool builders.
United States
Intel's Arizona and Oregon facilities anchor North American demand for advanced packaging inspection. FDA oversight of semiconductor-based medical devices tightens wafer-level qualification protocols. Albany Nanotech Complex in New York pilots EUV mask metrology for defense-qualified supply chains.
Germany
Dresden's Silicon Saxony cluster qualifies multi-beam e-beam systems for sub-7nm production under EU Chips Act funding. ECHA REACH compliance deadlines force chemistry reformulation for wafer cleaning consumables. Munich-area precision motion stage suppliers face capacity constraints from single-source fragility.
Japan
Japanese memory manufacturers in Hiroshima and Yokkaichi maintain laser scanning inspection bases for planar process monitoring. METI's semiconductor revitalization program directs subsidies toward domestic metrology tool development. Nagoya's precision equipment corridor supplies EUV-source metrology subsystems.
Semiconductor Metrology and Inspection Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue advanced packaging specialization and AI-augmented defect classification. The vendor base consolidates around three capability clusters: optical platform generalists, electron-beam resolution specialists, and packaging-focused niche players. Competitive positioning depends on installed base leverage, software algorithm differentiation, and service contract bundling strategies. M&A activity targets machine learning teams and multi-beam electron optics capabilities.
Within the optical inspection tier, KLA Corporation and Applied Materials, Inc. exemplify platform breadth strategies. Onto Innovation, Inc. occupies a specialist position in advanced packaging applications. These three companies represent contrasting archetypes: the diversified process control conglomerate, the integrated deposition-metrology hybrid, and the packaging-pure-play respectively.
| Leading Market Players |
|---|
| KLA Corporation |
| Applied Materials, Inc. |
| Onto Innovation, Inc. |
| Thermo Fisher Scientific Inc. |
| Hitachi High-Tech Corporation |
| ASML Holding N.V. |
| Camtek Ltd. |
| Lasertec Corporation |
| Nova Ltd. |
| Others |
Value Chain & Pricing Dynamics
Precision motion stage components from German and Japanese suppliers cascade through three pricing tiers as they reach tool builders, with EUV-source metrology subsystems commanding premium positioning against standard optical platform configurations.
Pricing Analysis
Service contract unbundling separates hardware ownership from algorithm updates and calibration labor, with memory manufacturers in Japan and Korea piloting subscription-based defect classification models. Pricing stratifies across premium multi-beam architectures, standard laser scanning platforms, and economy-grade optical systems based on resolution capability and throughput specifications. Cost compression in standard optical tiers intensifies as Chinese tool builders enter mid-range wafer inspection segments. Fabless design houses exhibit highest price sensitivity due to indirect metrology access through foundry partners, while leading-edge foundries prioritize capability over unit cost.
Supply Chain Analysis
Refurbished electron-beam platforms and certified pre-owned optical systems flow back through authorized service channels in Taiwan and South Korea, extending asset lifecycles for memory manufacturers. Supply concentration rests on German precision optics, Japanese motion control stages, and Taiwanese foundry demand clusters. Critical dependencies include EUV-source metrology subsystems, precision granite structures, and deep-ultraviolet illumination modules. Single-source vulnerability in precision motion stages exposes tool builders to allocation constraints. Distribution runs through direct OEM sales teams for leading-edge fabs and regional equipment distributors for legacy node customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race, with players pursuing captive control over precision motion stage production to defend margin structure against supply allocation risks.
For Market Incumbents: Acquire multi-beam electron optics capabilities to preempt displacement of laser scanning architectures at sub-7nm nodes. Secure long-term supply agreements with Japanese precision stage suppliers before capacity constraints harden, and embed machine learning defect classification modules directly into deposition and etch systems to lock in process control integration. For New Entrants and Emerging Players: Mid-tier analog and power semiconductor fabs in India and Southeast Asia represent underserved buyer archetypes lacking node-competitive yield management tools. Target greenfield fab buildouts under India's PLI scheme with packaged metrology solutions combining hardware and subscription-based algorithm updates, bypassing incumbent installed base advantages through capability-risk transfer pricing models. For Investors and Strategic Acquirers: Export license approval delays for sub-7nm inspection technologies bound for China are the leading indicator that regional supply chain fragmentation is accelerating. Position portfolios around equipment vendors with diversified manufacturing footprints across Taiwan, South Korea, and the United States, and monitor Bureau of Industry and Security classification reviews as early signals of market access restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Beam Electron Optics Acquisition | Secures resolution leadership as KLA Corporation and Applied Materials displace laser scanning at sub-7nm nodes. |
| India Greenfield Fab Partnership | Captures PLI-subsidized procurement windows before incumbent vendor lock-in solidifies at Gujarat Dholera. |
| Service Contract Unbundling | Transforms revenue streams for memory manufacturers in Japan and Korea through quarterly ML model refreshes. |
| REACH-Compliant Chemistry Reformulation | Qualifies alternative photoresist developers ahead of ECHA authorization deadlines at German and Dutch fabs. |
| Hybrid Optical-E-Beam Platform Launch | Consolidates metrology steps for Taiwan foundries ramping 2nm processes with reduced wafer handling. |
Study Parameters
Document review covered SEC 10-K filings from equipment vendors, EU Chips Act implementation documents, and ECHA REACH authorization timelines, complemented by interviews with fab process control engineers, metrology tool procurement managers, precision optics manufacturing executives, and semiconductor industry analysts. Secondary sources included customs trade data for precision stage imports, SEMI equipment market statistics, and national semiconductor program disbursement records. Bottom-up wafer start projections were triangulated against top-down capital expenditure forecasts.
Historical equipment shipment patterns were cross-referenced against panel input from foundry capital planning teams to derive growth trajectories across the projection horizon. Segmentation modeling incorporated product type, technology modality, end-user archetype, and application process step. CAGRs were derived from regression analysis of capital intensity per inspection point and node transition timelines. Industry-specific inputs included EUV adoption curves, 3D NAND layer count trajectories, and chiplet architecture penetration rates.
Revisions become necessary when export control classifications shift, EU Chips Act disbursement schedules slip, or precision stage supplier capacity constraints materialize. Forecasts reflect assumptions about heterogeneous integration complexity and multi-beam throughput improvements. Practitioners should monitor Bureau of Industry and Security licensing delays, ECHA substance restriction timelines, and German precision equipment order backlogs for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Sound Meter Market
Test and Measurement
Glow Wire Test Apparatus Market
Test and Measurement
Semiconductor Bond Testing Market
Test and Measurement
Anechoic Chamber Market
Test and Measurement
Ultrasonic Thickness Gauge Market
Test and Measurement
Liquid Immersion Cooling Fluid Compatibility Test Equipment Market
Test and Measurement
Gigabit Ethernet Test Equipment Market
Test and Measurement
Vibration Analyzer Market
Test and Measurement
Resonant Testing Machines Market
Test and Measurement
3D Automatic Optical Inspection Machine Market
Test and Measurement
Europe NDT Equipment Market
Test and Measurement
Modular Test Equipment Market
Test and Measurement
Global General Purpose Test Equipment (GPTE) Market
Test and Measurement
Active Dosimeter Market
Test and Measurement
Digital Depth Gauges Market
Test and Measurement
Photometer and Calorimeter Market