
 Aspiration Control Systems Market | 2026-2036
Aspiration Control Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Aspiration Control Systems Market Analysis
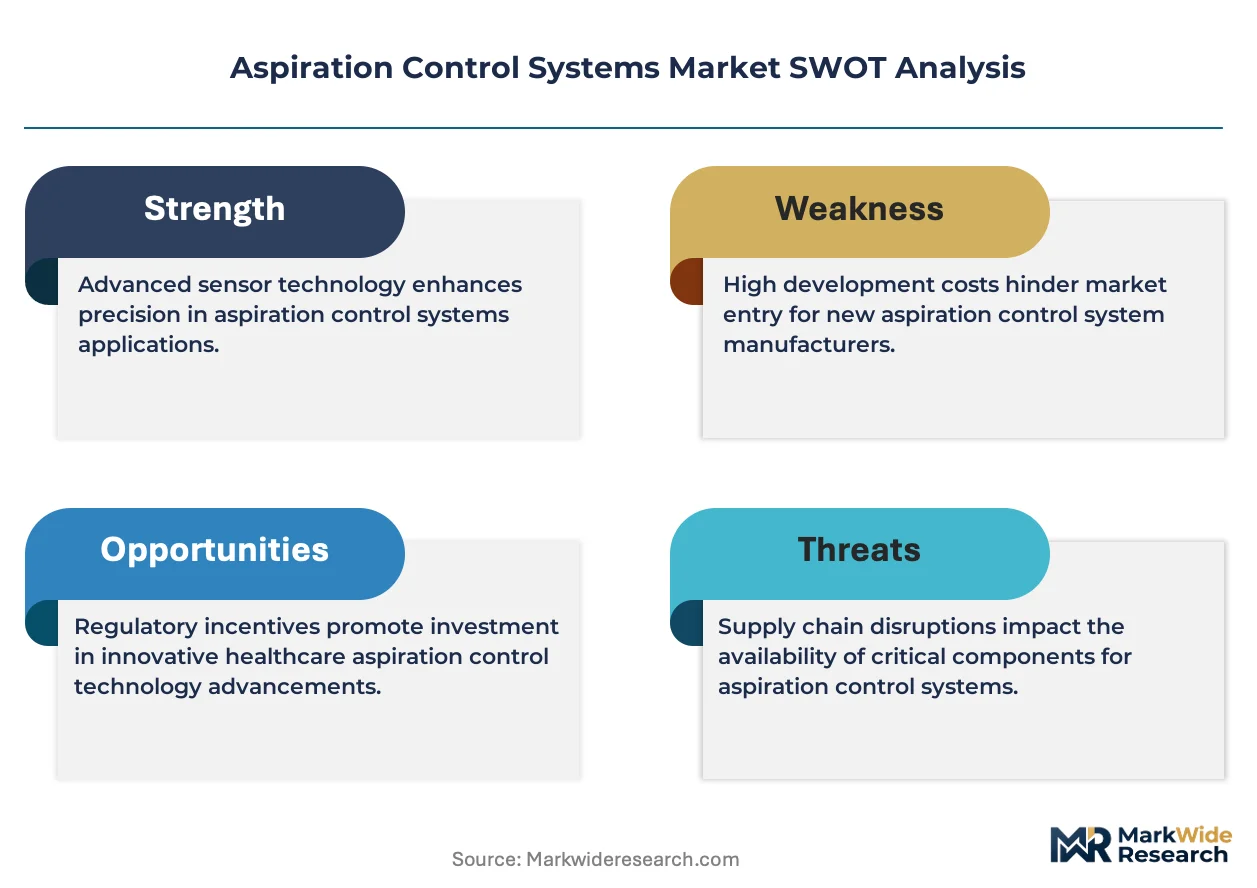
Healthcare facilities are unwinding decades of reliance on manual suction devices as automated and smart aspiration platforms gain procurement priority. Siemens sustains technology leadership through digital integration across hospital infrastructure, while Honeywell dominates industrial-grade pneumatic architectures with manufacturing scale that spans multiple continents. Parker Hannifin anchors the precision fluidics segment with specialized diaphragm pump engineering for contamination-sensitive environments.
Aspiration control systems encompass vacuum generation, pressure modulation, and fluid separation equipment designed to extract gases, liquids, or particulates with precision flow rates typically spanning 0.1 to 150 liters per minute. These systems serve critical functions in surgical theaters, environmental sampling stations, and analytical laboratories where uncontrolled fluid movement compromises sterility or measurement integrity. Automated systems command the largest installed base among product types, though smart systems embedding real-time pressure feedback and predictive maintenance algorithms represent the fastest-expanding margin pool. Digital solutions within the technology dimension are displacing legacy pneumatic architectures in research laboratories, while medical procedures remain the most structurally defended application segment due to reimbursement-linked procurement cycles.
The FDA's Quality System Regulation and the EU Medical Device Regulation impose divergent clinical evidence and post-market surveillance obligations that fragment product development roadmaps for manufacturers serving both jurisdictions. OSHA's bloodborne pathogens standard and ISO 14644 cleanroom classifications further shape specifications for healthcare and laboratory deployments. Stakeholders must monitor how cybersecurity mandates from the FDA and emerging AI validation requirements from the EU AI Act reshape the competitive bar for smart system certification.
Market Dynamics
Healthcare procurement teams are consolidating vendor relationships around platforms that integrate aspiration control with broader hospital automation ecosystems, compressing the addressable supplier base while elevating technical certification requirements.
Growth Catalysts
- EU MDR clinical evidence mandates:Stricter post-market surveillance obligations for Class IIa and IIb medical devices are forcing product refresh cycles that favor modular, upgradeable aspiration architectures over fixed-configuration legacy units.
- Laboratory automation integration:Analytical laboratories are embedding aspiration modules directly into liquid handling workstations, expanding addressable unit volume beyond standalone device replacement cycles.
- OSHA bloodborne pathogen enforcement:Healthcare facilities in the United States face intensified inspection protocols for suction equipment sterility assurance, accelerating capital deployment toward closed-system aspiration designs.
Market Restraints
- Precision diaphragm supply concentration:Specialized elastomer manufacturing for contamination-resistant pump components clusters in southern Germany and northern Switzerland, creating single-source vulnerability for diaphragm-dependent system architectures.
- EU F-Gas Regulation phase-down:Restrictions on fluorinated greenhouse gases used in certain vacuum pump cooling circuits are forcing refrigerant transitions that extend engineering validation timelines by 12-18 months.
- Manual suction device residual installed base:Decades of capital depreciation in emerging market healthcare facilities sustains demand for consumable tubing and canister replacements rather than full system upgrades.
Strategic Opportunities
- India CDSCO manufacturing incentives:Production-linked incentive schemes for medical devices are attracting component assembly investments that could reposition South Asia as an export hub for aspiration system subassemblies.
- Predictive maintenance algorithm deployment:Machine learning models trained on pressure signature anomalies are enabling subscription-based service revenue streams that decouple manufacturer economics from hardware shipment cycles.
- Environmental sampling station retrofit:Air quality monitoring networks across East Asia require portable aspiration units with calibrated flow rates, opening a specification-driven segment distinct from medical procurement patterns.
Industry Challenges
- Cybersecurity validation for FDA premarket submission:Smart aspiration systems with networked pressure monitoring must demonstrate threat modeling and patch management protocols that most legacy engineering teams lack in-house.
- ISO 14644 cleanroom integration complexity:Pharmaceutical manufacturing deployments require aspiration equipment that maintains particulate classification during operation, demanding custom housing designs that fragment production economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aspiration Control Systems Market |
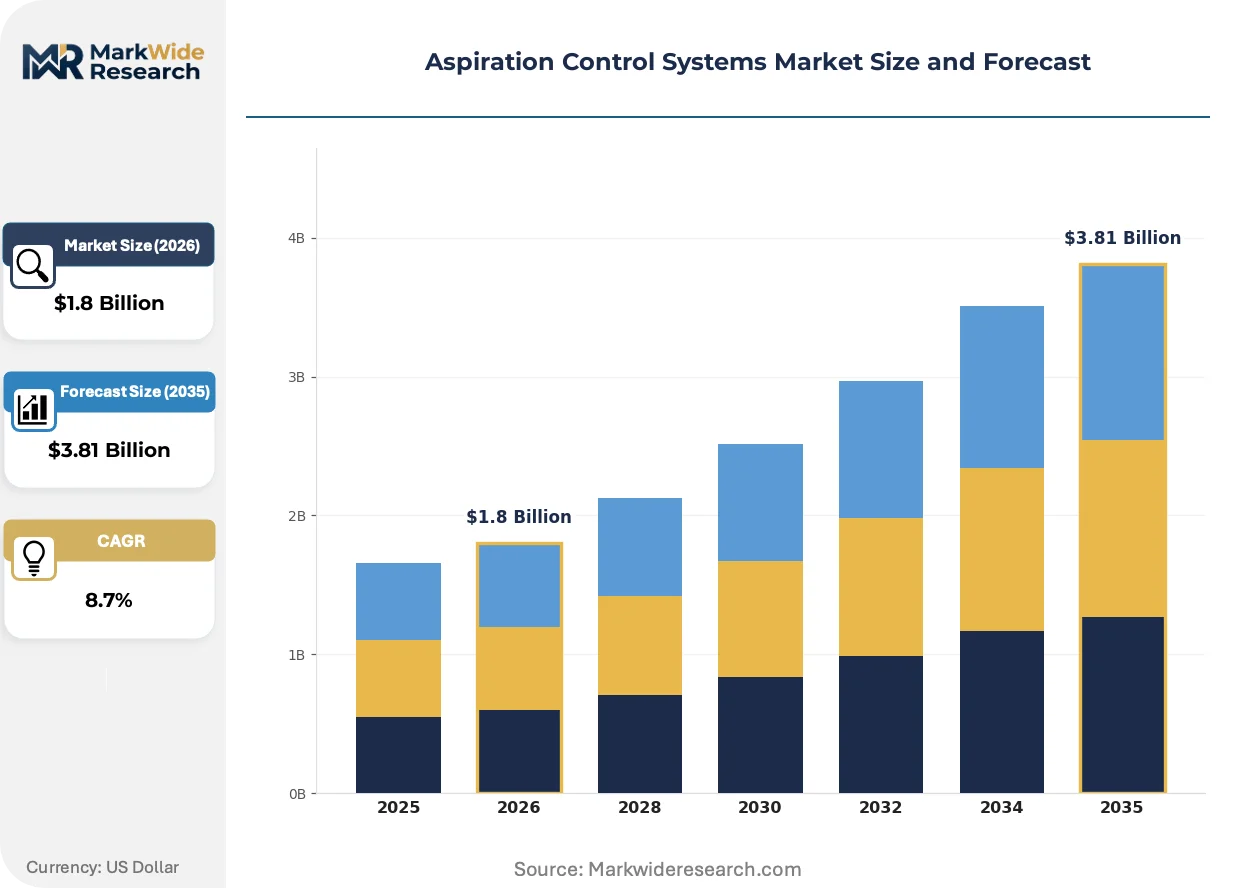
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Systems, Automated Systems, Hybrid Systems, Smart Systems End User: Healthcare Facilities, Industrial Operations, Research Laboratories, Commercial Establishments Technology: Pneumatic Solutions, Electrical Solutions, Mechanical Solutions, Digital Solutions Application: Medical Procedures, Environmental Monitoring, Laboratory Use, Waste Management |
| Companies Covered | Honeywell, Siemens, Parker Hannifin, General Electric, Penumbra, Medtronic, Abbott, VACUUBRAND GMBH + CO KG, INTEGRA Biosciences AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aspiration Control Systems Market Emerging Trajectories
Digital pressure sensing architectures are fragmenting the traditional boundary between pneumatic hardware and software-defined control, enabling real-time flow modulation that was previously mechanically impossible.
MEMS-based pressure transducers with sub-millibar resolution are fragmenting the incumbent sensor supply chain. Research laboratories in Germany and Switzerland are adopting these solid-state alternatives for chromatography and mass spectrometry front-ends. The shift compresses calibration intervals from quarterly to annual while enabling cloud-connected diagnostic pipelines that incumbent analog sensor vendors cannot match.
The EU AI Act's risk classification framework for medical device software is fragmenting product development roadmaps. Manufacturers must now document algorithmic transparency and post-deployment monitoring for aspiration systems with automated pressure adjustment. Surgical equipment portfolios face the steepest compliance burden, with several German and French suppliers accelerating in-house regulatory affairs hiring to maintain market access.
Consolidated procurement through regional hospital networks is fragmenting traditional distributor relationships. Large health systems in the United States and France are negotiating direct manufacturer contracts for aspiration platforms bundled with multi-year service agreements. This disintermediation compresses channel margins while elevating technical support capabilities to a primary competitive discriminator in vendor selection processes.
Aspiration Control Systems Market Segmentation
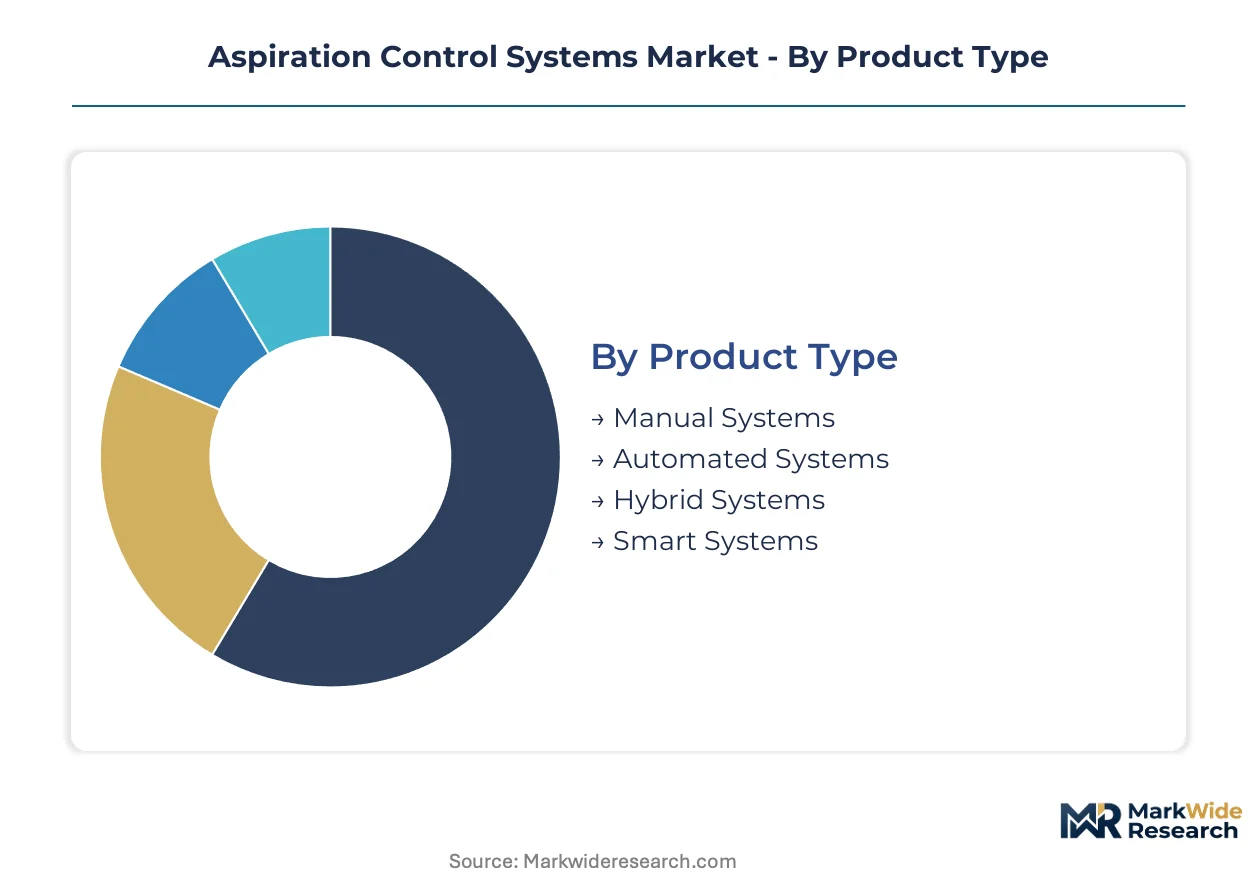
Aspiration control systems fragment across four intersecting dimensions that determine procurement channels, certification burdens, and service revenue potential. Product architecture and end-user environment together dictate whether units flow through medical device distributors, industrial supply houses, or direct manufacturer contracts.
Product Type:
Automated and smart systems increasingly bypass traditional distribution, reaching healthcare facilities through integrated platform procurement while manual units persist in emerging markets via consumable-replacement channels.
- Automated Systems:Vacuum generation and pressure modulation execute through programmable logic controllers without operator intervention. Demand concentrates in surgical theaters across Germany and the United States where OSHA bloodborne pathogen enforcement mandates closed-system designs. These units anchor the largest installed base and generate recurring calibration service revenue.
- Smart Systems:Real-time pressure feedback loops and predictive maintenance algorithms embed machine learning models trained on operational signatures. Research laboratories in Switzerland and analytical facilities in France are adopting these platforms fastest, driven by EU AI Act documentation requirements that favor systems with built-in algorithmic transparency.
- Manual Systems:Hand-operated suction devices with basic vacuum generation persist in price-sensitive procurement environments.
- Hybrid Systems:Semi-automated architectures blend manual override with electronic pressure monitoring for flexible deployment.
By volume, automated systems lead. By growth pace, smart systems are climbing the fastest.
End User:
Cost tier stratification separates capital-intensive healthcare procurement from specification-driven laboratory purchasing and price-sensitive industrial replacement cycles.
- Healthcare Facilities:Hospitals and surgical centers demand FDA-cleared or CE-marked devices with validated sterility assurance. Consolidated procurement through regional networks in France and the United States compresses the supplier base while elevating multi-year service contract requirements.
- Research Laboratories:Analytical and pharmaceutical facilities require ISO 14644-compliant designs with particulate containment during operation. Germany's chromatography and mass spectrometry clusters drive specification intensity here.
- Industrial Operations:Manufacturing environments prioritize pneumatic reliability and maintenance accessibility over precision sensing.
- Commercial Establishments:Dental clinics and outpatient facilities balance clinical necessity against capital budget constraints.
Healthcare facilities command the highest average selling prices. Research laboratories show the steepest technology refresh rates.
Technology:
Application context determines whether pneumatic legacy architectures, electrical precision platforms, or digitally native solutions win specification.
- Digital Solutions:MEMS-based pressure transducers with sub-millibar resolution enable cloud-connected diagnostic pipelines. These architectures are displacing analog alternatives in German and Swiss research laboratories where annual calibration intervals replace quarterly schedules.
- Pneumatic Solutions:Compressed air-driven vacuum generation dominates industrial waste management and environmental sampling where electrical isolation matters.
- Electrical Solutions:Motor-driven diaphragm pumps serve medical procedures requiring precise flow rate control across variable load conditions.
- Mechanical Solutions:Simple piston and rotary vane designs persist in cost-constrained manual device categories.
Pneumatic solutions retain the broadest geographic footprint. Digital solutions are gaining share fastest in regulated laboratory environments.
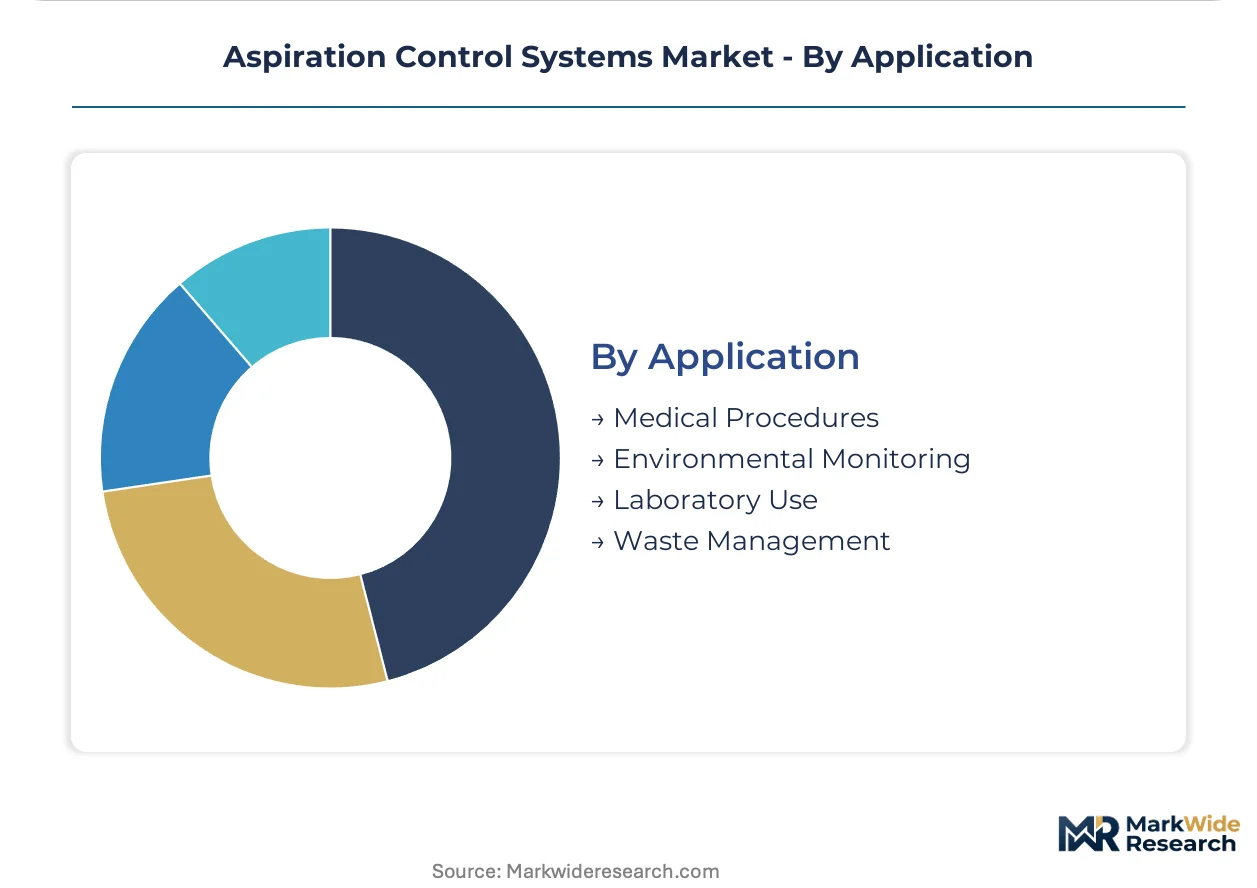
Application:
Margin structure diverges sharply between reimbursement-linked medical procurement and project-based environmental monitoring deployments.
- Medical Procedures:Surgical suction and fluid extraction carry the most structurally defended demand due to FDA and EU MDR certification requirements that lock in approved vendors. Reimbursement codes in the United States and Germany create procurement predictability.
- Environmental Monitoring:Air quality sampling stations across East Asia require portable aspiration units with calibrated flow rates. This specification-driven segment follows public infrastructure budgets rather than clinical procurement patterns.
- Laboratory Use:Liquid handling and sample preparation integrate aspiration modules into automated workstations.
- Waste Management:Industrial fluid and particulate extraction operates on replacement cycles tied to manufacturing output.
Medical procedures generate the most stable recurring revenue. Environmental monitoring shows the most volatile project-based demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision diaphragm pump components to Swiss analytical laboratories and French surgical equipment manufacturers, anchoring the primary trade-flow corridor for aspiration control technology.
United States
Healthcare procurement consolidation through regional hospital networks drives specification intensity for FDA-cleared aspiration platforms. OSHA bloodborne pathogen enforcement accelerates capital deployment toward closed-system designs. The Greater Boston biotech cluster embeds aspiration modules into automated liquid handling workstations.
Germany
Chromatography and mass spectrometry laboratories in southern Germany demand MEMS-based pressure transducers with sub-millibar resolution. EU MDR clinical evidence mandates force modular, upgradeable architectures over fixed-configuration legacy units. VACUUBRAND and INTEGRA Biosciences anchor laboratory and surgical suction supply chains in the Baden-Württemberg precision manufacturing belt.
Switzerland
Research laboratories adopt smart aspiration systems with predictive maintenance algorithms fastest among European markets. Swissmedic certification requirements for Class IIa medical devices elevate documentation burdens for automated pressure adjustment features. Basel's pharmaceutical manufacturing corridor requires ISO 14644-compliant aspiration equipment with particulate containment during operation.
France
Consolidated procurement through regional hospital networks compresses the supplier base while elevating multi-year service contract requirements. ANSM post-market surveillance obligations for surgical equipment accelerate regulatory affairs hiring among domestic suppliers. The Paris-Saclay research cluster drives specification intensity for cloud-connected diagnostic pipelines in analytical applications.
India
CDSCO production-linked incentive schemes for medical devices attract component assembly investments for aspiration system subassemblies. Manual suction device residual installed base sustains demand for consumable tubing and canister replacements rather than full system upgrades. Maharashtra's medical device manufacturing corridor positions South Asia as an emerging export hub for precision pump components.
Aspiration Control Systems Market Vendor Landscape
Listed leaders compete with private specialists across certification intensity and service contract bundling. The market structures around three tiers: diversified industrial conglomerates with hospital automation ecosystems, precision fluidics specialists with diaphragm engineering heritage, and medical device pure-plays with reimbursement-linked procurement relationships. Dominant competitive moves include direct manufacturer contracts disintermediating traditional distributors and predictive maintenance algorithm deployment enabling subscription-based service revenue.
Among diversified industrial conglomerates, Honeywell and Siemens exemplify scale-driven positions spanning pneumatic architectures and digital hospital infrastructure. Parker Hannifin occupies a specialist tier with precision fluidics engineering for contamination-sensitive environments. VACUUBRAND GMBH + CO KG and INTEGRA Biosciences AG represent private European specialists with concentrated presence in laboratory and surgical suction supply chains. Penumbra and Medtronic anchor the medical device pure-play tier where FDA premarket submission capabilities and reimbursement code alignment determine competitive access.
| Leading Market Players |
|---|
| Honeywell |
| Siemens |
| Parker Hannifin |
| General Electric |
| Penumbra |
| Medtronic |
| Abbott |
| VACUUBRAND GMBH + CO KG |
| INTEGRA Biosciences AG |
| Others |
Supply Flow & Price Mechanics
Eighteen-month engineering validation timelines for refrigerant transitions under EU F-Gas Regulation phase-down rules compress supplier pricing power while elongating procurement cycles for healthcare facilities seeking closed-system aspiration designs.
Pricing Analysis
Next-generation smart systems with predictive maintenance algorithms command 40-60% premia over automated platforms, while manual suction devices face persistent price erosion in emerging markets where consumable replacement cycles dominate procurement. Pricing stratifies across premium, standard, and economy tiers based on FDA/CE certification grade and multi-year service bundling. Cost compression in the manual device tier intensifies because decades of capital depreciation in India and Southeast Asia sustain demand for tubing and canister replacements rather than full system upgrades. Research laboratories in Germany and Switzerland show the least price sensitivity due to EU AI Act documentation requirements that favor algorithmically transparent platforms.
Supply Chain Analysis
Germany and Switzerland anchor precision diaphragm pump component manufacturing, with southern German elastomer specialists feeding contamination-resistant pump assemblies to Swiss analytical laboratories and French surgical equipment producers. Specialized fluoropolymer membranes and medical-grade silicone diaphragms draw from concentrated chemical processing corridors in the Baden-Württemberg precision manufacturing belt. Single-source vulnerability for diaphragm-dependent architectures intensifies as regional hospital network consolidation compresses the approved vendor base. Distribution runs through medical device distributors for FDA-cleared platforms, direct manufacturer contracts for integrated hospital automation ecosystems, and industrial supply houses for pneumatic waste management applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR clinical evidence mandates and FDA cybersecurity guidance are forcing product refresh cycles that favor modular, upgradeable aspiration architectures over fixed-configuration legacy units.
For Market Incumbents: Shield installed base relationships by accelerating in-house regulatory affairs hiring to manage EU AI Act algorithmic transparency documentation for smart systems with automated pressure adjustment. Deepen backward integration into MEMS-based pressure transducer supply chains to secure sub-millibar resolution components that cloud-connected diagnostic pipelines require. Defend against disintermediation by elevating technical support capabilities to primary competitive discriminator status in direct manufacturer contract negotiations with regional hospital networks.
For New Entrants and Emerging Players: Lead with environmental sampling station retrofits across East Asian air quality monitoring networks, where calibrated flow rate specifications create procurement patterns distinct from reimbursement-linked medical device channels. Target India's CDSCO production-linked incentive corridor for precision pump component assembly, leveraging Maharashtra's medical device manufacturing infrastructure to establish South Asian export hub positioning. Pursue subscription-based service revenue models that decouple economics from hardware shipment cycles through predictive maintenance algorithm deployment.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to divest non-core precision fluidics divisions amid healthcare automation platform consolidation. Five-to-ten-year viability hinges on regulatory certification asset durability rather than manufacturing scale alone. Watch for accelerated EU MDR post-market surveillance obligation enforcement as the signal indicating which modular architecture suppliers will capture surgical equipment procurement consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Modular Architecture Development | Stricter clinical evidence mandates force upgradeable designs over fixed-configuration legacy units. |
| MEMS Pressure Transducer Backward Integration | Solid-state alternatives displace analog sensors in German chromatography and mass spectrometry clusters. |
| Predictive Maintenance Algorithm Deployment | Machine learning models enable subscription revenue streams decoupled from hardware shipment cycles. |
| CDSCO Manufacturing Incentive Capture | Production-linked schemes reposition South Asia as export hub for aspiration system subassemblies. |
| Hospital System Direct Contract Negotiation | Consolidated procurement through regional networks disintermediates traditional distributor relationships. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR technical documentation databases, and hospital procurement contract registries. Conversations with biomedical engineers, GPO contracts managers, surgical equipment procurement directors, and regulatory affairs specialists at German and Swiss manufacturers inform demand-side validation. SEC 10-K disclosures from listed industrial conglomerates and customs trade data for precision pump component flows provide supply-side triangulation. Bottom-up unit economics and top-down macro healthcare expenditure trajectories converge in final market sizing.
Segmentation dimensions modeled span product architecture, end-user environment, technology generation, and application context across the projection horizon. Automated, smart, manual, and hybrid system categories intersect with healthcare facility, research laboratory, industrial operation, and commercial establishment procurement patterns. Digital, pneumatic, electrical, and mechanical technology tiers further fragment the addressable market. CAGRs derive from installed base replacement cycles, EU MDR-mandated refresh timelines, and laboratory automation integration penetration curves.
The analysis sits within stated boundaries; outcomes outside sustained FDA cybersecurity enforcement intensity or accelerated EU F-Gas refrigerant phase-down schedules would require recalibration. Forecasts reflect assumptions around regional hospital network consolidation velocity and MEMS sensor cost-down trajectories. Recalibration cycles align with material shifts in EU AI Act implementation guidance and CDSCO manufacturing incentive scheme revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Semiconductor Pyrometers Market
Sensors and Controls
Fluid Sensors Market
Sensors and Controls
Specialty Control Plasma Market
Sensors and Controls
Current Calibrator Market
Sensors and Controls
North America Sensor Market
Sensors and Controls
Aton Management and Monitoring System Market
Sensors and Controls
Europe MEMS and Sensors Market
Sensors and Controls
Inertial Measurement Unit (IMU) Market
Sensors and Controls
Quantum Sensors Market
Sensors and Controls
Digital Barometer Market
Sensors and Controls
United States Scintillator Market
Sensors and Controls
Global PH Sensor Market
Sensors and Controls
Earthquake Sensor Market
Sensors and Controls
Global MEMS and Sensors Market
Sensors and Controls
Global Capacitive Sensor Market
Sensors and Controls
Machine Control System Market