
 Battery Free Sensor Market | 2026-2036
Battery Free Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Free Sensor Market Intelligence
Compliance with the EU's Radio Equipment Directive (RED) for CE marking is collapsing the distinction between niche and mainstream suppliers. This framework mandates stringent testing for wireless devices, favoring established players with deep regulatory expertise. Texas Instruments leverages its extensive semiconductor portfolio to offer integrated, pre-certified modules. In contrast, EnOcean GmbH specializes in energy harvesting wireless technology for smart buildings, while Infineon Technologies competes on the basis of its security and power management components for connected devices.
Battery-free sensors are electronic devices that operate by harvesting ambient energy from sources like radio waves, heat, light, or vibrations. They typically integrate an energy transducer with an ultra-low-power microcontroller to function without a conventional power source. Their primary purpose is to enable long-term, zero-maintenance data collection for IoT applications. Radio Frequency Identification (RFID) sensors continue to lead in volume, while Piezoelectric and Thermoelectric sensors are gaining traction in industrial automation and structural health monitoring applications.
Regulatory frameworks directly influence device design and market access. In the United States, the FCC sets strict limits on radio frequency emissions, while the EU's RoHS directive restricts the use of specific hazardous materials in electronics. Concurrently, government-led initiatives, such as Japan's METI-driven push for smart factories, create significant demand pulls. Future success depends on developing solutions that conform to a fragmented spectrum allocation landscape while ensuring interoperability across major IoT platforms.
Market Dynamics
The central dynamic in the battery-free sensor market is the tension between the push for standardized communication protocols, driven by large-scale IoT deployments, and the persistent need for highly customized energy harvesting solutions tailored to specific operating environments.
Growth Catalysts
- Industrial IoT Initiatives:Government-backed programs, including Germany's Industry 4.0 and Japan's METI-led push for smart factories, create direct demand for predictive maintenance sensors in manufacturing.
- LPWAN Proliferation:The expanding coverage of Low-Power Wide-Area Networks enables cost-effective, long-range data transmission from battery-free sensors, unlocking applications in smart agriculture and logistics.
- Sustainable Building Mandates:Regulations like the EU Green Deal encourage the use of energy-harvesting wireless sensors for building automation to improve energy efficiency and reduce operational waste.
Market Restraints
- Limited Power Budget:The low energy captured from ambient sources restricts the complexity of onboard processing and the frequency of data transmission, limiting suitability for high-speed monitoring applications.
- Spectrum Fragmentation:Divergent radio frequency allocation rules set by bodies like the US FCC and national regulators across Europe complicate the design of a single sensor SKU for global markets.
- Performance Variability:The operational effectiveness of thermoelectric and photovoltaic sensors depends entirely on environmental conditions like thermal gradients or light availability, creating reliability concerns.
Strategic Opportunities
- Structural Health Monitoring:Deploying piezoelectric or vibration-harvesting sensors in civil infrastructure like bridges and pipelines represents a significant, underpenetrated application for long-term, zero-maintenance monitoring.
- Wearable Medical Devices:The convergence of flexible, biocompatible energy-harvesting materials with ultra-low-power microcontrollers opens opportunities for self-powered health monitors and diagnostic patches.
- Smart Packaging Integration:Embedding low-cost RFID or NFC-based sensors directly into product packaging enables real-time tracking and condition monitoring throughout the cold chain and retail supply chain.
Industry Challenges
- System Integration Complexity:Integrating data from diverse, often proprietary, battery-free sensor networks into legacy enterprise resource planning and industrial control systems remains a significant technical hurdle.
- Absence of Data Standards:A lack of universal standards for data formats and communication APIs across different sensor technologies inhibits interoperability between platforms from different vendors.
- Certification Bottlenecks:Navigating the complex and costly certification processes for wireless devices, including CE marking under the RED in Europe and FCC approval in the US, delays time-to-market.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Free Sensor Market |
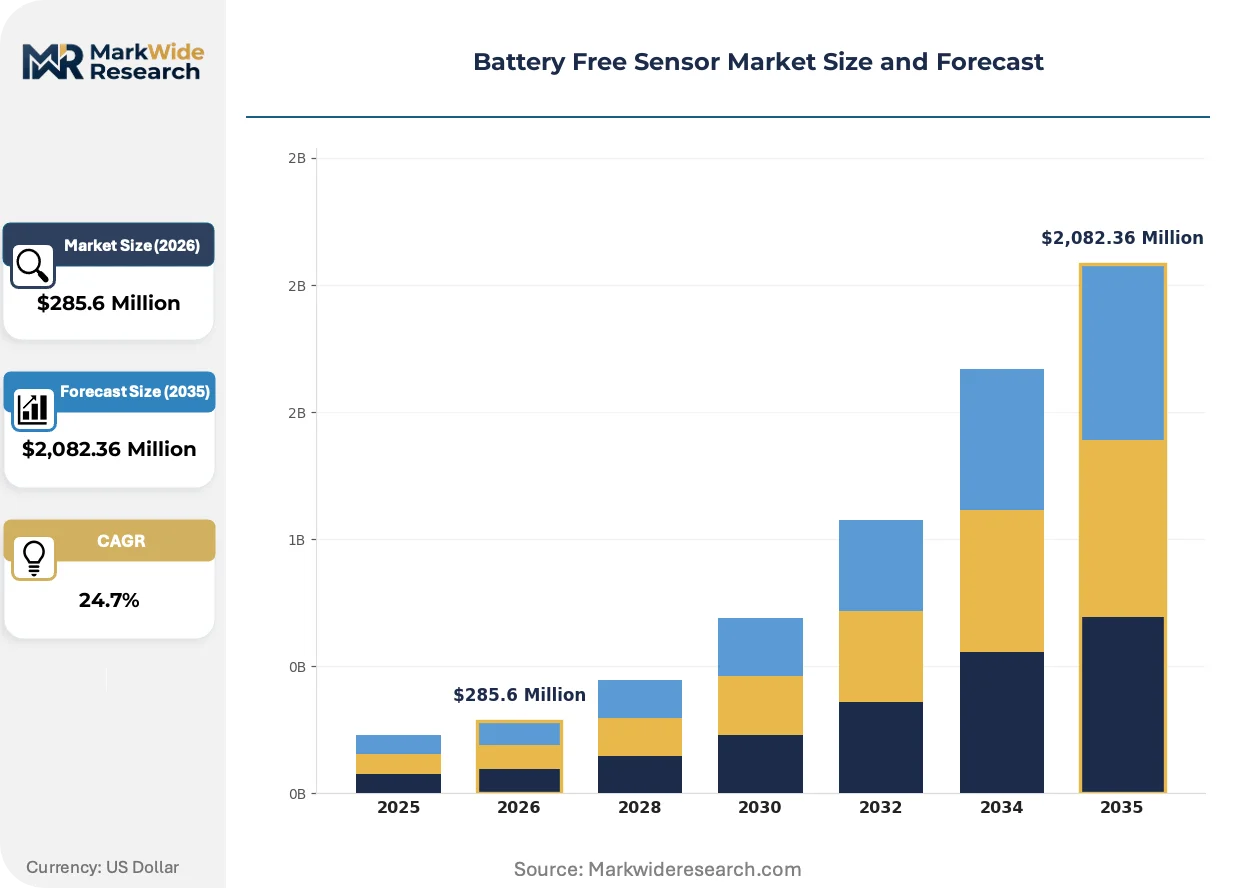
| Market Size in 2026 | $285.6 Million |
| Market Size in 2035 | $2,082.36 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radio Frequency Identification, Piezoelectric Sensors, Electromagnetic, Thermoelectric, Photovoltaic, Vibration Energy Harvesters Application: Smart Buildings, Industrial Automation, Environmental Monitoring, Asset Tracking, Structural Health Monitoring, Agriculture Management End User: Manufacturing Facilities, Logistics Providers, Research Institutes, Construction Firms, Agricultural Enterprises, Public Infrastructure Deployment: Wireless Sensor Networks, Standalone Systems, Embedded Systems, IoT Platforms, Remote Monitoring, Condition-Based Maintenance |
| Companies Covered | ON Semiconductor, Farsens, Axzon, Inductosense, Powercast, EnOcean GmbH, Texas Instruments, Infineon Technologies, Everactive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Free Sensor Market Strategic Shifts & Innovations
The market's evolution is defined by a shift from passive data collection toward intelligent, edge-based sensing. This transition is enabled by material science advancements and shaped by stricter regulatory requirements for wireless device security and material composition.
Advanced material science is a primary innovation driver. Flexible piezoelectric polymers and novel thermoelectric compounds function as efficient energy transducers for next-generation devices. These materials are seeing rapid evaluation for use in wearable medical patches and asset tags for curved industrial equipment. This material innovation is decomposing the monolithic sensor design, allowing the energy harvesting element to be physically separate and conform to a surface while the rigid processing unit is placed elsewhere.
Compliance with the EU's Radio Equipment Directive (RED) is reshaping product development cycles. The directive mandates stringent testing for wireless performance, electromagnetic compatibility, and radio spectrum efficiency for any device sold in the European Union. This forces manufacturers of industrial and building automation sensors to invest heavily in pre-certified modules or engage specialized labs, raising the barrier to entry for smaller firms.
End-user buying behavior is evolving from one-time hardware purchases toward data-centric service agreements. In logistics and cold chain management, customers are increasingly subscribing to monitoring services that provide temperature and location data, rather than owning the sensor hardware. This model disrupts traditional component distribution channels and benefits system integrators that offer a bundled solution, a trend most visible in North American and European markets.
Battery Free Sensor Market Segmentation
Understanding the segmentation of the battery-free sensor market is crucial for identifying areas of concentrated demand and emerging technological adoption. This detailed breakdown highlights how different product types, applications, end users, and deployment methods shape competitive strategies and market access across various industrial and commercial sectors.
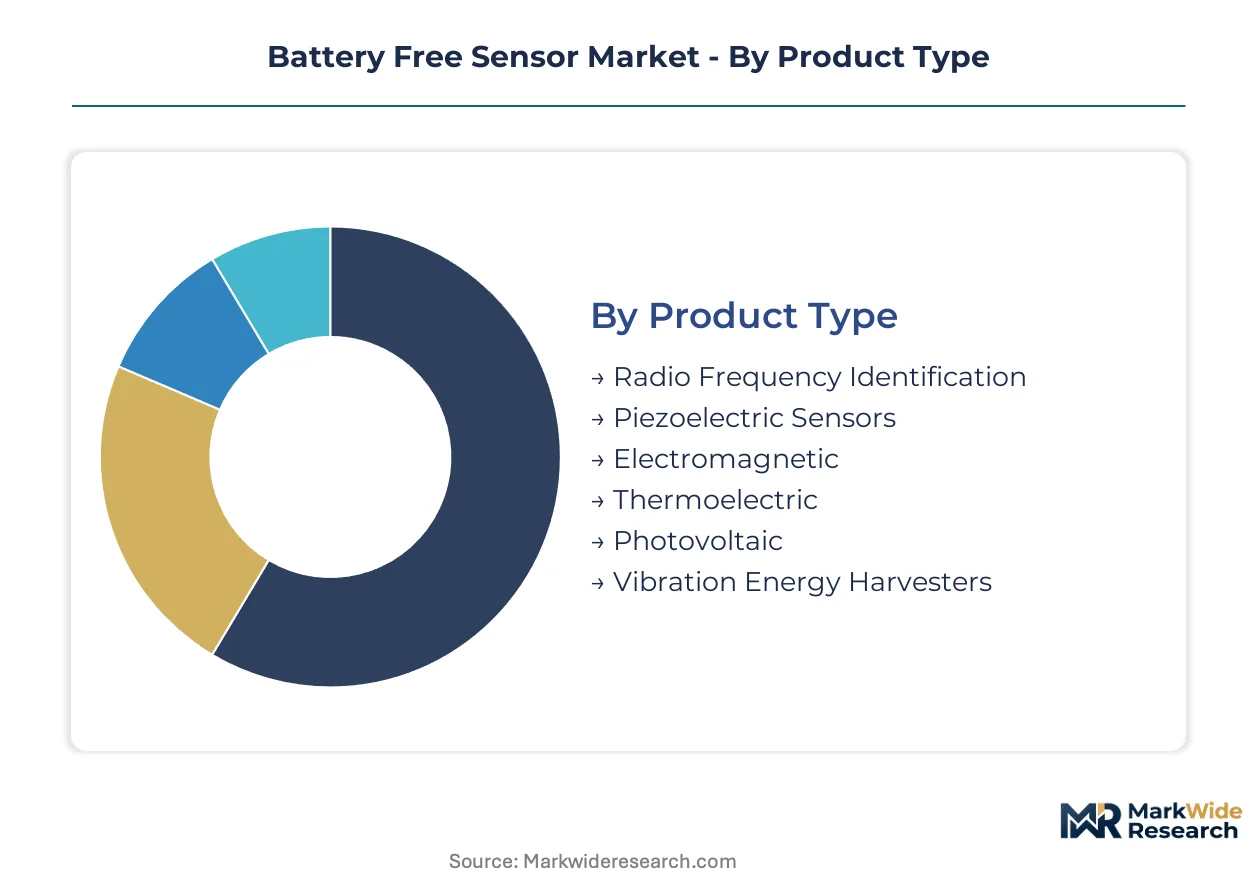
Product Type:
The product type segmentation reveals which sensor technologies are gaining traction in specific geographic markets and regulatory environments. Domestic demand in Germany, for instance, favors specific energy harvesting solutions for industrial automation, while Chinese manufacturing hubs drive volume for RFID applications.
- Radio Frequency Identification (RFID):These sensors utilize radio waves for power and data transmission, enabling contactless identification and tracking. Demand is concentrating in logistics and retail supply chains across North America and China, driven by the need for real-time inventory management.
- Piezoelectric Sensors:Piezoelectric materials generate an electrical charge in response to mechanical stress, converting vibrations into usable energy. Industrial automation applications in Germany and Japan are increasingly adopting these for predictive maintenance and structural health monitoring.
- Electromagnetic:These devices harvest energy from ambient electromagnetic fields, often used for low-power remote sensing in specialized environments.
- Thermoelectric:Thermoelectric sensors convert temperature differences into electrical energy, finding utility in industrial process monitoring where heat gradients are present.
- Photovoltaic:Photovoltaic sensors convert light into electrical energy, commonly deployed in outdoor environmental monitoring and smart building applications.
- Vibration Energy Harvesters:These systems capture kinetic energy from mechanical vibrations to power electronic devices, suitable for machinery monitoring in manufacturing facilities.
Radio Frequency Identification commands the established base. The steepest expansion runs through Piezoelectric Sensors.
Application:
Application segments are largely differentiated by the volume of data generated and the required operational lifespan for sensor deployments. High-volume applications like industrial automation in manufacturing facilities drive significant sensor unit demand.
- Industrial Automation:Battery-free sensors enable predictive maintenance and process optimization in factories and production lines. Manufacturers in Germany and Japan deploy these sensors to monitor equipment health and reduce downtime.
- Smart Buildings:These sensors manage environmental conditions, lighting, and access control in commercial and residential structures. The EU Green Deal initiatives bolster demand for energy-efficient solutions in European smart buildings.
- Environmental Monitoring:This segment includes sensors for tracking air quality, water levels, and soil conditions in agricultural and urban settings.
- Asset Tracking:Battery-free sensors provide location and status updates for goods and equipment throughout supply chains.
- Structural Health Monitoring:These applications involve monitoring the integrity of infrastructure like bridges and pipelines using vibration or strain sensors.
- Agriculture Management:Sensors collect data on soil moisture, temperature, and crop health to optimize farming practices.
Industrial Automation represents the largest volume segment. Structural Health Monitoring is expanding most quickly.
End User:
The end-user landscape reflects varying procurement patterns and integration complexities, with large manufacturing facilities often requiring customized solutions. Procurement patterns in Europe and North America increasingly favor bundled service agreements over standalone hardware purchases.
- Manufacturing Facilities:These users deploy sensors for process control, asset tracking, and predictive maintenance on production lines. Germany's Industry 4.0 initiatives significantly drive demand within its manufacturing sector.
- Logistics Providers:Companies in this sector use battery-free sensors for real-time tracking and condition monitoring of goods during transit. Cold chain management in North America relies heavily on these solutions.
- Research Institutes:Academic and private research entities utilize these sensors for experimental setups and advanced material science studies.
- Construction Firms:Construction companies apply sensors for structural health monitoring of new builds and existing infrastructure.
- Agricultural Enterprises:Farmers use battery-free sensors for precision agriculture, monitoring environmental factors and crop conditions.
- Public Infrastructure:Government bodies and public utilities deploy sensors for monitoring bridges, roads, and other critical infrastructure elements.
Manufacturing Facilities represent the largest end-user group. Logistics Providers are rapidly increasing their sensor deployments.
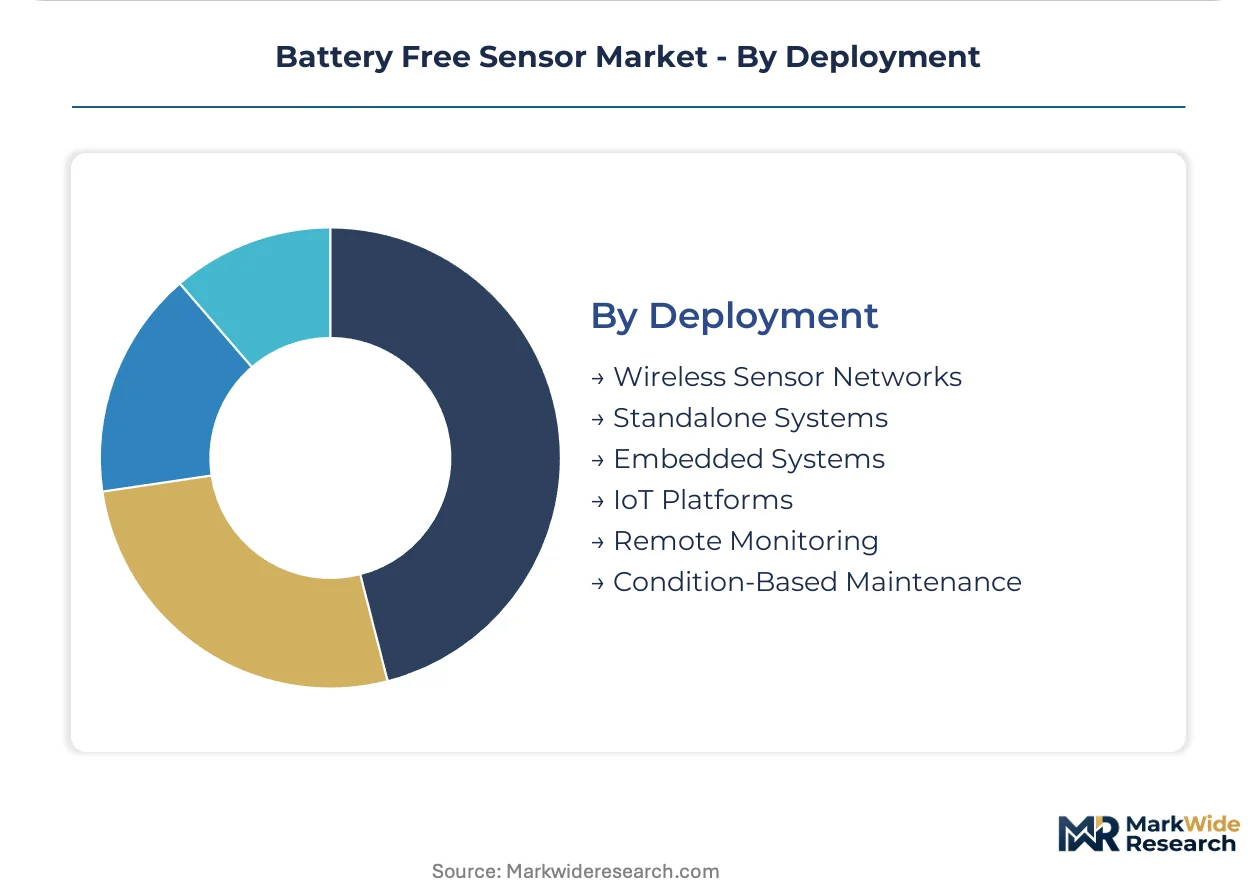
Deployment:
Deployment strategies vary based on the scale and complexity of the monitoring required, influencing the choice between standalone devices and integrated network solutions. The maturity of wireless communication technologies directly impacts the feasibility and cost-effectiveness of different deployment models.
- Wireless Sensor Networks:These involve multiple interconnected battery-free sensors communicating data to a central hub. Large-scale industrial and smart building deployments in Europe frequently leverage these networks.
- Standalone Systems:Individual sensors operate independently, typically for localized monitoring or simple data collection tasks. These are often found in niche environmental sensing applications.
- Embedded Systems:Sensors are integrated directly into machinery, products, or structures during manufacturing. This approach is common in smart packaging and advanced industrial equipment.
- IoT Platforms:Battery-free sensors connect to broader Internet of Things ecosystems for data aggregation and analytics. Major technology firms offer comprehensive platforms for this integration.
- Remote Monitoring:This involves collecting data from sensors in geographically dispersed or hard-to-reach locations. Agricultural enterprises use this for field monitoring.
- Condition-Based Maintenance:Sensors continuously monitor equipment parameters to predict failures and schedule maintenance proactively. This is a primary driver in manufacturing facilities.
Wireless Sensor Networks are a mature deployment method. IoT Platforms are expanding their integration capabilities fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal and similar global initiatives are actively shaping demand for battery-free sensors across key regions. These regulatory frameworks incentivize energy efficiency and sustainable practices in industrial and building automation. Manufacturing hubs worldwide are responding to these policy directives, creating a robust market.
Germany
Germany's Industry 4.0 initiatives drive significant demand for piezoelectric sensors in industrial automation. The EU's Radio Equipment Directive (RED) mandates stringent testing for wireless device performance and electromagnetic compatibility. Manufacturing clusters in Bavaria and North Rhine-Westphalia actively integrate these sensors for predictive maintenance and process optimization.
China
China's robust manufacturing sector creates substantial demand for RFID sensors in logistics and supply chain management. The dual carbon goals push for energy-efficient technologies in industrial applications and smart city development. Major industrial zones like the Yangtze River Delta are rapidly adopting battery-free solutions for inventory tracking and asset monitoring.
Japan
Japan's METI-driven push for smart factories generates a strong market for vibration energy harvesters in machinery monitoring. Japanese industrial standards (JIS) ensure product quality and interoperability in these advanced systems, fostering trust in their deployment. Automotive and electronics manufacturing centers around Tokyo and Osaka are primary adopters for long-term equipment health monitoring.
United States
The United States sees strong demand for battery-free sensors in asset tracking and structural health monitoring applications, particularly in critical infrastructure. FCC regulations govern radio frequency emissions for wireless devices, impacting design and market access for manufacturers. Industrial corridors in the Midwest and technology hubs in California utilize these sensors for infrastructure integrity and supply chain visibility.
Battery Free Sensor Market Key Industry Players
Player mix skews toward established semiconductor manufacturers and specialized energy harvesting firms, creating a dynamic competitive environment. The market structure exhibits a tiered consolidation, with large players providing integrated solutions and niche firms innovating on specific harvesting technologies. Strategic archetypes include broad-portfolio giants, specialized component providers, and system integrators focused on end-to-end solutions. Portfolio diversification into new application areas and strategic partnerships for ecosystem development are dominant competitive moves across the industry.
Within the broad-portfolio semiconductor archetype, Texas Instruments leverages its extensive component base to offer integrated, pre-certified modules for diverse applications, from industrial to consumer. EnOcean GmbH exemplifies a specialized firm, focusing exclusively on energy harvesting wireless technology for smart buildings and industrial automation, enabling zero-maintenance deployments. Infineon Technologies occupies a crucial position as a provider of security and power management components, essential for ensuring the reliability and data integrity of connected battery-free devices across various sectors. These companies anchor different segments of the market, from fundamental silicon to complete wireless solutions, influencing product development cycles.
| Leading Market Players |
|---|
| ON Semiconductor |
| Farsens |
| Axzon |
| Inductosense |
| Powercast |
| EnOcean GmbH |
| Texas Instruments |
| Infineon Technologies |
| Everactive |
| Others |
Cost & Logistics Intelligence
Flexible piezoelectric polymers replacing traditional silicon components simultaneously reshapes supply geography towards advanced material science hubs and alters pricing economics towards specialized material sourcing. This substitution dynamic drives shifts in manufacturing and cost structures within the battery-free sensor market.
Pricing Analysis
Certification level (CE marking under the EU's RED, FCC approval in the US) creates the primary spread in battery-free sensor pricing. Most transactions occur on a per-unit basis, though bundled service agreements gain traction in logistics. Performance reliability and customization for specific industrial environments also differentiate pricing. Pricing softness reflects intense competition from established semiconductor firms leveraging economies of scale. Industrial automation end-users are least price-sensitive due to critical application requirements, while high-volume RFID applications in retail exhibit greater price sensitivity.
Supply Chain Analysis
China and Germany anchor the manufacturing of core battery-free sensor components, including microcontrollers and energy harvesting elements. The supply chain draws from specialized material inputs like piezoelectric ceramics and novel thermoelectric compounds. Single-source vulnerability for advanced material components represents a structural risk. Distribution runs through a mix of direct sales to large industrial clients and indirect channels via system integrators, especially for smart building solutions in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Overcoming the scarcity of integrated systems engineering expertise represents a critical challenge for scaling battery-free sensor deployments. This skill gap prevents seamless integration of diverse sensor networks into existing enterprise architectures.
For Market Incumbents: Fortify intellectual property around energy harvesting efficiency and ultra-low-power processing to counter emerging specialized entrants. Invest in pre-certified module development for diverse regulatory environments like the EU and US, leveraging existing regulatory expertise. Control of the data analytics layer offers a lever against commoditization of basic sensor hardware, particularly as outcome-based service models gain traction.
For New Entrants and Emerging Players: Anchor in niche, high-value applications where performance variability is less critical or environmental conditions are stable. Structural health monitoring for civil infrastructure represents a penetrable segment with long-term data requirements. Develop interoperable solutions compatible with major IoT platforms to simplify system integration for end-users. A go-to-market angle focused on bundled data services, rather than just hardware, resonates with procurement patterns in North America.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with specialized component providers focused on a single energy harvesting technology or application vertical. The long-term viability of the market rests on widespread IoT adoption and supportive regulatory frameworks for sustainable technologies. A signal to watch is the increasing standardization of communication protocols, which will streamline integration and expand market reach for consolidated platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Integrating with major IoT platforms simplifies data aggregation for manufacturing facilities. |
| Certification Investment | Obtaining CE marking and FCC approval accelerates market access for wireless devices. |
| Strategic Partnership | Partnering with system integrators expands reach into complex industrial automation projects. |
| Advanced Material R&D | Developing novel piezoelectric polymers enhances sensor efficiency for wearable medical devices. |
| Long-term Service Agreement | Offering data-centric service agreements aligns with evolving procurement patterns in logistics. |
Research Approach
Operator-level perspectives from industrial automation managers, smart building developers, and logistics providers anchored the qualitative base for this study. Primary interviews with these stakeholders provided granular insights, which secondary validation against corporate annual reports, technical journals, and government publications reinforced. Bottom-up data collection on unit shipments and top-down market sizing triangulated the overall market landscape.
Sensitivity analysis framed the quantitative projections across the analysis window, modeling market growth under various adoption scenarios. Segmentation dimensions included product type, application, end-user, deployment method, and regional regulatory compliance. Compound Annual Growth Rates (CAGRs) were derived from historical data trends and projected adoption curves, with forecast inputs including industrial IoT investment levels and LPWAN infrastructure expansion.
Decision-makers should treat outputs as directional under current industrial policy and technological advancement assumptions; material deviation would warrant model refresh. Key risk factors include unforeseen regulatory changes impacting spectrum allocation or hazardous material restrictions. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Magnetometer Market
Sensors and Controls
Refrigeration Gauge Market
Sensors and Controls
Blue-Green Algae Sensors Market
Sensors and Controls
Fiber Bragg Grating Sensor Market
Sensors and Controls
Global Tilt Sensor Market
Sensors and Controls
Water Quality Sensor Market
Sensors and Controls
APAC Temperature Sensors Market
Sensors and Controls
Inductive Proximity Sensors Market
Sensors and Controls
Industrial Combustion Control Components and Systems Market
Sensors and Controls
Gyro Sensors Market
Sensors and Controls
Global Intelligent Flow Meter Market
Sensors and Controls
Digital Angle Gauge Market
Sensors and Controls
Lidar Ceilometer Market
Sensors and Controls
Nanopositioning Piezo Actuator Market
Sensors and Controls
Europe MEMS and Sensors Market
Sensors and Controls
Ultrasonic Sensors Market