
 Industrial Machine Vision Market | 2026-2036
Industrial Machine Vision Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Machine Vision Market Intelligence
Asian sensor foundries are rebalancing capacity toward high-resolution CMOS imagers after supply constraints in precision optics. Basler AG leverages its captive camera module production to secure allocation priority during tight supply windows. Cognex Corporation sustains R&D intensity in deep-learning inspection tools that reduce false-reject rates on semiconductor wafers. KEYENCE CORPORATION dominates Japan's domestic factory automation channel with same-day technical response coverage.
Industrial machine vision encompasses camera arrays, illumination rigs, image processors, and analytical software that capture, digitize, and interpret visual data from production environments, typically operating at frame rates exceeding 60 fps with sub-pixel measurement accuracy to automate quality verification and process control. Cameras and processors generate the bulk of hardware revenue, while AI-based vision algorithms represent the fastest-expanding technology tier as factories replace rule-based inspection with neural network classifiers. Quality control applications absorb the largest share of deployment spending across automotive and electronics end users, where zero-defect protocols mandate 100% inline inspection.
The EU AI Act imposes conformity assessment burdens on vision systems making autonomous pass-fail decisions, while FDA computer vision guidance shapes validation protocols for pharmaceutical packaging inspection in the United States. China's GB standards for industrial automation equipment, enforced by SAMR, mandate electromagnetic compatibility and safety certifications that determine market access for foreign camera suppliers. Stakeholders must weigh regulatory compliance costs against the operational savings from replacing manual inspection stations, particularly as AI-based systems trigger novel liability frameworks for automated defect classification.
Market Dynamics
AI-based neural network classifiers are displacing rule-based inspection algorithms across automotive and electronics assembly lines, forcing vision system vendors to restructure software architectures and validation protocols to meet emerging conformity requirements under the EU AI Act.
Growth Catalysts
- Zero-defect protocols:Automotive OEMs in Germany and Japan mandate 100% inline inspection at camera-based stations, expanding hardware deployment density on assembly lines.
- EU AI Act conformity pathways:Regulatory clarity on autonomous pass-fail decisions accelerates procurement cycles for validated vision systems in pharmaceutical packaging.
- High-resolution CMOS imagers:Asian sensor foundries rebalancing capacity toward precision optics resolve prior supply constraints and enable sub-pixel measurement accuracy.
Market Restraints
- Validation cost escalation:FDA computer vision guidance for medical device manufacturing extends compliance timelines and requires redundant testing protocols.
- Optics supply concentration:Precision lens manufacturing clusters in East Asia create allocation vulnerability during demand surges.
- Legacy integration friction:Rule-based inspection systems in mature factories resist neural network retrofit without full line revalidation.
Strategic Opportunities
- Battery cell inspection:China's eastern manufacturing corridor retrofitting production lines with AI-based defect detection creates concentrated demand pockets.
- Same-day technical response:Factory automation channels in Japan reward vendors with localized service coverage, favoring integrated hardware-software providers.
- Convergence of edge processing and 5G:Real-time inference at inspection stations combined with low-latency backhaul enables centralized model retraining without line shutdown.
Industry Challenges
- Deep-learning engineering scarcity:Semiconductor wafer inspection requires specialized neural network training expertise that outpaces current workforce supply.
- Multijurisdictional certification:Vision systems deployed across EU, US, and Chinese facilities must simultaneously satisfy CE marking, FDA validation, and SAMR electromagnetic compatibility testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Machine Vision Market |
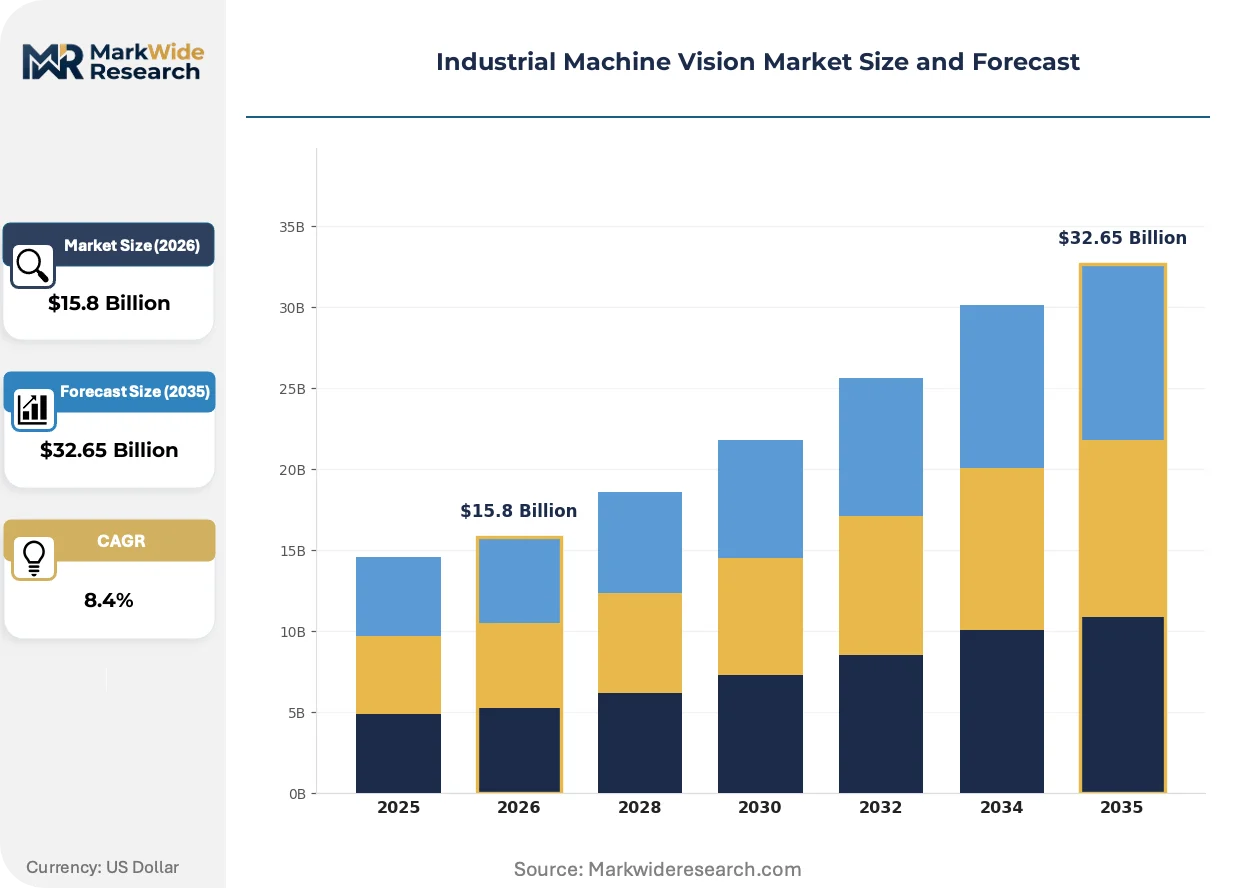
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $32.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cameras, Imaging Software, Processors, Lighting Technology: 2D Vision, 3D Vision, Laser-Based, AI-Based Application: Quality Control, Barcode Reading, Measurement, Identification End User: Automotive, Food & Beverage, Electronics, Packaging |
| Companies Covered | Basler AG, SICK AG, Cognex Corporation, Datalogic S.p.A., Zebra Technologies, KEYENCE CORPORATION, Omron Corporation, FANUC Corporation, Teledyne Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Machine Vision Market Strategic Shifts & Innovations
Inspection architectures are converging around software-defined platforms that decouple hardware acquisition from algorithm deployment, enabling faster model iteration without physical line reconfiguration.
Edge AI accelerators are unifying image capture, preprocessing, and neural network inference within single camera modules. Battery manufacturers in China's eastern corridor deploy these integrated units at frame rates exceeding 60 fps for real-time electrode defect classification. This unification compresses system architecture complexity and reduces dependency on external vision controllers.
The EU AI Act imposes conformity assessment burdens on autonomous pass-fail decision systems, requiring documented validation datasets and algorithmic transparency for high-risk industrial applications. Pharmaceutical packaging lines in Germany and France now embed compliance checkpoints within deployment workflows. Vision system vendors are restructuring software documentation and audit trail capabilities to satisfy notified body review.
Electronics contract manufacturers are consolidating supplier relationships around vendors offering captive camera module production and algorithm development under single accountability. This procurement compression displaces multi-vendor integration approaches previously common in tier-one assembly facilities. The shift is most visible in South Korea's display panel sector, where fabs prioritize vertically integrated vision partners to compress commissioning timelines.
Industrial Machine Vision Market Segmentation
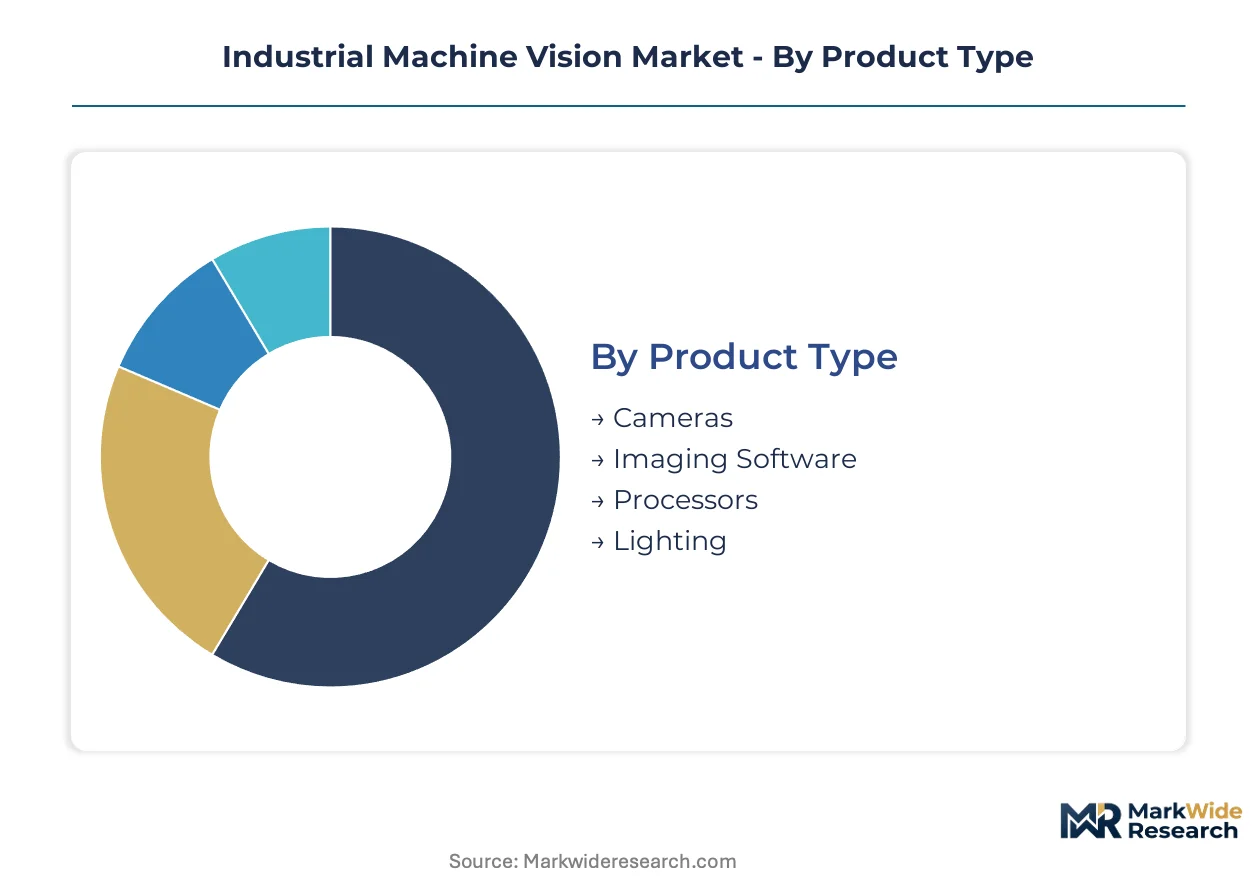
Industrial machine vision segmentation reveals how hardware components, algorithmic architectures, functional use cases, and vertical industries distribute investment and innovation differently. Each dimension exposes distinct margin structures, regulatory exposure, and competitive intensity that shape vendor strategy.
Product Type:
Cameras command the volume tier while imaging software captures premium margins through recurring license models.
- Cameras:CMOS and CCD sensor assemblies operating at frame rates exceeding 60 fps with sub-pixel accuracy. Demand concentrates in Germany and Japan where automotive OEMs mandate 100% inline inspection stations, though supply allocation tightens during precision optics shortages.
- Imaging Software:Neural network training platforms and inference engines that deploy defect classification models without line reconfiguration. Electronics contract manufacturers in South Korea's display panel sector prioritize vertically integrated vendors offering software bundled with hardware accountability.
- Processors:Edge AI accelerators unifying preprocessing and inference within single modules.
- Lighting:Structured LED arrays and strobing rigs for consistent illumination across inspection angles.
Today's leader: Cameras. Tomorrow's challenger: Imaging Software.
Technology:
2D vision maintains deployment density while AI-based architectures reshape validation protocols under emerging conformity frameworks.
- 2D Vision:Conventional area-scan and line-scan imaging for dimensional verification and surface defect detection. Automotive assembly lines in Germany rely on mature 2D architectures for paint and weld inspection where rule-based algorithms suffice.
- 3D Vision:Stereo, structured light, and time-of-flight systems capturing depth data for volumetric measurement. Battery manufacturers in China's eastern manufacturing corridor deploy 3D architectures for electrode alignment verification as cell formats scale.
- Laser-Based:Triangulation and confocal systems for micron-level surface profiling.
- AI-Based:Deep-learning classifiers displacing rule-based inspection across semiconductor wafer and pharmaceutical packaging lines.
2D vision anchors current installed base. AI-based systems climb the fastest as EU AI Act conformity pathways clarify procurement requirements.
Application:
Quality control absorbs the largest deployment spend while measurement applications command technical premium.
- Quality Control:Inline defect detection and pass-fail classification at production speed. Zero-defect protocols in Japanese automotive plants drive camera station density on assembly lines, triggering EU AI Act conformity burdens for autonomous decisions.
- Barcode Reading:OCR and 1D/2D code verification for traceability and serialization. Pharmaceutical packaging lines in France embed compliance checkpoints within deployment workflows to satisfy notified body review under tightening validation guidance.
- Measurement:Sub-pixel dimensional metrology for tolerance verification.
- Identification:Part recognition and sorting for flexible manufacturing cells.
Quality control dominates current procurement. Measurement applications gain share fastest as battery cell formats demand tighter dimensional tolerances.
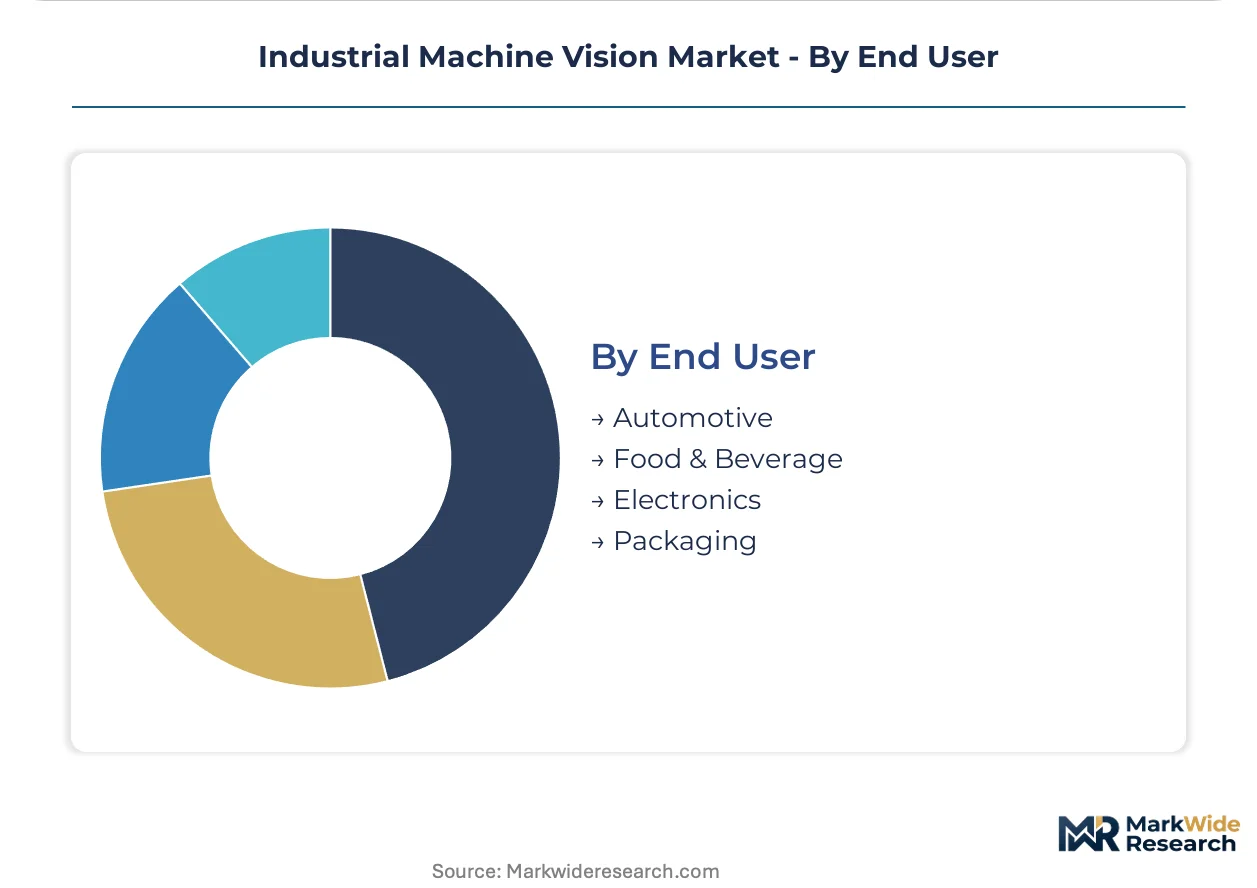
End User:
Automotive and electronics concentrate hardware volume while food and beverage presents underpenetrated retrofit opportunity.
- Automotive:Paint, weld, and assembly inspection across powertrain and body-in-white operations. German OEMs expand camera-based station deployment as zero-defect mandates harden, though legacy rule-based systems resist neural network retrofit without full line revalidation.
- Electronics:Semiconductor wafer, PCB, and display panel inspection requiring specialized neural network training expertise. South Korean fabs consolidate supplier relationships around vendors offering captive camera production and algorithm development under single accountability.
- Food & Beverage:Foreign object detection and packaging integrity verification.
- Packaging:Label verification, fill-level inspection, and serialization compliance.
Automotive anchors hardware demand. Electronics drives algorithmic innovation. Food and beverage represents the steepest expansion trajectory as hygiene regulations tighten inspection requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are relocating inspection equipment procurement to jurisdictions where regulatory clarity lowers total cost of ownership. The EU AI Act's conformity assessment burden in Europe contrasts with faster deployment cycles in Asia-Pacific manufacturing corridors, creating divergent investment patterns across major production centers.
Germany
Automotive OEMs mandate 100% inline camera inspection at paint and weld stations across Bavarian and Baden-Württemberg assembly plants. The EU AI Act imposes documented validation datasets and algorithmic transparency requirements on autonomous pass-fail systems. Stuttgart's automotive cluster drives hardware deployment density as zero-defect protocols harden procurement specifications.
China
Battery manufacturers in the eastern manufacturing corridor retrofit electrode production lines with AI-based defect detection systems. SAMR enforces GB standards for electromagnetic compatibility and safety certifications that determine market access for foreign camera suppliers. Suzhou and Shenzhen electronics hubs concentrate demand for high-resolution CMOS imagers with sub-pixel measurement accuracy.
Japan
Domestic factory automation channels reward vendors with same-day technical response coverage across Kanto and Kansai industrial belts. METI industrial standards shape validation protocols for semiconductor wafer inspection equipment. Nagoya's automotive cluster maintains dense camera station deployment as powertrain electrification accelerates quality verification requirements.
United States
Pharmaceutical packaging lines embed FDA computer vision guidance compliance checkpoints within deployment workflows. The FDA's validation protocols for medical device manufacturing extend compliance timelines and require redundant testing. Minnesota and Massachusetts medical device clusters concentrate procurement of validated vision systems for serialization and traceability applications.
South Korea
Display panel fabs consolidate supplier relationships around vertically integrated vision partners to compress commissioning timelines. MFDS pharmaceutical regulations shape packaging inspection requirements for domestic drug manufacturers. Gyeonggi-do semiconductor complexes drive demand for specialized neural network training expertise in wafer defect classification.
Industrial Machine Vision Market Key Industry Players
German and Japanese producers anchor the premium hardware tier; American software specialists hold algorithmic differentiation. The vendor base stratifies across three tiers: integrated hardware-software providers with captive camera production, pure-play software vendors licensing inference engines, and regional system integrators bundling third-party components. Two strategic archetypes dominate competitive positioning: vertically integrated manufacturers controlling sensor-to-software stacks, and AI-native challengers decoupling algorithm deployment from hardware acquisition. Capacity expansion in Asian sensor foundries and strategic partnerships between edge processor vendors and camera manufacturers represent the dominant competitive moves.
Among Germany-based fabricators, Basler AG and SICK AG exemplify the integrated hardware archetype with captive production capabilities. Cognex Corporation anchors the American software-specialist tier. These three companies occupy positions that illustrate the market's fundamental segmentation between sensor manufacturing control and algorithmic differentiation, with each archetype pursuing distinct pathways to secure allocation priority during precision optics supply constraints.
| Leading Market Players |
|---|
| Basler AG |
| SICK AG |
| Cognex Corporation |
| Datalogic S.p.A. |
| Zebra Technologies |
| KEYENCE CORPORATION |
| Omron Corporation |
| FANUC Corporation |
| Teledyne Technologies Inc. |
| Others |
Cost & Logistics Intelligence
Family-owned German camera specialists anchor the premium hardware tier, financing capacity expansion through retained earnings rather than external capital. This ownership structure preserves pricing discipline during precision optics shortages while constraining aggressive discounting that would erode long-term supplier relationships.
Pricing Analysis
Distributor margins absorb compression when automotive OEMs negotiate direct procurement contracts for high-volume camera deployments. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated pharmaceutical systems from general factory automation hardware. Cost compression in the standard tier intensifies because Asian sensor foundries expanded CMOS imager capacity. Electronics contract manufacturers in South Korea exhibit highest price sensitivity due to consolidated supplier relationships, while medical device clusters in Minnesota and Massachusetts accept premium pricing for validated compliance documentation.
Supply Chain Analysis
Dual-sourcing requirements from German automotive OEMs mandate qualified secondary suppliers for critical illumination and lens components. Manufacturing concentrates in Germany, Japan, and China, with precision optics drawing from Taiwanese glass foundries and Japanese optical coating specialists. Raw material dependencies include high-purity silicon wafers, rare-earth phosphors for LED arrays, and specialized epoxy resins for sensor packaging. Single-source vulnerability persists in EUV-grade optical substrates. Distribution runs through factory automation channel partners with localized technical service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in industrial machine vision rests on software recurring revenue displacing transactional hardware sales, with AI-based defect classification commanding subscription premiums over perpetual licenses.
For Market Incumbents: Deploy captive camera module production as the priority lever to secure allocation priority during Asian sensor foundry tightness. Basler AG and SICK AG exemplify this defensive posture. Consolidate algorithm development under single accountability to match South Korean display panel procurement preferences. Neural network engineering scarcity threatens incumbents unable to retain specialized wafer inspection talent. For New Entrants and Emerging Players: Cloud-based vision platforms offer the most penetrable entry route into mid-tier electronics contract manufacturers seeking faster model iteration without line reconfiguration. Target food and beverage inspection as the underpenetrated vertical where hygiene regulations tighten requirements but legacy rule-based systems dominate. Pursue direct-to-factory sales bypassing established channel partners to compress commissioning timelines. For Investors and Strategic Acquirers: Industrial automation conglomerates are the most active acquirer in this space, seeking AI-native vision software to complement mechanical portfolios. The five-to-ten year viability window favors targets with documented EU AI Act conformity pathways and pharmaceutical validation track records. Watch battery manufacturer capex announcements in China's eastern corridor as the demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Captive CMOS imager production secures allocation priority during Asian foundry tightness for German camera specialists. |
| AI Algorithm Platform Launch | Software-defined vision architectures enable faster neural network deployment without physical line reconfiguration for electronics manufacturers. |
| EU AI Act Conformity Investment | Documented validation datasets and audit trail capabilities unlock pharmaceutical packaging procurement in Germany and France. |
| Same-Day Technical Service Expansion | Localized response coverage captures factory automation channel preference in Japan's Kanto and Kansai industrial belts. |
| Battery Cell Inspection Partnership | Electrode defect detection specialization addresses concentrated retrofit demand in China's eastern manufacturing corridor. |
Research Approach
Coverage spans Germany, Japan, China, and the United States, with primary inputs from each manufacturing cluster. The research combines interviews with plant engineers, OEM procurement teams, aftermarket service heads, and vision system integration specialists with secondary validation from SEC filings, customs trade records, SAMR certification databases, and EU notified body conformity assessments. Bottom-up deployment counts triangulate against top-down vendor revenue estimates.
Rate-of-change decomposition separates volume growth from value mix shifts across the projection horizon. The analytical framework models segmentation across product type, technology architecture, functional application, and end-use vertical, with additional dimensioning by regulatory compliance tier. CAGRs derive from installed base turnover rates and new line expansion patterns. Forecast inputs include automotive zero-defect protocol adoption curves and battery manufacturer capex cycles.
The model assumes a particular technology adoption path; alternative pathways for edge AI accelerator integration would alter the outlook. Forecasts reflect assumptions about EU AI Act implementation timelines, FDA validation protocol stability, and Asian sensor foundry capacity expansion. Deviation in automotive electrification rates or semiconductor capital expenditure cycles would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Pico Projector Market
Imaging
Middle East and Africa Thermal Imaging Systems Market
Imaging
Global Waterproof Camera Market
Imaging
Hybrid Imaging Market
Imaging
Video Capture Card Market
Imaging
Image Based Barcode Reader Market
Imaging
Short-Wave Infrared (SWIR) Camera Market
Imaging
Global Microscopy Market
Imaging
Borescope Market
Imaging
Phosphor Screen Scanner Market
Imaging
Micro-Magnetic Resonance Imaging Market
Imaging
APAC Image Sensors Market
Imaging
On-Chip Color Filters Market
Imaging
Frame Grabber Market
Imaging
Widefield Imaging Systems Market
Imaging
Whole Slide Imaging Systems Market