
 Instrumented Load Shackle Market | 2026-2036
Instrumented Load Shackle Market Size, Share, and Industry Trends Forecast 2026-2036
Instrumented Load Shackle Market Foresight
Direct-to-operator digital channels is reshaping how instrumented load shackle manufacturers reach end users in marine and energy sectors. Crosby Group leverages its forged hardware heritage to sustain premium positioning in heavy-duty lifting applications. Straightpoint specializes in wireless telemetry integration, differentiating its portfolio from conventional wired alternatives. Interface Inc. anchors North American supply through calibrated sensor manufacturing and in-house strain gauge production.
An instrumented load shackle incorporates strain gauge load cells or force sensors within a forged steel bow and pin assembly to measure tensile loads during lifting operations, typically rated from one tonne to over one thousand tonnes with accuracy classes of 0.1% to 0.5% of full scale. The device transmits real-time data to crane operators, rigging engineers, or centralized monitoring systems to prevent overload conditions and document compliance with safety protocols. Wireless shackles capture expanding share in offshore and construction sectors where cable management poses operational constraints. IoT-enabled technology platforms create the fastest-growing margin pool by embedding predictive maintenance algorithms and cloud-based fleet analytics. Heavy-duty shackles retain stable demand in oil and gas applications where proof loading and fatigue resistance specifications remain stringent.
OSHA crane and rigging standards in the United States mandate load verification for critical lifts above defined thresholds, while the EU Machinery Directive and ATEX certification frameworks enforce intrinsically safe design for hazardous zone deployment. Lloyd's Register and DNV classification societies further shape product acceptance in marine and subsea markets through type approval protocols. Stakeholders must weigh captive sensor manufacturing against modular sourcing strategies as telemetry integration deepens and certification breadth becomes the decisive bid criterion.
Market Dynamics
Wireless telemetry integration is compressing replacement cycles across marine and energy sectors as offshore operators abandon cable-dependent architectures for intrinsically safe, battery-powered load monitoring systems that eliminate rigging complexity.
Growth Catalysts
- EU ATEX certification mandates:Hazardous zone deployment requirements in North Sea oil operations accelerate wireless shackle adoption over conventional wired alternatives that fail spark-resistance protocols.
- Subsea lifting expansion:Deepwater rigging operations in Norway, the United States, and Singapore concentrate demand for corrosion-resistant, high-capacity instrumented shackles rated above 500 tonnes.
- Predictive maintenance algorithms:IoT-enabled platforms embed fleet analytics that transform load monitoring from reactive safety compliance into proactive asset management.
Market Restraints
- Strain gauge supply concentration:Precision sensor manufacturing clusters in Germany and Japan create input vulnerability for shackle assemblers without captive gauge production.
- ATEX certification timeline friction:Intrinsically safe design approval cycles extend 12-18 months, gating product launches for hazardous zone applications.
- Fiber-optic load monitoring substitution:Emerging optical sensing technologies in aerospace testing applications threaten displacement of electrical strain gauge architectures in precision-critical segments.
Strategic Opportunities
- Direct-to-operator digital channels:Marine and energy sector procurement bypasses traditional distribution through manufacturer-hosted configuration platforms with embedded calibration documentation.
- OSHA crane standard expansion:United States regulatory threshold reductions for mandatory load verification widen addressable market in construction and infrastructure verticals.
- Cloud-based fleet analytics convergence:Integration of shackle telemetry with crane management systems creates subscription revenue pools beyond hardware replacement cycles.
Industry Challenges
- Calibration technician scarcity:Certified strain gauge calibration expertise concentrates among aging specialists, constraining field service expansion for wireless shackle deployments.
- Legacy system integration complexity:Hardwired crane monitoring architectures in installed base require protocol bridging hardware that extends deployment timelines and erodes margin.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Instrumented Load Shackle Market |
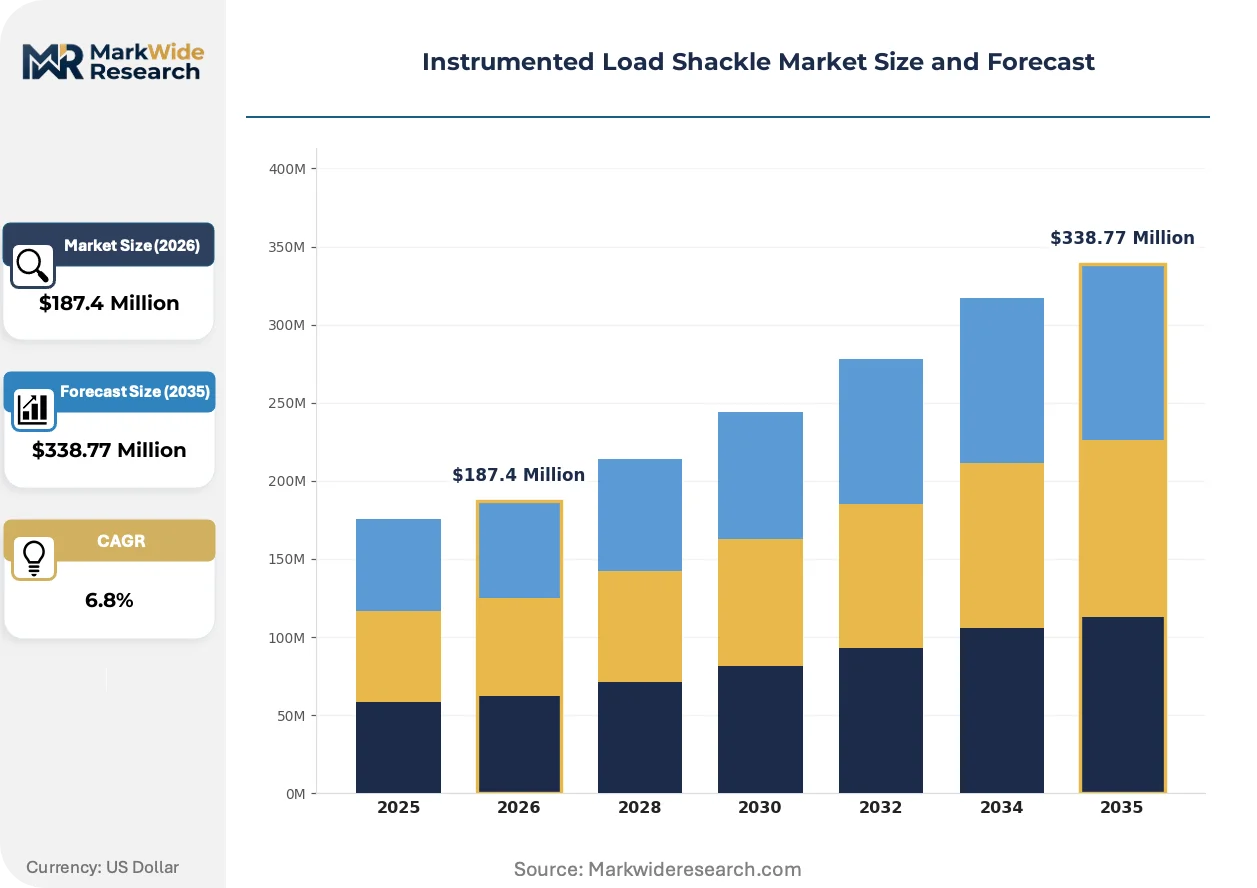
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wireless Shackles, Wired Shackles, Heavy-Duty Shackles, Lightweight Shackles End User: Construction, Marine, Oil & Gas, Aerospace Technology: Load Cells, Sensors, IoT-enabled, Analog Application: Material Handling, Lifting Operations, Load Monitoring, Safety Compliance |
| Companies Covered | Straightpoint, Crosby Group, Load Monitoring Systems, LCM Systems, Interface Inc., Rugged Controls, Load Cell Central, JCM Load Monitoring, Applied Measurements Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Instrumented Load Shackle Market Shifts & Advancements
Digital telemetry architectures are severing the historical link between load monitoring hardware and physical cable infrastructure, enabling deployment in previously inaccessible operational environments while compressing total installation cost structures.
Self-powered wireless load cells with energy-harvesting vibration generators are rendering obsolete battery-dependent telemetry systems that require scheduled maintenance access in subsea and elevated rigging applications. Offshore contractors in the North Sea and Gulf of Mexico deploy these units in unmanned platform installations where battery replacement costs exceed hardware depreciation. The elimination of power infrastructure is rendering obsolete the cable routing specifications that previously constrained shackle placement and drove custom engineering for each lift configuration.
OSHA crane and rigging standards in the United States mandate load verification documentation for critical lifts above defined tonnage thresholds, forcing construction fleet operators to retrofit legacy cranes with certified instrumented shackles or face insurance premium penalties. The regulation compresses replacement cycles for non-certified hardware and elevates documentation capabilities to primary purchase criteria. Heavy construction contractors in Texas and Louisiana respond by specifying shackles with embedded data logging and USB extraction ports that satisfy audit requirements without auxiliary recording equipment.
Buyer consolidation among offshore drilling contractors concentrates procurement authority with fleet managers who unbundle after-sales service from hardware acquisition, selecting calibration and recertification providers through separate competitive tenders. This disintermediation compresses manufacturer service margins and shifts revenue toward initial equipment sales with reduced recurring attachment rates. The pattern is most visible in Singapore and Norway where integrated drilling contractors operate standardized rig fleets across multiple regulatory jurisdictions.
Instrumented Load Shackle Market Segmentation
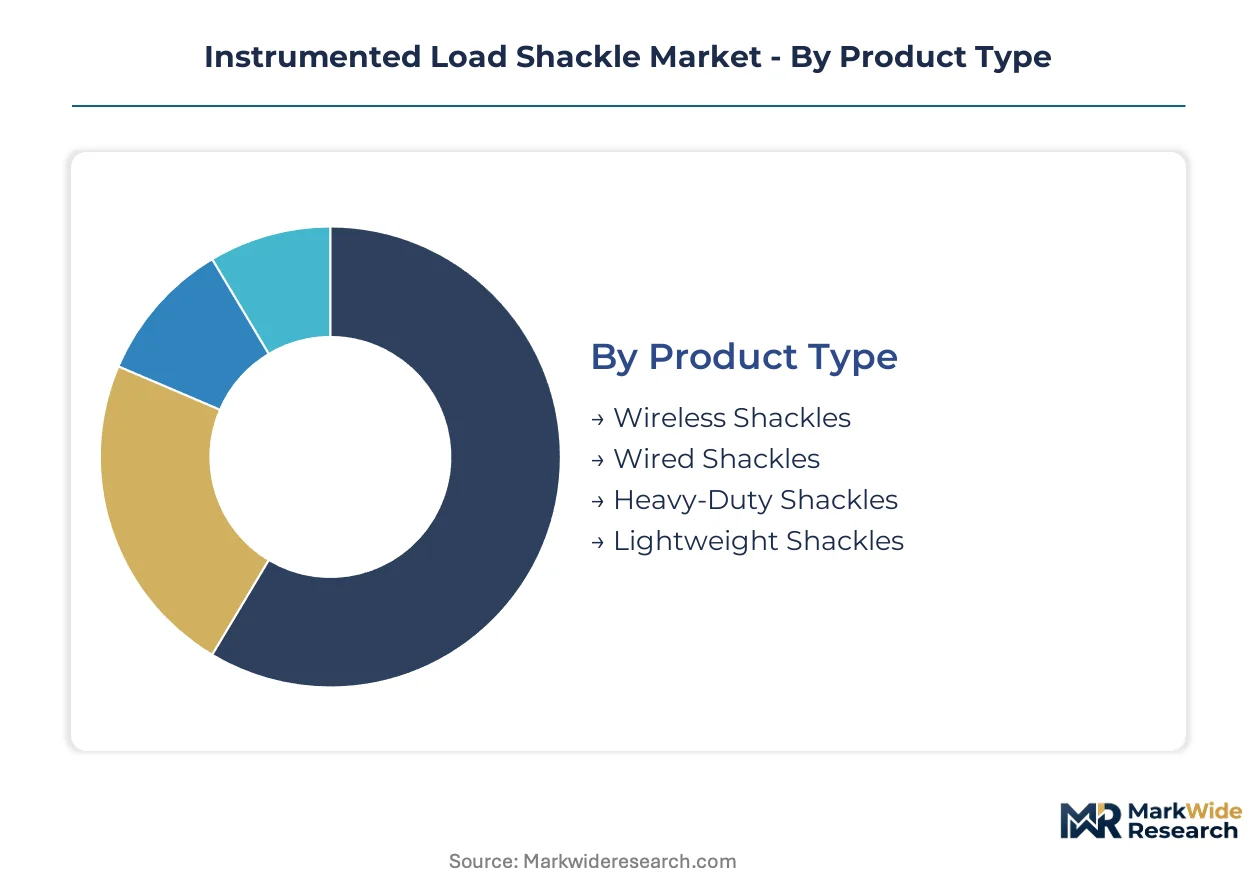
Segmentation in instrumented load shackles reveals divergent replacement economics. Wireless architectures compress hardware cycles through battery dependency, while heavy-duty forged units endure decades in subsea moorings. Procurement patterns split between fleet standardization and application-specific specification.
Product Type:
Replacement velocity varies sharply across physical architectures. Wireless units turn over fastest due to battery degradation and telemetry obsolescence, while heavy-duty forged shackles persist through multiple recertification cycles.
- Wireless Shackles:Battery-powered telemetry modules with intrinsically safe RF transmission eliminate cable routing in offshore platforms. North Sea operators specify these for unmanned installations where maintenance access costs exceed hardware replacement. ATEX certification requirements and battery chemistry limitations drive 5-7 year replacement cycles versus 15+ years for passive hardware.
- Heavy-Duty Shackles:Forged alloy steel assemblies rated above 500 tonnes with integrated strain gauge load cells withstand subsea corrosion and cyclic fatigue. Deepwater rigging contractors in Norway and the Gulf of Mexico specify these for permanent mooring installations where proof loading and DNV type approval are mandatory.
- Wired Shackles:Cabled strain gauge systems with analog or digital output remain prevalent in onshore construction where cable management poses no operational constraint.
- Lightweight Shackles:Aluminum or composite-bodied units under 50 tonnes serve temporary rigging and entertainment staging applications where portability dominates capacity requirements.
Heavy-duty shackles dominate installed base through longevity. Wireless shackles are where expansion concentrates as offshore electrification accelerates.
End User:
Capital intensity and safety regulation stringency create distinct procurement behaviors across verticals. Oil and gas operators prioritize certification breadth; construction fleets chase total cost per lift.
- Oil & Gas:Offshore drilling contractors and subsea installation firms mandate ATEX-certified wireless telemetry for hazardous zone deployment. Norway's Equinor and US Gulf operators specify shackles with embedded data logging for regulatory audit trails. Procurement concentrates with fleet managers who unbundle calibration services from hardware acquisition.
- Marine:Shipyards and port operators deploy corrosion-resistant shackles for cargo handling and vessel mooring. Singapore's PSA International and Rotterdam terminal operators drive demand for high-cycle fatigue resistance in continuous loading environments.
- Construction:Crane rental fleets and infrastructure contractors face OSHA-mandated load verification for critical lifts above defined thresholds. Texas and Louisiana contractors retrofit legacy equipment to avoid insurance premium penalties.
- Aerospace:Aircraft manufacturers and testing facilities employ precision-calibrated shackles for structural load testing and assembly line lifting, though fiber-optic sensing encroaches on electrical strain gauge architectures in this segment.
Oil and gas commands premium pricing through certification complexity. Construction represents the fastest volume expansion as regulatory thresholds widen.
Technology:
Sensor architecture determines margin structure and service attachment rates. IoT platforms capture recurring revenue; analog systems remain pure hardware plays.
- IoT-enabled:Cloud-connected shackles with embedded predictive maintenance algorithms and fleet analytics transform load monitoring into subscription-based asset management. These units command hardware premiums and generate recurring SaaS revenue through telemetry platform access.
- Load Cells:Strain gauge-based force measurement remains the dominant transduction method, with calibration traceability to national standards laboratories serving as primary differentiation.
- Sensors:Piezoelectric and capacitive alternatives address specific frequency response or temperature range requirements in specialized testing applications.
- Analog:Millivolt-per-volt output signals without digital processing persist in legacy crane systems and price-sensitive temporary rigging where documentation requirements are minimal.
Analog systems retain share in installed base retrofit constraints. IoT-enabled architectures are climbing the fastest as fleet digitization budgets expand.
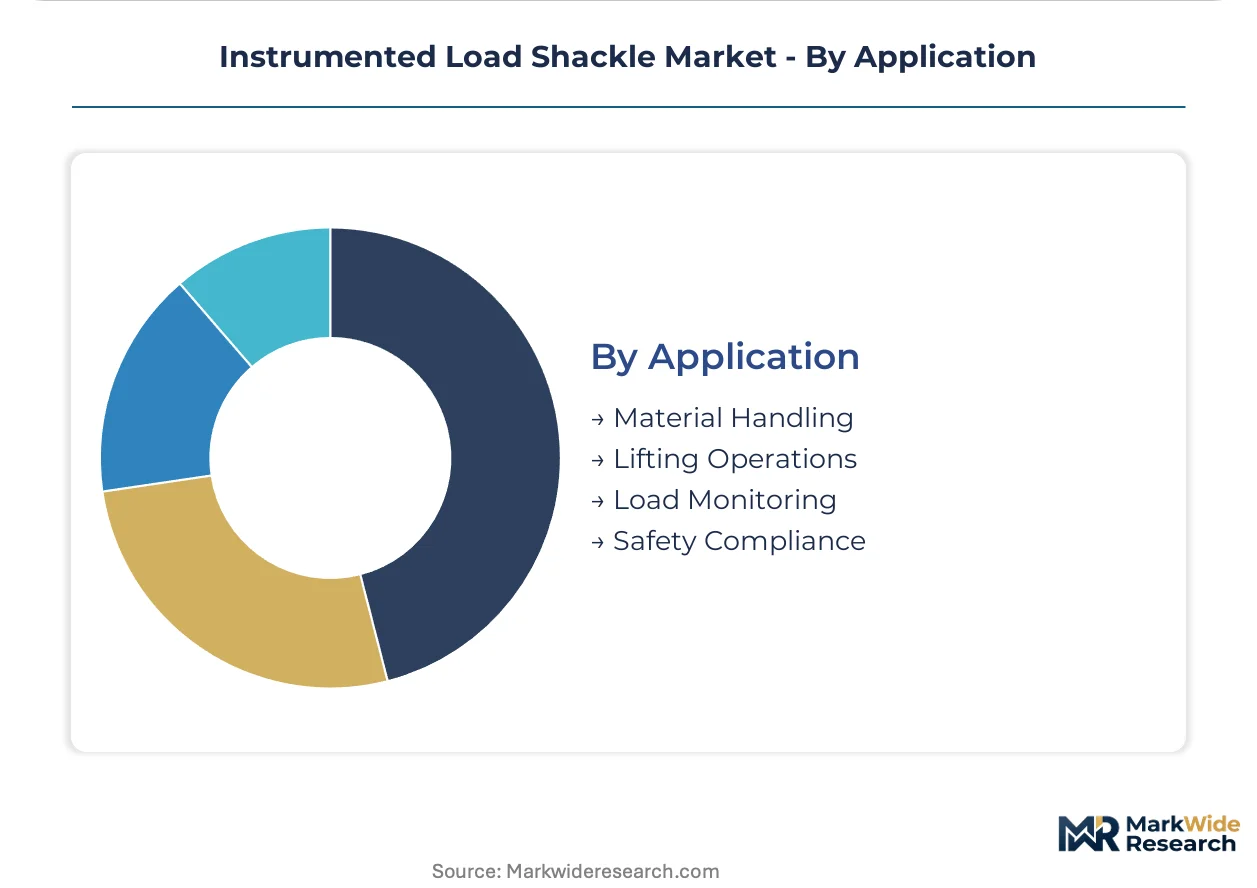
Application:
Use case specificity dictates accuracy class requirements and documentation depth. Safety compliance applications demand calibration certificates; material handling prioritizes throughput.
- Safety Compliance:Documented load verification for regulatory audit and insurance certification requires shackles with traceable calibration, data logging, and extraction protocols. OSHA and EU Machinery Directive mandates concentrate demand in construction and offshore verticals.
- Load Monitoring:Real-time tensile measurement during lifting operations prevents overload conditions and enables dynamic load distribution across multiple pick points in complex rigging configurations.
- Lifting Operations:General-purpose hoisting and rigging across industrial and entertainment applications where overload protection is required but documentation thresholds are lower.
- Material Handling:Repetitive cargo movement in ports and warehouses where speed and durability outweigh precision specifications.
Safety compliance dominates specification intensity. Load monitoring is gaining share fastest as predictive maintenance platforms penetrate fleet operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price premiums in Norway's subsea sector exceed those in Texas construction markets by substantial margins, reflecting certification complexity and operational risk differentials across regional demand pools.
United States
OSHA crane standards mandate load verification documentation for critical lifts above defined tonnage thresholds across Texas and Louisiana construction corridors. The Department of Labor enforces compliance through inspection protocols that elevate certified hardware to primary purchase criteria. Gulf of Mexico offshore contractors in Houston concentrate procurement authority with fleet managers who unbundle calibration services from equipment acquisition.
Norway
Equinor and integrated drilling contractors drive specification intensity for ATEX-certified wireless telemetry in North Sea hazardous zone deployments. The country's Petroleum Safety Authority enforces intrinsically safe design standards that gate product acceptance in subsea applications. Stavanger anchors regional demand as subsea lifting operations expand across deepwater rigging configurations requiring corrosion-resistant assemblies rated above 500 tonnes.
Germany
Precision strain gauge manufacturing clusters in Bavaria and Baden-Württemberg create supply-side concentration for sensor inputs. The EU Machinery Directive and ATEX certification frameworks implemented through federal labor inspectorates tighten product standards for hazardous zone deployment. Industrial automation hubs around Munich and Stuttgart generate secondary demand for calibrated load monitoring in heavy machinery testing applications.
Singapore
PSA International and port terminal operators deploy high-cycle fatigue-resistant shackles for continuous cargo handling in tropical marine environments. The Maritime and Port Authority enforces safety protocols that align with Lloyd's Register classification requirements for vessel mooring installations. Jurong Port and Tuas terminal expansions concentrate regional procurement volume among integrated drilling contractors operating standardized rig fleets.
United Kingdom
North Sea decommissioning programs and offshore wind installation drive demand for wireless telemetry in Aberdeen's energy corridor. The Health and Safety Executive enforces LOLER regulations that mandate thorough examination and documentation for lifting equipment in industrial applications. Scottish port operators in Peterhead and Montrose specify corrosion-resistant hardware for subsea cable laying and turbine foundation installation campaigns.
Instrumented Load Shackle Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying calibrated sensor modules and forged hardware assemblies. The vendor base organizes around three strategic archetypes: forged heritage manufacturers with captive metallurgy capabilities, wireless telemetry specialists with embedded RF engineering, and calibration service providers with accredited laboratory infrastructure. Consolidation pressure concentrates among mid-scale assemblers lacking captive strain gauge production or ATEX certification breadth. Dominant competitive moves include backward integration into sensor manufacturing and geographic expansion through classification society type approvals.
Among wireless telemetry specialists, Straightpoint occupies a position exemplifying RF-integrated load monitoring architectures, while Crosby Group represents forged hardware heritage extending into instrumented assemblies. Interface Inc. anchors North American supply through calibrated sensor manufacturing capabilities. These three entities illustrate the competitive tension between component depth and system integration breadth that defines procurement decisions in offshore and marine verticals.
| Leading Market Players |
|---|
| Straightpoint |
| Crosby Group |
| Load Monitoring Systems |
| LCM Systems |
| Interface Inc. |
| Rugged Controls |
| Load Cell Central |
| JCM Load Monitoring |
| Applied Measurements Ltd |
| Others |
Supply & Pricing Matrix
German precision strain gauge manufacturing clusters in Bavaria and Baden-Württemberg anchor upstream sensor supply, concentrating margin capture with calibrated load cell producers who command hardware premiums through captive gauge production and ATEX certification breadth.
Pricing Analysis
Configured-to-order pricing for ATEX-certified wireless telemetry modules commands substantial premiums over standard wired alternatives, with certification grade and embedded data logging capabilities as primary price differentiation drivers. Pricing pressure stems from buyer consolidation among offshore drilling contractors who unbundle calibration services from hardware acquisition. Construction fleet operators in Texas and Louisiana exhibit highest price sensitivity due to insurance-driven retrofit mandates, while Norwegian subsea operators accept premium positioning for corrosion-resistant assemblies rated above 500 tonnes.
Supply Chain Analysis
Contract manufacturing for forged alloy steel bow and pin assemblies concentrates with specialized metallurgical foundries in Germany, the United States, and Norway. Raw material dependencies span high-grade alloy steel billets, precision strain gauges, and intrinsically safe RF telemetry modules. Supply chain risk centers on single-source vulnerability for ATEX-certified battery chemistries subject to extended 12-18 month approval cycles. Distribution runs through direct-to-operator digital channels that bypass traditional rigging equipment distributors in marine and energy sectors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory entrenchment story where ATEX certification timelines and Lloyd's Register type approvals create switching costs that protect incumbent positions against unapproved substitutes.
For Market Incumbents: Insulate market position through backward integration into strain gauge manufacturing to offset German and Japanese sensor supply concentration, while expanding ATEX certification breadth to cover emerging battery chemistries. Fiber-optic load monitoring technologies in aerospace testing applications represent a substitution threat requiring telemetry R&D investment to maintain architecture relevance. For New Entrants and Emerging Players: Mid-market construction crane rental fleets in the US Gulf Coast represent the most penetrable entry point, where OSHA-mandated load verification documentation creates first-mover advantage for shackles with embedded USB extraction ports. A calibration-service-first go-to-market angle bypasses incumbent hardware lock-in by addressing the scarcity of certified strain gauge technicians. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed wireless telemetry specialists lacking captive forged hardware capabilities. Long-term viability over a 5-10 year window hinges on IoT platform subscription revenue attachment rates displacing pure hardware replacement cycles. The signal to watch is cloud-based fleet analytics penetration rates among integrated drilling contractors operating standardized rig fleets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Strain Gauge Manufacturing | Crosby Group and Interface Inc. reduce German sensor dependency through captive Bavarian production facilities. |
| ATEX Certification Expansion | Straightpoint extends intrinsically safe design coverage to emerging solid-state battery chemistries for unmanned platform deployment. |
| Direct-to-Operator Digital Channel Launch | Manufacturer-hosted configuration platforms with embedded calibration documentation bypass traditional rigging distributors. |
| Predictive Maintenance Platform Integration | IoT-enabled shackles transform load monitoring into subscription-based asset management with crane management system convergence. |
| Energy-Harvesting Telemetry Development | Self-powered wireless load cells with vibration generators eliminate battery maintenance in subsea and elevated rigging applications. |
Research Methodology
A spread of perspectives from offshore drilling contractors, crane fleet managers, calibration service technicians, and rigging engineers converged on the working assumptions underlying this analysis. Primary interviews with procurement leads at Equinor, PSA International, and Gulf of Mexico operators combined with secondary validation through Lloyd's Register type approval databases, OSHA enforcement records, and EU Machinery Directive implementation reports. Bottom-up segment sizing across wireless, heavy-duty, wired, and lightweight shackle architectures triangulated against top-down industry spend estimates from marine and energy sector capital expenditure disclosures.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling replacement cycles, regulatory threshold expansions, and telemetry platform adoption curves. Segmentation dimensions included product architecture, end-use vertical, sensor technology tier, and application specificity. CAGRs were derived from installed base turnover rates and new-build penetration assumptions. Industry-specific forecast inputs incorporated North Sea decommissioning schedules and US offshore wind installation pipelines.
Stress conditions across ATEX certification timeline delays, strain gauge supply disruptions, and fiber-optic substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and buyer consolidation trajectories. Quarterly review of wireless telemetry patent filings and classification society type approval volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Inertial Sensors Market
Sensors and Controls
Gyro Sensors Market
Sensors and Controls
Pressure Transducer Market
Sensors and Controls
Bio-FET Market
Sensors and Controls
Smart Level Probe Market
Sensors and Controls
Europe Bulk Acoustic Wave Sensors Market
Sensors and Controls
Specialty Control Plasma Market
Sensors and Controls
60GHz Radar Evaluation Kit Market
Sensors and Controls
Body Worn Antenna Market
Sensors and Controls
MEMS Energy Harvesting Devices Market
Sensors and Controls
China PV Monitoring Systems Market
Sensors and Controls
Heart Beat Sensor Market
Sensors and Controls
APAC Nano Sensors Market
Sensors and Controls
Laser Displacement Sensor Market
Sensors and Controls
Middle East and Africa Occupancy Sensors Market
Sensors and Controls
Fork Sensor Market