
 Pressure Transmitter and Transducer Market | 2026-2036
Pressure Transmitter and Transducer Market Size, Share, and Industry Trends Forecast 2026-2036
Pressure Transmitter and Transducer Market Analytics
Pharmaceutical manufacturing is repositioning demand toward hygienic pressure instruments with sanitary process connections. Emerson Electric Co. leverages its Rosemount portfolio to dominate high-purity bioprocessing applications. WIKA Group specializes in modular transmitter architectures that sustain margins across batch pharmaceutical operations. Siemens AG anchors European demand through integrated automation platforms that bundle pressure sensing with distributed control systems.
Pressure transmitters and transducers convert fluid or gas pressure into standardized electrical signals, typically 4-20 mA or digital protocols, using sensing elements such as piezoresistive silicon or capacitive ceramic diaphragms manufactured through MEMS wafer processing and laser welding. These instruments serve critical process control, safety interlock, and custody transfer functions across continuous and batch industrial operations. Differential pressure instruments lead revenue contribution due to their ubiquity in flow measurement and filter monitoring applications, while optical sensing technology represents the fastest-expanding technology segment as fiber-optic designs penetrate explosive atmospheres and electromagnetic interference environments. Wireless installation configurations are displacing conventional hardwired approaches in remote monitoring and asset integrity programs, though panel mount formats retain the largest installed base in centralized control rooms.
The US EPA mandates continuous emissions monitoring for oil and gas facilities, directly stimulating replacement demand for certified pressure instrumentation. EU F-Gas Regulation and ATEX directives constrain product design, forcing manufacturers to validate intrinsically safe and hermetically sealed constructions for European market access. China's GB standards and SAMR metrology certification add parallel compliance layers for instruments deployed in state-owned refinery and chemical complexes. Stakeholders must weigh regional certification portfolios against the cost of platform standardization as regulatory divergence deepens across Atlantic and Pacific markets.
Market Dynamics
Wireless pressure sensing architectures are displacing hardwired installations across upstream oil and gas assets, while EPA methane monitoring mandates and EU F-Gas hermetic sealing requirements force simultaneous hardware refresh cycles.
Growth Catalysts
- EPA Continuous Emissions Monitoring:Oil and gas operators in Texas and North Dakota must deploy certified pressure instrumentation for methane leak detection, creating replacement pull through 2035.
- Pharmaceutical Bioprocessing Expansion:Single-use bioreactor adoption demands hygienic pressure transmitters with sanitary Tri-Clamp connections and surface finishes below Ra 0.8 micrometers.
- Fiber-Optic Sensing Penetration:Intrinsic safety requirements in explosive atmospheres drive optical pressure transducer deployment where electromagnetic interference renders electrical sensors unusable.
Market Restraints
- MEMS Wafer Supply Concentration:Piezoresistive silicon sensing elements depend on 200mm wafer fabrication capacity concentrated in Taiwan and South Korea.
- Multi-Jurisdiction Certification Burden:ATEX, IECEx, and FM approvals for hazardous area deployment add twelve to eighteen months to product launch timelines.
- Capacitive Ceramic Cost Volatility:High-purity alumina diaphragm substrates face alumina powder price swings tied to bauxite refining capacity in China.
Strategic Opportunities
- Saudi Aramco Digital Field Programs:Mega-project instrumentation packages for Jafurah and Marjan developments specify wireless pressure monitoring with decade-long service contracts.
- Hydrogen Infrastructure Buildout:700-bar dispensing protocols require pressure transducers with hydrogen embrittlement-resistant Inconel wetted parts and TÜV certification.
- Carbon Capture Injection Monitoring:EPA Class VI well rules mandate continuous downhole pressure verification, opening subsurface instrumentation demand.
Industry Challenges
- Fieldbus Protocol Fragmentation:HART, Foundation Fieldbus, Profibus PA, and emerging Ethernet-APL standards force firmware architecture complexity and testing matrix expansion.
- Calibration Technician Scarcity:Deadweight tester operation and traceable pressure standard maintenance require skilled metrology personnel in short supply across US Gulf Coast refining clusters.
- Legacy 4-20 mA Integration:Brownfield DCS upgrades demand signal conditioners and loop isolators that add failure points and commissioning complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pressure Transmitter and Transducer Market |
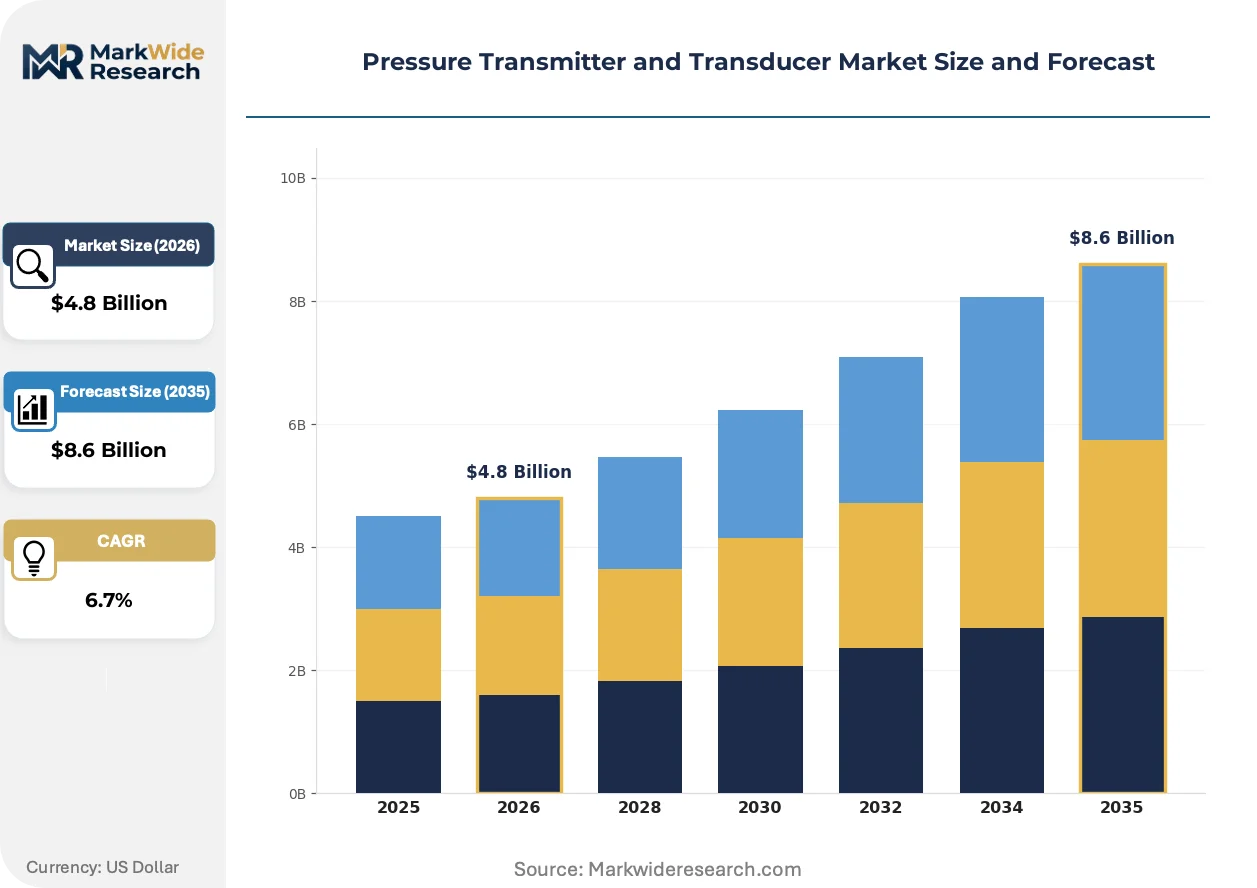
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Absolute Pressure, Gauge Pressure, Differential Pressure, Vacuum Pressure Technology: Strain Gauge, Capacitive, Piezoelectric, Optical End User: Oil & Gas, Water & Wastewater, Food & Beverage, Pharmaceuticals Installation Type: Panel Mount, Pipe Mount, Direct Mount, Wireless |
| Companies Covered | Honeywell International Inc., Siemens AG, Emerson Electric Co., WIKA Group, Endress+Hauser Group, ABB Ltd, Schneider Electric SE, Danfoss Group, Yokogawa Electric Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pressure Transmitter and Transducer Market Evolving Landscape
Silicon carbide and sapphire sensing materials are penetrating extreme-pressure applications while digital twins and edge analytics compress calibration intervals and shift maintenance from reactive to predictive models.
Optical fiber Bragg grating pressure transducers is converging with distributed sensing networks in subsea production systems. Norwegian operators deploy these instruments at 3,000-meter depths for wellhead monitoring. The technology is converging with ROV-less intervention architectures that eliminate hydraulic flying leads and reduce topside footprint.
EU F-Gas Regulation Phase-Down tightens hermetic sealing requirements for pressure transmitters containing fill fluids. Manufacturers must validate helium leak rates below 1×10⁻⁶ mbar·l/s for market access. German chemical complexes in Ludwigshafen and Leverkusen now specify welded seal designs that eliminate O-ring permeation paths.
Asset integrity programs now unbundle pressure transmitter replacement from full DCS modernization. US refineries in Houston and Beaumont execute rolling upgrades of critical safety loops while deferring control platform investments. Channel partners capture service revenue through certified loop verification and SIL validation documentation.
Pressure Transmitter and Transducer Market Segmentation
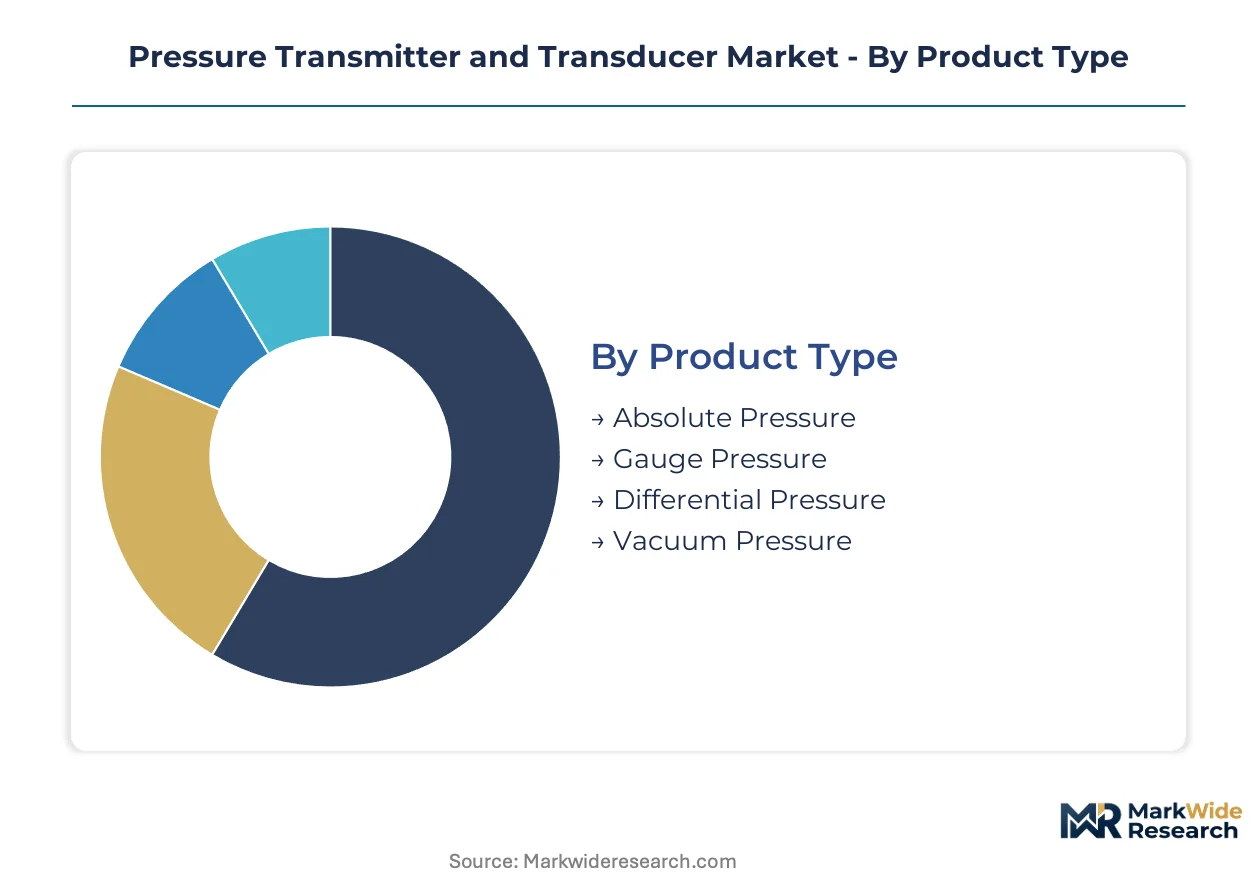
Pressure instrumentation segments diverge sharply between standardized commodity transmitters and application-specific engineered systems. Procurement teams balance interchangeability against process-critical performance specifications across hazardous area certifications and sanitary design requirements.
Product Type:
Standardization dominates absolute and gauge pressure categories, while differential pressure instruments demand extensive customization for flow computation algorithms and impulse line configurations.
- Differential Pressure:These instruments measure pressure differences across orifice plates, venturi tubes, and pitot arrays using dual diaphragm capacitive cells or resonant silicon sensors. Demand concentrates in Texas Permian Basin oilfield flow metering and German Ludwigshafen chemical complex filter monitoring applications, where EPA custody transfer rules and EU ATEX directives mandate redundant sensing architectures.
- Absolute Pressure:Sealed reference vacuum chambers enable altitude-compensated measurements critical for aerospace test stands and meteorological stations. Vacuum-sealed MEMS fabrication in Taiwan supplies sensing elements for avionics manufacturers in Toulouse and Seattle.
- Gauge Pressure:Ventilated reference ports simplify installation in open atmospheric applications including HVAC duct static pressure and pump discharge monitoring.
- Vacuum Pressure:Pirani and ionization gauge hybrids serve semiconductor wafer processing chambers requiring sub-millitorr resolution.
Leading the category by volume: Differential Pressure. Growing fastest: Vacuum Pressure.
Technology:
Cost tiers separate mature electromechanical approaches from emerging photonic platforms requiring specialized fiber splicing and signal conditioning expertise.
- Strain Gauge:Bonded foil and thin-film wheatstone bridge configurations dominate legacy industrial installations. German machine tool builders in Stuttgart specify these for hydraulic press force monitoring.
- Capacitive:Ceramic diaphragm capacitance cells achieve 0.025% accuracy for custody transfer applications. Alumina substrate supply from Chinese bauxite refineries constrains margin stability.
- Piezoelectric:Quartz crystal resonant frequency shifts enable dynamic pressure measurement in combustion research and blast testing facilities.
- Optical:Fiber Bragg grating and Fabry-Pérot interferometric designs eliminate electrical ignition risks in Norwegian North Sea subsea wellheads. Intrinsic safety certification accelerates replacement of conventional 4-20 mA transmitters in hydrogen blending stations.
Strain Gauge claims the largest installed base. Optical technology expands most quickly in explosive atmosphere applications.
End User:
Customer procurement maturity ranges from speculative spot-buying in fragmented water utilities to decade-long framework agreements with integrated oil majors.
- Oil & Gas:Upstream operators deploy subsea pressure transducers rated for 15,000 psi and 150°C in Brazilian pre-salt fields. Saudi Aramco's Marjan development specifies wireless HART-enabled transmitters for wellhead monitoring.
- Pharmaceuticals:Single-use bioreactor adoption drives demand for hygienic transmitters with 316L stainless steel wetted surfaces and Ra 0.4 micrometer electropolish finishes. FDA process analytical technology initiatives mandate continuous pressure verification.
- Water & Wastewater:Municipal treatment plants specify submersible level transmitters for wet well control and filter backwash sequencing.
- Food & Beverage:Clean-in-place protocols require 3-A sanitary certified instruments with tri-clamp process connections.
Oil & Gas generates the highest average selling prices. Pharmaceuticals demonstrates the steepest expansion trajectory driven by bioprocessing capacity builds.
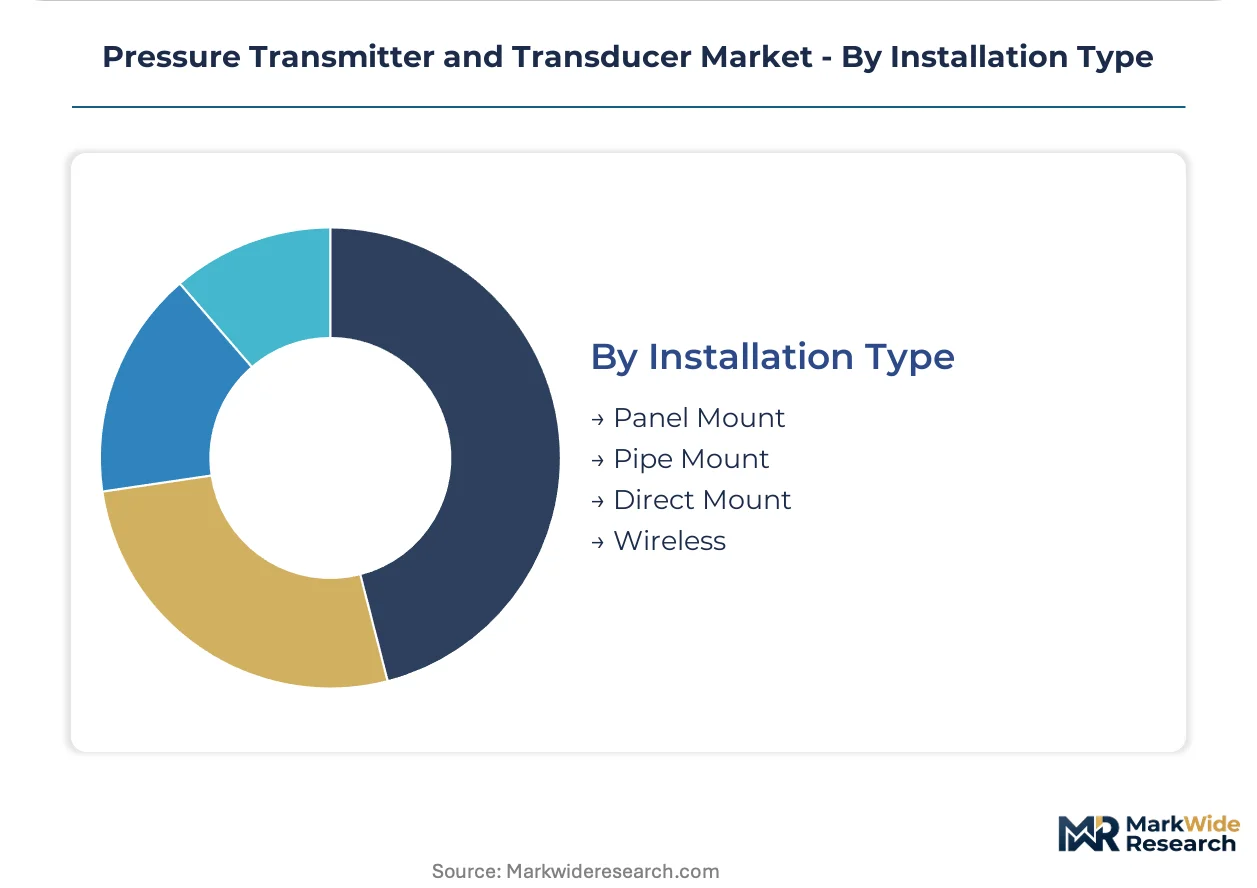
Installation Type:
Mounting configurations reflect the tension between centralized control room accessibility and distributed field intelligence placement.
- Wireless:ISA100.11a and WirelessHART protocols eliminate conduit and cable tray costs in sprawling refinery tank farms. North Dakota Bakken shale operators deploy battery-powered transmitters for temporary wellpad monitoring before pipeline connection.
- Panel Mount:DIN rail and enclosure-mounted transmitters aggregate signals in centralized DCS architectures. Legacy 4-20 mA loop-powered designs persist in Houston Ship Channel refineries.
- Pipe Mount:Direct process connection via threaded or flanged fittings minimizes impulse line leakage points in high-pressure hydrogen service.
- Direct Mount:Compact manifold-mounted transmitters reduce impulse line length for fast pressure response in compressor anti-surge control.
Panel Mount retains the largest cumulative deployment. Wireless configurations gain share fastest in greenfield upstream developments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial automation clusters around Stuttgart and Munich concentrate European demand for precision pressure instrumentation, while US shale operators and Saudi mega-projects anchor investment cycles across Atlantic and Middle Eastern markets.
United States
Texas Permian Basin operators deploy wireless pressure transmitters for methane leak detection under EPA continuous emissions monitoring mandates. The Houston Ship Channel refining corridor sustains replacement demand for SIL-certified safety loops. North Dakota Bakken shale producers specify battery-powered instruments for temporary wellpad monitoring before pipeline tie-in.
Germany
Ludwigshafen and Leverkusen chemical complexes specify welded seal designs eliminating O-ring permeation paths under EU F-Gas Regulation hermetic sealing requirements. Stuttgart machine tool builders source strain gauge pressure sensors for hydraulic press force monitoring. Munich automation clusters drive integrated pressure sensing bundled with distributed control systems.
Saudi Arabia
Saudi Aramco's Jafurah and Marjan developments specify wireless HART-enabled transmitters with decade-long service contracts for digital field instrumentation. The Eastern Province gas processing infrastructure requires subsea pressure transducers rated for high-pressure sour service. Riyadh-based engineering procurement contractors consolidate mega-project instrument packages.
China
State-owned refinery and chemical complexes in the Yangtze River Delta require GB standards compliance and SAMR metrology certification for custody transfer applications. Shandong Province petrochemical expansions drive differential pressure instrument demand for flow metering. Beijing-Tianjin-Hebei industrial corridors face dual carbon goals pressure monitoring requirements.
Norway
North Sea subsea operators deploy fiber Bragg grating pressure transducers at 3,000-meter depths for ROV-less wellhead intervention architectures. Stavanger offshore engineering clusters validate optical sensing for explosive atmosphere certification. Bergen subsea technology suppliers integrate pressure monitoring with distributed sensing networks.
Pressure Transmitter and Transducer Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with consolidated positions in high-purity pharmaceutical applications contrasting fragmented supply for standardized industrial gauges. Three archetypes dominate: diversified automation conglomerates bundling pressure sensing with control platforms; focused instrumentation specialists defending margin through modular architectures; and regional fabricators capturing service-intensive brownfield replacement cycles. Competitive dynamics center on M&A for hazardous area certification portfolios and capacity expansion for MEMS wafer fabrication.
Among diversified automation conglomerates, Siemens AG anchors European demand through integrated platform strategies, while Emerson Electric Co. occupies a position exemplifying portfolio breadth across process industries. WIKA Group represents the focused specialist archetype, with German GmbH structure signaling engineering-intensive product development. These three companies illustrate how competitive positioning diverges between bundled automation solutions and standalone instrument excellence.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Siemens AG |
| Emerson Electric Co. |
| WIKA Group |
| Endress+Hauser Group |
| ABB Ltd |
| Schneider Electric SE |
| Danfoss Group |
| Yokogawa Electric Corporation |
| Others |
Value Network & Pricing Analysis
Alumina powder price benchmarks from Chinese bauxite refineries cascade through pressure transmitter manufacturing tiers, compressing margins on capacitive ceramic diaphragm products while amplifying pricing power for piezoresistive silicon specialists with captive MEMS wafer supply.
Pricing Analysis
Lead-time premiums command substantial markups in pharmaceutical bioprocessing, where single-use reactor deployments demand sanitary pressure instruments within eight-week windows versus standard sixteen-week cycles. Three-tier pricing structure across premium, standard, and economy levels stratifies by ATEX certification grade and surface finish specifications, with German chemical buyers least sensitive to price and municipal water utilities most elastic. Pricing pressure stems from MEMS foundry overcapacity in Taiwan, forcing standard gauge transmitter producers toward volume discounts. After-sales calibration bundling now separates premium tier positioning from transactional spot sales.
Supply Chain Analysis
Freight cost volatility from Asia-Pacific semiconductor corridors disrupts just-in-time delivery commitments for European automation integrators. Sensing element fabrication concentrates in Taiwan, South Korea, and Japan, drawing from high-purity alumina substrates, Inconel wetted parts, and fiber-optic cable assemblies. Single-source vulnerability pervades 200mm MEMS wafer supply, with distribution running through authorized channel partners holding hazardous area certification inventory. German industrial clusters maintain safety stock for critical safety loop replacements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around certification-heavy incumbents as EU F-Gas hermetic sealing mandates and EPA methane monitoring rules force smaller fabricators toward exit or acquisition.
For Market Incumbents: Anchor defensive positioning through backward integration into MEMS wafer fabrication capacity in Taiwan or South Korea, eliminating foundry margin capture. Deepen channel control by certifying regional service partners for SIL validation documentation, countering emerging optical sensing specialists with faster loop verification turnaround.
For New Entrants and Emerging Players: Fiber-optic pressure transducers for hydrogen blending stations offer technology-first penetration where electromagnetic interference excludes conventional electrical sensors. Target Norwegian subsea engineering clusters with ROV-less intervention architectures, leveraging intrinsic safety certification gaps among incumbent 4-20 mA suppliers. Go-to-market through Bergen and Stavanger offshore technology integrators bypasses established channel lock-in.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap specialists with ATEX/IECEx certification portfolios in Germany's Stuttgart automation corridor. Five-to-ten year viability hinges on wireless HART protocol mastery and pharmaceutical sanitary design capabilities. Monitor Saudi Aramco mega-project instrumentation package awards as inflection signal for digital field program momentum.
| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Wafer Capacity Expansion | Captive fabrication in Taiwan insulates margins from foundry pricing volatility. |
| Hydrogen Service Certification | TÜV validation for 700-bar Inconel wetted parts opens German dispensing infrastructure. |
| Wireless Protocol Mastery | ISA100.11a and WirelessHART expertise captures Saudi Aramco digital field contracts. |
| Optical Sensing Acquisition | Fiber Bragg grating technology addresses Norwegian subsea explosive atmosphere requirements. |
| Sanitary Design Investment | Ra 0.4 micrometer electropolish capabilities penetrate single-use bioreactor demand. |
Research Methodology
Multi-period observation of EPA enforcement patterns, EU F-Gas implementation timelines, and Saudi Aramco procurement cycles anchored the trend analysis, supplemented by interviews with plant engineers at Texas Permian Basin operators, instrumentation procurement leads at German chemical complexes, subsea technology directors in Norwegian offshore clusters, and metrology calibration technicians across US Gulf Coast refining corridors. Secondary validation drew from EPA regulatory filings, SAMR metrology certification databases, SEC 10-K instrument segment disclosures, and subsea project development registries. Bottom-up transmitter deployment counts triangulated against top-down industrial automation spend estimates.
Input-output matrices modeled pressure transmitter demand across product type, technology platform, end-user industry, and installation configuration dimensions throughout the forecast period. CAGRs derived from segment-level unit economics and replacement cycle analysis, incorporating MEMS wafer supply constraints, regulatory compliance cost pass-through assumptions, and wireless adoption curve parameters specific to upstream oil and gas asset integrity programs.
Several conditions sit outside the modeled scope, including abrupt trade policy shifts affecting Taiwan semiconductor exports, unanticipated EPA methane rule suspension, and breakthrough solid-state sensing technologies displacing conventional diaphragm architectures. Forecasts reflect documented assumptions about certification timeline stability and foundry capacity expansion plans. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Smart Pressure Sensors Market
Sensors and Controls
US Digital Thermometer Market
Sensors and Controls
Current Transducer Market
Sensors and Controls
APAC Acoustic Sensors Market
Sensors and Controls
Microseismic Monitoring Technology Market
Sensors and Controls
Thermal Anemometer Market
Sensors and Controls
Millimeter Wave Sensors and Modules Market
Sensors and Controls
MEMS Pressure Sensors Market
Sensors and Controls
Global Level Sensors Market
Sensors and Controls
Solid Flow Rate Valve Control Market
Sensors and Controls
United States Proximity Sensor Market
Sensors and Controls
China Digital Thermometer Market
Sensors and Controls
Global Printed Sensor Market
Sensors and Controls
Inductive Proximity Sensors Market
Sensors and Controls
North America Sensor Market
Sensors and Controls
Automotive Image Sensors Market