
 Germany Digital Thermometer Market | 2026-2036
Germany Digital Thermometer Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Digital Thermometer Market Insights
Equipment leasing and pay-per-use arrangements for clinical-grade temperature monitoring systems is rewriting competitive dynamics for mid-sized manufacturers. Testo SE & Co. KGaA leverages its calibration service network to anchor long-term hospital contracts. Geratherm Medical AG specializes in dual-scale clinical-home crossover designs that occupy a defensible niche. PCE Deutschland GmbH competes on rapid fulfillment for industrial and medical channel partners.
A digital thermometer is an electronic temperature measurement instrument employing thermistors, thermocouples, or infrared sensors to quantify thermal radiation or conductive heat, typically displaying readings within 0.1°C resolution on LCD or LED interfaces; its primary function spans clinical diagnostics, industrial process control, food safety verification, and environmental monitoring. Infrared units lead hospital procurement volumes due to non-contact hygiene protocols, while Bluetooth-enabled smart thermometers represent the fastest-expanding technology segment as home care platforms integrate continuous temperature logging. Standard digital models retain dominant household penetration, though margin pools concentrate in wireless clinical systems certified for ward-level data transmission.
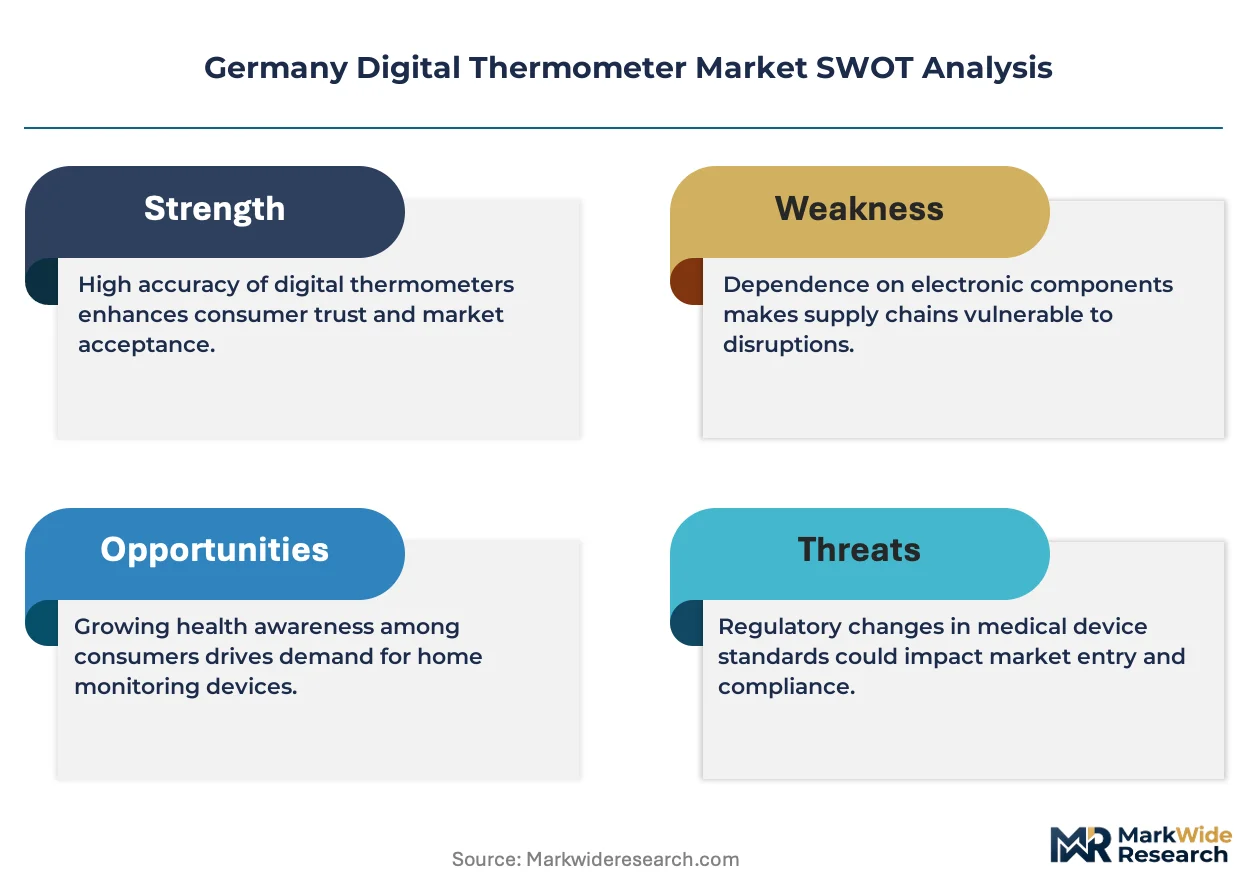
Germany's Medical Device Regulation (MDR) implementation, supervised by BfArM and notified bodies, mandates enhanced clinical evidence and post-market surveillance for Class IIa temperature monitors, elevating compliance costs but filtering non-compliant imports. The country's national metrology institute (PTB) enforces calibration traceability standards that shape procurement specifications for clinical buyers. Stakeholders must monitor evolving cybersecurity requirements for connected thermometers as BSI guidance on networked medical devices hardens.
Market Dynamics
German hospital procurement officers now prioritize contactless infrared thermometers with ward-integrated data logging, a shift driven by MDR-mandated infection control documentation and Bavaria's sensor manufacturing concentration.
Growth Catalysts
- MDR compliance mandates:Updated Medical Device Regulation requirements from BfArM enforce post-market surveillance for Class IIa temperature monitors, filtering non-compliant imports and elevating certified domestic suppliers.
- Home care platform integration:Bluetooth-enabled smart thermometers connect to telemedicine dashboards, expanding addressable demand beyond clinical settings into remote patient monitoring networks.
- Bavaria sensor corridor:Precision thermistor and infrared detector manufacturing clusters around Munich and Nuremberg reduce lead times for German OEMs serving Central European hospital systems.
Market Restraints
- Calibration infrastructure costs:PTB traceability requirements for clinical-grade devices impose recurring metrology expenses that squeeze margins on mid-volume production runs.
- Semiconductor input volatility:Discrete sensor chips and microcontrollers face supply concentration risks from Asian foundry networks, disrupting assembly schedules for German device manufacturers.
- Disposable probe substitution:Single-use temperature strips and disposable thermocouple probes compete for routine screening applications in outpatient clinics, limiting unit economics for reusable digital systems.
Strategic Opportunities
- Baden-Württemberg industrial IoT:Factory automation and process control sectors in Stuttgart's manufacturing belt underutilize calibrated infrared thermometers for predictive maintenance monitoring.
- BSI cybersecurity guidance:Hardening standards for networked medical devices create first-mover advantages for German manufacturers building encrypted data transmission into ward-level temperature systems.
- Pay-per-use leasing models:Equipment-as-a-service arrangements for clinical temperature monitoring allow mid-sized hospitals to access premium infrared systems without capital expenditure commitment.
Industry Challenges
- Embedded systems engineering scarcity:Firmware development for BLE-enabled thermometers requires rare combinations of medical device regulation knowledge and wireless protocol expertise, constraining product roadmap velocity.
- MDR technical documentation timelines:Clinical evidence compilation and notified body review cycles for Class IIa certification extend 18-24 months, delaying revenue recognition for new product variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Digital Thermometer Market |
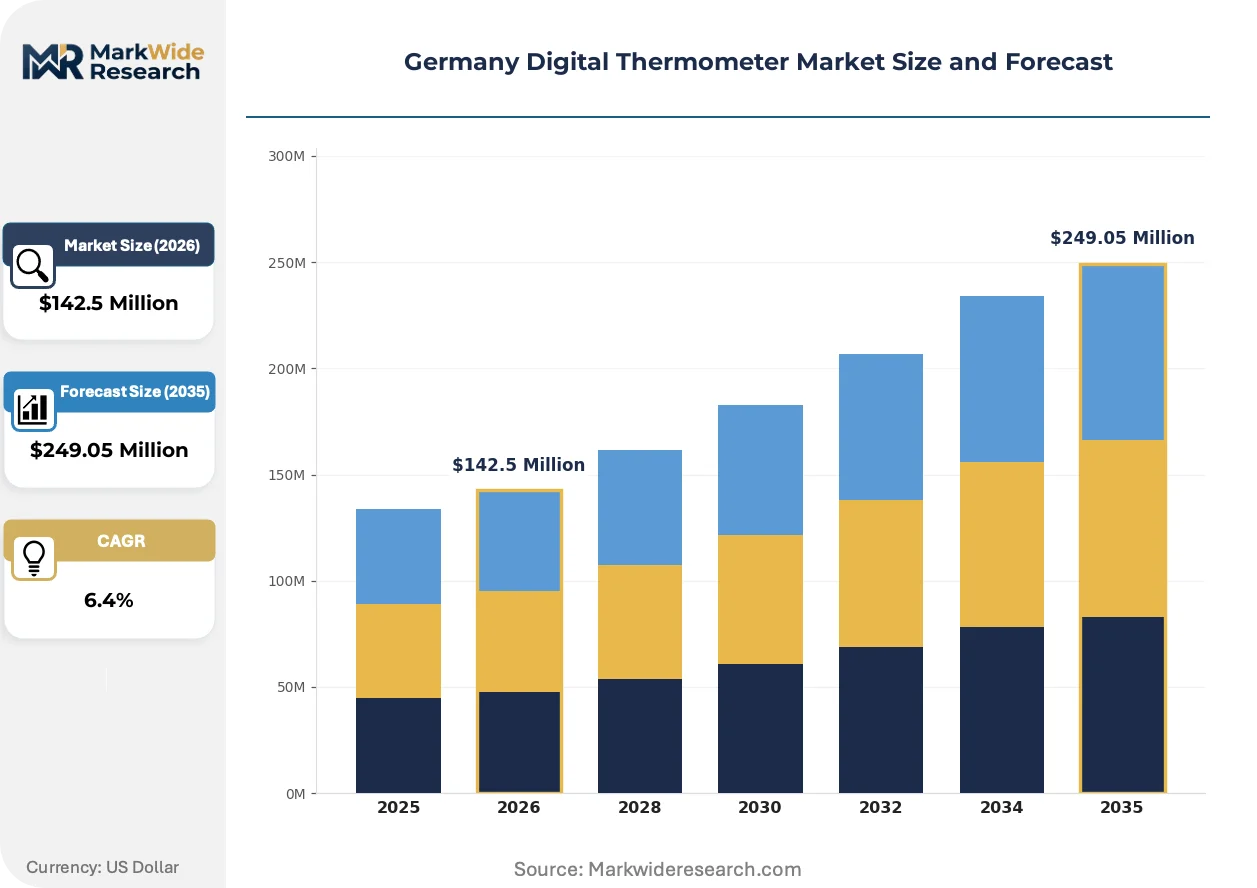
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $249.05 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infrared, Ear, Oral, Rectal End User: Households, Hospitals, Clinics, Laboratories Application: Fever Monitoring, Home Care, Pediatric Use, Sports Technology: Wireless, Bluetooth, Smart Thermometers, Standard Digital |
| Companies Covered | Geratherm Medical AG, Testo SE & Co. KGaA, Amarell GmbH & Co. KG, Thermo Fisher Scientific GmbH, AFRISO-EURO-INDEX GmbH, Ahlborn Mess- und Regelungstechnik GmbH, PCE Deutschland GmbH, WIKA Alexander Wiegand SE & Co. KG, Ashcroft Instruments GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Digital Thermometer Market Trends and Innovations
Temperature sensing technology in Germany is converging around three vectors: sensor miniaturization enabling non-invasive continuous monitoring, regulatory digitization of compliance workflows, and procurement model experimentation disrupting traditional device ownership.
Infrared thermopile arrays with MEMS fabrication is migrating from spot-measurement guns to continuous skin-patch monitors. University hospital neonatal intensive care units in Heidelberg and Berlin pilot these systems for thermoregulation surveillance. The technology is compressing measurement intervals from episodic spot checks to real-time data streams, forcing ward IT infrastructure upgrades.
MDR Article 10 technical documentation requirements now mandate clinical evaluation reports and post-market clinical follow-up plans for all Class IIa temperature monitors. German notified bodies have extended review queues, causing manufacturers to front-load biocompatibility and electromagnetic testing. Smaller OEMs without dedicated regulatory affairs functions face consolidation pressure or partnership dependence.
Hospital buying committees now unbundle device procurement from calibration service contracts, treating temperature monitoring as operational expenditure rather than capital equipment. This purchasing pattern shift favors Testo SE and similar service-network incumbents who can bundle hardware with PTB-traceable annual recalibration. The model is most visible in North Rhine-Westphalia's hospital procurement alliances, where shared service organizations negotiate multi-site equipment leases.
Germany Digital Thermometer Market Segmentation
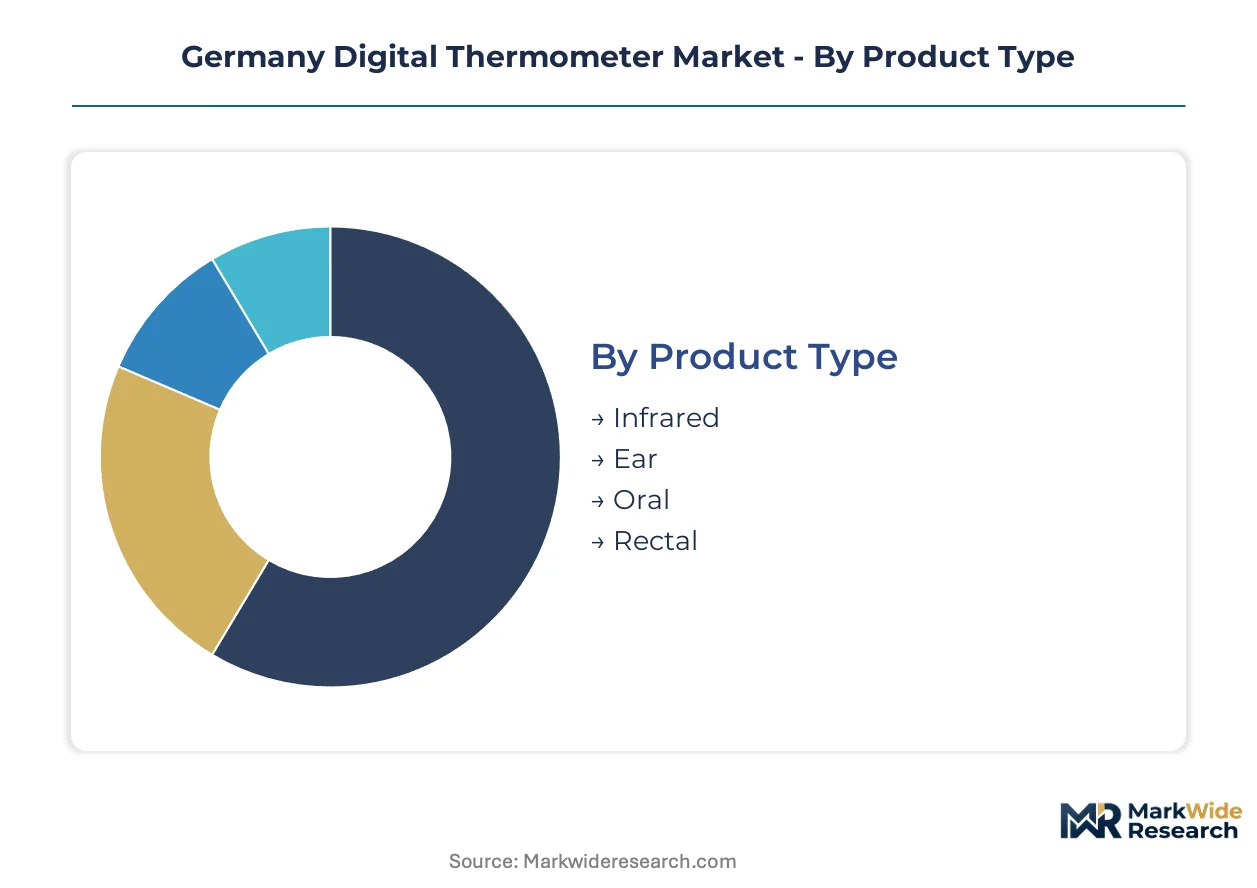
Digital thermometer segmentation in Germany reflects divergent clinical standards, consumer price sensitivity, and regulatory complexity across use environments. Product architecture, connectivity protocols, and end-user procurement power create distinct margin pools that manufacturers must navigate simultaneously.
Product Type:
Mature contact-based formats coexist with emerging non-contact technologies as MDR compliance reshapes hospital procurement specifications.
- Infrared:Thermopile sensors detect thermal radiation from temporal arteries or skin surfaces without physical contact. Bavarian hospital procurement alliances specify these units for infection control protocols under updated BfArM surveillance requirements.
- Ear:Tympanic membrane measurement via infrared probes delivers core temperature approximations in 1-2 seconds. Pediatric departments in Berlin and Munich university hospitals favor this format for speed-critical screening workflows.
- Oral:Sub-lingual thermistor probes remain the default household standard due to sub-€20 price positioning and familiar operation protocols.
- Rectal:Precision thermocouple assemblies serve neonatal intensive care and pre-surgical baselines where core temperature accuracy overrides patient discomfort considerations.
Oral thermometers retain volume leadership; infrared devices hold the steepest expansion curve.
End User:
Cost tier stratification separates capital-intensive institutional buyers from price-elastic consumer segments with diverging service expectations.
- Hospitals:Ward-integrated systems with PTB-traceable calibration cycles and MDR Class IIa certification dominate procurement specifications. North Rhine-Westphalia hospital alliances negotiate multi-site equipment leases bundling hardware with annual metrology services.
- Households:Bluetooth-enabled smart thermometers with smartphone app integration command premium positioning in urban centers. Telemedicine platform partnerships in Hamburg and Frankfurt expand remote monitoring use cases.
- Clinics:Outpatient facilities balance disposable probe substitution risks against reusable digital unit economics for routine fever screening.
- Laboratories:Calibrated reference thermometers with 0.01°C resolution support pharmaceutical stability testing and industrial process validation in Baden-Württemberg manufacturing clusters.
Hospitals drive premium revenue concentration; households deliver the broadest unit volume base.
Application:
Volume distribution across applications tracks demographic health priorities and seasonal demand patterns with distinct technology requirements.
- Fever Monitoring:Epidemiological surveillance integration demands encrypted data transmission and ward-level EMR connectivity. Heidelberg university hospital pilots real-time temperature streaming for sepsis early warning systems.
- Home Care:Post-acute discharge protocols and chronic disease management platforms in Bavaria create recurring demand for patient-operated devices with caregiver dashboard sharing.
- Pediatric Use:Rapid measurement speed and non-invasive formats dominate parent purchasing criteria for infant and toddler applications.
- Sports:Core temperature monitoring for endurance athletes and occupational heat stress programs represents a niche industrial segment with specialized data logging requirements.
Fever monitoring commands institutional procurement budgets; home care applications are climbing the fastest.
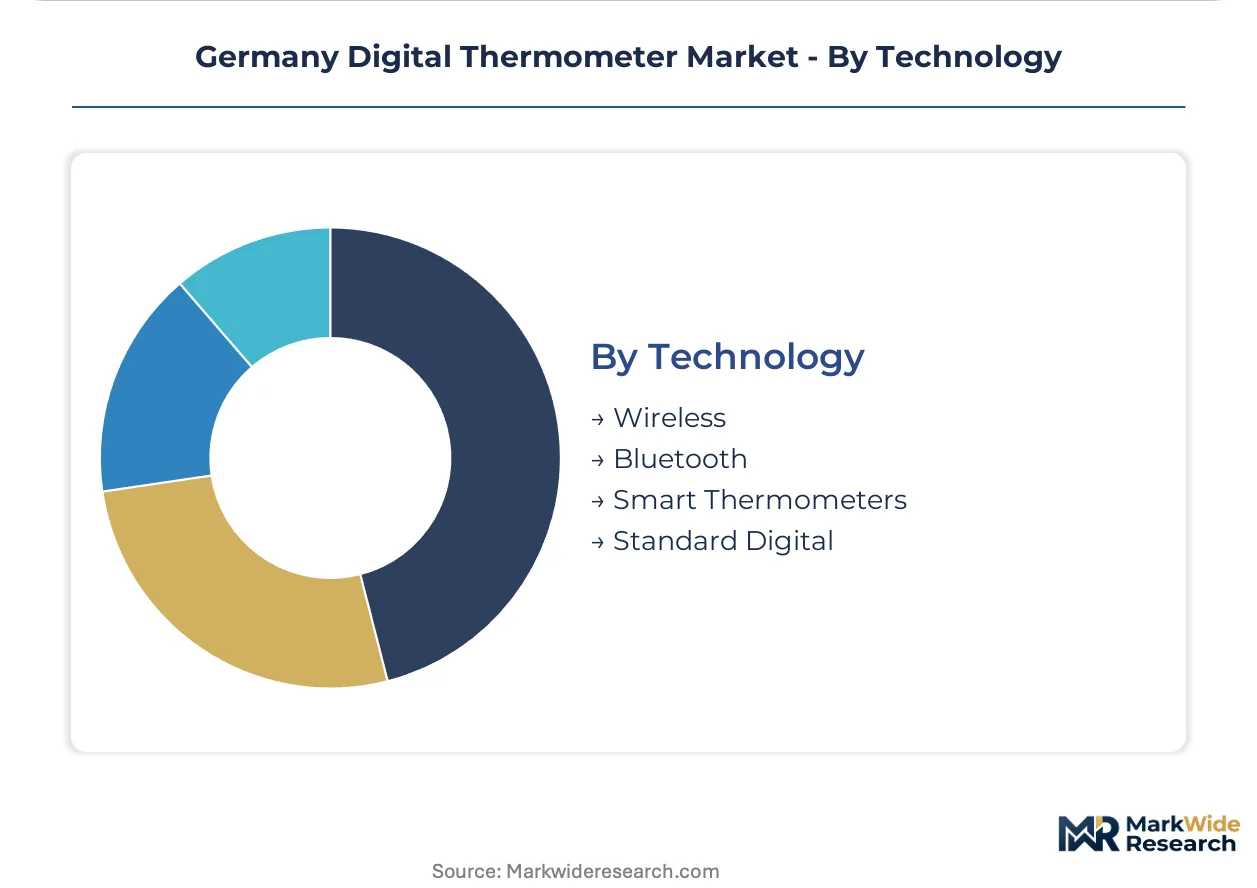
Technology:
Supply concentration in wireless protocol stacks and sensor miniaturization creates capability scarcity that constrains product roadmap velocity for smaller OEMs.
- Smart Thermometers:AI-powered trend analysis and symptom correlation algorithms differentiate premium consumer offerings. Firmware development combines medical device regulation expertise with machine learning pipeline engineering.
- Bluetooth:BLE 5.0 connectivity enables continuous logging with smartphone bridge functionality. BSI cybersecurity guidance for networked medical devices shapes encryption implementation requirements.
- Wireless:WiFi-enabled ward systems with centralized nurse station dashboards support hospital infection control documentation mandates under MDR post-market surveillance protocols.
- Standard Digital:LCD-display thermistors without connectivity features retain dominant household penetration through pharmacy retail channels and sub-€15 price positioning.
Standard digital units retain volume leadership; smart thermometers hold the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Updated MDR compliance mandates from BfArM are redirecting procurement flows toward domestic German manufacturers with established PTB calibration networks, while regional hospital alliances in North Rhine-Westphalia pioneer equipment-as-a-service contracting models that reshape capital deployment patterns across Central European healthcare systems.
North Rhine-Westphalia
Hospital procurement alliances in Cologne and Düsseldorf negotiate multi-site equipment leases bundling infrared thermometers with annual PTB-traceable recalibration services. BfArM's MDR enforcement elevates compliance costs for Class IIa devices, filtering smaller import competitors. The Ruhr Valley medical device service corridor concentrates third-party metrology providers supporting ward-integrated temperature monitoring systems.
Bavaria
Precision thermistor and infrared detector manufacturing clusters around Munich and Nuremberg reduce component lead times for domestic OEMs serving university hospital systems. BSI cybersecurity guidance for networked medical devices shapes firmware development requirements for Bluetooth-enabled clinical thermometers. The Medical Valley Erlangen anchors sensor miniaturization R&D for continuous monitoring applications.
Baden-Württemberg
Stuttgart's industrial automation belt underutilizes calibrated infrared thermometers for predictive maintenance in factory process control. MDR documentation requirements for clinical evidence compilation extend product development timelines for device manufacturers without dedicated regulatory affairs functions. The Karlsruhe technology region hosts embedded systems engineering talent pools scarce across European medical device sectors.
Berlin-Brandenburg
Telemedicine platform partnerships in Berlin expand remote patient monitoring use cases for Bluetooth-enabled smart thermometers with caregiver dashboard sharing. Charité university hospital pilots real-time temperature streaming for sepsis early warning systems integrating with EMR infrastructure. The Adlershof technology park concentrates health IT startups bridging consumer wearable and clinical-grade device boundaries.
Hamburg
Port logistics and maritime occupational health programs create specialized demand for core temperature monitoring devices in heat stress prevention applications. The city's health economy cluster supports pilot programs for post-acute discharge protocols using patient-operated temperature devices. BfArM's post-market surveillance databases track device performance across northern German hospital networks.
Germany Digital Thermometer Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability tiers: multinational precision instrument conglomerates with embedded medical divisions, mid-sized German family-owned manufacturers with deep calibration service networks, and specialized sensor technology firms with industrial-to-medical crossover expertise. Strategic archetypes include the full-service hospital contractor, the component-scale precision specialist, and the industrial-channel fast follower. Dominant competitive moves center on backward integration into sensor assembly capacity and pay-per-use leasing model deployment.
Among German-based precision instrument manufacturers, Testo SE & Co. KGaA and Geratherm Medical AG exemplify contrasting strategic positions within the domestic supply base. Testo anchors the full-service hospital contractor archetype through its calibration infrastructure footprint, while Geratherm occupies the clinical-home crossover specialist tier with dual-scale product architectures. PCE Deutschland GmbH represents the industrial-channel fast follower model competing on fulfillment velocity for non-clinical applications. These three manufacturers collectively illustrate the capability segmentation defining competitive dynamics under tightening MDR compliance regimes.
| Leading Market Players |
|---|
| Geratherm Medical AG |
| Testo SE & Co. KGaA |
| Amarell GmbH & Co. KG |
| Thermo Fisher Scientific GmbH |
| AFRISO-EURO-INDEX GmbH |
| Ahlborn Mess- und Regelungstechnik GmbH |
| PCE Deutschland GmbH |
| WIKA Alexander Wiegand SE & Co. KG |
| Ashcroft Instruments GmbH |
| Others |
Pricing and Supply Chain Analysis
Asian foundry concentration for thermopile sensors and microcontroller chips concentrates upstream bargaining power with Taiwan and South Korean semiconductor suppliers, compressing margin pools for German device assemblers while shifting value capture toward calibration service bundling and MDR-certified system integrators downstream.
Pricing Analysis
Certification level creates the primary spread between clinical-grade and consumer-tier offerings, with MDR Class IIa ward-integrated systems commanding substantial premiums over standard digital household units. Three-tier pricing structure across premium, standard, and economy levels separates PTB-traceable hospital contracts from pharmacy retail channels and unbranded import substitutes. Pricing pressure stems from disposable probe substitution in outpatient screening workflows, squeezing unit economics for reusable digital formats. Household segments exhibit highest price sensitivity, while hospital procurement alliances prioritize total cost of ownership over per-unit acquisition costs.
Supply Chain Analysis
Contract manufacturing capacity for precision thermistor assemblies concentrates with Bavarian sensor specialists and select East Asian EMS providers serving medical device OEMs. Component sourcing draws from Taiwan for infrared detector chips, China for LCD display modules, and Germany for precision calibration equipment. Single-source vulnerability around thermopile sensor foundries exposes assembly schedules to geopolitical disruption and allocation rationing. Distribution runs through hospital procurement alliances in North Rhine-Westphalia, pharmaceutical wholesale channels for retail pharmacy placement, and direct industrial sales for Baden-Württemberg manufacturing clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through multi-site hospital procurement alliances that unbundle hardware from service contracts, fragmenting traditional manufacturer pricing authority and elevating vendors with integrated calibration networks.
For Market Incumbents: Build regulatory compliance moats through captive notified body relationships and front-loaded MDR technical documentation capacity. Deepen backward integration into precision thermistor manufacturing to reduce lead time exposure from Asian sensor foundries. Secure long-term calibration service contracts with North Rhine-Westphalia hospital alliances before competitive entrants replicate the bundled offering. For New Entrants and Emerging Players: Pursue white-space positioning in Baden-Württemberg industrial IoT applications where calibrated infrared thermometers remain underdeployed for predictive maintenance monitoring. Target Stuttgart manufacturing belt facilities with equipment-as-a-service pricing that bypasses capital expenditure approval cycles. Establish telemedicine platform partnerships in Berlin-Brandenburg for Bluetooth-enabled home care integration. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across MDR-certified device manufacturing as clinical evidence compilation and post-market surveillance infrastructure become mandatory fixed costs. Favor acquisition targets with established PTB-traceable calibration networks and existing notified body relationships over pure hardware assemblers. Monitor BSI cybersecurity guidance implementation timelines as an inflection signal for connected thermometer compliance premiums.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Front-Loading | Accelerated clinical evidence compilation reduces notified body queue exposure for Class IIa certification. |
| Calibration Service Network Expansion | PTB-traceable annual recalibration bundling captures recurring revenue from hospital procurement alliances. |
| Cybersecurity Firmware Investment | BSI-compliant encrypted data transmission creates first-mover advantage in ward-integrated systems. |
| Industrial IoT Channel Development | Baden-Württemberg manufacturing belt penetration diversifies revenue beyond clinical saturation. |
| Telemedicine Platform Integration | Bluetooth-enabled dashboard connectivity expands addressable demand into remote patient monitoring networks. |
Research Methodology
A standing panel of hospital procurement officers, biomedical engineering directors, GPO contracts managers, and calibration service technicians provided ongoing calibration of demand assumptions and pricing benchmarks. Primary fieldwork combined structured interviews with secondary validation against BfArM device registrations, PTB calibration certification databases, hospital procurement alliance contract disclosures, and Bavarian medical device manufacturing cluster employment data. Bottom-up unit economics modeling triangulated against top-down market sizing from trade flow analysis and sector revenue aggregates.
Scenario-bracketing around MDR implementation timelines and semiconductor supply volatility generated bounded projection ranges across the modeling period. Segmentation dimensions included product architecture, connectivity protocol, end-user procurement tier, and regional hospital alliance membership. CAGRs derived from fitted growth curves applied to validated baseline estimates, with cross-reference to sensor component demand trends and clinical installation rates.
Sensitivities concentrate around notified body review queue extensions, thermopile sensor allocation disruptions, and BSI cybersecurity guidance enforcement intensity. Forecasts reflect documented assumptions regarding MDR compliance cost trajectories and hospital capital expenditure recovery patterns. Quarterly review of BfArM registration approval rates and Bavarian sensor foundry order backlogs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Air Flow Monitoring System Market
Sensors and Controls
PM2.5 Sensors Market
Sensors and Controls
Global Hazardous Location Thermostats Market
Sensors and Controls
Photoelectric Sensor Market
Sensors and Controls
Temperature Monitoring System Market
Sensors and Controls
MEMS-Based IMU Market
Sensors and Controls
Occupancy Sensor Market
Sensors and Controls
Wearable Thermometers Market
Sensors and Controls
China PV Monitoring Systems Market
Sensors and Controls
Photodiode Sensors Market
Sensors and Controls
Printed Antenna Market
Sensors and Controls
Middle East and Africa MEMS and Sensors Market
Sensors and Controls
Mexico Digital Thermometer Market
Sensors and Controls
ADAS Sensors Market
Sensors and Controls
Insulation Monitoring Devices (IMD) Market
Sensors and Controls
Global Pressure Calibrators Market