
 Sound Sensor Market | 2026-2036
Sound Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Sound Sensor Market Intelligence
Acoustic engineering talent is collapsing across Western Europe, forcing sensor makers to relocate R&D functions or automate calibration workflows. TDK Corporation leverages its MEMS fabrication expertise to sustain high-volume microphone output for consumer devices manufacturers. Knowles Corporation dominates precision audio capture for hearing health and voice recognition platforms. STMicroelectronics anchors industrial sensor supply through backward integration into piezoelectric material processing.
A sound sensor converts acoustic pressure waves into electrical signals through capacitive, piezoelectric, or MEMS transduction mechanisms, typically operating across frequency ranges from infrasonic to ultrasonic bands for detection, measurement, or control purposes. MEMS microphones command the largest revenue share due to smartphone integration density, while piezoelectric sensors capture expanding margins in structural health monitoring for industrial equipment producers. Digital signal processing architectures are displacing analog front-ends in security systems and environmental monitoring networks where multi-node arrays require synchronized data streams.
FCC equipment authorization rules govern RF-emitting sound sensors in US consumer electronics, while REACH restricts hazardous substances in European-sold piezoelectric ceramics and ECHA substance evaluations increasingly target lead-based compositions. The EU AI Act will classify voice recognition systems as high-risk when deployed in biometric identification contexts, forcing algorithmic transparency documentation from sensor-to-cloud pipelines. Stakeholders must monitor evolving substance restrictions and AI liability frameworks to anticipate compliance-driven product redesign cycles.
Market Dynamics
The automotive industry's pivot toward advanced driver-assistance systems is restructuring procurement priorities, forcing sensor suppliers to align output with ISO 26262 functional safety certification and real-time acoustic processing requirements.
Growth Catalysts
- EU Green Deal noise pollution mandates:Stricter decibel limits for urban environments are compelling municipalities across Germany, France, and the Netherlands to deploy networked environmental monitoring arrays.
- MEMS fabrication scale economies:Semiconductor foundries in Taiwan and South Korea are extending capacity reservations to audio MEMS, lowering unit costs for high-volume consumer electronics integration.
- Industrial predictive maintenance:Piezoelectric acoustic emission sensors are capturing structural fatigue signatures in rotating machinery, enabling condition-based intervention before catastrophic failure.
Market Restraints
- Piezoelectric ceramic input concentration:High-purity lead zirconate titanate supply chains cluster in Chinese material processors, exposing OEMs to export restriction volatility and ECHA substance evaluation timelines.
- RF interference susceptibility:Capacitive MEMS microphones operating near 2.4 GHz wireless bands require electromagnetic shielding that adds 15-20% to bill-of-material costs.
- Acoustic calibration labor scarcity:Western Europe's collapsing pool of qualified acoustic engineers extends R&D cycles and forces automation capital deployment.
Strategic Opportunities
- India industrial automation corridors:PLI scheme incentives for electronics manufacturing are attracting sensor module assembly investments in Tamil Nadu and Karnataka industrial zones.
- Voice biometric security integration:The EU AI Act's high-risk classification for biometric identification systems is creating demand for transparent, auditable sensor-to-cloud signal chains.
- Edge AI acoustic processing:Convergence of MEMS microphones with neural network accelerators enables on-device keyword spotting without cloud dependency, opening battery-constrained IoT deployments.
Industry Challenges
- Multi-standard certification complexity:Simultaneous FCC equipment authorization, CE marking, and REACH substance compliance extends product launch timelines by 8-14 months.
- Legacy analog infrastructure integration:Industrial facilities with 4-20 mA control loops require signal conditioning bridges that introduce latency incompatible with real-time safety applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sound Sensor Market |
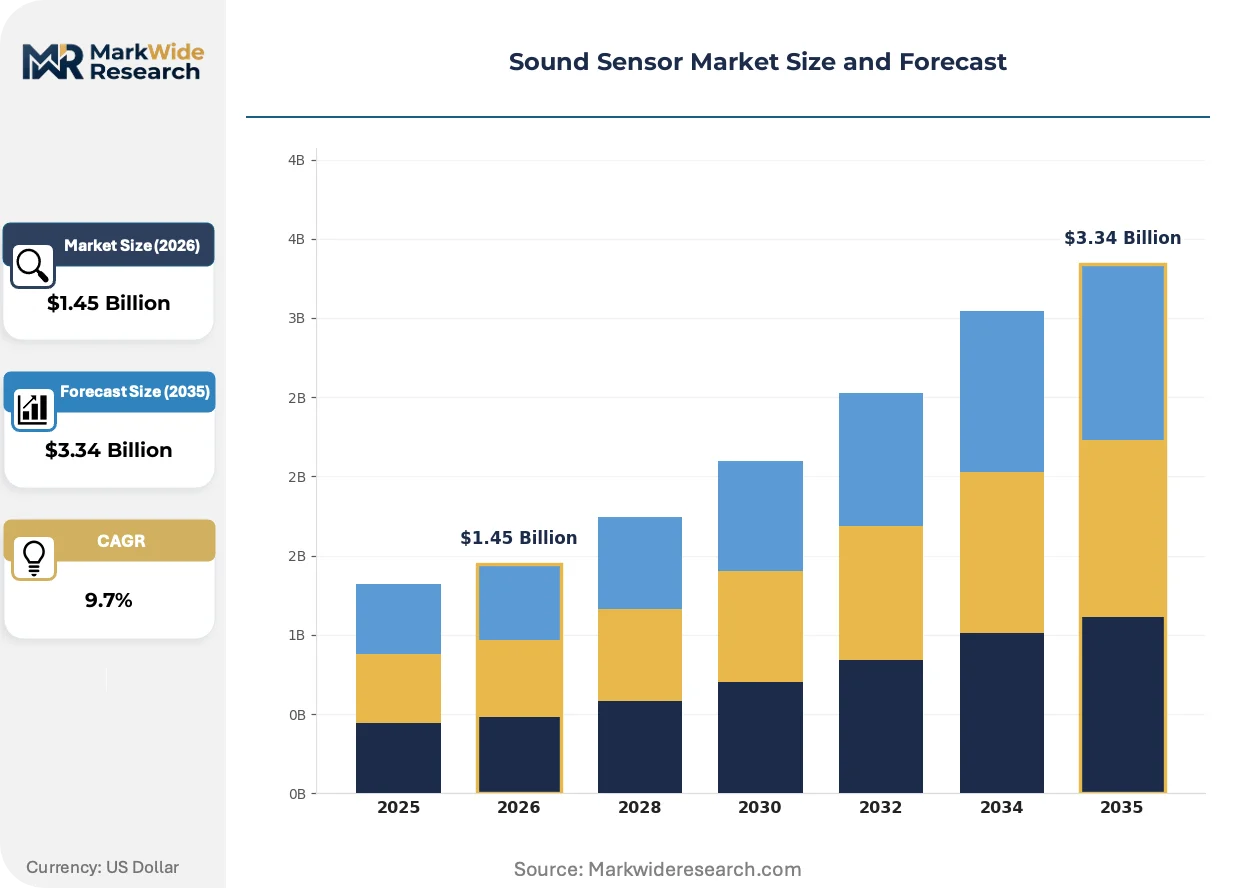
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $3.34 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microphone Array, Piezoelectric Sensor, Capacitive Sensor, MEMS Microphone, Electret Condenser Microphone Technology: Analog, Digital, Acoustic Wave, Ultrasonic, Optical, Fiber Optic Application: Consumer Electronics, Industrial Automation, Security Systems, Environmental Monitoring, Automotive Safety, Voice Recognition End User: Consumer Devices Manufacturers, Industrial Equipment Producers, Security Service Providers, Environmental Agencies, Vehicle Makers |
| Companies Covered | TDK Corporation, Analog Devices, STMicroelectronics, Siemens AG, Honeywell International Inc., Infineon Technologies, Knowles Corporation, Goertek, Murata Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sound Sensor Market Strategic Shifts & Innovations
Digital signal processing architectures are actively restructuring how acoustic data moves from transduction to decision, compressing the traditional analog-digital boundary and enabling synchronized multi-node arrays.
Beamforming microphone arrays with integrated digital signal processors are supplanting single-element analog microphones in security and conferencing applications. Corporate and institutional buyers are specifying steerable audio capture with spatial filtering in new construction projects. This supplanting is compressing margins for standalone analog microphone suppliers while rewarding silicon-integrated solution providers.
REACH substance restrictions and ECHA evaluations targeting lead-based piezoelectric compositions are forcing material reformulation across European-sold industrial sensors. Manufacturers are qualifying potassium sodium niobate alternatives that sacrifice sensitivity for regulatory compliance. German automotive OEMs are demanding full material disclosure documentation extending three tiers up the supply chain.
Acoustic sensor procurement is consolidating through tier-one electronics distributors who bundle calibration services with volume supply agreements. Original equipment manufacturers in consumer electronics are bypassing traditional component distributors to negotiate directly with MEMS foundries for smartphone program allocations. This channel compression is most pronounced in South Korea and Taiwan where foundry concentration enables direct engagement models.
Sound Sensor Market Segmentation
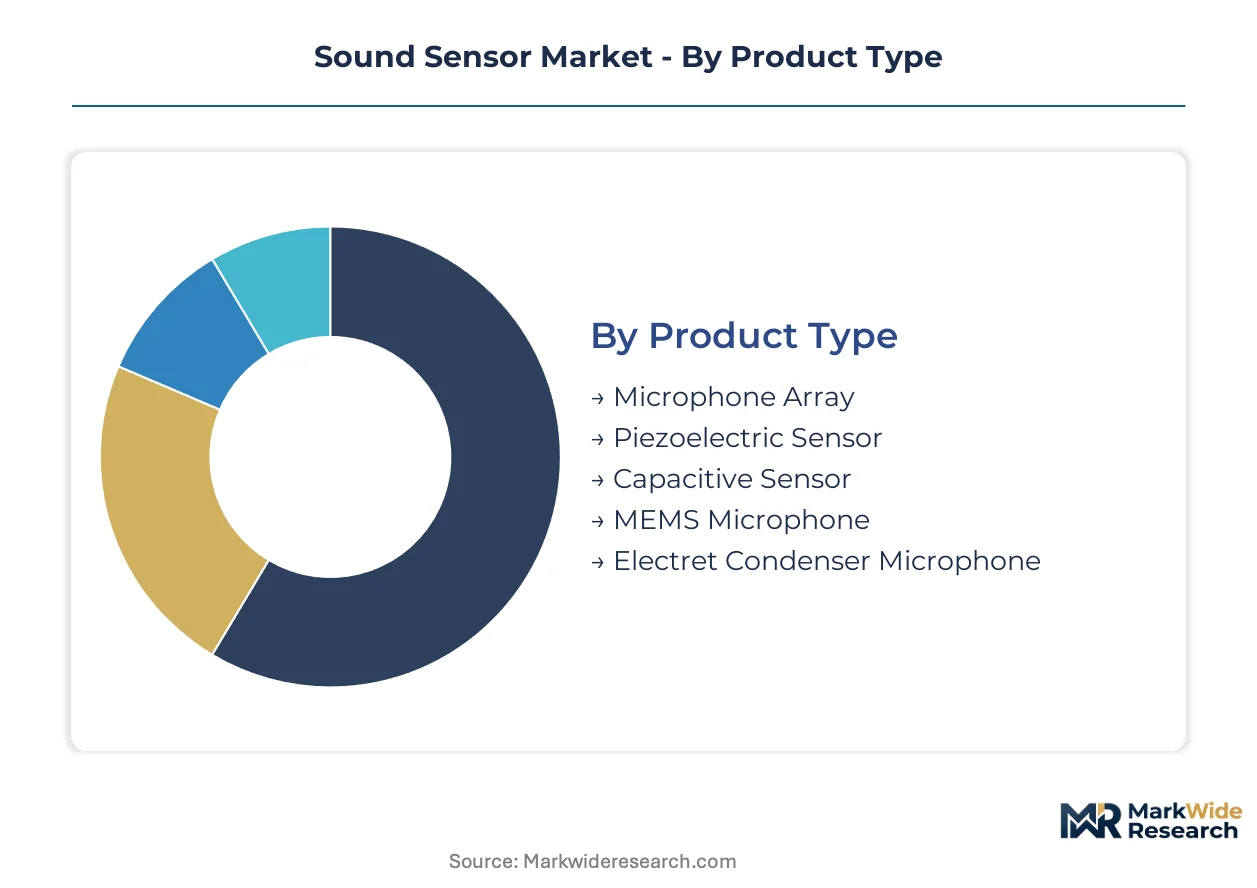
Sound sensor procurement patterns diverge sharply across transduction physics and signal processing architectures. Product type selection dictates foundry partnerships and calibration requirements. Application context determines certification burdens and integration complexity.
Product Type:
MEMS microphones face acute substitution pressure from capacitive alternatives in cost-sensitive consumer applications, while piezoelectric sensors defend position through material science barriers in industrial contexts.
- MEMS Microphone:Silicon-fabricated capacitive structures integrate analog-to-digital converters on-die, enabling direct digital audio output. Smartphone manufacturers in Taiwan and South Korea dominate procurement volumes, driven by beamforming array requirements for voice assistants. Unit economics from 300mm wafer scale sustain margin compression that electret alternatives cannot match.
- Piezoelectric Sensor:Lead zirconate titanate or potassium sodium niobate ceramics convert mechanical strain to electrical charge without external bias. German automotive OEMs and industrial automation clusters in Stuttgart and Munich specify these for structural health monitoring, where REACH compliance documentation now extends three supply chain tiers.
- Microphone Array:Spatially distributed elements with integrated beamforming algorithms enable directional audio capture.
- Capacitive Sensor:Parallel-plate architectures with fixed bias voltage serve cost-optimized single-channel applications.
- Electret Condenser Microphone:Permanently polarized dielectric films persist in legacy automotive and intercom installations.
MEMS microphones anchor the volume base while piezoelectric sensors gain share at the steepest rate in industrial predictive maintenance deployments.
Technology:
Digital signal architectures command premium pricing in multi-node synchronized arrays, whereas analog front-ends persist where latency tolerance permits simpler integration.
- Digital:Pulse-density modulation outputs eliminate analog routing noise and enable time-division multiplexing across dozens of nodes. Security system integrators in the Netherlands and France specify digital microphones for urban noise monitoring arrays mandated by EU Green Deal decibel limits.
- Ultrasonic:Transducers operating above 20 kHz enable non-contact distance measurement and material defect detection. Industrial equipment producers in Tamil Nadu and Karnataka deploy these for automated quality inspection lines under India's PLI scheme incentives.
- Analog:Continuous voltage output maintains compatibility with legacy 4-20 mA industrial control loops.
- Acoustic Wave:Surface or bulk wave propagation enables high-Q resonant sensing for precision frequency applications.
- Optical:Laser interferometry measures acoustic pressure through refractive index modulation.
- Fiber Optic:Intrinsic or extrinsic fiber configurations provide electromagnetic immunity for hazardous environments.
Analog technology retains the largest installed base while digital architectures expand most quickly in new environmental monitoring network deployments.
Application:
Automotive safety applications impose the steepest certification burdens, while consumer electronics drives the absolute volume scale that shapes foundry capacity allocation.
- Consumer Electronics:Smartphone, laptop, and wearable integration demands sub-millimeter package dimensions with automatic gain control. TDK Corporation and Knowles Corporation compete for design wins in voice recognition platforms where beamforming requires matched microphone pairs.
- Automotive Safety:Advanced driver-assistance systems require ISO 26262 ASIL-rated acoustic sensors for emergency vehicle detection and cabin monitoring. German vehicle makers in Wolfsburg and Munich specify these for level-2 autonomy feature sets.
- Industrial Automation:Condition monitoring of rotating machinery through acoustic emission analysis.
- Security Systems:Perimeter intrusion detection and gunshot localization networks.
- Environmental Monitoring:Urban noise mapping and wildlife acoustic census deployments.
- Voice Recognition:Far-field capture for smart speaker and automotive command interfaces.
Consumer electronics anchors the volume base while automotive safety gains share at the steepest rate as level-2 autonomy penetration deepens.
End User:
Vehicle makers concentrate procurement power through platform standardization, whereas environmental agencies fragment demand across municipal procurement jurisdictions.
- Vehicle Makers:Platform-level acoustic specifications span infotainment, hands-free calling, and advanced driver-assistance functions. German OEMs negotiate directly with MEMS foundries for multi-year program allocations, bypassing traditional component distributors.
- Industrial Equipment Producers:Predictive maintenance retrofits and original equipment integration for rotating machinery. Clusters in Stuttgart and Munich specify piezoelectric acoustic emission sensors with calibration certificates traceable to PTB standards.
- Consumer Devices Manufacturers:Smartphone, laptop, and wearable original design manufacturers.
- Security Service Providers:Private and municipal surveillance system integrators.
- Environmental Agencies:National and municipal noise pollution monitoring authorities.
Vehicle makers anchor the volume base while industrial equipment producers gain share at the steepest rate as condition-based maintenance replaces scheduled interventions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA substance evaluations and EU Green Deal decibel mandates are reshaping procurement patterns across European sound sensor markets, while Asian foundry concentration and North American automotive safety regulations create divergent demand clusters.
Germany
Automotive OEMs in Wolfsburg and Munich specify ISO 26262 ASIL-rated acoustic sensors for level-2 autonomy systems. REACH compliance documentation now extends three supply chain tiers for piezoelectric ceramics. Stuttgart industrial automation clusters drive premium sensor procurement for structural health monitoring applications.
United States
FCC equipment authorization rules govern RF-emitting sound sensors in consumer electronics and security networks. NHTSA safety mandates accelerate advanced driver-assistance system integration. Detroit automotive suppliers and Silicon Valley consumer device manufacturers concentrate procurement through tier-one electronics distributors.
China
High-purity lead zirconate titanate supply chains cluster in domestic material processors serving industrial sensor OEMs. MIIT standards for smart city deployments drive environmental monitoring array installations. Yangtze River Delta MEMS foundries extend capacity reservations to audio components for smartphone manufacturers.
South Korea
Semiconductor foundries negotiate directly with consumer electronics OEMs for multi-year microphone program allocations. MFDS medical device regulations shape hearing health sensor specifications. Seoul Capital Area electronics manufacturers dominate beamforming array procurement for voice recognition platforms.
India
PLI scheme incentives attract sensor module assembly investments in Tamil Nadu and Karnataka industrial zones. BIS certification requirements for industrial automation equipment extend product launch timelines. Mumbai and Pune automotive suppliers integrate acoustic emission sensors for predictive maintenance retrofits.
Sound Sensor Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with MEMS fabrication scale separating volume players from niche material science defenders. Consolidation pressure concentrates around automotive safety certification and foundry capacity allocation. Two archetypes dominate: silicon-integrated platform providers leveraging semiconductor scale, and piezoelectric material specialists defending regulatory-compliant industrial positions. Competitive moves center on backward integration into piezoelectric material processing and direct foundry engagement bypassing traditional distribution.
Among Asia-Pacific fabricators, TDK Corporation and Goertek exemplify the scale-driven MEMS platform tier, while Knowles Corporation occupies a position within precision audio capture specialists. STMicroelectronics anchors European industrial supply through captive material processing capabilities. These three represent divergent strategic postures: foundry-direct consumer volume, medical-grade precision specialization, and vertically integrated industrial durability.
| Leading Market Players |
|---|
| TDK Corporation |
| Analog Devices |
| STMicroelectronics |
| Siemens AG |
| Honeywell International Inc. |
| Infineon Technologies |
| Knowles Corporation |
| Goertek |
| Murata Manufacturing |
| Others |
Cost & Logistics Intelligence
Twelve-to-sixteen-week lead times for ISO 26262-certified MEMS microphones concentrate pricing power with Taiwan and South Korean foundries, while buyers in Stuttgart and Munich absorb premium markups for REACH-compliant piezoelectric documentation. This inventory compression rewards direct foundry engagement and punishes distributor-dependent procurement strategies.
Pricing Analysis
Price spreads between German automotive OEM specifications and consumer electronics procurement in Taiwan reach three-to-one multiples. Three-tier pricing structure across automotive-grade, industrial-certified, and consumer-level sensors separates ISO 26262 ASIL-rated units from standard MEMS alternatives. Cost compression in consumer-grade MEMS intensifies as Yangtze River Delta foundries extend capacity reservations. Industrial equipment producers in Stuttgart exhibit lowest price sensitivity due to predictive maintenance ROI requirements.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for MEMS microphones, while China clusters high-purity lead zirconate titanate processing for piezoelectric ceramics. Raw material dependencies include 300mm silicon wafers, PZT ceramics, and potassium sodium niobate alternatives. Single-source vulnerability concentrates in Chinese material processors facing ECHA export evaluation timelines. Distribution runs through tier-one electronics distributors who bundle calibration certificates with volume agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must defend against optical acoustic sensors and fiber-based alternatives encroaching on hazardous environment applications where electromagnetic immunity commands premium positioning.
For Market Incumbents: Secure captive piezoelectric material processing in Germany or Eastern Europe to insulate against Chinese export restriction volatility. Deepen backward integration into MEMS foundry partnerships in Taiwan, bypassing distributor markups for automotive program allocations. ISO 26262 certification investment separates defensible premium tiers from commodity MEMS substitution.
For New Entrants and Emerging Players: CE marking fast-track through notified body pre-submission opens white-space in EU environmental monitoring arrays mandated by Green Deal decibel limits. Target Tamil Nadu and Karnataka industrial zones under India's PLI scheme where BIS certification gaps delay incumbent product launches. Lead with edge AI acoustic processing modules for battery-constrained IoT deployments.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with undermonetized acoustic emission sensor divisions. Five-to-ten-year viability hinges on regulatory compliance automation rather than raw sensitivity performance. Watch ECHA substance evaluation timelines as inflection indicators for material reformulation capex cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Piezoelectric Processing | German automotive OEMs now demand three-tier material disclosure documentation upstream. |
| Direct Foundry Engagement Model | Taiwanese MEMS fabricators negotiate program allocations bypassing traditional component distributors. |
| Edge AI Acoustic Module Development | Neural network accelerators paired with MEMS enable on-device processing without cloud dependency. |
| REACH-Compliant Material Reformulation | Potassium sodium niobate alternatives sacrifice sensitivity for ECHA evaluation compliance. |
| Calibration Service Bundling | Tier-one distributors capture margin through acoustic calibration certificates traceable to PTB standards. |
Research Approach
Operator-level perspectives from MEMS foundry engineers, automotive Tier 1 procurement managers, industrial maintenance directors, and acoustic calibration specialists anchored the qualitative base. Primary interviews combined with secondary validation from SEC 10-K filings, ECHA substance evaluation registers, EU Green Deal implementation reports, and Taiwan semiconductor capacity disclosure data. Bottom-up sensor shipment estimates triangulated against top-down automotive electronics content analysis.
Sensitivity analysis tested forecast outputs against foundry capacity expansion scenarios and REACH restriction timelines across the projection horizon. Segmentation dimensions modeled include transduction physics, signal processing architecture, application certification tier, and regional regulatory cluster. CAGRs derived from shipment volume trajectories weighted by average selling price bands specific to automotive safety versus consumer electronics procurement.
Underlying assumptions cover sustained EU Green Deal enforcement, stable Taiwan-South Korea foundry output, and gradual PZT material substitution, with deviation risk concentrated in Chinese export restriction volatility and acoustic engineering labor scarcity. Recalibration cycles align with ECHA evaluation publication schedules and major automotive platform launch windows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Europe Pressure Sensors Market
Sensors and Controls
Eye Tracking Systems Market
Sensors and Controls
Asia-Pacific Wireless Brain Sensors Market
Sensors and Controls
Contact Steering Torque Sensor Market
Sensors and Controls
Ultrasonic Sensors Market
Sensors and Controls
Silicon-Based Fingerprint Sensors Market
Sensors and Controls
Nano Positioning System Market
Sensors and Controls
Global Nanosensors Market
Sensors and Controls
Nanopositioning Piezo Actuator Market
Sensors and Controls
Acoustic Sensors Market
Sensors and Controls
Automotive MEMS Market
Sensors and Controls
Global Ultrasonic Gas Leak Detector Market
Sensors and Controls
Asia-Pacific Industrial Control System Market
Sensors and Controls
Chemical Sensors Market
Sensors and Controls
Automation Control Components and Devices Market
Sensors and Controls
Safety Laser Scanner Market