
 Surface Inspection Market | 2026-2036
Surface Inspection Market Size, Share, and Industry Trends Forecast 2026-2036
Surface Inspection Market Outlook
ISO 9001 quality management certification is rotating the competitive landscape toward vendors with documented metrology traceability. Cognex Corporation leverages machine vision software ecosystems to sustain pricing power in high-throughput electronics inspection. Basler AG anchors European demand through specialized industrial camera portfolios. Keyence Corporation dominates direct sales channels across Asian manufacturing clusters with integrated sensor-to-software platforms.
Surface inspection encompasses non-destructive evaluation of material topography, coating integrity, and geometric conformity using optical, laser, or acoustic sensing modalities with sub-micron resolution thresholds. Its primary purpose is eliminating defective units before downstream assembly, thereby reducing warranty exposure and material scrap in precision manufacturing. Camera-based image processing leads installed base volumes due to mature CMOS supply chains and falling per-pixel costs, while laser scanning captures expanding share in dimensional gauging of turbine blades and battery electrodes. Cloud-based deployment remains nascent but attracts quality-control departments seeking centralized defect pattern libraries across distributed plants.
FDA medical device quality system regulations and EU Machinery Directive safety standards mandate validated inspection protocols for implantable components and automated production lines. REACH substance restrictions further shape sensor housing material selection and lubricant chemistry in European installations. Stakeholders must monitor convergence between AI-driven anomaly detection and evolving cybersecurity frameworks for connected factory architectures.
Market Dynamics
Semiconductor fabs in Taiwan and South Korea are compressing inspection cycle times to match wafer-level throughput scaling, forcing equipment vendors to decouple hardware refresh rates from software upgrade paths.
Growth Catalysts
- EU Machinery Directive safety mandates:Automated production lines across European automotive stamping plants now require validated surface inspection protocols, expanding replacement demand for legacy gauging stations.
- CMOS sensor resolution thresholds:Sub-micron defect detection in battery electrode manufacturing is pulling 12-megapixel and higher camera configurations into standard specifications for EV supply chains.
- East Asian electronics corridors:Contract manufacturers in Shenzhen and Ho Chi Minh City are consolidating inspection stations to reduce headcount in final assembly verification.
Market Restraints
- Specialized optical component supply:German and Japanese precision lens suppliers control critical coating technologies, exposing equipment builders to single-source pricing volatility.
- Deep learning model training costs:Semiconductor fabs face six-figure outlays for labeled defect datasets before deploying AI-driven anomaly detection at production scale.
- Acoustic sensing substitution:Ultrasonic thickness gauging captures share in pipeline weld inspection where surface roughness tolerances are relaxed.
Strategic Opportunities
- Cloud-based defect pattern libraries:Quality-control departments in distributed plant networks are piloting centralized training data repositories to reduce per-site model development overhead.
- India PLI scheme for electronics:Smartphone and component manufacturing incentives are attracting first-time inspection equipment deployments in Noida and Sriperumbudur clusters.
- AI-cybersecurity framework convergence:Connected factory architectures create openings for vendors bundling anomaly detection with IEC 62443-compliant network segmentation.
Industry Challenges
- Multi-modal system integration:Combining optical, laser, and acoustic sensing modalities requires scarce mechatronics expertise that OEMs struggle to retain.
- ISO 9001 metrology traceability documentation:Certification timelines stretch 12-18 months for vendors without existing quality management infrastructure.
- Legacy MES compatibility:Brownfield semiconductor fabs face protocol translation costs when retrofitting inspection stations into 1990s-era manufacturing execution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surface Inspection Market |
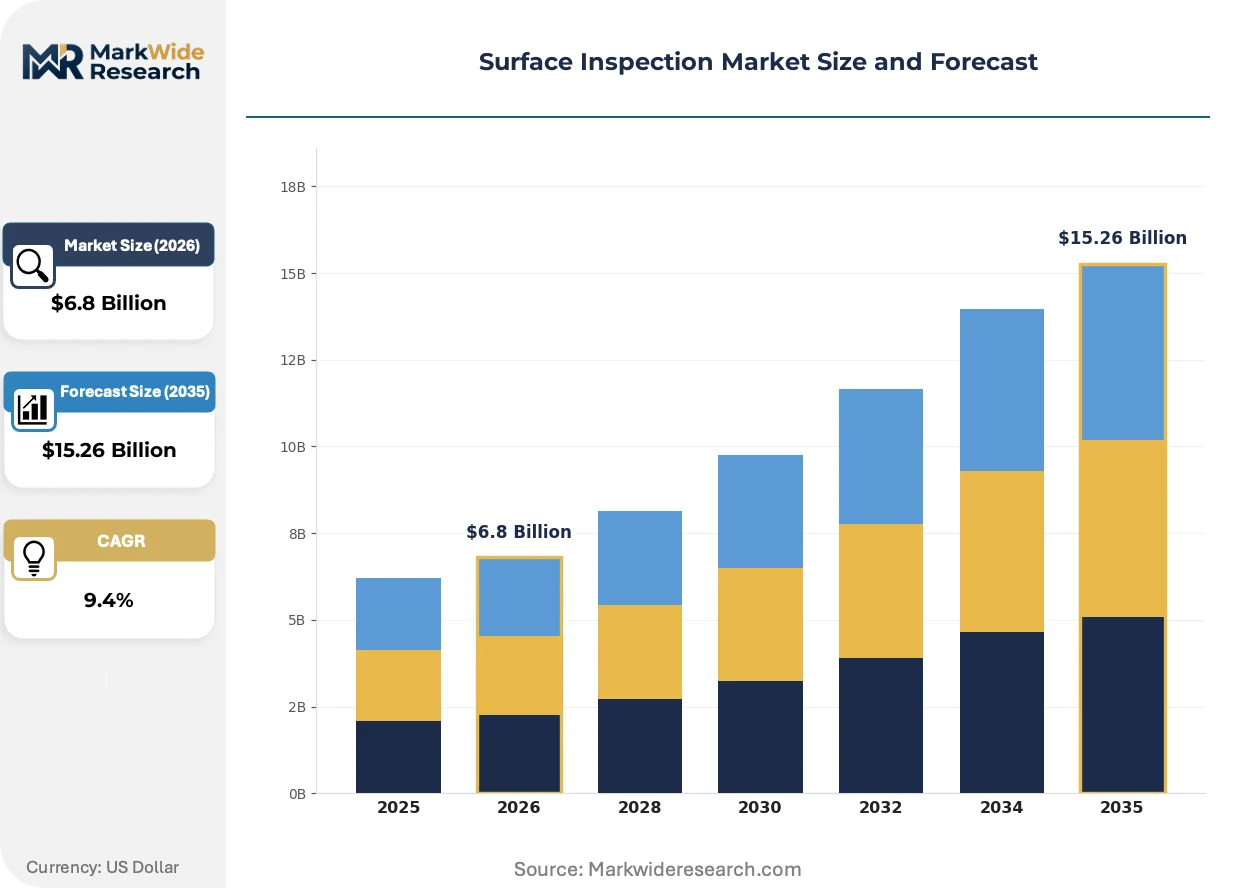
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Image Processing, Laser Scanning, Ultrasonic Testing, Visual Inspection Application: Aerospace Components, Automotive Parts, Electronics Manufacturing, Metal Fabrication End User: Manufacturers, Quality Control Departments, Research Institutions, OEMs Deployment: On-Premises, Cloud-Based, Hybrid, Mobile Solutions |
| Companies Covered | ISRA Vision, Panasonic Corporation, Cognex Corporation, AMETEK Surface Vision, Basler AG, Keyence Corporation, Teledyne Technologies, Vitronic GmbH, Omron Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surface Inspection Market Strategic Shifts
Inspection architectures are bifurcating between edge-computing stations for latency-sensitive defect rejection and cloud-connected systems for pattern learning across distributed production networks.
Hyperspectral imaging is fragmenting the visible-spectrum camera monopoly in food-grade packaging and pharmaceutical blister inspection. Meat processors in Denmark and chocolate manufacturers in Switzerland are adopting 400-1000nm line-scan configurations to detect contamination beneath transparent films. The technology is compressing hardware differentiation toward sensor-agnostic software pipelines that swap spectral bands without mechanical retooling.
REACH substance restrictions on sensor housing polymers are forcing housing redesigns across European installations. ECHA candidate list updates targeting phthalates and brominated flame retardants are accelerating aluminum enclosure adoption at 15-20% cost premiums. Battery electrode manufacturers in Germany and medical device molders in Ireland are absorbing these premiums to maintain CE marking continuity.
After-sales service unbundling is displacing bundled maintenance contracts in high-volume electronics inspection. Taiwanese semiconductor fabs are negotiating per-inspection pricing for software updates and remote diagnostics, separating hardware warranty from algorithm retraining fees. This compression is most visible in Kaohsiung and Taichung corridors where contract manufacturers operate on thin capital deployment cycles.
Surface Inspection Market Segmentation
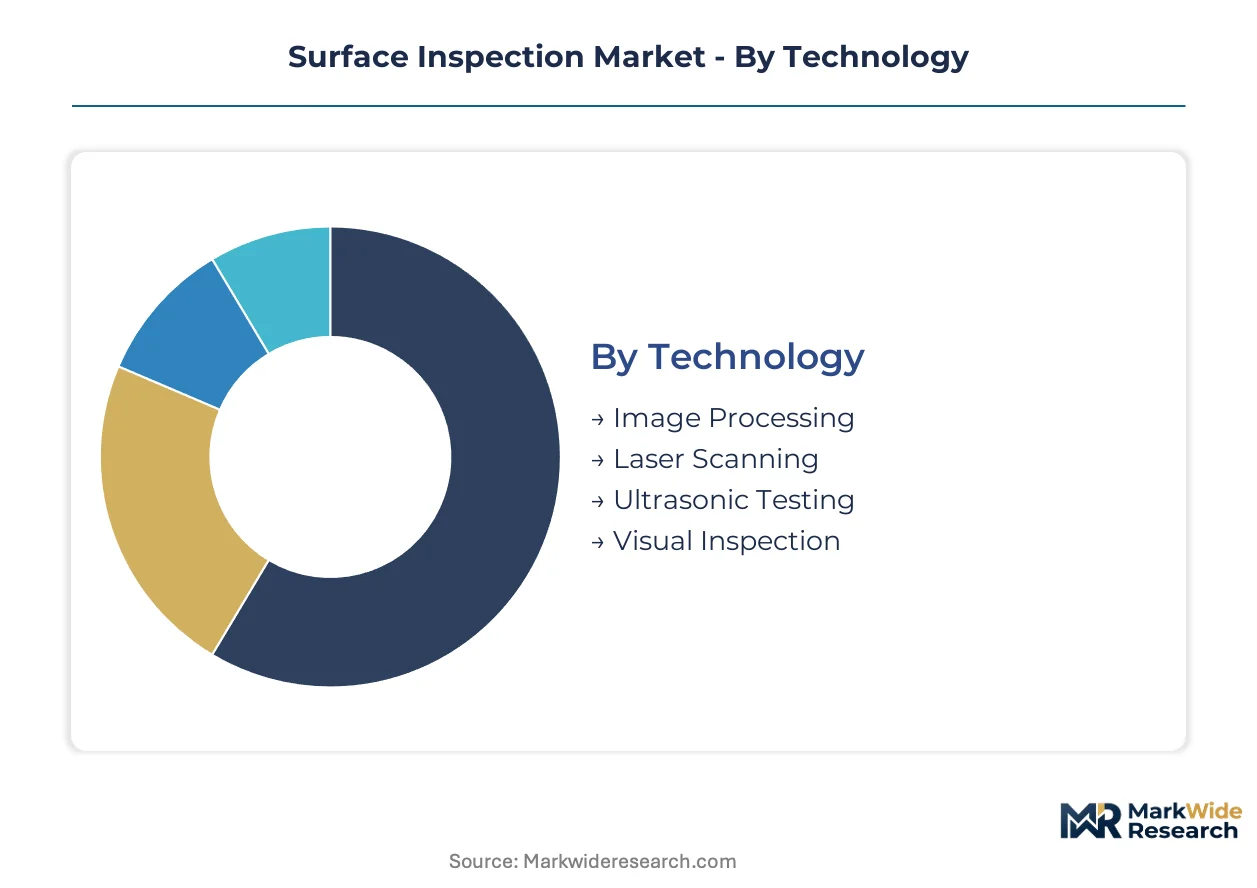
Surface inspection vendors configure product portfolios around sensing modality, manufacturing vertical, and operational architecture. Segment boundaries determine pricing power, with technology and deployment models commanding the steepest margin differentials.
Technology:
Margin pools concentrate in multi-sensor fusion platforms that combine optical and laser modalities for dimensional verification.
- Image Processing:CMOS line-scan cameras with sub-micron resolution dominate wafer-level defect detection in Taiwanese semiconductor fabs. Battery electrode manufacturers in South Korea are pulling 12-megapixel configurations into standard specifications as EV production scales.
- Laser Scanning:Triangulation and confocal systems capture turbine blade geometric conformity with sub-10-micron accuracy. German automotive stamping plants specify laser gauging for brake rotor surface flatness under EU Machinery Directive safety mandates.
- Ultrasonic Testing:Thickness gauging penetrates pipeline weld inspection where surface roughness tolerances permit acoustic substitution. This modality avoids optical occlusion in corroded carbon steel environments.
- Visual Inspection:Operator-guided magnified examination persists in medical device final verification where regulatory traceability requires human sign-off.
Image processing holds installed capacity. Laser scanning is rotating up the share rankings.
Application:
Application mix tracks capital deployment cycles across durable goods manufacturing, with electronics and automotive showing the shortest replacement intervals.
- Electronics Manufacturing:Automated optical inspection compresses cycle times to match wafer throughput scaling in Hsinchu and Pyeongtaek corridors. Contract manufacturers consolidate stations to reduce headcount in final assembly verification.
- Automotive Parts:Stamping plants across Stuttgart and Wolfsburg require validated surface protocols under EU Machinery Directive mandates. EV battery electrode inspection is pulling high-resolution camera configurations into tier-1 supplier specifications.
- Aerospace Components:Turbine blade dimensional gauging demands laser scanning for cooling hole geometry verification. FAA airworthiness directives mandate documented inspection traceability for flight-critical castings.
- Metal Fabrication:Sheet metal surface defect detection serves construction and appliance supply chains with lower resolution thresholds than precision manufacturing verticals.
Electronics manufacturing anchors volume demand. Automotive parts are climbing the fastest as EV production reshapes component specifications.
End User:
Customer type determines procurement authority, with OEMs capturing bundled system sales and quality departments driving software subscription attach rates.
- Quality Control Departments:Centralized defect pattern libraries across distributed plants are piloting cloud-based training data repositories. These units negotiate per-inspection pricing for algorithm retraining separate from hardware warranty.
- Manufacturers:In-house production lines absorb capital equipment for latency-sensitive defect rejection where cloud connectivity introduces unacceptable latency.
- OEMs:Original equipment manufacturers specify inspection protocols for supplier qualification, mandating metrology traceability documentation under ISO 9001 certification requirements.
- Research Institutions:Academic and government laboratories validate novel sensing modalities before production-scale deployment, with procurement cycles extending 18-24 months.
Quality control departments are gaining procurement influence. Manufacturers retain the largest installed base.
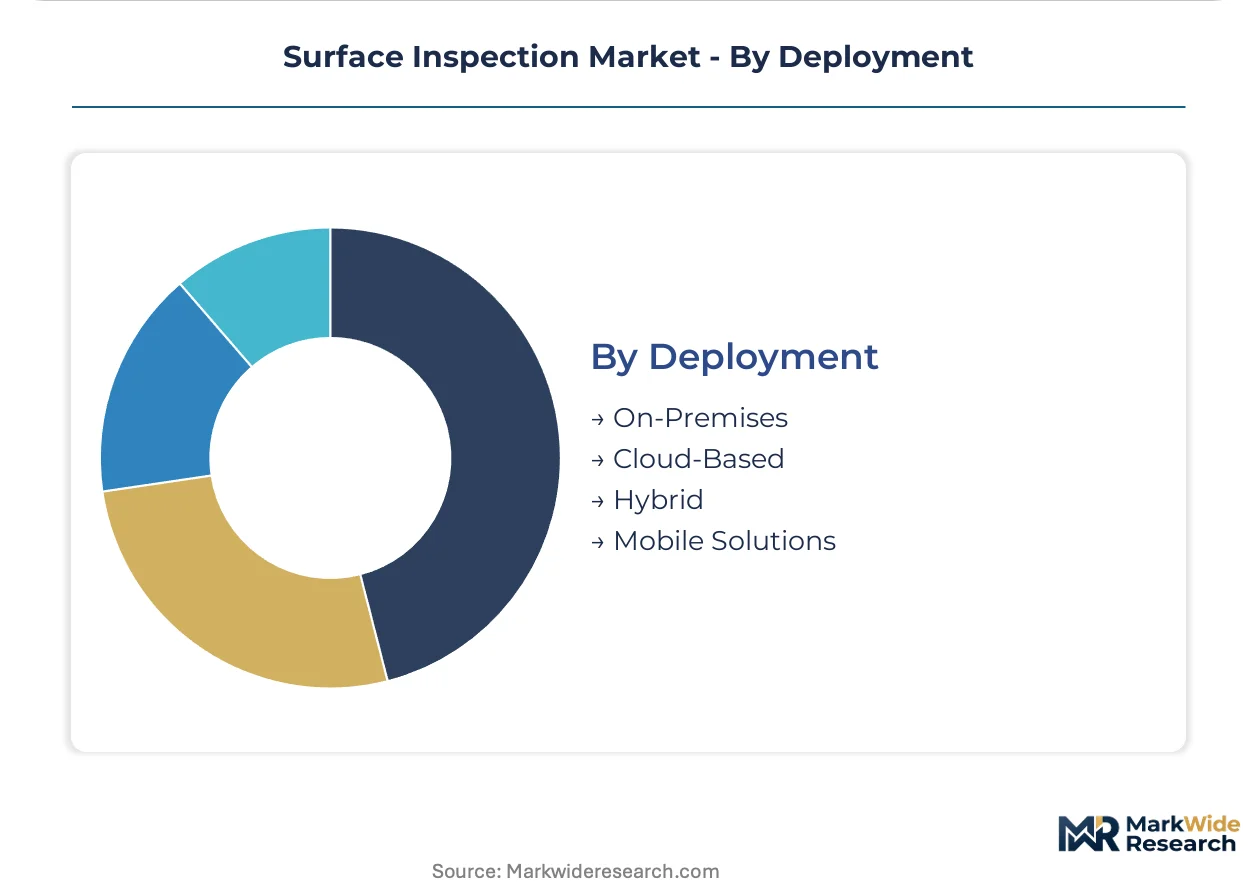
Deployment:
Deployment architecture splits between latency-sensitive edge systems and pattern-learning cloud configurations, with hybrid models capturing complex manufacturing environments.
- On-Premises:Edge-computing stations process defect rejection decisions within millisecond cycle times required by high-speed electronics assembly lines. Taiwanese semiconductor fabs prioritize local inference to avoid network dependency.
- Cloud-Based:Centralized training data repositories reduce per-site model development overhead for quality departments operating distributed plant networks. FDA 21 CFR Part 11 compliance remains a deployment constraint for pharmaceutical applications.
- Hybrid:Edge inference with cloud synchronization balances latency requirements against pattern learning across production networks. This architecture dominates brownfield semiconductor fab retrofits.
- Mobile Solutions:Portable inspection units serve field maintenance and construction site verification where fixed installations are impractical.
On-premises systems retain the largest installed footprint. Cloud-based deployment is expanding most quickly in distributed manufacturing networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for electronics manufacturing is attracting first-time inspection equipment deployments, while EU Machinery Directive mandates reshape European automotive stamping protocols. East Asian semiconductor corridors in Taiwan and South Korea continue compressing inspection cycle times to match wafer throughput scaling.
United States
FDA medical device quality system regulations mandate validated inspection protocols for implantable components, driving metrology traceability requirements. FAA airworthiness directives enforce documented inspection standards for flight-critical aerospace castings. The Pacific Northwest and Greater Boston clusters host precision manufacturing facilities deploying automated optical inspection for semiconductor and medical device production.
Germany
EU Machinery Directive safety standards require validated surface inspection protocols across automated automotive production lines. ECHA REACH substance restrictions on sensor housing polymers accelerate aluminum enclosure adoption despite cost premiums. Stuttgart and Wolfsburg stamping plants specify laser gauging systems for brake rotor surface flatness verification under regulatory mandates.
China
MIIT industrial upgrading policies promote smart manufacturing adoption including automated quality control systems. GB standards for electronics manufacturing tighten defect detection thresholds for export-oriented production. The Yangtze River Delta and Pearl River Delta clusters concentrate contract manufacturers consolidating inspection stations to reduce final assembly headcount.
South Korea
MFDS medical device regulations align with international quality management standards for component traceability. Government semiconductor industry support programs accelerate wafer-level defect detection equipment deployment. Pyeongtaek and Hsinchu corridor fabs compress inspection cycle times to match advanced process node throughput scaling.
India
PLI scheme incentives for smartphone and component manufacturing attract first-time inspection equipment deployments. BIS quality certification requirements shape vendor selection for electronics manufacturing clusters. Noida and Sriperumbudur corridors host expanding contract manufacturing facilities implementing automated optical inspection for export production.
Surface Inspection Market Competitive Environment
Listed leaders compete with private specialists across sensing modality and geographic coverage dimensions. The vendor base stratifies between integrated platform providers and component specialists, with tiered pricing separating premium multi-sensor fusion from standard camera configurations. Two dominant archetypes occupy distinct positions: machine vision software ecosystem builders and industrial camera hardware specialists. Competitive moves concentrate on strategic partnerships for AI model training data access and geographic expansion through localized service networks.
Within the integrated platform tier, Cognex Corporation and Keyence Corporation exemplify sensor-to-software bundling strategies that capture pricing power in high-throughput electronics corridors. Basler AG anchors European demand through specialized industrial camera portfolios. AMETEK Surface Vision and Teledyne Technologies occupy positions spanning multiple sensing modalities for industrial applications. Vitronic GmbH represents German precision engineering specialization in automated inspection systems.
| Leading Market Players |
|---|
| ISRA Vision |
| Panasonic Corporation |
| Cognex Corporation |
| AMETEK Surface Vision |
| Basler AG |
| Keyence Corporation |
| Teledyne Technologies |
| Vitronic GmbH |
| Omron Corporation |
| Others |
Value Chain & Pricing Dynamics
Per-inspection software licensing contracts lock in multi-year supply access for Taiwanese semiconductor fabs while exposing equipment vendors to price compression from unbundled after-sales service demands. This contract structure concentrates procurement leverage among contract manufacturers operating on thin capital deployment cycles in Kaohsiung and Taichung corridors.
Pricing Analysis
Certification level creates the primary spread between ISO 9001-traceable metrology systems and standard camera configurations lacking documented quality management infrastructure. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated medical device inspection stations from automotive-tier equipment and basic electronics verification units. Cost compression in standard camera tiers is intensifying because South Korean battery electrode manufacturers are pulling 12-megapixel configurations into baseline specifications. Contract manufacturers in Shenzhen and Ho Chi Minh City exhibit the highest price sensitivity, while FDA-regulated medical device molders in Ireland absorb premiums for CE marking continuity.
Supply Chain Analysis
Extended lead times for German and Japanese precision lens coatings are forcing equipment builders to carry buffer inventory of critical optical subassemblies. Supply concentrates in Taiwan and South Korea for CMOS sensors, Germany for precision optics, and Japan for laser scanning components. Equipment builders draw from aluminum enclosure suppliers facing ECHA REACH substance restrictions on phthalates and brominated flame retardants. Single-source vulnerability in specialized optical coating technologies exposes vendors to pricing volatility from precision lens suppliers. Distribution runs through direct sales channels anchored by Keyence Corporation across Asian manufacturing clusters and specialized industrial distributors serving European automotive stamping plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Algorithm retraining fees and remote diagnostics subscriptions are expanding faster than hardware warranty revenue, converting capital equipment vendors into recurring-revenue service platforms. This service-attach opportunity reshapes competitive positioning around software ecosystem depth rather than sensor specification alone.
For Market Incumbents: Secure ISO 9001 certification timelines for metrology traceability documentation to defend against emerging sensor-to-software platform competitors. Lock in backward integration into precision lens coating capabilities to reduce single-source dependency on German and Japanese suppliers. Channel control through localized service networks in Noida and Sriperumbudur clusters protects against PLI scheme entrants.
For New Entrants and Emerging Players: ISO 9001 fast-track certification programs open white-space penetration in Indian electronics manufacturing corridors where BIS quality requirements shape vendor selection. Target cloud-based defect pattern library deployments for quality control departments across distributed plant networks seeking centralized training data repositories. Go-to-market leverage rests on per-inspection pricing models that separate hardware warranty from algorithm retraining fees.
For Investors and Strategic Acquirers: Multi-sensor fusion platform specialists with documented AI-cybersecurity framework convergence represent the most defensible acquisition archetype for long-term viability across the 5-10 year connected factory architecture transition. Watch for IEC 62443-compliant network segmentation bundling with anomaly detection as the inflection signal indicating vendor differentiation beyond commodity camera configurations.
| Strategic Initiative | Industry Significance |
|---|---|
| Software Ecosystem Expansion | Machine vision software pipelines capture pricing power in high-throughput electronics corridors. |
| Multi-Sensor Fusion Development | Combined optical-laser platforms command margin premiums in dimensional gauging applications. |
| Cloud-Based Defect Library Deployment | Centralized training data repositories reduce per-site model development overhead for quality departments. |
| Regulatory Certification Investment | ISO 9001 and EU Machinery Directive compliance opens automotive and medical device procurement channels. |
| Geographic Service Network Expansion | Localized support infrastructure in Indian PLI corridors captures first-time equipment deployment demand. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with quality control directors, semiconductor fab engineers, automotive stamping plant managers, and industrial camera procurement leads; and secondary validation through SEC 10-K filings of listed inspection equipment vendors, EU Machinery Directive implementation guidance, ECHA REACH substance restriction updates, and MIIT smart manufacturing policy documents. Bottom-up triangulation across sensing modality deployment counts and top-down cross-check against capital equipment spending patterns anchored volume and value estimates.
Across the analysis window, the forecasting framework modeled technology segmentation by sensing modality, application vertical across electronics manufacturing and automotive parts, deployment architecture across edge and cloud configurations, and geographic production cluster concentration. CAGRs were derived from equipment replacement cycle compression rates and wafer throughput scaling trajectories in Taiwanese and South Korean semiconductor fabs. Industry-specific inputs included CMOS sensor resolution migration curves and EU regulatory mandate implementation timelines.
The analysis sits within stated boundaries; outcomes outside sustained East Asian electronics manufacturing corridor expansion or accelerated EU Machinery Directive enforcement would require recalibration. Forecasts reflect documented assumptions about inspection cycle time compression rates and cloud adoption thresholds in distributed manufacturing networks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
VXI Testing Equipment Market
Test and Measurement
Ohm Meter Market
Test and Measurement
Radiation Effects Testing Market
Test and Measurement
E-Axle and Inverter Efficiency and Reliability Test Platforms Market
Test and Measurement
5G Testing Devices Market
Test and Measurement
Battery Testing Equipment Market
Test and Measurement
Electrical Conductivity Meters Market
Test and Measurement
Electrical and Electronic Test Equipment Market
Test and Measurement
Pressure Calibration Equipment Market
Test and Measurement
LAMEA Semiconductor Metrology and Inspection Market
Test and Measurement
Electrolyzer Test System Market
Test and Measurement
NIR Moisture Analyzers Sales Market
Test and Measurement
EMC Electromagnetic Compatibility Test Laboratory Market
Test and Measurement
In-Circuit Test Market
Test and Measurement
Gauss Meter Market
Test and Measurement
Color Meter Market