
 MEMS Energy Harvesting Devices Market | 2026-2036
MEMS Energy Harvesting Devices Market Size, Share, and Industry Trends Forecast 2026-2036
MEMS Energy Harvesting Devices Market Foresight
Software-defined power management is broadening what suppliers deliver beyond hardware alone. STMicroelectronics International NV leverages its foundry scale to anchor European supply of integrated harvester-plus-storage modules. Texas Instruments Inc competes through precision analog front-ends that optimize power extraction across variable vibration inputs. EnOcean GmbH specializes in complete wireless sensor kits where energy harvesting eliminates battery maintenance entirely.
MEMS energy harvesting devices convert ambient mechanical, thermal, or electromagnetic energy into usable electrical power through microscale transducers fabricated on silicon or thin-film substrates, typically generating microwatts to milliwatts at output voltages under five volts for autonomous sensor networks. Piezoelectric device types currently lead in vibration-dense industrial settings due to superior power density and mature thin-film PZT deposition processes, while thermoelectric variants are gaining fastest in wearable technology applications where body-heat differentials sustain continuous operation. Remote sensors and IoT devices represent the deepest margin pools because end-users prioritize total cost of ownership reduction over unit hardware cost.
The EPA and FCC in the United States shape demand through emissions standards and unlicensed spectrum rules that favor low-power wireless nodes, while REACH and the EU Green Deal in Europe restrict hazardous substances and mandate lifecycle energy accounting for deployed electronics. Stakeholders must monitor how evolving Ecodesign requirements and emerging carbon-border adjustments alter component qualification timelines and sourcing geography.
Market Dynamics
The EU F-Gas Regulation and REACH compliance deadlines are compressing qualification timelines for wireless sensor suppliers, forcing faster integration of energy-autonomous architectures into industrial IoT deployments across European manufacturing clusters.
Growth Catalysts
- EU Green Deal lifecycle mandates:Brussels now requires embodied carbon accounting for deployed electronics, pushing automotive OEMs toward vibration-harvesting sensor nodes that eliminate battery replacement logistics.
- Thin-film PZT deposition:Mature piezoelectric manufacturing processes at 200mm wafer scale have collapsed unit costs for industrial vibration harvesters, accelerating adoption in German predictive maintenance networks.
- Industrial automation clusters:Stuttgart and Munich manufacturing hubs are standardizing self-powered condition-monitoring systems, creating concentrated demand pull for integrated harvester-plus-storage modules.
Market Restraints
- Substrate material concentration:High-purity PZT ceramic suppliers concentrate in East Asian specialty chemical producers, exposing European module assemblers to input volatility and extended lead times.
- Power output ceiling:Thermoelectric MEMS harvesters face fundamental Seebeck coefficient limitations in body-heat applications, capping continuous output below one milliwatt for wearable form factors.
- REACH substance restrictions:Candidate list updates targeting lead-containing piezoelectrics are forcing reformulation cycles that extend component qualification by eight to fourteen months.
Strategic Opportunities
- Smart building retrofits:France and Italy are mandating wireless environmental sensors in existing commercial stock, opening retrofit demand for thermal-gradient harvesters that exploit HVAC duct differentials.
- 5G small cell densification:Telecom infrastructure operators are piloting vibration-harvesting health monitors on tower-mounted equipment, converting wind-induced oscillation into maintenance-alert power.
- AI Act edge compliance:Brussels requirements for on-device inference are pushing sensor OEMs toward energy-autonomous designs that eliminate cloud-dependency risks for critical infrastructure monitoring.
Industry Challenges
- Multi-physics simulation talent:Coupled electromechanical-thermal modeling for harvester optimization requires rare expertise spanning COMSOL, MEMS process flows, and power electronics, constraining design velocity at mid-tier suppliers.
- CE-RED radio certification:Energy-autonomous wireless nodes must demonstrate sustained transmission under variable harvester output, extending test cycles and complicating module integration timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MEMS Energy Harvesting Devices Market |
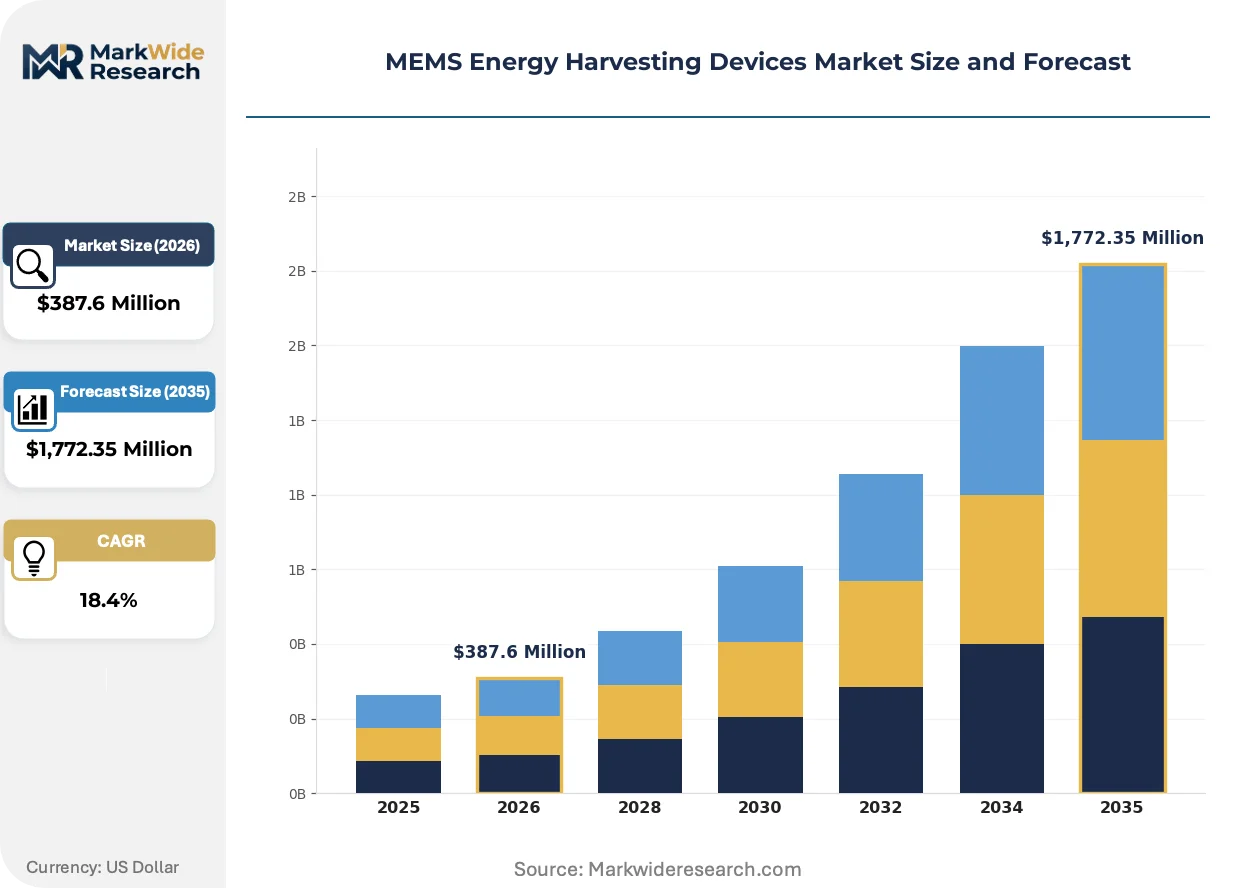
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,772.35 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Piezoresistive, Electromagnetic, Piezoelectric, Thermoelectric End User: Consumer Electronics, Industrial Automation, Healthcare Devices, Smart Grids Application: Wearable Technology, Remote Sensors, IoT Devices, Vibration Monitoring Technology: Microfabrication, Scalable Manufacturing, Low Power Electronics, Wireless Communication |
| Companies Covered | ABB Ltd, Lam Research Corp, Analog Devices Inc, Holst Centre, Texas Instruments Inc, STMicroelectronics International NV, Cymbet Corp, 8power Ltd, EnOcean GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MEMS Energy Harvesting Devices Market Shifts & Advancements
Silicon foundries are repositioning idle 200mm capacity toward MEMS sensor fabrication, while regulatory pressure on battery logistics is accelerating architectural shifts toward ambient-powered electronics in industrial and building automation segments.
Aluminum nitride (AlN) thin-film piezoelectrics are integrating into CMOS-compatible process flows at European foundries, enabling monolithic integration of harvester, rectifier, and storage on single dice. Automotive Tier-1s in Germany are qualifying these co-fabricated modules for tire-pressure and brake-wear sensors, collapsing bill-of-materials complexity while meeting ASIL reliability grades. The structural compression this is integrating eliminates wire-bond interconnects and their failure modes, reducing warranty exposure for safety-critical deployments.
REACH authorization procedures for lead zirconate titanate alternatives are tightening substance compliance windows, forcing harvester suppliers to accelerate lead-free piezoelectric qualification before 2026 sunset dates. The industrial consequence is a bifurcation between legacy PZT designs serving existing automotive contracts and aluminum nitride or potassium sodium niobate formulations targeting new European medical and building automation certifications. German industrial sensor OEMs are most affected, redirecting R&D toward potassium-based compositions that bypass candidate list restrictions.
Buyers are consolidating vendor relationships around suppliers offering integrated wireless sensor kits rather than discrete harvester components, compressing procurement cycles and shifting negotiation leverage toward complete-system qualification. Distributors in the DACH region are responding by building application engineering teams that configure harvester-antenna-storage combinations for specific vibration spectra. This consolidation is most visible in predictive maintenance contracts for Bavarian automotive stamping plants, where total-cost-of-ownership guarantees now dominate hardware unit pricing in supplier selection criteria.
MEMS Energy Harvesting Devices Market Segmentation
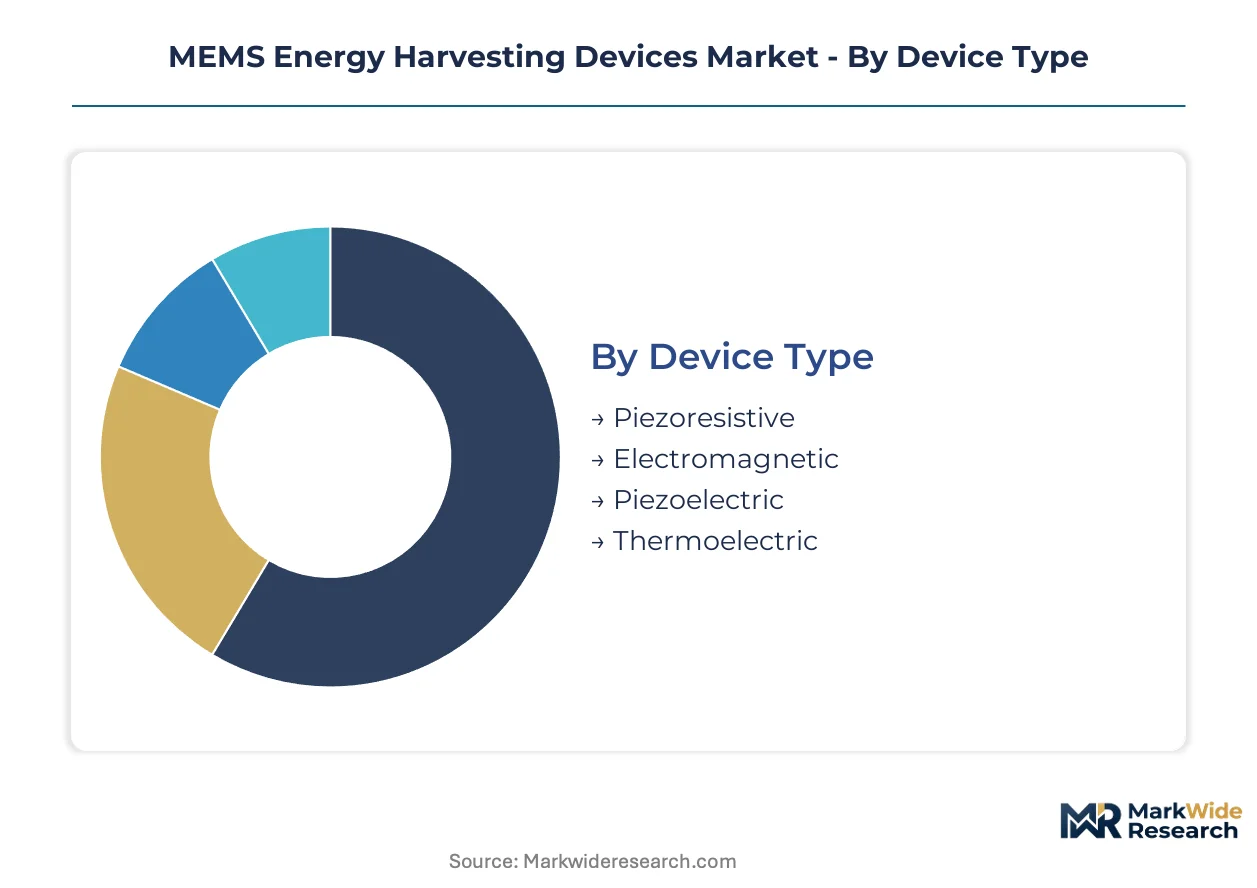
Segmentation in MEMS energy harvesting reveals how power density requirements and regulatory compliance windows fragment procurement strategies across end-use verticals. Buyers prioritize different harvester architectures based on whether their deployment favors vibration-rich industrial settings or thermal-gradient wearables.
Device Type:
Buyers select harvester transduction mechanisms based on ambient energy availability and power output density requirements for their specific deployment environment.
- Piezoelectric:Thin-film PZT or aluminum nitride layers convert mechanical strain into electrical charge through direct piezoelectric effect, achieving the highest power density among MEMS harvesters. German automotive stamping plants and Bavarian predictive maintenance networks concentrate procurement here, driven by REACH deadlines forcing lead-free reformulation toward potassium sodium niobate alternatives.
- Thermoelectric:Bismuth telluride or silicon-based Seebeck junctions exploit temperature differentials, fundamentally limited by material physics to sub-milliwatt outputs. Body-heat harvesting for French and Italian wearable medical monitors represents the steepest expansion trajectory, though output ceilings constrain continuous sensing applications.
- Electromagnetic:Coil-magnet assemblies on flexible substrates generate current through Faraday induction, favored in high-displacement low-frequency vibration environments. Industrial conveyor systems in Stuttgart manufacturing clusters specify these for reliability-critical condition monitoring.
- Piezoresistive:Strain-sensitive doped silicon elements modulate resistance under mechanical load, typically paired with active power management circuits. Bridge health monitoring in German civil infrastructure applications drives niche adoption where strain measurement precision outweighs absolute power generation.
Piezoelectric harvesters lead on scale; thermoelectric variants lead on momentum.
End User:
Total cost of ownership calculations vary sharply across end users, with battery replacement logistics driving divergent willingness-to-pay for energy-autonomous architectures.
- Industrial Automation:Self-powered condition monitoring in Stuttgart and Munich manufacturing hubs eliminates battery swap labor costs and unplanned downtime. EU Green Deal embodied carbon mandates accelerate vibration-harvesting sensor deployment across German automotive supply chains.
- Consumer Electronics:Premium wearable OEMs integrate thermal harvesters for always-on health tracking, though thermodynamic limits cap functionality extension. Italian and Spanish consumer electronics assemblers pilot these in smartwatch straps exploiting skin-to-ambient differentials.
- Healthcare Devices:Implantable and patch-based monitors demand biocompatible harvester materials with decade-long reliability. German medical device certification timelines under MDR extend qualification cycles for lead-free piezoelectric formulations.
- Smart Grids:Distribution transformer and substation monitoring favors electromagnetic harvesters extracting energy from 50Hz field coupling. French grid operators specify these for remote fault detection in rural network segments.
Industrial automation dominates procurement volume; healthcare devices command premium pricing tiers.
Application:
Application-specific power budgets and duty cycle requirements dictate whether harvester-plus-storage integration or discrete component sourcing proves economically optimal.
- Remote Sensors:Asset monitoring nodes in inaccessible locations prioritize elimination of maintenance visits entirely. German chemical plants along the Rhine corridor deploy vibration-harvesting pressure and temperature transmitters, with F-Gas Regulation compliance accelerating wireless retrofit timelines.
- IoT Devices:Dense sensor networks in smart buildings require sustained transmission under variable harvester output. French commercial retrofit mandates for HVAC-integrated environmental sensing create concentrated demand for thermal-gradient harvesters exploiting duct differentials.
- Wearable Technology:Form factor constraints and skin-contact requirements favor flexible thermoelectric or piezoelectric films. Italian fashion-technology collaborations prototype energy-autonomous garments for occupational health monitoring.
- Vibration Monitoring:Rotating machinery diagnostics demand wideband harvester response across machine-specific frequency spectra. Munich-area automotive powertrain test beds standardize piezoelectric harvesters for real-time bearing degradation detection.
Remote sensors anchor revenue concentration; IoT device deployments expand most quickly.
Technology:
Process maturity and CMOS compatibility determine whether European foundries can capture value from harvester fabrication or cede volume to East Asian specialty producers.
- Microfabrication:Deep reactive ion etching and thin-film deposition define resonant structures and piezoelectric stacks at wafer scale. German Fraunhofer Institute pilot lines demonstrate 200mm aluminum nitride integration compatible with automotive ASIL grades.
- Scalable Manufacturing:Transition from research-scale to high-volume production requires process control over piezoelectric domain orientation and residual stress. East Asian PZT ceramic suppliers currently dominate substrate supply, exposing European module assemblers to lead time volatility.
- Low Power Electronics:Sub-threshold CMOS design and impedance matching circuits maximize energy extraction efficiency. Texas Instruments and STMicroelectronics compete through precision analog front-ends optimized for variable harvester output.
- Wireless Communication:Energy-autonomous transmission protocols must demonstrate sustained operation under intermittent power availability. CE-RED certification complexity extends test cycles for integrated harvester-radio-storage modules.
Microfabrication commands R&D investment intensity; scalable manufacturing determines commercial viability at volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting MEMS energy harvesting module assembly toward jurisdictions with streamlined chemical substance compliance, while demand concentrates in manufacturing clusters facing strict battery-replacement cost pressures.
Germany
Automotive OEMs in Stuttgart and Munich are eliminating battery logistics from tire-pressure and brake-wear sensor networks. EU Green Deal embodied carbon mandates under REACH accelerate vibration-harvesting adoption across Bavarian predictive maintenance contracts. Fraunhofer Institute pilot lines in Dresden demonstrate 200mm aluminum nitride integration for ASIL-qualified automotive modules.
United States
EPA emissions standards and FCC unlicensed spectrum rules favor low-power wireless nodes in industrial IoT deployments. California's building decarbonization codes are mandating wireless environmental sensors in commercial retrofits, creating demand for thermal-gradient harvesters. Silicon Valley foundries are repositioning idle 200mm capacity toward MEMS sensor fabrication.
France
Smart building retrofit mandates require wireless HVAC-integrated environmental sensing in existing commercial stock. ANSM medical device timelines extend qualification cycles for biocompatible harvester materials in implantable monitors. Paris-region telecom infrastructure operators pilot vibration-harvesting health monitors on tower-mounted 5G equipment.
Japan
METI industrial efficiency programs subsidize self-powered condition monitoring in precision manufacturing. JIS standards for wireless sensor reliability compress CE-RED certification timelines for Japanese OEMs exporting to Europe. Nagoya automotive clusters specify piezoelectric harvesters for real-time bearing degradation detection in powertrain test beds.
China
MIIT dual carbon goals mandate energy-autonomous architectures in state-owned industrial IoT deployments. GB standards for hazardous substance restriction align with REACH substance lists, reducing qualification friction for export-bound modules. Yangtze River Delta foundries dominate high-purity PZT ceramic substrate supply for global module assemblers.
MEMS Energy Harvesting Devices Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated wireless sensor kit suppliers capturing procurement consolidation in German industrial automation while discrete harvester component vendors serve Asian electronics assemblers. The vendor base organizes around three strategic archetypes: foundry-scale semiconductor houses with MEMS fabrication capabilities, precision analog specialists optimizing power extraction circuits, and complete-system integrators eliminating battery maintenance entirely. Dominant competitive moves include backward integration into piezoelectric material supply and application engineering team expansion to configure harvester-antenna-storage combinations for specific vibration spectra.
Among European-based fabricators, STMicroelectronics International NV occupies a position exemplifying foundry-scale integration of harvester-plus-storage modules, while EnOcean GmbH represents the complete-system archetype through wireless sensor kits where energy harvesting eliminates battery logistics entirely. Texas Instruments Inc anchors the precision analog tier, with analog front-end optimization for variable vibration inputs distinguishing its competitive posture. These three patterns—monolithic integration, system-level elimination of maintenance, and circuit-level extraction efficiency—define the competitive vectors shaping procurement consolidation in DACH-region industrial sensor contracts.
| Leading Market Players |
|---|
| ABB Ltd |
| Lam Research Corp |
| Analog Devices Inc |
| Holst Centre |
| Texas Instruments Inc |
| STMicroelectronics International NV |
| Cymbet Corp |
| 8power Ltd |
| EnOcean GmbH |
| Others |
Supply & Pricing Matrix
PZT ceramic substrate costs cascade through three downstream pricing tiers before reaching German automotive OEMs, with East Asian specialty chemical producers capturing margin at the raw material layer while European module assemblers absorb volatility through contract structures.
Pricing Analysis
Distributor margins in the DACH region compress procurement cycles around integrated wireless sensor kits rather than discrete harvester components. Three-tier pricing structure across ASIL-qualified automotive, CE-marked industrial, and uncertified prototyping levels reflects certification investment recovery timelines. Cost compression in standard-grade industrial modules intensifies as Fraunhofer Institute pilot lines demonstrate 200mm aluminum nitride integration. Tier 1 automotive buyers exhibit lowest price sensitivity due to total-cost-of-ownership guarantees dominating supplier selection, while mid-tier building automation assemblers face acute pressure from retrofit mandate volume requirements.
Supply Chain Analysis
Returns and refurbishment flows remain nascent for energy-autonomous sensor nodes, though REACH substance restrictions are forcing reformulation cycles that extend component qualification timelines. High-purity PZT ceramic supply concentrates in China, Japan, and South Korea, exposing European module assemblers to input volatility. Bismuth telluride for thermoelectric junctions and aluminum nitride thin-film substrates feed from specialty chemical producers with limited alternative sourcing. Single-source vulnerability in lead-free piezoelectric formulations intensifies as potassium sodium niobate qualification timelines stretch. Distribution runs through DACH-region distributors building application engineering teams for harvester-antenna-storage configuration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MEMS energy harvesting has entered a late-cycle quality phase where automotive OEMs now specify ASIL-qualified modules over cost-optimized alternatives, rewarding suppliers with captive foundry capacity and certified material supply.
For Market Incumbents: Deepen backward integration into aluminum nitride thin-film deposition to secure supply continuity ahead of REACH lead-free sunset deadlines. Expand Dresden pilot line capacity to capture Bavarian predictive maintenance contract renewals. Defensive consolidation around complete wireless sensor kits protects against discrete component commoditization. For New Entrants and Emerging Players: CMOS-compatible piezoelectric process expertise offers entry into French smart building retrofit mandates where thermal-gradient harvesters exploit HVAC duct differentials. White-space concentrates in biocompatible potassium sodium niobate formulations for German medical device certifications under MDR timelines. Go-to-market through DACH-region distributors with application engineering capabilities accelerates qualification. For Investors and Strategic Acquirers: Consolidation pressure builds where foundry-scale MEMS fabrication capability intersects with REACH-compliant material supply. Long-term viability favors integrated harvester-plus-storage module suppliers over discrete component vendors. Acquisition targets center on European foundries with 200mm aluminum nitride process maturity. Monitor CE-RED certification completion rates for integrated harvester-radio modules as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Piezoelectric Material Supply | Captive aluminum nitride deposition secures REACH compliance ahead of PZT reformulation deadlines. |
| ASIL Qualification Investment | Automotive safety-grade certification opens Stuttgart and Munich OEM direct procurement channels. |
| Application Engineering Team Expansion | DACH-region distributor technical support configures harvester-antenna-storage combinations for specific vibration spectra. |
| CE-RED Pre-Certification Program | Streamlined radio compliance accelerates integrated module deployment for industrial IoT retrofits. |
| Potassium Sodium Niobate Process Development | Lead-free piezoelectric formulation bypasses REACH candidate list restrictions for medical and building automation. |
Research Methodology
Coverage spans Germany, France, Italy, the United States, and Japan, with primary inputs from each market cluster combined with secondary validation. MEMS fabrication engineers, automotive Tier 1 procurement leads, industrial IoT platform architects, and DACH-region distribution channel managers contributed structured interviews. Secondary sources include ECHA REACH substance databases, CE-RED certification filings, Fraunhofer Institute technical publications, and SEC filings from analog semiconductor suppliers. Bottom-up unit economics for harvester-plus-storage modules triangulate against top-down industrial automation capex forecasts.
Rate-of-change decomposition separates volume expansion from price-mix effects across the analysis window. Segmentation dimensions modeled include device type, end-user vertical, application power budget, and CMOS process compatibility tier. CAGRs derive from fitted growth curves applied to wafer-scale production capacity announcements and regulatory mandate implementation schedules. Forecast inputs incorporate EU Green Deal embodied carbon accounting timelines and F-Gas Regulation wireless retrofit compliance windows.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH substance list updates and East Asian PZT ceramic supply disruptions. Forecasts reflect documented assumptions regarding aluminum nitride process yield maturation and CE-RED certification cycle durations. Practitioners should monitor lead-free piezoelectric qualification completion rates and 200mm foundry capacity reallocation announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Nano Radiation Sensors Market
Sensors and Controls
Sensor Screwdrivers Market
Sensors and Controls
Volatile Organic Compound Gas Sensor Market
Sensors and Controls
North America Sensor Market
Sensors and Controls
Battery Monitor Market
Sensors and Controls
Timing Device Market
Sensors and Controls
Piezoelectric Accelerometer Market
Sensors and Controls
Current Calibrator Market
Sensors and Controls
Atomic Clock Market
Sensors and Controls
IR Emitter and Receiver Market
Sensors and Controls
Japan Sensor Market
Sensors and Controls
Radar Level Transmitter Market
Sensors and Controls
Middle East and Africa Temperature Sensors Market
Sensors and Controls
Quantum Dot Sensor Market
Sensors and Controls
China PV Monitoring Systems Market
Sensors and Controls
Global Radar Sensor Market