
 US Pressure Sensors Market | 2026-2036
US Pressure Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
US Pressure Sensors Market Analytics
Sensor-as-a-service subscription models for calibration and predictive maintenance is hardening into a standard revenue layer alongside hardware sales. Honeywell International Inc. leverages its aerospace pedigree to dominate high-reliability segments with multi-year service contracts. Sensata Technologies Inc. sustains automotive OEM relationships through captive supply of piezoresistive modules for electric powertrain thermal management. Emerson Electric Co. anchors industrial process automation with integrated pressure-temperature diagnostics and remote monitoring software.
Pressure sensors transduce fluid or gas pressure into electrical signals through piezoresistive, capacitive, optical, or ultrasonic mechanisms, typically operating across ranges from fractions of a psi to thousands of psi with accuracy thresholds of 0.1% full scale or tighter. These devices serve critical safety and process control functions in automotive braking systems, aircraft hydraulic circuits, medical ventilators, and chemical plant pipelines. Differential pressure sensors command premium margins in HVAC and cleanroom applications where precise airflow measurement prevents contamination. Piezoresistive silicon technology leads unit volume due to semiconductor batch fabrication economics, while optical pressure sensing gains traction in electromagnetic interference environments such as MRI suites and high-voltage switchgear.
FDA medical device cybersecurity mandates and NHTSA automated vehicle safety standards are tightening certification requirements for pressure sensor accuracy, traceability, and fail-safe behavior. EPA emissions monitoring rules in stationary sources and OSHA process safety management directives further shape product specifications for industrial installations. Stakeholders must monitor evolving interoperability standards between wireless pressure transmitters and cloud-based asset management platforms to preserve competitive position.
Market Dynamics
Automotive electrification is compressing sensor deployment timelines across battery thermal management and electric brake systems, while FDA cybersecurity mandates and NHTSA automated vehicle guidance force recertification of legacy pressure monitoring architectures.
Growth Catalysts
- NHTSA Automated Vehicle Safety Standards:Mandates for redundant pressure monitoring in electric brake-by-wire systems are accelerating OEM procurement cycles for ASIL-D certified components.
- Battery thermal management:Electric vehicle powertrains require distributed pressure sensing across coolant loops and refrigerant circuits, expanding unit volumes per vehicle platform.
- California industrial corridor concentration:Semiconductor fabrication and hydrogen infrastructure buildout in the San Francisco Bay Area and Los Angeles basin are pulling high-purity pressure transmitters.
Market Restraints
- Silicon wafer supply concentration:Piezoresistive MEMS fabrication depends on 300mm silicon substrates sourced from a concentrated East Asian supplier base, exposing cost volatility.
- EPA emissions monitoring compliance costs:Continuous pressure monitoring mandates in stationary source permits impose recurring calibration and data logging burdens on industrial operators.
- Optical sensing substitution:Fiber-optic pressure transducers are displacing electrical sensors in MRI suites and high-voltage switchgear where electromagnetic interference immunity is mandatory.
Strategic Opportunities
- Texas hydrogen hub deployment:Department of Energy-funded regional clean hydrogen centers are creating demand for high-pressure hydrogen-compatible sensors in compression and dispensing infrastructure.
- Sensor-as-a-service calibration subscriptions:Predictive maintenance contracts bundling hardware, cloud diagnostics, and field recertification are opening recurring revenue streams alongside unit sales.
- OSHA process safety management integration:Industrial facilities are consolidating pressure, temperature, and vibration monitoring under unified asset management platforms to satisfy safety audit requirements.
Industry Challenges
- ASIL-D functional safety certification timelines:Automotive pressure sensors for brake and thermal systems require 18-24 month validation cycles that compress product refresh windows.
- Legacy 4-20mA integration friction:Industrial operators face stranded asset risks when migrating analog pressure transmitters to wireless ISA100 or HART-IP architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Pressure Sensors Market |
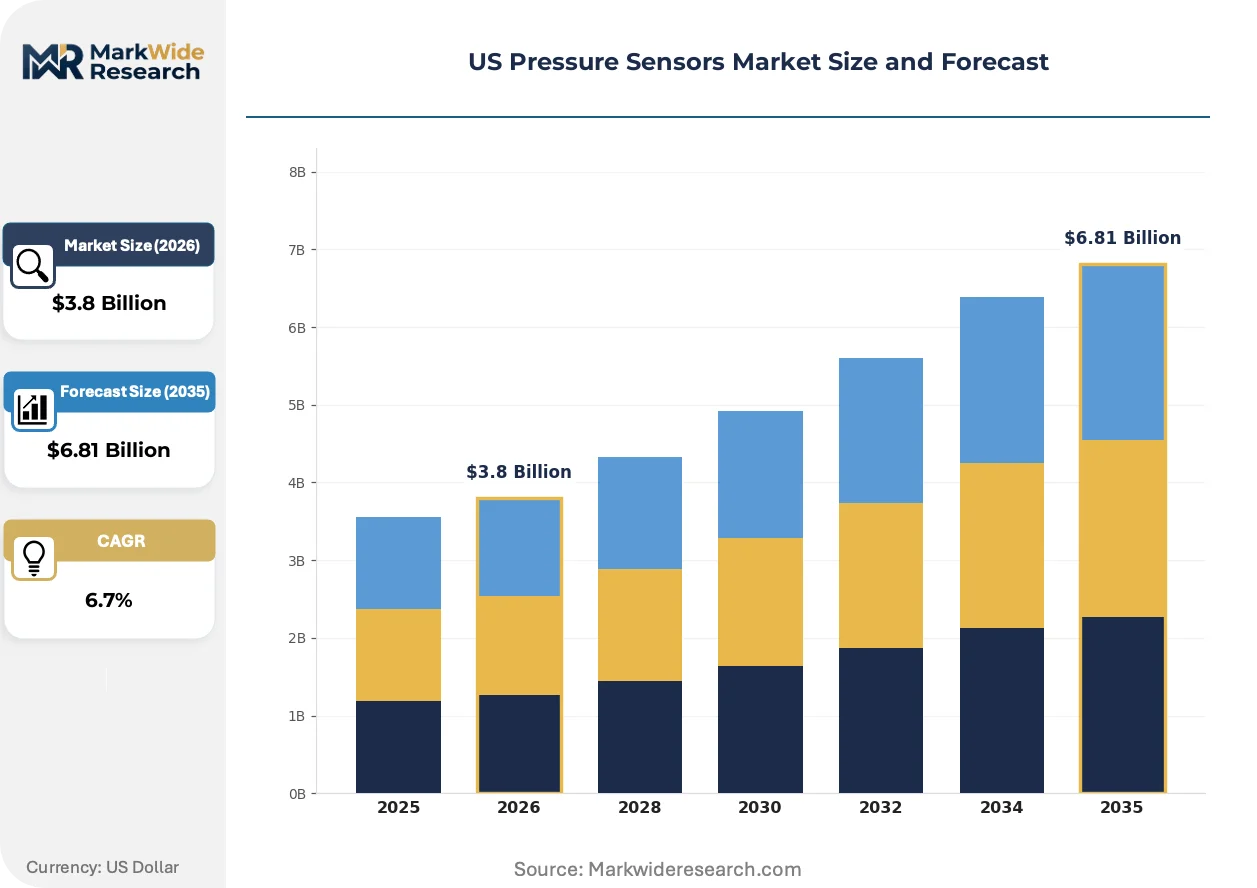
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Absolute, Differential, Gauge, Sealed Technology: Piezoresistive, Capacitive, Optical, Ultrasonic End User: Automotive, Aerospace, Healthcare, Industrial Installation: Panel Mount, Inline, Wireless, Portable |
| Companies Covered | Honeywell International Inc., Sensata Technologies Inc., Emerson Electric Co., TE Connectivity Ltd., ABB Ltd., Bosch Sensortec GmbH, All Sensors Corp., Rockwell Automation Inc., Endress+Hauser AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Pressure Sensors Market Evolving Landscape
Silicon carbide MEMS processing and optical interferometric sensing are unifying pressure-temperature measurement in a single transducer package, compressing sensor count and wiring complexity across electric vehicle platforms and industrial automation.
Multi-physics sensing is unifying piezoresistive pressure measurement with integrated temperature compensation and vibration diagnostics in a single die. Tier 1 automotive suppliers are adopting these fused sensors for electric powertrain thermal management. The convergence is unifying what were three discrete components into one sealed module, reducing wiring harness mass and assembly labor.
FDA medical device cybersecurity requirements are mandating encrypted data transmission and secure boot capabilities for pressure sensors used in infusion pumps and ventilators. Manufacturers must implement hardware security modules and software bill of materials documentation. Hospital procurement committees are prioritizing FDA 510(k) submissions with explicit cybersecurity attestations over legacy cleared devices.
California's industrial operators are compressing procurement cycles for pressure instrumentation to satisfy South Coast Air Quality Management District emissions monitoring deadlines. Distributors are responding with regional inventory pre-positioning and same-day calibration services. The behavioral shift is most visible in Los Angeles basin refineries and semiconductor fabs where permit compliance dates are non-negotiable.
US Pressure Sensors Market Segmentation
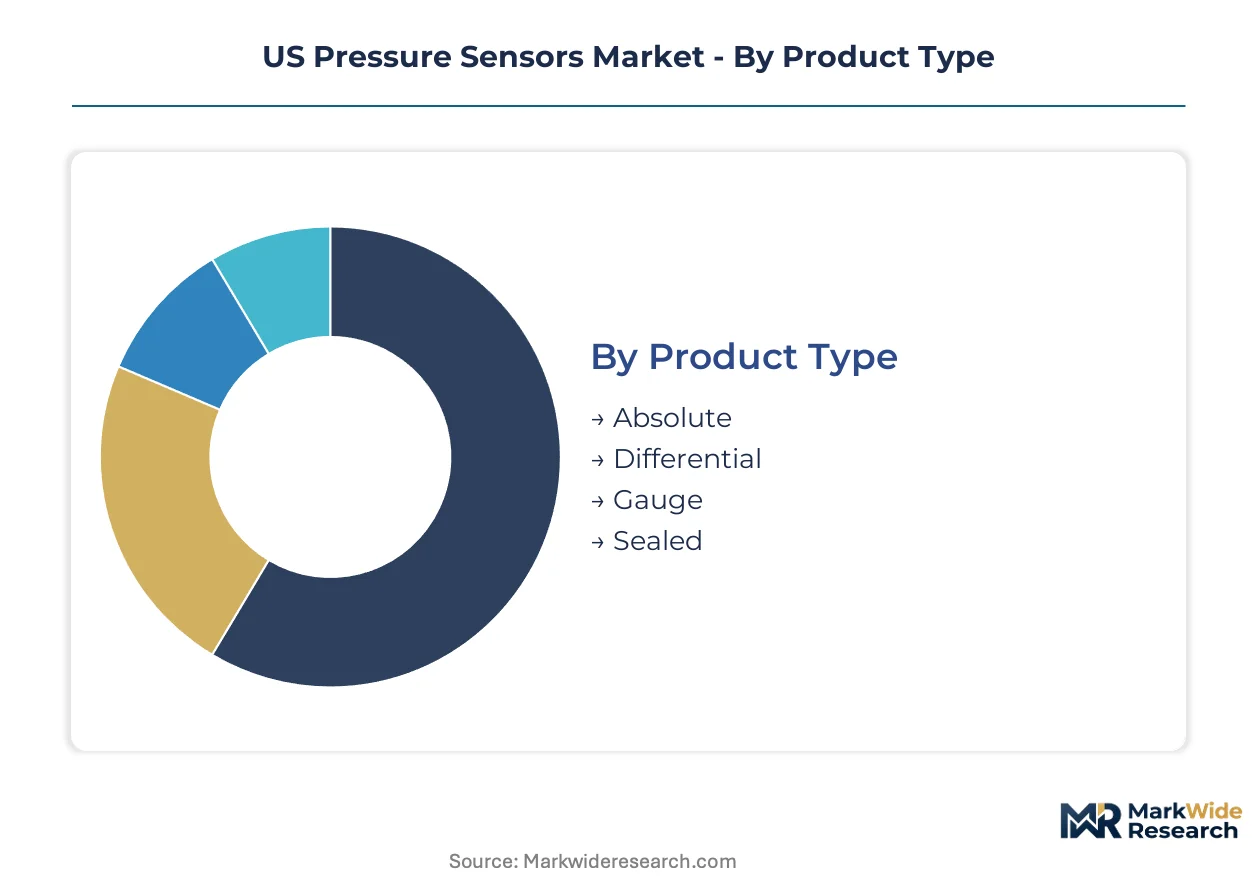
Pressure sensor procurement in the United States fragments across four structural dimensions that determine specification rigor, certification burden, and service attach rates. Product type and technology choices cascade through installation constraints and end-user compliance requirements, creating distinct margin architectures within each segment cluster.
Product Type:
Standardization versus customization tension runs deepest in product type selection, where off-the-shelf gauge sensors compete with application-engineered absolute and differential variants requiring sealed reference chambers.
- Absolute:Vacuum-referenced designs measure pressure against a sealed zero-pressure cavity, essential for altitude sensing in aircraft cabin management and barometric compensation in automotive engine control modules. Demand concentrates in Boeing's Washington state supply chain and Gulfstream's Georgia operations, where FAA certification timelines stretch procurement cycles. NHTSA emissions calibration mandates are accelerating absolute sensor deployment across powertrain management systems.
- Differential:Dual-port architectures capture pressure delta across filtration membranes, HVAC dampers, and medical ventilator flow circuits. California semiconductor fabs and Texas hydrogen compression stations are pulling premium units with 0.05% accuracy thresholds. EPA continuous emissions monitoring rules are tightening differential sensor calibration frequencies in refinery and chemical plant stacks.
- Gauge:Atmospheric-referenced units dominate unit volume through cost-optimized designs for industrial pneumatics and consumer appliance pressure switches.
- Sealed:Hermetically isolated references serve submersible and high-humidity environments in offshore oil platforms and wastewater treatment infrastructure.
Most installed capacity flows through gauge sensors in industrial maintenance applications. Expansion is steepest in differential configurations driven by cleanroom and hydrogen infrastructure buildout.
Technology:
Cost tier stratification separates mature silicon MEMS processes from emerging optical and ultrasonic platforms commanding 3-5x unit premiums.
- Piezoresistive:Silicon strain-gauge elements fabricated through semiconductor batch processes deliver the lowest cost per sensing point across automotive and industrial volume applications. Michigan's automotive belt and California's industrial corridor absorb the majority of domestic piezoresistive output. NHTSA brake-by-wire mandates are forcing ASIL-D certification upgrades that favor established piezoresistive suppliers with validation track records.
- Capacitive:Parallel-plate displacement sensing achieves superior stability in temperature-cycling environments, particularly aerospace fuel tank ullage measurement and satellite propulsion systems. NASA contractor facilities in Alabama and Colorado are specifying capacitive architectures for long-duration mission reliability. FAA DER-approved designs command extended lead times and premium pricing.
- Optical:Fiber-Bragg grating and interferometric methods eliminate electromagnetic interference vulnerability in MRI suites and high-voltage switchgear.
- Ultrasonic:Time-of-flight acoustic measurement penetrates corrosive and high-temperature media in chemical process and downhole drilling applications.
Volume concentrates in piezoresistive silicon given automotive scale economies. Optical platforms are climbing the fastest as FDA MRI safety standards and utility grid hardening drive substitution away from electrical sensing.
End User:
Customer type determines certification depth, with medical and aerospace buyers imposing the most exhaustive qualification protocols.
- Automotive:Electric powertrain thermal management and brake-by-wire redundancy are expanding sensor counts per vehicle platform. Michigan OEMs and Tesla's Nevada operations are consolidating supplier bases around ASIL-D capable Tier 1s. NHTSA automated vehicle guidance is mandating redundant pressure monitoring architectures with deterministic failure modes.
- Aerospace:Hydraulic system monitoring, fuel quantity gauging, and environmental control systems require DO-178C software and DO-254 hardware compliance. Boeing's Washington engineering centers and Lockheed Martin's Texas operations specify multi-source qualification for flight-critical sensors. FAA Part 25 certification cycles extend 24-36 months for new designs.
- Healthcare:Infusion pump, ventilator, and dialysis pressure monitoring face FDA cybersecurity mandates and 510(k) submission requirements.
- Industrial:Process automation, HVAC, and emissions monitoring absorb the broadest product mix with varying accuracy and environmental sealing specifications.
Revenue concentrates in automotive through platform standardization and volume scale. Healthcare applications are expanding most quickly as FDA cybersecurity rules force replacement of legacy cleared devices.
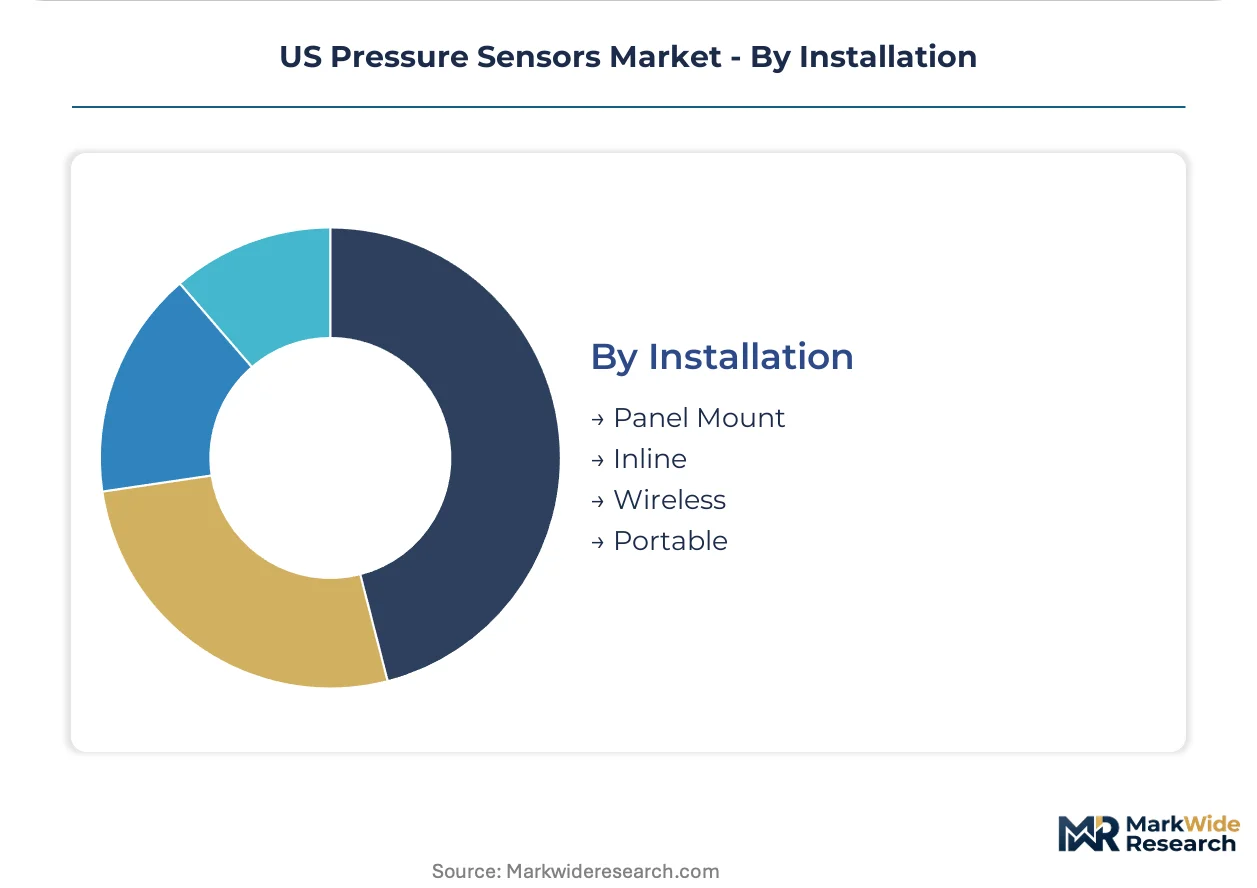
Installation:
Geography of deployment shapes connectivity architecture, with wireless adoption concentrated in brownfield retrofits and remote asset monitoring scenarios.
- Panel Mount:Enclosure-integrated designs with threaded process connections dominate control room and skid-mounted equipment applications. Texas petrochemical complexes and Louisiana refineries specify NEMA 4X housings for outdoor instrument shelters. OSHA process safety management audits are driving standardized panel configurations to simplify compliance documentation.
- Inline:Flow-through bodies with welded or flanged connections serve pipeline and vessel penetration points in oil & gas and chemical processing. Permian Basin operators and Gulf Coast LNG export terminals are specifying inline designs with remote seal diaphragms for sour service compatibility. EPA leak detection and repair programs are tightening inline sensor inspection intervals.
- Wireless:Battery-powered ISA100 and WirelessHART transmitters eliminate conduit runs in tank farm and distributed asset applications.
- Portable:Handheld calibrators and data loggers support field verification and temporary troubleshooting in maintenance operations.
Unit volume flows through panel mount configurations in greenfield construction. Wireless installations are gaining share fastest as industrial operators consolidate distributed assets under cloud-based management platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While Germany's automotive belt concentrates piezoresistive sensor fabrication for European OEMs, the United States dominates high-reliability aerospace and medical certification demand through its distinct regulatory architecture.
California
Semiconductor fabrication and hydrogen infrastructure buildout in the San Francisco Bay Area and Los Angeles basin are pulling high-purity pressure transmitters. South Coast Air Quality Management District emissions monitoring deadlines are compressing procurement cycles for industrial instrumentation. Los Angeles basin refineries and semiconductor fabs are driving same-day calibration service demand.
Michigan
Electric vehicle powertrain thermal management and brake-by-wire systems are expanding sensor counts per vehicle platform. NHTSA automated vehicle safety standards are mandating redundant pressure monitoring with ASIL-D certification. Detroit-area OEMs and Tier 1 suppliers are consolidating supplier bases around validated piezoresistive module sources.
Texas
Department of Energy-funded regional clean hydrogen centers are creating demand for high-pressure hydrogen-compatible sensors in compression infrastructure. EPA continuous emissions monitoring rules are tightening calibration frequencies in Permian Basin operations. Gulf Coast LNG export terminals are specifying inline designs with remote seal diaphragms.
Washington State
Boeing's engineering centers and satellite propulsion contractors are specifying capacitive pressure architectures for long-duration aerospace missions. FAA Part 25 certification cycles extend 24-36 months for new flight-critical sensor designs. Pacific Northwest aerospace clusters absorb premium units with DO-178C software compliance requirements.
US Pressure Sensors Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with tiered concentration emerging around certification depth rather than scale alone. The vendor base organizes into three functional layers: diversified industrial conglomerates with captive sensor divisions, pure-play transducer specialists with ASIL-D or FDA validation track records, and regional fabricators serving cost-optimized maintenance markets. Dominant competitive moves center on multi-year service contract bundling and backward integration into MEMS wafer processing.
Within the diversified industrial tier, Honeywell International Inc. and Emerson Electric Co. exemplify the aerospace-to-automation span that commands premium positioning through integrated hardware-software offerings. Sensata Technologies Inc. occupies a specialist position anchored in automotive OEM relationships. These three entities represent distinct archetypes: the conglomerate leveraging cross-sector certification credibility, the automation incumbent bundling remote diagnostics, and the automotive-native supplier capturing electric powertrain thermal management volumes.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Sensata Technologies Inc. |
| Emerson Electric Co. |
| TE Connectivity Ltd. |
| ABB Ltd. |
| Bosch Sensortec GmbH |
| All Sensors Corp. |
| Rockwell Automation Inc. |
| Endress+Hauser AG |
| Others |
Value Network & Pricing Analysis
300mm silicon wafer costs cascade through piezoresistive MEMS fabrication into three-tier pricing stratification across automotive, industrial, and medical certification grades. East Asian substrate concentration feeds cost volatility into ASIL-D automotive modules while FDA cybersecurity mandates sustain premium tiers for hospital-grade ventilator sensors.
Pricing Analysis
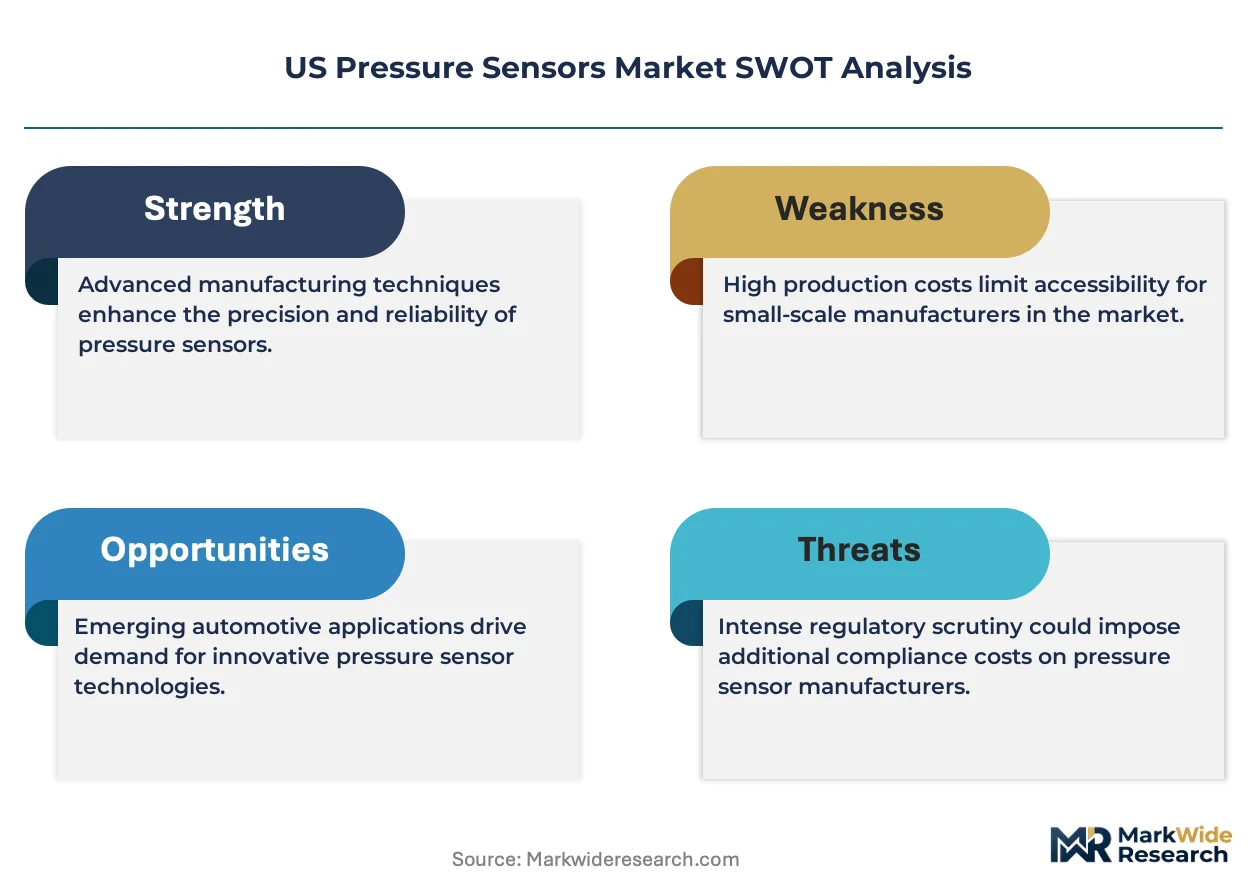
Capacity additions in South Korea and Taiwan are reshaping price floors for standard industrial gauge sensors, compressing margins on uncalibrated units while ASIL-D certified automotive modules and FDA 510(k) cleared medical devices maintain pricing power through validation track records. Price differentiation rests on certification burden and service attach rates, with automotive OEMs least sensitive due to platform lock-in and maintenance contractors most sensitive due to spot procurement patterns. Cost compression in commodity industrial tiers is intensifying because Chinese MEMS foundries are expanding 200mm equivalent capacity.
Supply Chain Analysis
Dual-sourcing requirements from Boeing and Detroit-area OEMs mandate multi-supplier qualification for flight-critical capacitive designs and brake-by-wire piezoresistive modules. Geographic supply concentration centers on Taiwan and South Korea for 300mm silicon substrates, Japan for ceramic packaging materials, and Germany for precision reference standards. Raw material dependencies include silicon wafers, borosilicate glass for anodic bonding, and specialty epoxies for harsh media isolation. Single-source vulnerability in advanced MEMS foundry capacity exposes automotive qualification timelines. Distribution runs through authorized distributors with calibration service capabilities for industrial accounts and direct OEM supply agreements for automotive and aerospace volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in US pressure sensors hinges on sensor-as-a-service recurring revenue attaching to hardware sales and silicon carbide MEMS processing cost-down curves. Premium-tier shift toward optical platforms in MRI and high-voltage switchgear applications sustains pricing power absent from commodity industrial gauge markets.
For Market Incumbents: To counter optical sensing substitution in electromagnetic interference environments, Honeywell and Sensata should deepen backward integration into silicon carbide wafer processing and secure captive supply of hydrogen-compatible metallization for Texas hub deployments. ASIL-D certification investment remains the priority defensive lever against emerging MEMS foundries in East Asia. For New Entrants and Emerging Players: Regional hydrogen compression operators in Texas and California semiconductor fabs with South Coast Air Quality Management District compliance deadlines represent underserved buyer archetypes with compressed procurement cycles and limited incumbent relationships. White-space concentration in high-purity differential transmitters for cleanroom applications and portable calibration services for same-day turnaround offers the most penetrable entry path. Go-to-market execution should anchor on distributor partnerships with pre-positioned regional inventory. For Investors and Strategic Acquirers: Consolidation pressure builds where FDA cybersecurity mandates force hospital procurement committees to replace legacy cleared devices, creating acquisition opportunities for 510(k) holders with hardware security module implementations. Long-term viability favors specialists with multi-year automotive service contracts and aerospace DER-approved designs over commodity industrial gauge fabricators. The signal to watch is NHTSA automated vehicle rulemaking pace, which would accelerate ASIL-D procurement cycles and validate premium-tier positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-as-a-Service Subscription Launch | Recurring revenue from predictive maintenance contracts attaches to Honeywell and Emerson hardware deployments. |
| Silicon Carbide MEMS Foundry Investment | In-house processing of pressure-temperature fused sensors reduces die count for Tesla and Detroit OEM thermal platforms. |
| FDA 510(k) Cybersecurity Pathway | Hardware security module documentation satisfies hospital procurement committee requirements for infusion pump sensors. |
| Texas Hydrogen Hub Partnership | High-pressure hydrogen-compatible sensor qualification captures Department of Energy-funded compression infrastructure demand. |
| ASIL-D Certification Acceleration | Shortened validation timelines defend automotive incumbent position against emerging MEMS suppliers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with Tier 1 automotive procurement officers, biomedical engineers at hospital purchasing committees, plant engineers at California refineries, and aftermarket service heads at industrial distributors with secondary validation against NHTSA guidance documents, FDA 510(k) submission databases, EPA emissions monitoring rulemakings, and SEC filings from diversified sensor manufacturers. Bottom-up unit demand modeling and top-down market sizing triangulated across piezoresistive, capacitive, and optical technology segments.
Historical reference periods anchored the projection horizon to observed adoption curves for brake-by-wire systems, battery thermal management architectures, and hydrogen infrastructure buildout. The analytical framework modeled demand across product type, technology platform, end-user certification tier, and installation configuration, with CAGRs derived from segment-level unit expansion and value-per-unit trends. Forecast inputs included electric vehicle platform sensor counts, semiconductor fab construction pipelines, and South Coast Air Quality Management District permit timelines.
Underlying measurement precision varies by segment; automotive and medical applications carry tighter precision than commodity industrial maintenance markets due to visible OEM procurement data and FDA submission tracking. Forecasts reflect assumptions about NHTSA rulemaking pace, silicon wafer supply stability, and hydrogen hub deployment schedules. Deviation in FDA cybersecurity enforcement intensity or East Asian foundry capacity expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Wearable Temperature Sensors Market
Sensors and Controls
Europe Acoustic Sensors Market
Sensors and Controls
DCT Mechatronic Control Unit Market
Sensors and Controls
Battery Module Sensors Market
Sensors and Controls
Italy Digital Thermometer Market
Sensors and Controls
Global Industrial Smart Sensors Market
Sensors and Controls
Distributed Temperature Sensing Market
Sensors and Controls
Non-Glass Capacitive Sensors Market
Sensors and Controls
Asia-Pacific Current Transducer Market
Sensors and Controls
Smart Glove Market
Sensors and Controls
Shutter Sensors Market
Sensors and Controls
Inductive Proximity Sensors Market
Sensors and Controls
Robotic Sensors Market
Sensors and Controls
Exhaust Sensors for Automotive Market
Sensors and Controls
Brazil Electric Power Steering (EPS) Sensor Market
Sensors and Controls
MEMS Market