
 Surface Levelling Equipment Market | 2026-2036
Surface Levelling Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Surface Levelling Equipment Market Analysis
Equipment rental networks in North America is narrowing as national chains consolidate regional inventories around high-utilization laser screed and motor grader models. Wacker Neuson leverages its European manufacturing footprint to sustain cross-border parts availability for surface planer fleets. Husqvarna AB competes through specialized concrete finishing attachments that anchor its position in commercial slab work. Multiquip Inc. differentiates via portable vibratory screeds that dominate mid-scale paving jobs across the southwestern United States.
Surface levelling equipment encompasses motorized machinery designed to achieve precise horizontal or graded planes through blade manipulation, vibratory compaction, or rotary cutting, typically operating within tolerance ranges of three to six millimetres over ten metres depending on laser or GPS guidance integration. These systems serve primary industrial purposes in preparing subgrades for concrete pours, agricultural field drainage, and mineral extraction site rehabilitation. Motor graders occupy the largest installed base among product types due to their versatility across highway maintenance and residential earthworks, while concrete laser screeds command premium positioning in warehouse and logistics facility construction where flatness specifications are tightest. GPS-enabled technology segments are expanding fastest as semi-automatic blade control retrofits displace manual stake-and-string methods on large civil projects.
The EPA Tier 4 Final emissions framework and OSHA silica exposure limits jointly compel manufacturers to integrate dust suppression and after-treatment systems into surface planer and screed designs, raising engineering compliance costs but filtering marginal competitors from the North American market. EU REACH restrictions on hydraulic fluid formulations and the F-Gas Regulation governing climate-controlled operator cabs add parallel certification burdens for equipment sold across European member states. Stakeholders must monitor how forthcoming battery-electric powertrain mandates for construction zones reshape equipment weight distribution and blade hydraulic response characteristics.
Market Dynamics
GPS-enabled blade control systems are compressing project timelines for German road contractors facing EU Green Deal emissions deadlines, while Chinese inland provinces drive equipment deployment for high-speed rail corridors. This technological-regulatory intersection is restructuring fleet investment priorities across both mature and emerging construction markets.
Growth Catalysts
- EU Green Deal emissions standards:German contractors are retrofitting motor grader fleets with GPS guidance to meet Tier 4 Final equivalent off-road machinery rules, accelerating replacement cycles in Europe's largest equipment market.
- High-speed rail earthworks:China's inland provinces require precision subgrade preparation for 350 km/h rail corridors, concentrating demand for laser screed and motor grader deployment in Sichuan and Shaanxi.
- Silica exposure mandates:OSHA's respirable crystalline silica limits are compelling dust suppression integration into surface planer designs, filtering marginal competitors from the North American rental channel.
Market Restraints
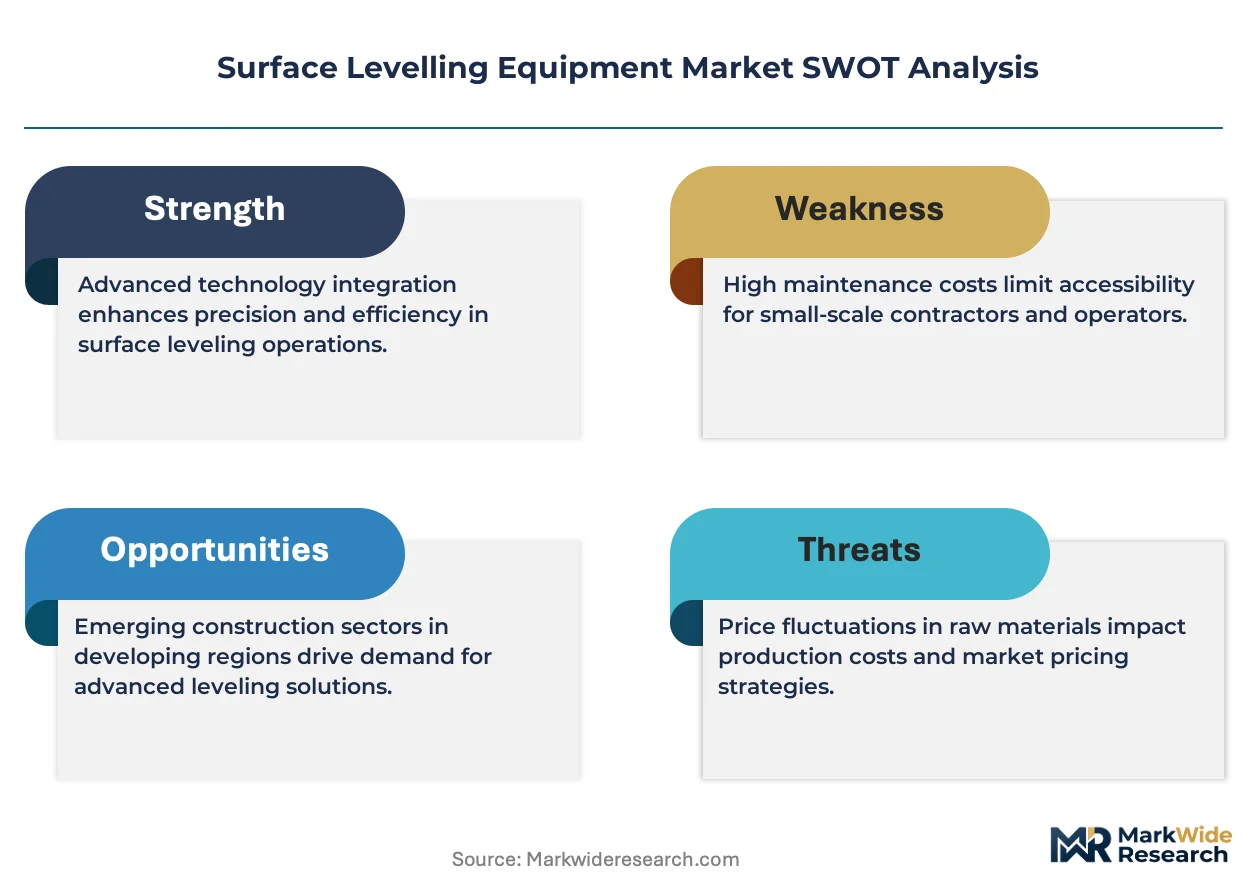
- Hydraulic fluid formulation costs:EU REACH restrictions on mineral oil alternatives are raising compliance burdens for equipment sold across member states, particularly affecting mid-tier manufacturers without captive chemical supply.
- After-treatment system integration:EPA Tier 4 Final diesel particulate filters and selective catalytic reduction hardware add weight and cooling requirements that degrade blade response characteristics in compact graders.
- Battery-electric powertrain immaturity:Energy density limitations in lithium-ion packs for construction equipment extend charging intervals beyond acceptable jobsite downtime thresholds for continuous earthmoving operations.
Strategic Opportunities
- Semi-automatic stakeless grading:GPS blade control retrofits are displacing manual stake-and-string methods on large civil projects, opening aftermarket attachment revenue for precision agriculture technology crossovers.
- Warehouse flatness specifications:E-commerce logistics facility construction demands tighter tolerance concrete finishing than highway work, positioning laser screed vendors for premium pricing in industrial submarkets.
- Rental fleet consolidation:North American national chains are absorbing regional inventories around high-utilization models, creating white space for specialized concrete finishing attachments in commercial slab segments.
Industry Challenges
- Telematics integration complexity:Legacy motor grader hydraulic architectures resist seamless integration with IoT-enabled fleet management platforms, delaying real-time blade position monitoring deployment.
- Cross-border parts availability:European manufacturing footprints must sustain spare parts logistics across Schengen and non-Schenen jurisdictions, complicating inventory positioning for surface planer blade consumables.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surface Levelling Equipment Market |
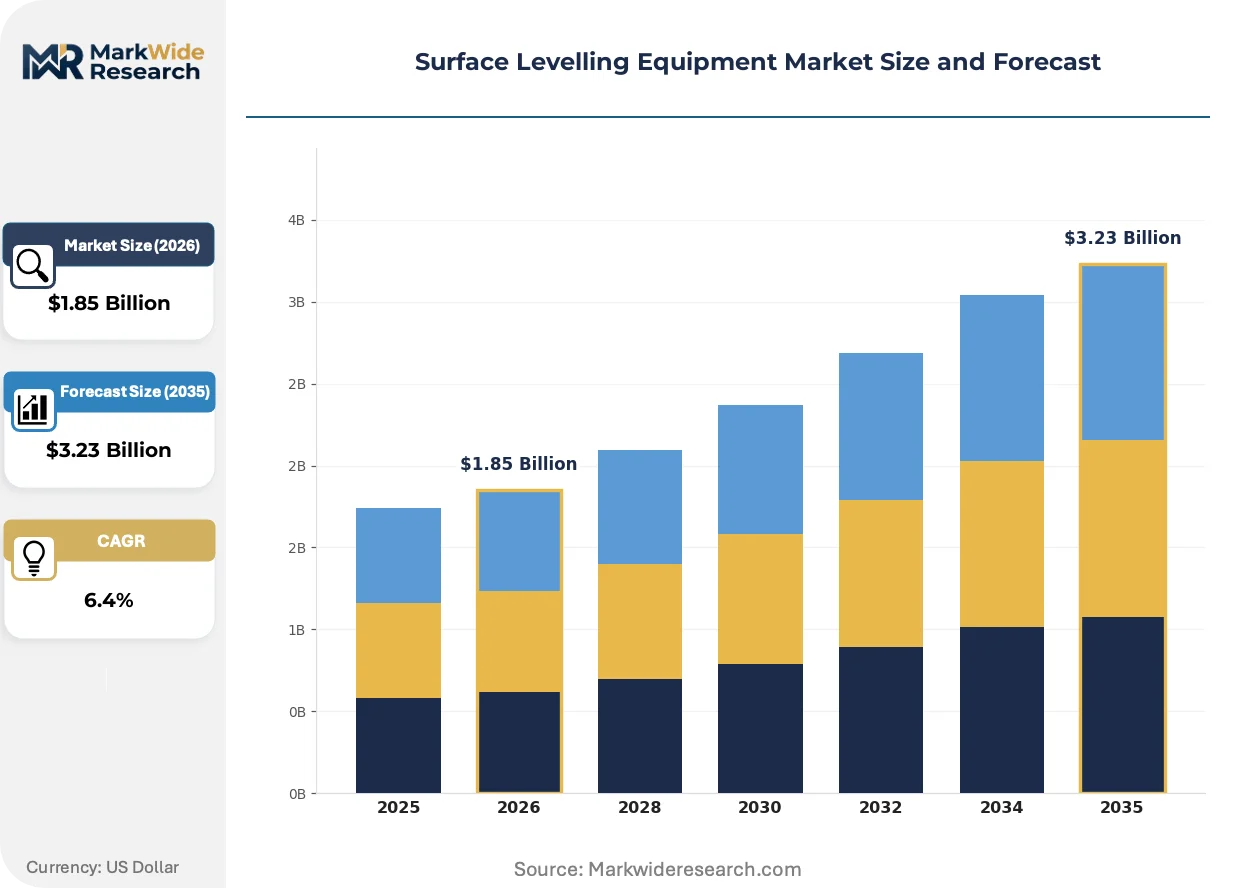
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
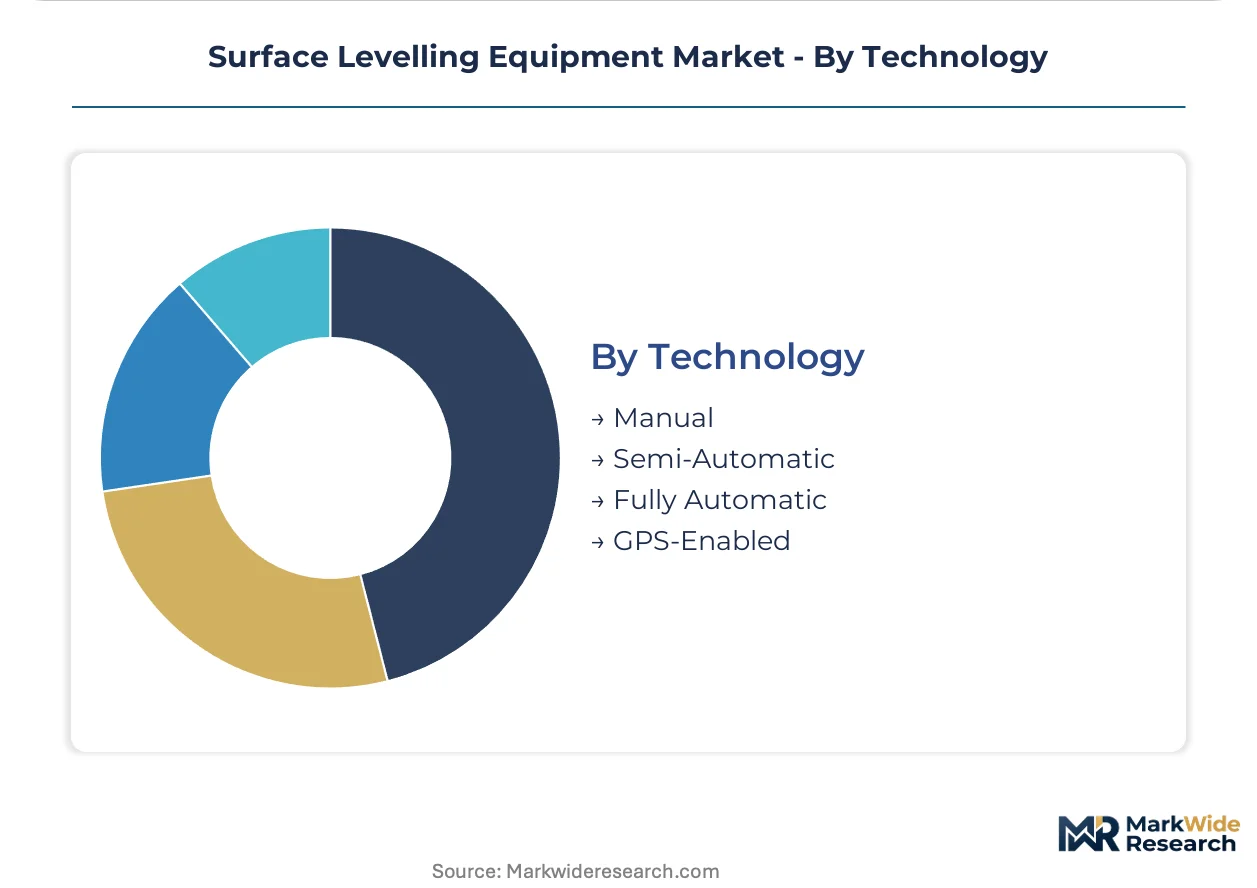
| Segmentation | Product Type: Laser Leveling Systems, Motor Graders, Surface Planers, Concrete Laser Screeds Application: Construction, Agriculture, Landscaping, Mining End User: Contractors, Farmers, Municipalities, Mining Companies Technology: Manual, Semi-Automatic, Fully Automatic, GPS-Enabled |
| Companies Covered | MBW Inc., Bartell Global Inc., Wacker Neuson, Chicago Pneumatic, Husqvarna AB, Allen Engineering Corporation, Lievers Holland, Multiquip Inc., Lindley, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surface Levelling Equipment Market Emerging Trajectories
Autonomous blade control and electric powertrains are converging to reshape equipment operator roles and jobsite energy logistics. These shifts are compressing traditional skill hierarchies while opening new service revenue architectures.
Laser-guided concrete screed technology is collapsing the tolerance gap between manual wet screeding and machine-controlled flatness. Warehouse and logistics facility contractors in the United States are adopting these systems at replacement-cycle velocity. The structural consequence is collapsing premium pricing for superflat floor specifications previously requiring specialized German imports.
The F-Gas Regulation governing climate-controlled operator cabs is accelerating heat pump and low-global-warming-potential refrigerant adoption in European equipment designs. This industrial consequence raises engineering costs but creates compliance differentiation for manufacturers with integrated HVAC development capabilities. Motor grader and surface planer categories sold across Germany, France, and Benelux are responding with modular cab retrofit programs.
Equipment-as-a-service contracting is displacing outright purchase for mid-scale paving contractors in the southwestern United States. Rental networks are unbundling maintenance and telematics subscriptions from hourly machine rates. This pattern is most visible in Arizona and Texas commercial slab markets where project volatility makes fixed asset ownership uneconomical.
Surface Levelling Equipment Market Segmentation
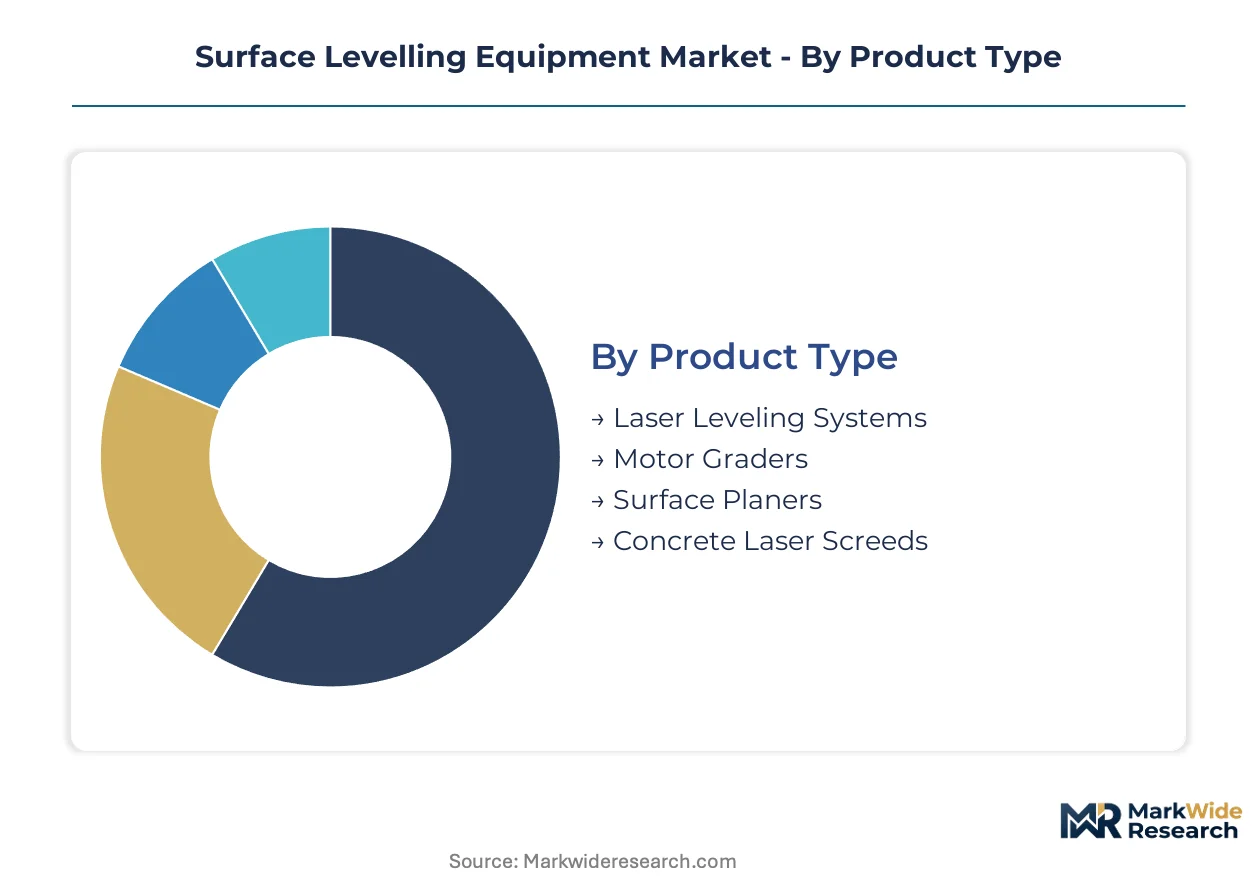
Surface levelling equipment segmentation reveals divergent replacement cycles across product categories. Contractors align fleet composition with project duration, tolerance specifications, and regulatory compliance windows rather than uniform depreciation schedules.
Product Type:
Motor graders turn over every 7-10 years under heavy highway utilization, while concrete laser screeds cycle faster at 4-6 years due to precision component wear. Surface planers and laser leveling systems occupy intermediate positions shaped by cutting blade consumption and optical calibration intervals.
- Motor Graders:Articulated-frame designs with moldboard widths spanning 3.7 to 4.9 meters dominate highway maintenance and residential earthworks. German road contractors are retrofitting these units with GPS blade control to meet EU Green Deal emissions deadlines, accelerating replacement decisions in Europe's largest equipment market.
- Concrete Laser Screeds:Self-propelled and ride-on configurations achieve flatness tolerances of FF50-FF100 for warehouse slab specifications. E-commerce logistics facility construction in the United States is concentrating demand where superflat floor requirements exceed highway-grade finishing capabilities.
- Surface Planers:Rotary drum cutters with carbide-tipped teeth remove asphalt or concrete to precise depths. OSHA silica exposure mandates are forcing dust suppression integration into new unit designs, filtering marginal competitors from North American rental channels.
- Laser Leveling Systems:Mast-mounted laser receivers paired with hydraulic blade controls enable subgrade preparation within three-millimetre tolerances. Agricultural field drainage projects in the midwestern United States represent concentrated uptake for precision land forming applications.
Motor graders dominate installed base. Concrete laser screeds are where expansion concentrates.
Application:
Construction commands premium pricing for tight-tolerance equipment, while mining and agriculture tolerate wider deviation bands at lower capital intensity. Landscaping occupies a mid-tier position where aesthetic finish requirements meet constrained municipal procurement budgets.
- Construction:Highway, commercial slab, and residential subdivision projects require graduated precision levels from rough cut to final grade. China's inland provinces are driving motor grader and laser screed deployment for high-speed rail corridor earthworks in Sichuan and Shaanxi.
- Agriculture:Field drainage, irrigation preparation, and land reclamation utilize laser leveling systems for uniform water distribution. The southwestern United States concentrates demand where water scarcity mandates precision surface management for crop yield optimization.
- Mining:Haul road maintenance and site rehabilitation employ motor graders with reinforced frames for abrasive operating conditions. Mineral extraction companies in Australia prioritize dust-sealed cab designs for operator protection in arid climates.
- Landscaping:Golf course construction, park development, and residential hardscaping utilize compact graders and walk-behind screeds. Municipal procurement cycles in France and Benelux favor equipment-as-a-service contracting to manage volatile project pipelines.
Construction generates highest equipment revenue per unit hour. Agriculture delivers the steepest expansion trajectory for GPS-enabled retrofits.
End User:
Contractors maintain the most heterogeneous fleets, mixing owned core assets with rental supplementation. Municipalities and mining companies favor captive fleets with extended depreciation horizons, while farmers concentrate investment in single-purpose laser leveling systems.
- Contractors:Road construction, commercial paving, and earthmoving specialists balance motor grader ownership against laser screed rental for project-specific tolerance demands. National rental chain consolidation in North America is narrowing equipment availability around high-utilization models.
- Farmers:Large-scale agricultural operations in the midwestern United States and Australian wheat belts invest in mast-mounted laser systems for field drainage efficiency. Equipment-as-a-service penetration remains limited due to seasonal utilization concentration.
- Municipalities:City and county highway departments maintain motor grader fleets for snow removal and road maintenance across extended service intervals. EPA Tier 4 Final compliance costs are compressing procurement volumes for mid-sized municipal operators.
- Mining Companies:Integrated and contract miners deploy heavy-duty graders with reinforced drawbars and circle gear protection. Telematics integration complexity delays real-time blade position monitoring deployment in legacy fleet architectures.
Contractors represent the largest addressable equipment spend. Farmers are gaining share fastest in GPS-enabled technology adoption.
Technology:
Manual and semi-automatic systems retain installed base dominance, while GPS-enabled segments capture incremental investment. Fully automatic configurations remain nascent outside demonstration projects and autonomous mining trials.
- GPS-Enabled:Satellite-guided blade control with RTK correction achieves two-centimetre vertical accuracy without stake-and-string reference. German contractors facing EU Green Deal emissions standards are prioritizing these retrofits to compress project timelines and reduce rework fuel consumption.
- Semi-Automatic:Laser or sonic sensor-assisted hydraulic control reduces operator skill requirements for consistent grade achievement. Warehouse and logistics facility contractors in the United States are adopting these systems at replacement-cycle velocity for commercial slab work.
- Manual:Conventional lever-operated blade control persists in emerging markets and legacy fleet operations where capital constraints override precision requirements. Basic motor graders without guidance integration dominate municipal procurement in price-sensitive jurisdictions.
- Fully Automatic:Autonomous blade control with machine learning path planning remains confined to mining haul road maintenance and experimental highway construction pilots. Battery-electric powertrain immaturity constrains continuous operation viability for earthmoving duty cycles.
Semi-automatic systems anchor current revenue. GPS-enabled configurations are climbing the fastest as precision agriculture technology crossovers penetrate construction applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing for GPS-enabled surface levelling equipment commands 40% higher unit economics in Germany than in China's inland provinces, creating a stark regional asymmetry in manufacturer margin capture and technology deployment timelines.
United States
Warehouse construction in Dallas-Fort Worth and Phoenix drives laser screed deployment for e-commerce logistics facilities. OSHA silica exposure mandates filter marginal competitors from rental channels. Arizona and Texas commercial slab markets concentrate equipment-as-a-service contracting adoption.
Germany
Road contractors in Bavaria and North Rhine-Westphalia retrofit motor grader fleets with GPS blade control to compress project timelines. EU Green Deal emissions standards accelerate replacement cycles for Tier 4 Final equivalent off-road machinery. Stuttgart industrial corridor anchors precision agriculture technology crossover into construction applications.
China
High-speed rail earthworks in Sichuan and Shaanxi provinces concentrate demand for motor graders and laser screeds capable of 350 km/h corridor subgrade preparation. MEE dual carbon goals reshape equipment procurement specifications for infrastructure state-owned enterprises. Chengdu-Chongqing economic circle drives precision earthmoving equipment deployment inland.
India
National highway expansion under Bharatmala Pariyojana generates motor grader demand across Maharashtra and Gujarat. BIS certification requirements for construction machinery raise compliance barriers for imported surface planers. Mumbai-Pune industrial corridor concentrates rental fleet investment for road contractors.
Australia
Mineral extraction haul road maintenance in Western Australia and Queensland employs heavy-duty graders with dust-sealed cab designs. TGA-equivalent state-level equipment safety frameworks govern autonomous blade control trials in Pilbara mining operations. Perth engineering services cluster supports telematics integration for legacy fleet architectures.
Surface Levelling Equipment Market Vendor Landscape
Full-line manufacturers and specialized attachment producers split the market along precision-versus-versatility lines. The vendor base concentrates around three strategic tiers: European engineering-centric groups, North American rental-channel specialists, and Asia-Pacific scale fabricators. Dominant competitive moves include GPS guidance technology licensing partnerships and cross-border spare parts logistics consolidation.
Within the European engineering tier, Wacker Neuson and Husqvarna AB exemplify divergent specialization strategies. Wacker Neuson leverages its manufacturing footprint to sustain parts availability across Schengen jurisdictions. Husqvarna AB occupies a position in concrete finishing attachments for commercial slab segments. Among North American rental-channel specialists, Multiquip Inc. anchors portable vibratory screed supply for southwestern United States paving contractors.
| Leading Market Players |
|---|
| MBW Inc. |
| Bartell Global Inc. |
| Wacker Neuson |
| Chicago Pneumatic |
| Husqvarna AB |
| Allen Engineering Corporation |
| Lievers Holland |
| Multiquip Inc. |
| Lindley, Inc. |
| Others |
Supply Flow & Price Mechanics
Tariff exposure on German-made hydraulic components widens the customization-premium spread between configured-to-order motor graders and standard inventory units, compressing margins for mid-tier assemblers while rewarding captive manufacturing footprints in Schengen jurisdictions.
Pricing Analysis
The customization-premium spread separates GPS-enabled blade control retrofits from base motor grader configurations by fifteen to twenty-five percent depending on RTK correction tier and telematics bundling. Pricing stratifies across premium, standard, and economy tiers anchored by CE certification grade, EPA Tier 4 Final compliance status, and after-sales service coverage duration. Cost compression in standard-grade equipment is intensifying because Chinese scale fabricators are exporting laser screed platforms at contract-based long-term offtake terms. Municipal highway departments exhibit highest price sensitivity due to fixed procurement budgets, while e-commerce logistics facility developers demonstrate lowest sensitivity given superflat floor specification premiums.
Supply Chain Analysis
Supplier-financing facilities extended by German and Austrian hydraulic component manufacturers allow mid-scale motor grader assemblers to manage working capital through ninety-day payment terms on precision valve assemblies. Manufacturing concentrates in Germany, China, and the United States for final assembly, with critical inputs drawing from Japanese servo motors, Italian hydraulic pumps, and Chinese steel castings. Single-source vulnerability sits with RTK correction module suppliers concentrated in Bavaria engineering clusters. Distribution runs through national rental chain networks in North America and captive dealer arrangements in European member states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering cyclical recovery driven by EU Green Deal emissions deadlines accelerating replacement cycles for Tier 4 Final equivalent off-road machinery across German road construction fleets.
For Market Incumbents: Pre-empt margin erosion from Chinese scale fabricators by securing captive supply of laser receiver modules through backward integration into precision agriculture technology suppliers. Accelerate certification investment for F-Gas Regulation compliance in climate-controlled cab designs to filter marginal competitors from Benelux and French municipal procurement channels. For New Entrants and Emerging Players: Build out equipment-as-a-service contracting capabilities targeting Arizona and Texas commercial slab markets where project volatility makes fixed asset ownership uneconomical for mid-scale paving contractors. Penetrate the agricultural laser leveling segment in the midwestern United States through seasonal rental partnerships with irrigation equipment dealers. For Investors and Strategic Acquirers: EPA Tier 4 Final and EU Green Deal implementation reshapes the acquisition landscape toward targets with integrated after-treatment system engineering capabilities and cross-border parts logistics infrastructure. Long-term viability centers on manufacturers capable of bridging precision agriculture technology crossovers into construction applications. Monitor battery-electric powertrain energy density breakthroughs as the signal for inflection in equipment weight distribution and hydraulic response characteristics.| Strategic Initiative | Industry Significance |
|---|---|
| GPS Guidance Technology Licensing | RTK correction partnerships with precision agriculture vendors compress German contractor project timelines. |
| Cross-Border Spare Parts Consolidation | Schengen logistics hubs reduce surface planer blade consumable lead times for Wacker Neuson service networks. |
| Equipment-as-a-Service Platform Launch | Unbundled maintenance subscriptions capture Arizona and Texas commercial slab contractor spend. |
| Dust Suppression System Integration | OSHA silica compliance filters marginal competitors from North American surface planer rental channels. |
| Battery-Electric Powertrain Development | Energy density improvements would reshape motor grader weight distribution and blade hydraulic response. |
Methodological Framework
A spread of perspectives from fleet managers at national rental chains, procurement leads at German road construction contractors, aftermarket service heads at European manufacturers, and precision agriculture technology developers converged on the working assumptions for GPS-enabled blade control adoption trajectories. Primary interview insights combined with secondary validation from EPA enforcement data, EU Green Deal implementation timelines, OSHA silica exposure rulemaking records, and customs trade statistics for surface levelling equipment imports. Bottom-up equipment unit economics and top-down construction sector capex projections were triangulated to anchor market sizing.
Demand-supply-balance framing across the analysis window modeled motor grader and laser screed deployment against high-speed rail earthworks timelines in Chinese inland provinces and warehouse construction pipelines in Dallas-Fort Worth and Phoenix. Segmentation dimensions included product type, application, end user, and technology tier with industry-specific treatment of GPS guidance integration levels. CAGRs were derived from replacement cycle compression effects and regulatory compliance windows rather than extrapolated historical trends. Forecast inputs incorporated EU REACH hydraulic fluid formulation cost trajectories and lithium-ion energy density improvement curves for construction equipment duty cycles.
Sensitivities concentrate around EPA Tier 4 Final enforcement intensity, EU Green Deal implementation pacing, and battery-electric powertrain commercialization timelines for continuous earthmoving operations. Forecasts reflect documented assumptions regarding German contractor fleet retrofit decisions and Chinese state-owned enterprise procurement specifications. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Bandsaw Market
Tools
Level Floats Market
Tools
Tool Storage Market
Tools
Entrenching Tool Market
Tools
Air Drills Market
Tools
Welding Guns Market
Tools
Nail Gun Market
Tools
Manual Cutting Equipment Market
Tools
Global Zero Point Clamping System Market
Tools
Automatic Heat Press Machines Market
Tools
Rivet Gun Market
Tools
Air Hammer Market
Tools
Hand Tools Market
Tools
Tile Cutter Market
Tools
Drill Presses Market
Tools
Blowing Torch Market