
 Hydraulic Spreader Market | 2026-2036
Hydraulic Spreader Market Size, Share, and Industry Trends Forecast 2026-2036
Hydraulic Spreader Market Foresight
The direct-to-municipality sales channel is narrowing as regional distributors consolidate procurement contracts for hydraulic rescue tools. IDEX Corporation leverages its portfolio breadth to sustain long-term service agreements with North American fire departments. Enerpac anchors industrial applications through its established hydraulic systems expertise, while Holmatro dominates European emergency services with specialized extrication equipment.
A hydraulic spreader is a high-force tool that uses pressurized fluid to generate linear spreading motion, typically achieving forces exceeding 100 kN through hardened alloy steel arms and precision-sealed hydraulic cylinders. Its primary purpose is to separate compressed materials or structures in rescue, construction, and maintenance operations where mechanical advantage exceeds human or pneumatic capacity. Standard spreaders occupy the mature volume tier with predictable replacement cycles, while dual action spreaders command premium positioning due to their bidirectional operational efficiency in confined extrication scenarios. Emergency services applications concentrate margin pools where NFPA and EN compliance certifications create procurement barriers.
OSHA workplace safety standards and the EU Machinery Directive shape product design mandates, forcing manufacturers to integrate load-holding valves and ergonomic control interfaces. Germany's KBA and France's ANSM influence type-approval pathways for rescue equipment deployed in public safety fleets. Stakeholders must monitor evolving interoperability requirements between hydraulic spreaders and competing battery-powered extrication tools.
Market Dynamics
Municipal fire departments across Germany, the United States, and Japan are consolidating procurement contracts into multi-year framework agreements, compressing vendor margins while demanding integrated rescue tool systems rather than standalone hydraulic spreaders.
Growth Catalysts
- Emergency vehicle fleet modernization:Fire departments in Germany are replacing legacy mechanical rescue tools with hydraulic systems that meet updated EN 13204 standards for spreading force verification.
- NFPA 1936 compliance mandates:North American fire departments face procurement deadlines requiring certified hydraulic rescue equipment, accelerating replacement cycles for aging spreader inventories.
- Urban tunnel infrastructure expansion:Construction authorities in Japan are specifying hydraulic spreaders for confined-space structural collapse scenarios, creating parallel demand beyond traditional emergency services.
Market Restraints
- Hardened alloy steel input volatility:Specialized metallurgical grades required for spreader arms face price instability tied to nickel and chromium supply concentration in specific mining jurisdictions.
- Single-source hydraulic cylinder sealing:Precision seal manufacturing clusters in Germany create supply vulnerability for non-European assemblers seeking qualified component suppliers.
- Battery-powered extrication substitution:Cordless rescue tools from competing technology categories are capturing share in light-vehicle extrication scenarios where spreading force requirements are moderate.
Strategic Opportunities
- Indian industrial maintenance vertical:Power plant and refinery operators in Gujarat and Maharashtra are adopting hydraulic spreaders for heat exchanger and pipeline maintenance, representing an underpenetrated application segment.
- EU Green Deal circularity requirements:Machinery remanufacturing mandates are creating certified refurbishment pathways for hydraulic spreader cores, extending asset life cycles and opening service revenue streams.
- Telematics-integrated fleet management:Convergence of hydraulic tool diagnostics with municipal asset tracking systems enables predictive maintenance contracts and usage-based pricing models.
Industry Challenges
- Hydraulic systems technician scarcity:Fire department maintenance divisions lack personnel trained in high-pressure fluid system diagnostics and seal replacement protocols.
- EN 13204 recertification timelines:Spreader manufacturers face extended approval periods as notified bodies adapt testing protocols for bidirectional spreading force measurement.
- Legacy pneumatic tool integration:Municipal fleets with mixed rescue equipment inventories struggle to standardize training and maintenance procedures across hydraulic and compressed-air systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydraulic Spreader Market |
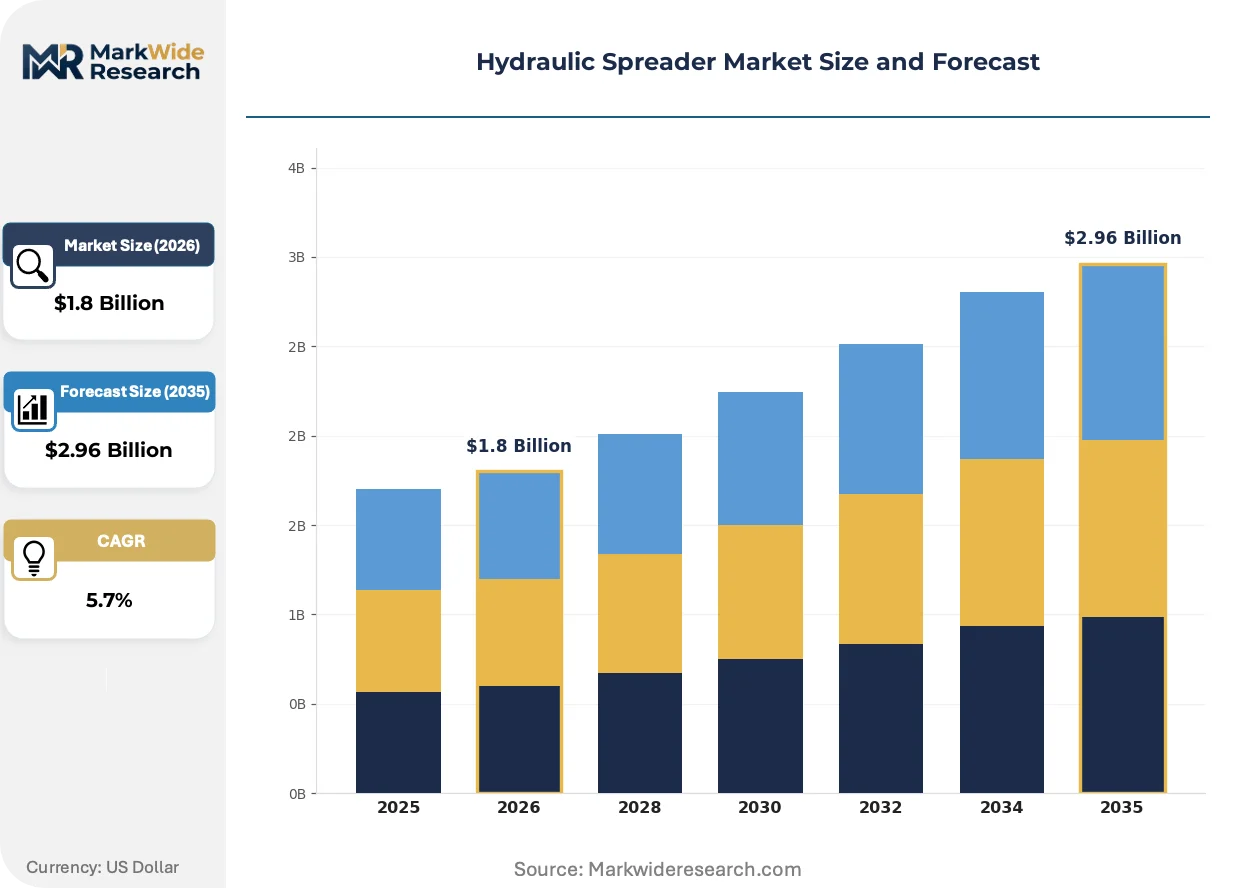
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Spreaders, Variable Spreaders, Fixed Spreaders, Dual Action Spreaders End User: Construction, Agriculture, Emergency Services, Waste Management Technology: Hydraulic, Mechanical, Pneumatic, Manual Application: Landscape Management, Agricultural Application, Flood Response, Firefighting |
| Companies Covered | IDEX Corporation, Enerpac, Bosch Rexroth, Holmatro, Phoenix Rescue Equipment, Equalizer International Ltd, Weber-Hydraulik, Amkus, Rehobot, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydraulic Spreader Market Shifts & Advancements
Electrification of rescue tool power sources and digital integration of maintenance diagnostics are compressing traditional product life cycles while opening adjacent service revenue streams for equipment vendors.
Composite-reinforced spreader arms incorporating carbon fiber hybrid structures are reducing tool weight by approximately thirty percent without sacrificing spreading force capacity. Fire departments in Scandinavian municipalities are piloting these lightweight configurations for rapid deployment scenarios. The technology is rendering obsolete traditional all-steel arm designs that limit single-operator maneuverability in confined vehicle extrications.
The EU Machinery Directive's 2023 update mandates integrated load-holding valves and ergonomic control interfaces for all hydraulic rescue tools sold within member states. German manufacturers are redesigning control architectures to incorporate redundant safety interlocks and force-feedback handles. Spreader models lacking these certifications are being withdrawn from European municipal tender processes, reshaping competitive positioning in the region's largest market.
Consolidated procurement frameworks are displacing single-tool purchasing across North American fire departments. Regional cooperative purchasing organizations in Texas and California are aggregating demand across dozens of municipalities, extracting volume discounts and standardized service terms. This concentration is most visible in the United States, where IDEX Corporation and specialized distributors are restructuring sales organizations to respond to RFP-driven purchasing rather than relationship-based account management.
Hydraulic Spreader Market Segmentation
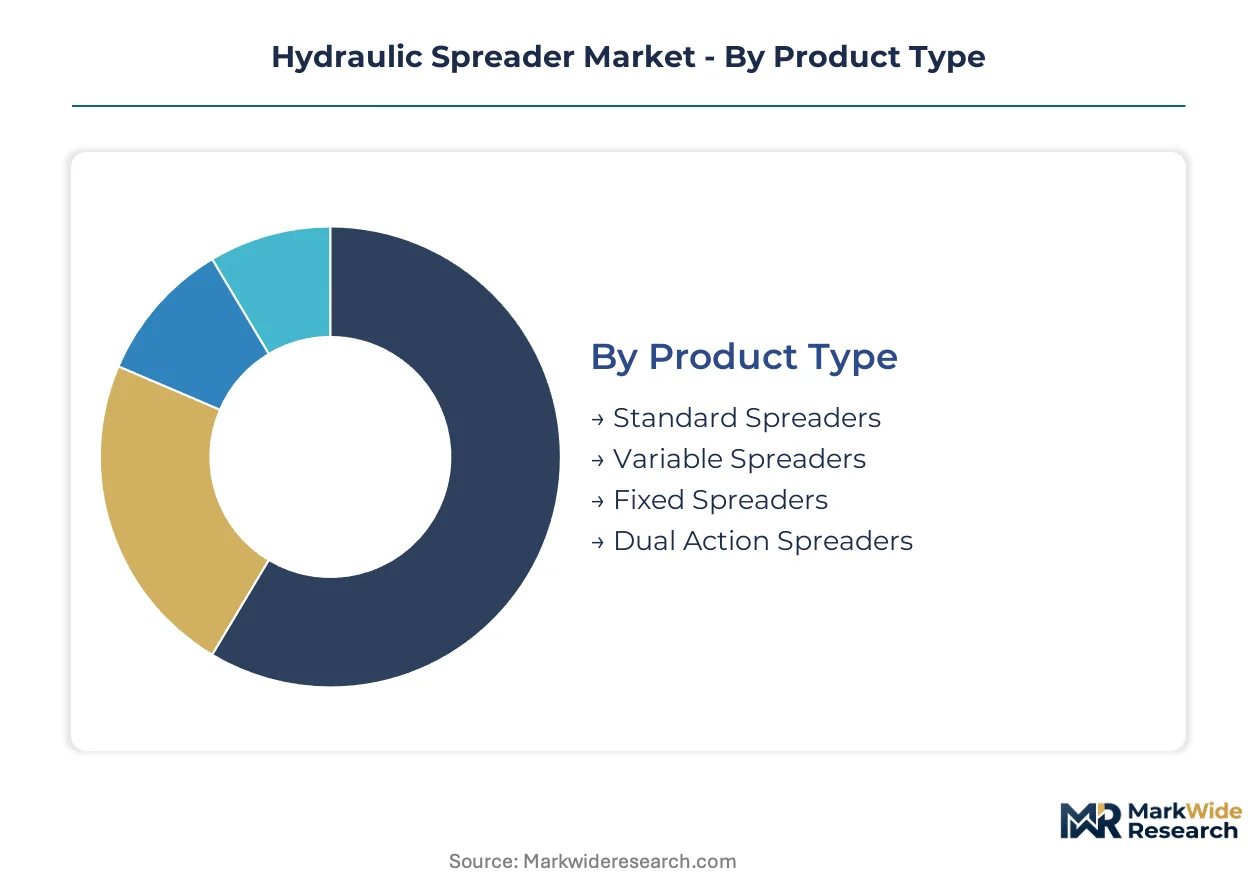
Segmentation in hydraulic spreaders reveals divergent replacement dynamics across product architectures and end-use environments. Cycle times compress where regulatory certification mandates accelerate turnover, while industrial maintenance applications sustain extended asset lifecycles.
Product Type:
Replacement velocity varies sharply across hydraulic spreader architectures, with certified emergency-service configurations turning over fastest due to EN 13204 and NFPA 1936 recertification deadlines.
- Standard Spreaders:These units employ single-acting hydraulic cylinders with fixed arm geometries, delivering predictable spreading force for routine vehicle extrication. German municipal fire departments in Bavaria and North Rhine-Westphalia are retiring legacy standard units ahead of updated EU Machinery Directive compliance deadlines.
- Dual Action Spreaders:Bidirectional hydraulic circuits enable simultaneous arm extension and retraction without cylinder reset, cutting operational cycle time by half in confined-space rescues. Demand concentrates in Japanese urban tunnel authorities and Scandinavian rapid-response brigades where single-operator deployment is mandatory.
- Variable Spreaders:Adjustable arm pivot points allow field reconfiguration for spreading versus crushing operations.
- Fixed Spreaders:Rigid arm geometry limits these to dedicated industrial maintenance roles with lower duty-cycle requirements.
Standard spreaders dominate installed base across municipal fleets globally. Dual action spreaders are where expansion concentrates as procurement shifts toward integrated rescue tool systems.
End User:
Margin structures diverge across customer categories, with certified emergency services commanding premium pricing while industrial buyers negotiate volume-driven service agreements.
- Emergency Services:Municipal fire departments and dedicated rescue squads require NFPA 1936 or EN 13204 certified equipment with traceable spreading force documentation. Procurement in Texas and California runs through consolidated cooperative purchasing organizations that aggregate demand across dozens of municipalities.
- Construction:Infrastructure contractors deploy hydraulic spreaders for structural steel positioning and formwork separation. Japanese construction authorities specify these tools for confined-space collapse scenarios in urban tunnel networks.
- Agriculture:Farm equipment repair shops use lower-force spreaders for machinery maintenance and implement adjustment.
- Waste Management:Recycling facilities employ spreaders for bale breaking and container decompression with minimal precision requirements.
Emergency services anchor premium revenue pools through compliance-driven replacement cycles. Construction is climbing the fastest as infrastructure investment accelerates across East Asian markets.
Technology:
Technology selection determines maintenance burden and operator training depth, with hydraulic systems demanding specialized technician expertise that constrains adoption in under-resourced departments.
- Hydraulic:Pressurized fluid systems achieving forces exceeding 100 kN through hardened alloy steel arms and precision-sealed cylinders. OSHA workplace safety standards and the EU Machinery Directive mandate load-holding valves and ergonomic control interfaces for all hydraulic rescue tools sold within member states.
- Pneumatic:Compressed-air systems offer lighter weight and simpler maintenance but deliver lower peak force. French fire departments with legacy pneumatic inventories struggle to standardize training across mixed equipment fleets.
- Mechanical:Ratchet and screw mechanisms serve low-force applications without external power requirements.
- Manual:Hand-operated spreaders persist in remote agricultural settings with intermittent usage patterns.
Hydraulic technology captures the dominant share of new procurement in certified rescue applications. Battery-powered alternatives are gaining share fastest in light-vehicle extrication where moderate spreading force suffices.
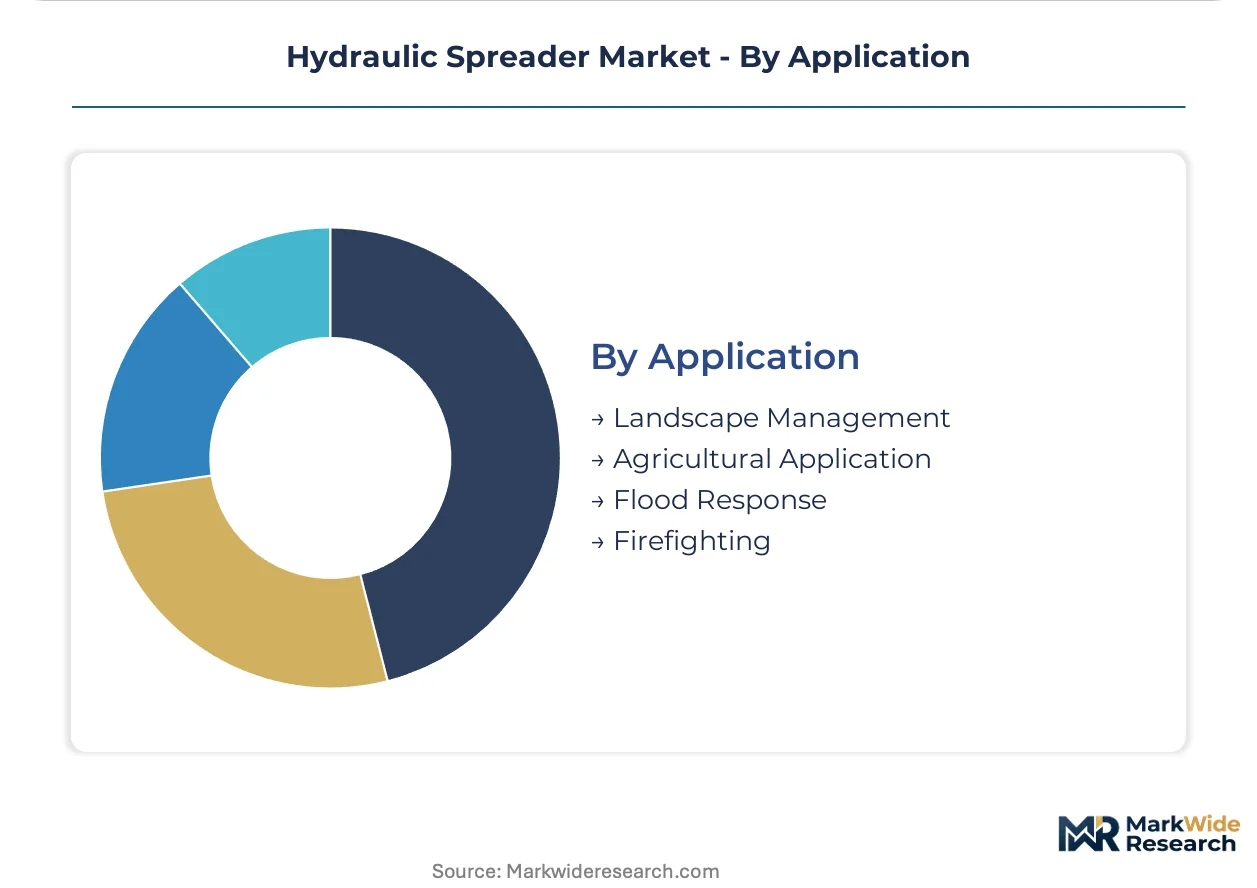
Application:
Application-specific requirements shape force-range specifications and portability demands, with flood response and firefighting imposing the most severe operational constraints.
- Firefighting:Vehicle extrication demands rapid deployment, bidirectional operation, and compatibility with integrated rescue tool systems. German manufacturers Holmatro and Weber-Hydraulik anchor production clusters serving both domestic rescue services and export markets.
- Flood Response:Structural debris removal and barrier installation require corrosion-resistant finishes and extended reach capabilities. Japanese authorities specify hydraulic spreaders for confined-space scenarios following urban flooding events.
- Agricultural Application:Machinery repair and livestock handling equipment maintenance drive demand for mid-force portable units.
- Landscape Management:Tree and root separation applications utilize lower-force spreaders with extended arm geometries.
Firefighting commands the largest certified-equipment procurement volume. Flood response is expanding most quickly as climate adaptation investments accelerate infrastructure hardening programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German municipalities extract 15-20% pricing premiums over North American fire departments due to stricter EN 13204 certification requirements and consolidated procurement frameworks. This asymmetry compresses margins for exporters serving German specifications while rewarding domestic producers with qualified testing infrastructure.
United States
Texas and California cooperative purchasing organizations aggregate demand across dozens of municipalities, extracting volume discounts from vendors. OSHA workplace safety standards mandate load-holding valves and ergonomic control interfaces for all hydraulic rescue tools. Regional distributors in the Southeast are consolidating procurement contracts, displacing direct-to-department sales channels.
Germany
Bavaria and North Rhine-Westphalia fire departments are retiring legacy standard spreaders ahead of updated EU Machinery Directive compliance deadlines. KBA type-approval pathways influence rescue equipment deployed in public safety fleets. Holmatro and Weber-Hydraulik anchor production clusters serving both domestic rescue services and export markets.
Japan
Urban tunnel authorities in Tokyo and Osaka specify hydraulic spreaders for confined-space structural collapse scenarios. METI infrastructure investment programs accelerate replacement cycles for aging municipal rescue equipment. Japanese construction authorities are creating parallel demand beyond traditional emergency services through climate adaptation investments.
France
ANSM and CNIL influence type-approval pathways for rescue equipment in public safety fleets. French fire departments with legacy pneumatic inventories struggle to standardize training across mixed equipment fleets. Municipal procurement in Île-de-France is shifting toward integrated rescue tool systems rather than standalone hydraulic spreaders.
India
Power plant and refinery operators in Gujarat and Maharashtra are adopting hydraulic spreaders for heat exchanger and pipeline maintenance. BIS certification requirements are creating procurement barriers for uncertified equipment imports. Industrial maintenance verticals represent underpenetrated application segments with extended asset lifecycles.
Hydraulic Spreader Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying precision-sealed cylinders and hardened alloy steel arms. The vendor base structures around three tiers: diversified industrial conglomerates with rescue tool portfolios, dedicated hydraulic equipment manufacturers, and regional fabricators serving maintenance verticals. Two dominant competitive moves are reshaping positioning: consolidated procurement frameworks are forcing sales organization restructuring toward RFP-driven account management, and EU Green Deal circularity mandates are opening certified refurbishment service revenue streams.
Among diversified industrial conglomerates, IDEX Corporation occupies a position exemplifying portfolio breadth across rescue tool categories. German specialists Holmatro and Weber-Hydraulik represent the dedicated equipment manufacturer archetype, anchoring production clusters that serve both domestic emergency services and export certification requirements. These three entities illustrate how geographic proximity to notified bodies and municipal procurement hubs translates into competitive positioning.
| Leading Market Players |
|---|
| IDEX Corporation |
| Enerpac |
| Bosch Rexroth |
| Holmatro |
| Phoenix Rescue Equipment |
| Equalizer International Ltd |
| Weber-Hydraulik |
| Amkus |
| Rehobot |
| Others |
Supply & Pricing Matrix
Undercapacity in German precision seal manufacturing is tightening supplier discipline and amplifying pricing power for domestic hydraulic component producers serving certified rescue tool assemblers. This utilization dynamic cascades downstream, where municipal procurement consolidation extracts volume concessions that compress margins for non-European vendors lacking localized testing infrastructure.
Pricing Analysis
Configured-to-order dual action spreaders command spreads exceeding standard units by substantial margins, reflecting bidirectional circuit complexity and EN 13204 recertification engineering. Three-tier pricing structure across premium certified, standard compliant, and economy industrial levels stratifies the market, with NFPA 1936 and EN 13204 certification tiers driving the steepest differentiation. Cost compression in standard spreaders is intensifying because consolidated cooperative purchasing organizations in Texas and California aggregate municipal demand into framework agreements. Industrial maintenance buyers in Indian power generation exhibit highest price sensitivity, while German emergency services procurement shows lowest sensitivity due to mandated compliance deadlines.
Supply Chain Analysis
Hardened alloy steel feedstock draws from metallurgical processing clusters in Germany, Sweden, and Japan, with specialized nickel-chromium grades tethered to concentrated mining jurisdictions. Precision hydraulic cylinder seals rest on German manufacturing capacity, while alloy steel arms hinge on Scandinavian and Japanese forging expertise. Single-source vulnerability concentrates in notified body certification pathways, where extended EN 13204 recertification timelines create approval bottlenecks. Distribution runs through regional cooperative purchasing organizations and specialized rescue equipment distributors, displacing direct-to-municipality sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where integrated rescue tool system interoperability is displacing standalone hydraulic spreader procurement, rewarding vendors with breadth across battery-powered and hydraulic categories.
For Market Incumbents: Pre-empt battery-powered extrication substitution by accelerating hybrid system development and securing long-term service contracts with consolidated municipal purchasers. Defend margin position through backward integration into precision seal manufacturing and captive control over German notified body relationships. Certification investment in bidirectional spreading force measurement protocols represents the critical defensive lever against emerging cordless competitors. For New Entrants and Emerging Players: Establish a beachhead in Indian industrial maintenance verticals where BIS certification requirements create procurement barriers for uncertified imports but demand remains underpenetrated. Target power plant and refinery operators in Gujarat and Maharashtra with heat exchanger maintenance applications, leveraging lower compliance burdens than emergency services segments. Telematics-integrated fleet management partnerships with municipal asset tracking providers offer the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vendors with predictive maintenance contracts and certified refurbishment capabilities under EU Green Deal circularity mandates. Long-term viability over the next decade favors platform integrators with rescue tool portfolio breadth and proximity to municipal procurement hubs. Acquisition targets should display vertical integration into precision hydraulic components and established notified body relationships. The signal to monitor is battery-powered extrication tool share capture in light-vehicle rescue scenarios.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Refurbishment Program | EU Green Deal circularity mandates extend asset lifecycles and open service revenue streams for hydraulic spreader cores. |
| Telematics Integration Partnership | Convergence with municipal asset tracking systems enables predictive maintenance contracts and usage-based pricing models. |
| Precision Seal Manufacturing Scale-Up | German seal production clusters create supply vulnerability that backward integration addresses for non-European assemblers. |
| Bidirectional Force Certification Investment | EN 13204 recertification timelines for dual action spreaders reshape competitive positioning in European tender processes. |
| Industrial Maintenance Channel Development | Indian power plant and refinery operators in Gujarat represent underpenetrated demand with extended replacement cycles. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with fire department procurement officers, hydraulic systems maintenance directors, and rescue equipment distributors; and secondary validation through SEC filings of diversified industrial conglomerates, EN 13204 certification databases, and municipal cooperative purchasing records. OEM procurement teams at integrated rescue tool manufacturers and aftermarket service heads at regional distributors provided operational perspective. Bottom-up triangulation across product architecture demand and top-down validation against consolidated municipal framework agreement values anchored volume estimates.
Forecast inputs considered spreading force certification tier, end-use environment emergency versus industrial, technology architecture hydraulic against battery-powered, and regional regulatory cluster EU Machinery Directive against OSHA standards. CAGRs derived from replacement cycle analysis across municipal fleet modernization programs and infrastructure investment trajectories. Analysis window spans from base year through projection horizon. Modeled inputs included urban tunnel authority specifications in Japan and climate adaptation procurement acceleration in flood response applications.
Sensitivities concentrate around battery-powered extrication substitution rates, nickel-chromium alloy steel price volatility, and EN 13204 recertification timeline extensions. Forecasts reflect assumptions regarding municipal procurement consolidation continuity and EU Machinery Directive enforcement consistency. Material shifts in cordless rescue tool performance thresholds or notified body testing protocol changes would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
North America and Europe Snow Blowers Market
Construction Equipment
Italy Construction Equipment Market
Construction Equipment
Tower Crane Market
Construction Equipment
Rotary Hammers Market
Construction Equipment
Crawler Dozers Market
Construction Equipment
CNC Machine Tools Market
Construction Equipment
Overhead Cranes Market
Construction Equipment
Global Cut and Bend Equipment Market
Construction Equipment
Hydraulic Shearing Machine Market
Construction Equipment
India Construction Equipment Rental Market
Construction Equipment
Separation Machinery Market
Construction Equipment
United States Crane Market
Construction Equipment
Portable Rebar Bending Machine Market
Construction Equipment
Bulldozer Rental Market
Construction Equipment
Jackhammer Market
Construction Equipment
Middle-East and Africa Anchors and Grouts Market