
 Entrenching Tool Market | 2026-2036
Entrenching Tool Market Size, Share, and Industry Trends Forecast 2026-2036
Entrenching Tool Market Analysis
Military buyers are redrawing demand patterns across the entrenching tool landscape, pulling procurement volumes away from traditional gardening and consumer segments. The AMES Companies leverages its long-standing government contracts and forged-steel production capacity to anchor its position in defense-grade supply chains. SOG Specialty Knives competes through advanced folding mechanisms and military-spec finishes that meet NSN catalog requirements. Gerber Legendary Blades dominates the premium tactical segment with multi-tool integration that extends utility beyond pure excavation functions.
An entrenching tool is a compact, collapsible digging implement engineered from high-carbon steel or aircraft-grade aluminum alloys, typically featuring a tri-fold design with D-handle or T-handle configurations and hardened blade edges rated for rocky or frozen terrain. The device serves military engineers, emergency responders, and landscaping professionals who require portable earth-moving capability in confined or remote settings. Steel-blade shovels occupy the largest share of product-type revenue due to their durability under combat conditions, while carbon fiber variants represent the fastest-growing material segment as weight reduction becomes critical for dismounted infantry loads. Military operations command the dominant application share, though emergency services procurement is expanding fastest as disaster-response agencies standardize on interoperable equipment.
FDA oversight applies to entrenching tools used in humanitarian medical excavation, while ISO 9001 certification governs manufacturing quality across export-oriented suppliers. The EU AI Act and REACH chemical compliance increasingly shape material selection for European defense contractors seeking cross-border tender eligibility. Stakeholders must monitor evolving NATO standardization agreements and national military procurement cycles to anticipate volume commitments and specification shifts.
Market Dynamics
Carbon fiber composite adoption is compressing traditional steel-blade dominance as NATO procurement specifications harden around dismounted infantry load reduction targets. Military buyers now weight portability metrics above raw durability in tender evaluations.
Growth Catalysts
- Bundeswehr Modernization:Germany's defense procurement office has elevated entrenching tools to priority equipment categories under its EUR 100 billion special fund, creating a reference standard for allied forces.
- REACH Chemical Compliance:European defense contractors seeking cross-border tender eligibility must certify coating and handle materials against ECHA substance restrictions, filtering out non-compliant suppliers.
- Multi-Function Tool Integration:Blade designs incorporating saw teeth, wire cutters, and pry functions are displacing single-purpose excavation implements in military kit configurations.
Market Restraints
- High-Carbon Steel Price Volatility:Blade-grade steel input costs fluctuate with scrap metal and alloy additive markets, compressing margins on forged-steel product lines.
- East Asian Supply Concentration:Carbon fiber pre-preg and composite molding capacity clusters in China and Taiwan, exposing NATO suppliers to geopolitical supply interruption risks.
- NSN Catalog Specification Rigidity:NATO stock number qualification protocols lock designs for multi-year procurement cycles, delaying adoption of incremental material innovations.
Strategic Opportunities
- Disaster Response Agency Standardization:FEMA and analogous European civil protection bodies are consolidating interoperable equipment specifications, opening non-military procurement channels.
- EU Green Deal Procurement Incentives:Defense and public safety tenders increasingly weight lifecycle carbon footprint scoring, favoring domestic European composite manufacturing over imported steel.
- Direct-to-Unit Digital Channels:Military supply depots and unit quartermasters are piloting e-procurement platforms that bypass traditional distributor markups for standardized NSN items.
Industry Challenges
- Composite Technician Scarcity:Carbon fiber layup and autoclave curing expertise concentrates in aerospace and motorsport sectors, forcing tool manufacturers to compete for qualified production staff.
- ISO 9001 Recertification Burden:Three-year audit cycles and documentation requirements consume management bandwidth at mid-tier forging and fabrication shops.
- Legacy Inventory Integration:New collapsible designs must interface with existing carrier systems and load-bearing equipment already fielded across NATO forces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Entrenching Tool Market |
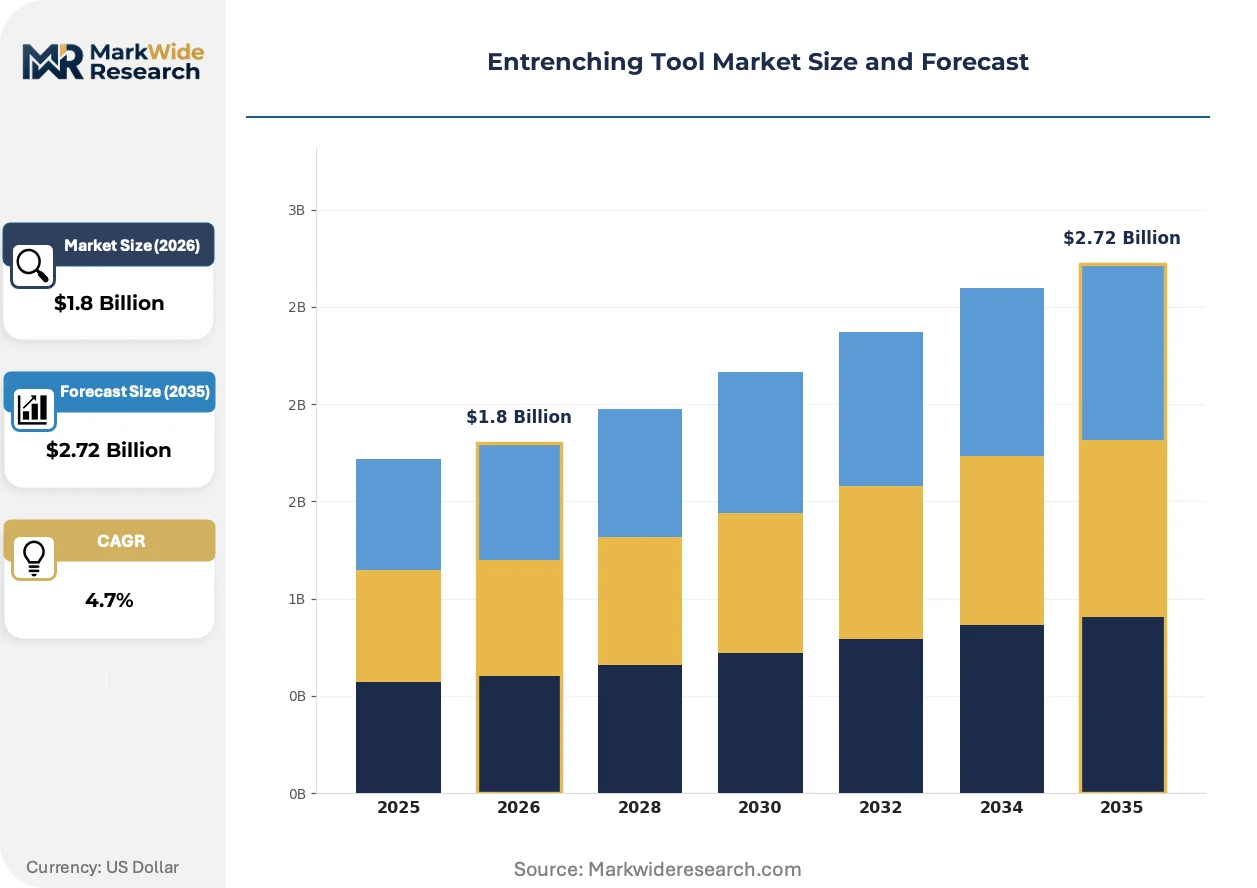
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shovels, Spades, Trowels, Picks End User: Construction Companies, Military, Gardening Enthusiasts, Disaster Relief Material: Steel, Aluminum, Carbon Fiber, Plastic Application: Military Operations, Landscaping, Emergency Services, Agriculture |
| Companies Covered | The AMES Companies, Imperial Schrade Corp, SOG Specialty Knives, Cold Steel, Rhino USA, Coleman's Military Surplus, The Benchmade Knife Company, Gerber Legendary Blades, Columbia River Knife & Tool, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Entrenching Tool Market Emerging Trajectories
Material science advances and procurement digitization are restructuring how entrenching tools are specified, manufactured, and distributed. Three developments are compressing traditional competitive advantages.
Titanium-aluminide hybrid alloys are supplanting conventional high-carbon steel in premium blade segments. Special operations units across NATO member forces are field-testing these materials for alpine and arctic deployment. The resulting weight-stiffness ratios are enabling entirely new handle geometries that fold flatter than tri-fold predecessors.
REACH Annex XVII restrictions on chromium(VI) compounds are forcing coating reformulations across European supply chains. Electroless nickel and physical vapor deposition finishes are displacing hexavalent chrome plating on hardened blades. German and French defense contractors are accelerating qualification timelines for alternative surface treatments to maintain tender eligibility.
Unit-level digital requisitioning is compressing traditional distributor networks. Military quartermasters in the United States and United Kingdom are piloting platform-based purchasing that connects manufacturers directly to end-users. This disintermediation is most visible in special operations commands with delegated procurement authority, where lead times for specialized configurations have collapsed from months to weeks.
Entrenching Tool Market Segmentation
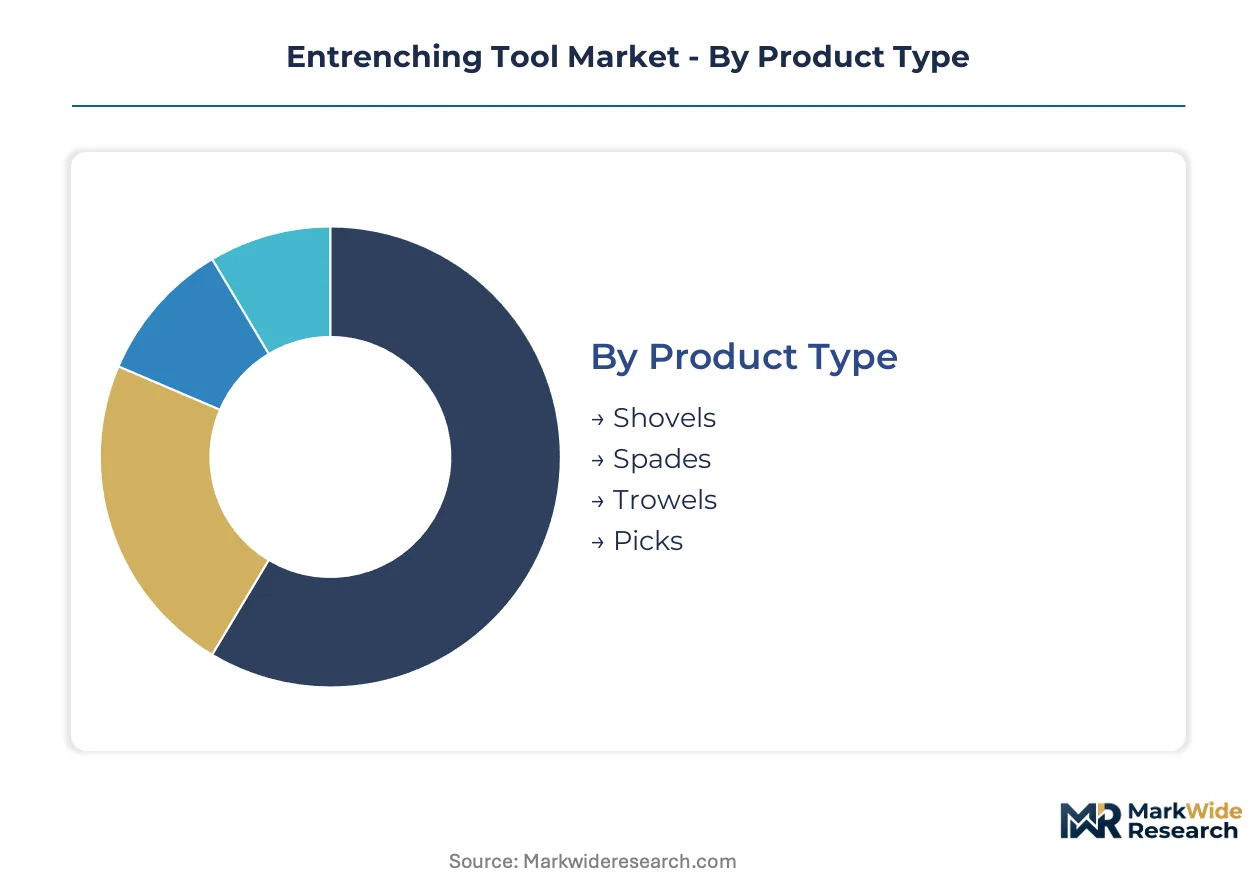
Entrenching tool procurement splits sharply between defense-grade specifications governed by NATO stock number protocols and consumer-grade purchases driven by price elasticity. Understanding these segment boundaries clarifies where carbon fiber innovations displace legacy materials and which regulatory frameworks filter supplier eligibility.
Product Type:
REACH Annex XVII and ISO 9001 certification requirements create divergent compliance burdens across implement categories, with military-spec items facing stricter surface treatment and traceability mandates than consumer equivalents.
- Shovels:Tri-fold and D-handle configurations dominate military kit configurations, with Bundeswehr and allied NATO forces specifying hardened blade edges rated for frozen terrain excavation. German defense procurement offices anchor volume commitments through multi-year framework agreements that prioritize forged-steel durability over weight reduction.
- Spades:Narrower blade profiles serve combat engineering and trench-digging applications where penetration depth matters more than load capacity. Carbon fiber composite variants are gaining traction fastest among special operations units with discretionary procurement authority.
- Trowels:Compact hand tools fill gardening and light landscaping niches with minimal regulatory overlay.
- Picks:Mattock-style implements combine cutting and prying functions for rocky soil conditions in alpine and arctic deployments.
Established volume favors shovels; emerging adoption favors spades.
End User:
Cost tier stratification separates premium defense procurement from price-sensitive consumer channels, with certification grade and order scale driving pricing differentiation.
- Military:NATO standardization agreements and NSN catalog qualification lock designs for multi-year cycles, with German, French, and British defense contractors consolidating around interoperable specifications. REACH compliance and ECHA substance restrictions filter supplier pools for cross-border tender eligibility.
- Construction Companies:Commercial buyers prioritize unit economics and replacement cycle predictability over multi-function integration.
- Gardening Enthusiasts:Retail channels serve hobbyist demand with minimal specification rigidity.
- Disaster Relief:FEMA and European civil protection agencies are consolidating interoperable equipment standards, opening non-military procurement volumes.
Defense contracts concentrate revenue; disaster relief agencies are expanding procurement fastest.
Material:
Application requirements dictate material selection, with load-bearing demands and environmental exposure determining whether durability or weight reduction takes priority.
- Steel:High-carbon and aircraft-grade alloys remain the default for combat conditions where blade hardness cannot compromise. Input cost volatility from scrap metal and alloy additive markets compresses margins on forged product lines.
- Carbon Fiber:Composite layup and autoclave curing expertise drawn from aerospace sectors enables one-third weight reduction without sacrificing stiffness. East Asian pre-preg concentration in China and Taiwan exposes NATO suppliers to geopolitical interruption risks.
- Aluminum:Aircraft-grade alloys occupy a middle tier for applications where corrosion resistance matters more than edge retention.
- Plastic:Polymer handles and glass-filled nylon components reduce cost in consumer and training-grade implements.
Steel dominates current fielded inventory; carbon fiber is climbing the fastest in procurement pipelines.
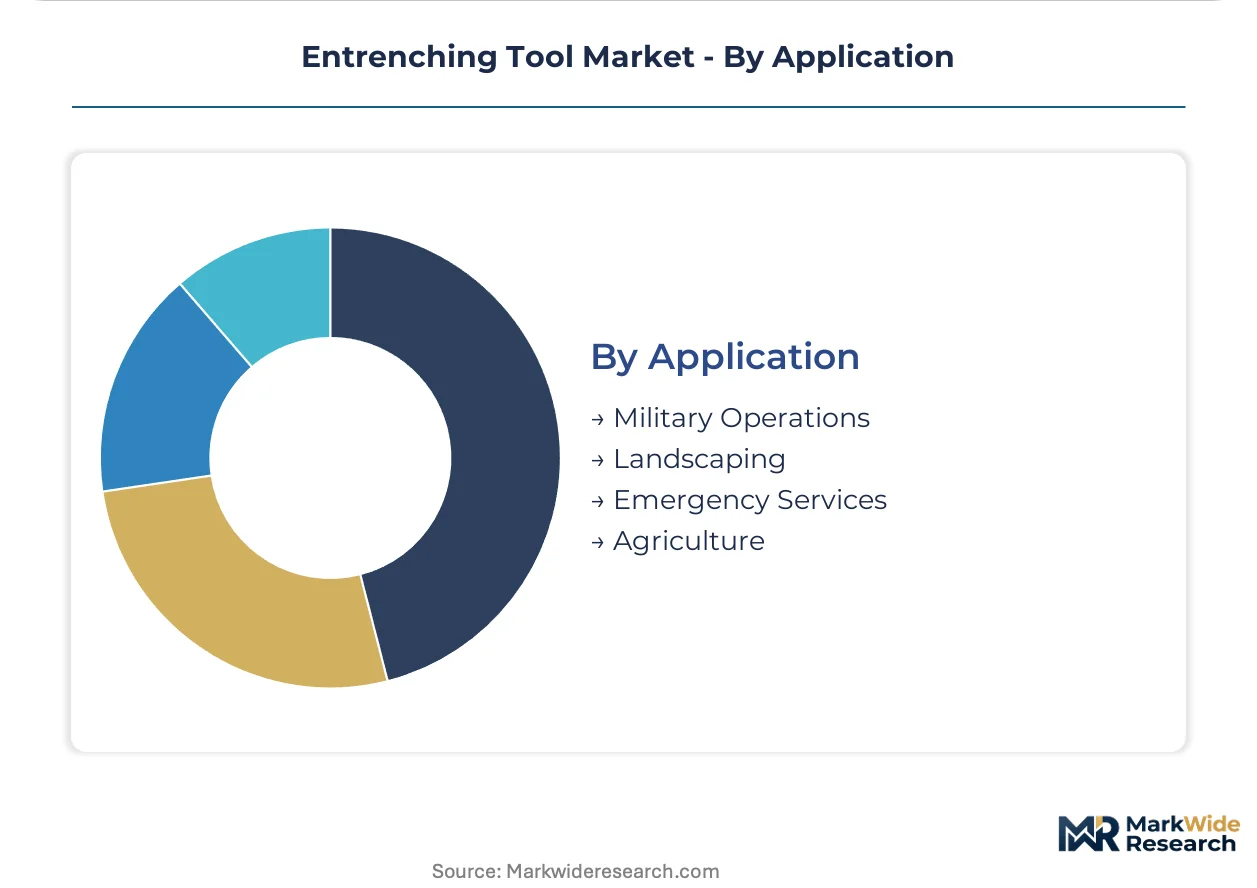
Application:
Customer type and maturity stage segment demand, with established military doctrine contrasting against emerging standardization in civilian emergency response.
- Military Operations:Dismounted infantry load reduction targets are compressing traditional steel-blade dominance in tender evaluations, with portability metrics now weighted above raw durability. German modernization programs under the EUR 100 billion special fund establish reference standards for allied forces.
- Emergency Services:Fire departments and search-and-rescue units are standardizing on collapsible designs compatible with vehicle-mounted equipment lockers.
- Landscaping:Commercial groundskeeping and residential gardening sustain steady replacement demand with minimal specification evolution.
- Agriculture:Farm and vineyard applications favor fixed-handle durability over collapsible convenience.
Defense procurement anchors current revenue; emergency services are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement offices and disaster-response agencies concentrate purchasing authority across NATO member states, with national military modernization programs and civil protection standardization initiatives driving geographic demand variation.
Germany
Bundeswehr procurement under the EUR 100 billion special fund elevates entrenching tools to priority equipment categories, creating reference standards for allied forces. REACH Annex XVII compliance filters supplier eligibility for cross-border tenders. Solingen's blade manufacturing cluster supplies hardened steel components to defense contractors seeking NATO qualification.
United States
FEMA and special operations commands with delegated procurement authority are piloting direct-to-unit digital requisitioning platforms. FDA oversight applies to tools designated for humanitarian medical excavation missions. Tennessee and Oregon host forging and fabrication facilities serving military-spec production lines.
France
Direction Générale de l'Armement consolidates interoperable equipment specifications with German and British counterparts under NATO standardization agreements. ECHA substance restrictions accelerate qualification timelines for alternative blade coatings. Saint-Étienne's metallurgical tradition supports specialized surface treatment development.
United Kingdom
Ministry of Defence procurement cycles lock designs for multi-year frameworks through NSN catalog qualification protocols. UK special operations units are field-testing titanium-aluminide hybrid alloys for alpine deployment. Sheffield's steelworking heritage anchors domestic forging capacity for combat-grade implements.
China
Carbon fiber pre-preg and composite molding capacity clusters expose NATO suppliers to geopolitical supply interruption risks. MIIT industrial policy guides domestic composite manufacturing expansion. Shenzhen and Dongguan concentrate precision molding expertise drawn from consumer electronics supply chains.
Entrenching Tool Market Vendor Landscape
Player mix skews toward defense contractors with forged-steel production capacity and multi-tool specialists with military-spec finishing capabilities. Market structure concentrates around long-standing government relationships and NSN catalog qualification rather than price competition. Two strategic archetypes dominate: legacy forging houses with vertical integration into blade-grade steel supply, and precision engineering firms with aerospace-derived composite expertise. Competitive moves center on capacity expansion in alternative surface treatments and strategic partnerships with disaster-response agencies.
Among North American blade specialists, The AMES Companies, SOG Specialty Knives, and Gerber Legendary Blades occupy positions across the defense-grade supply chain spectrum. The AMES Companies exemplifies the legacy forging house archetype through its government contract heritage. SOG Specialty Knives represents precision engineering capabilities aligned with military-spec catalog requirements. Gerber Legendary Blades anchors the premium tactical segment where multi-function integration extends utility beyond pure excavation functions.
| Leading Market Players |
|---|
| The AMES Companies |
| Imperial Schrade Corp |
| SOG Specialty Knives |
| Cold Steel |
| Rhino USA |
| Coleman's Military Surplus |
| The Benchmade Knife Company |
| Gerber Legendary Blades |
| Columbia River Knife & Tool |
| Others |
Supply Flow & Price Mechanics
ISO 9001 certification gates supplier eligibility while simultaneously stratifying price tiers, forcing mid-tier forging shops to absorb audit costs or exit defense-grade tenders entirely. This dual filtering mechanism concentrates pricing power among qualified incumbents who can spread compliance overhead across NATO framework volumes.
Pricing Analysis
Carbon fiber composite variants command substantial premiums over forged-steel predecessors, with titanium-aluminide hybrids occupying an emerging premium tier above both. Pricing stratifies across premium, standard, and economy tiers driven by certification grade and volume scale in procurement contracts. Cost compression in steel-blade segments intensifies because scrap metal and alloy additive markets fluctuate unpredictably. Military buyers with delegated procurement authority exhibit lowest price sensitivity, while gardening enthusiasts and commercial construction purchasers drive hard unit economics negotiations.
Supply Chain Analysis
China and Taiwan anchor carbon fiber pre-preg and composite molding capacity, while Germany and the United States retain forged-steel blade production clusters. Blade-grade steel draws from scrap metal recyclers and specialty alloy suppliers, with composite layup expertise feeding from aerospace and motorsport sectors. Single-source vulnerability in East Asian pre-preg concentration exposes NATO suppliers to geopolitical interruption risks. Distribution runs through military supply depots and authorized defense contractors for NSN-catalog items, with direct-to-unit digital channels emerging for special operations procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as disaster-response agencies standardize equipment specifications, creating niche entry points alongside entrenched defense contractors. Procurement digitization and material substitution are splitting demand into distinct buyer archetypes with diverging qualification requirements.
For Market Incumbents: Secure NSN catalog qualification lock-in through accelerated alternative surface treatment investments, as REACH Annex XVII restrictions on chromium(VI) compounds threaten existing coating supply chains. Deepen backward integration into blade-grade steel supply to buffer margin pressure from alloy additive volatility. Expand autoclave curing capacity before aerospace competitors capture composite technician talent pools. For New Entrants and Emerging Players: Anchor in European disaster-response agency procurement, where FEMA and civil protection bodies lack entrenched supplier relationships compared to military channels. Target carbon fiber spade configurations for special operations units with discretionary authority outside rigid NSN cycles. Pursue direct digital platform relationships with unit quartermasters piloting e-procurement bypass of traditional distributors. For Investors and Strategic Acquirers: REACH Annex XVII coating reformulation deadlines reshape the acquisition landscape by devaluing hexavalent chrome-dependent forging assets while premiumizing alternative surface treatment capabilities. Mid-term viability through the next decade hinges on positioning for post-steel material transitions in dismounted infantry load reduction programs. Monitor Bundeswehr procurement award announcements as volume commitment inflection indicators for allied NATO force follow-on orders.| Strategic Initiative | Industry Significance |
|---|---|
| Alternative Surface Treatment Qualification | REACH Annex XVII compliance maintains tender eligibility for European defense contractors. |
| Carbon Fiber Layup Capacity Expansion | Autoclave curing expertise from aerospace sectors enables one-third weight reduction targets. |
| Direct-to-Unit Digital Channel Development | Platform-based purchasing collapses lead times for special operations quartermasters. |
| Disaster Response Agency Partnership | FEMA standardization opens non-military procurement volumes outside NSN rigidities. |
| Backward Steel Supply Integration | Captive blade-grade steel production buffers margin compression from alloy volatility. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with defense procurement officers, composite manufacturing engineers, disaster-response agency equipment specialists, and military quartermasters with delegated purchasing authority. Secondary validation drew from NATO standardization agreement documentation, ECHA substance restriction databases, Bundeswehr procurement announcements, and customs trade data on carbon fiber pre-preg movements. Bottom-up volume estimates from product-type and application segments were triangulated against top-down defense budget allocation analysis.
Across the analysis window, projections incorporate segmentation dimensions spanning material composition, end-user category, and regional regulatory cluster. CAGRs were derived from trend extrapolation of procurement cycle timing and material substitution rates. Forecast inputs include Bundeswehr modernization spend trajectories, REACH compliance cost absorption curves, and carbon fiber composite adoption slopes from special operations field testing programs.
Underlying assumptions cover sustained NATO defense spending commitments and stable East Asian pre-preg supply access, with deviation risk concentrated in geopolitical interruption scenarios or abrupt alloy price spikes. Forecasts reflect these documented conditions with acknowledged sensitivity to procurement cycle delays and certification timeline extensions. Recalibration cycles align with material shifts in defense procurement specifications and regulatory enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Industrial Ladder Market
Tools
Mechanical Hand Tools Market
Tools
Handheld Engraving Machine Market
Tools
Metal Cutting Machine Market
Tools
Europe Power Tools Market
Tools
Concrete Saw Market
Tools
Woodworking Router Bits Market
Tools
Drilling Tools Market
Tools
Ultra Hard Material Cutting Machines Market
Tools
Global Table Saws Market
Tools
Woodpecker Tools Market
Tools
L Allen Wrench Market
Tools
Woodworking Circular Saw Blades Market
Tools
Tool Setting Gauges Market
Tools
Ripper Market
Tools
Fiber Laser Cutting Machines Market