
 Fully Automatic Metal Band Saw Machine Market | 2026-2036
Fully Automatic Metal Band Saw Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Fully Automatic Metal Band Saw Machine Market Insights
Germany is reconfiguring European supply dynamics for precision metal cutting equipment through expanded production of CNC-enabled band saw systems. Behringer GmbH leverages its Baden-Württemberg manufacturing base to sustain leadership in dual-column architectures for heavy steel processing. Kasto Maschinenbau GmbH & Co. KG anchors German export competitiveness through integrated material handling systems bundled with sawing lines. Cosen Saws competes aggressively across Asia-Pacific workshop segments with compact horizontal designs optimized for aluminum and brass cutting.
A fully automatic metal band saw machine executes programmed cutting cycles without operator intervention, typically integrating servo-feed mechanisms, blade tensioning systems, and automatic material clamping to achieve repeatability within 0.1 mm across steel, aluminum, and exotic alloys. Horizontal band saw configurations dominate volume deployment in metal fabrication and general manufacturing due to their efficiency in structural steel and bar stock processing. CNC band saw systems command premium positioning in aerospace and automotive end-user segments where complex angle cuts and material traceability requirements justify higher capital investment. Dual-column architectures lead in maintenance and heavy manufacturing use cases demanding stability during large-diameter cutting operations.
OSHA machine guarding standards and EPA metalworking fluid discharge regulations shape US market access requirements for equipment certification and operational compliance. CE marking under the EU Machinery Directive and REACH substance restrictions influence blade material specifications and coolant system designs for European deployment. Stakeholders must monitor evolving ISO 16089 safety standards for automatic sawing equipment and assess how servo-drive efficiency metrics align with emerging factory energy benchmarking protocols.
Market Dynamics
Servo-driven feed mechanisms are displacing hydraulic systems across precision cutting applications, compressing cycle times while satisfying China's MIIT energy efficiency mandates for industrial equipment.
Growth Catalysts
- Electric Vehicle Chassis Production:Automotive OEMs in Germany and Japan are scaling automated cutting capacity to meet precision tolerances for aluminum-intensive EV structural components.
- MIIT Efficiency Mandates:China's Ministry of Industry and Information Technology standards are accelerating replacement of conventional hydraulic band saws with servo-driven alternatives in metalworking clusters.
- Aerospace Material Traceability:CNC-enabled systems with integrated data logging are capturing demand from aerospace suppliers facing AS9100 quality documentation requirements.
Market Restraints
- Blade Material Concentration:High-performance bimetal and carbide-tipped blade supply concentrates among specialty steel producers in Austria and Sweden, creating input cost volatility.
- CE Certification Complexity:EU Machinery Directive compliance timelines and Notified Body backlogs extend equipment approval cycles for non-European manufacturers.
- Plasma Cutting Substitution:Fiber laser and plasma cutting systems are capturing thick-plate applications above 150mm where band saw speed advantages diminish.
Strategic Opportunities
- Southeast Asia Workshop Modernization:Vietnam and Indonesia's metal fabrication sectors remain underpenetrated by fully automatic systems, presenting first-mover positioning for servo-driven horizontal configurations.
- Remanufacturing Services:Blade rewelding and machine retrofit programs align with EU Green Deal circular economy incentives and extend customer lifetime value.
- Digital Twin Integration:Convergence of band saw control systems with predictive maintenance platforms enables outcome-based service models for fleet operators.
Industry Challenges
- Servo System Integration Complexity:Retrofitting legacy hydraulic band saws with servo-feed mechanisms requires controls engineering expertise scarce in regional distributor networks.
- ISO 16089 Compliance Burden:Evolving safety standards for automatic sawing equipment demand redesigned guarding systems and emergency stop architectures, extending R&D cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fully Automatic Metal Band Saw Machine Market |
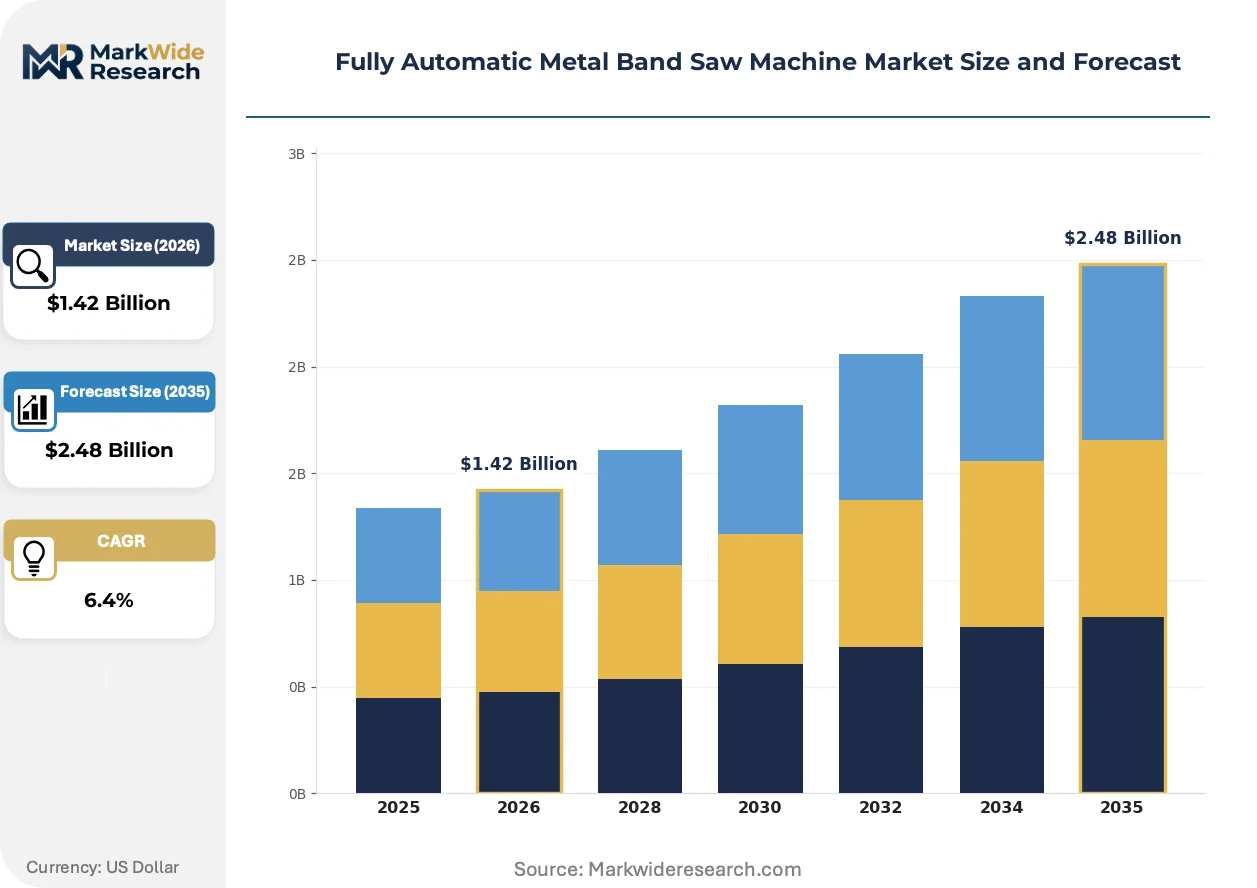
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Band Saw, Horizontal Band Saw, Dual-Column Band Saw, CNC Band Saw Material Cut: Steel, Aluminum, Brass, Plastic Use Case: Metal Fabrication, Workshop, Manufacturing, Maintenance End User: Aerospace, Automotive, Construction, General Industry |
| Companies Covered | Amada Machine Tools Co. Ltd., Behringer GmbH, Cosen Saws, Kasto Maschinenbau GmbH & Co. KG, Everising Machine Co., L.S. Starrett Company Limited, Mega Machine Co. Ltd, DoALL Sawing Products, MEBA Metall-Bandsagemaschinen GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fully Automatic Metal Band Saw Machine Market Trends and Innovations
Control architectures and blade materials are undergoing coordinated transformation, with digitalization and sustainability pressures rewriting equipment specification criteria across buyer segments.
Servo-electric feed systems are migrating from niche aerospace applications toward mainstream structural steel processing. Mid-tier fabricators in the US Midwest are adopting these mechanisms to reduce hydraulic fluid maintenance and align with corporate energy reduction targets. The shift is compressing price premiums between servo and hydraulic configurations while elevating baseline buyer expectations for programmable precision.
REACH substance restrictions are forcing reformulation of metalworking fluids and blade coatings used in European-deployed equipment. Manufacturers are substituting boron-free coolants and eliminating chromium-based surface treatments to maintain CE marking eligibility. German and Italian OEMs are absorbing compliance costs into premium-tier product lines while pushing economy configurations toward Asian markets with less stringent chemical regulations.
After-sales service unbundling is fragmenting traditional equipment-plus-maintenance bundles. Large automotive stamping plants in Detroit and Chicago manufacturing clusters are negotiating blade supply and preventive maintenance through separate contracts, pressuring OEM margins on initial machine sales. Distributors are responding by developing captive blade rewelding capabilities to capture recurring revenue streams.
Fully Automatic Metal Band Saw Machine Market Segmentation
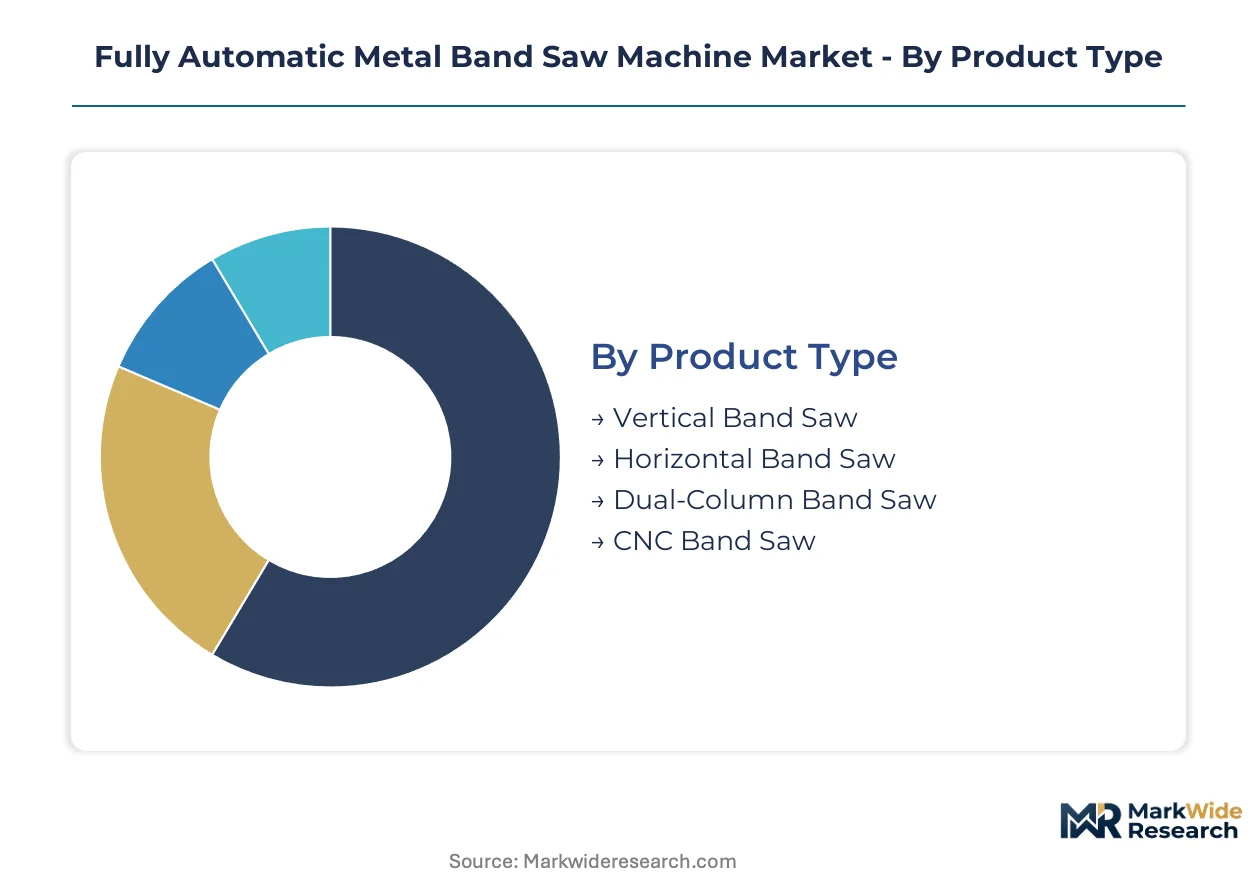
Segmentation in the fully automatic metal band saw machine market reveals how equipment specifications align with distinct operational requirements across material types and end-use environments. Buyers prioritize different performance attributes based on whether they process structural steel in high-volume fabrication or precision alloys in aerospace quality systems.
Product Type:
Cost tier differentiation across product architectures determines capital allocation patterns and aftermarket service attach rates for metal cutting operations.
- Horizontal Band Saw:These machines position the blade horizontally for gravity-assisted cutting of bar stock and structural sections. Metal fabrication shops in the US Midwest concentrate procurement here for efficiency in steel processing. The configuration dominates volume deployment due to lower capital barriers and reduced operator training requirements.
- CNC Band Saw:Computer numerical control enables programmable angle cuts, automatic material indexing, and integrated data logging for traceability. Aerospace suppliers facing AS9100 documentation mandates drive specification intensity here. The premium positioning reflects precision tolerances and connectivity requirements that justify higher initial investment.
- Vertical Band Saw:Blade orientation suits contour cutting and intricate shapes in smaller workpieces. Job shops handling mixed material portfolios specify these for aluminum and brass applications.
- Dual-Column Band Saw:Twin vertical columns provide frame rigidity for large-diameter cutting operations. Heavy manufacturing and maintenance facilities deploy these for stability under high blade tension.
Horizontal configurations hold installed capacity. CNC systems are rotating up the share rankings as traceability requirements intensify across regulated industries.
Material Cut:
Application-specific cutting dynamics shape blade selection, coolant system design, and feed mechanism calibration for different workpiece compositions.
- Steel:Carbon and alloy steel cutting demands bimetal blades with variable tooth pitch to manage chip load across solid sections. Automotive OEMs in Germany scale automated capacity here for EV chassis components requiring precision tolerances. The segment anchors volume demand due to structural steel prevalence in construction and heavy fabrication.
- Aluminum:Softer material properties permit higher cutting speeds with specialized tooth geometries that prevent chip welding. Electric vehicle production lines in Japan concentrate procurement for lightweight structural components. The shift toward aluminum-intensive vehicle platforms accelerates specification of high-speed servo-feed systems.
- Brass:Copper-zinc alloys require controlled feed rates to prevent work hardening and surface tearing. Plumbing fixture manufacturers and decorative metalwork shops specify dedicated cutting parameters.
- Plastic:Non-metallic cutting employs modified blade speeds and tooth configurations to manage melting and chip evacuation. Industrial packaging and composite material processors represent niche demand.
Steel retains the largest installed base. Aluminum is climbing the fastest as automotive lightweighting mandates propagate through supply chains.
Use Case:
Customer type segmentation distinguishes between production-scale operations and intermittent cutting environments with differing utilization patterns and service requirements.
- Metal Fabrication:Dedicated cutting departments in structural steel processors run multiple shifts with high equipment utilization. Chicago and Detroit manufacturing clusters concentrate demand for horizontal configurations with automatic material handling. The segment drives volume for mid-tier servo-driven systems that balance throughput against capital constraints.
- Manufacturing:OEM in-house cutting operations integrate band saws within production lines for raw material preparation. Tier-1 automotive suppliers specify CNC-enabled systems with MES connectivity for production tracking.
- Workshop:Small-batch and prototype cutting environments prioritize flexibility over automation. Independent job shops across Southeast Asia represent underpenetrated opportunity for compact horizontal designs.
- Maintenance:Repair and overhaul facilities require occasional cutting of large-diameter shafts and replacement components. Equipment rental and remanufacturing services support this intermittent usage pattern.
Metal fabrication commands the deepest installed base. Manufacturing is gaining share fastest as OEMs internalize precision cutting capacity.
End User:
Volume and margin distribution across end-use industries reflects regulatory intensity, material sophistication, and supply chain consolidation patterns.
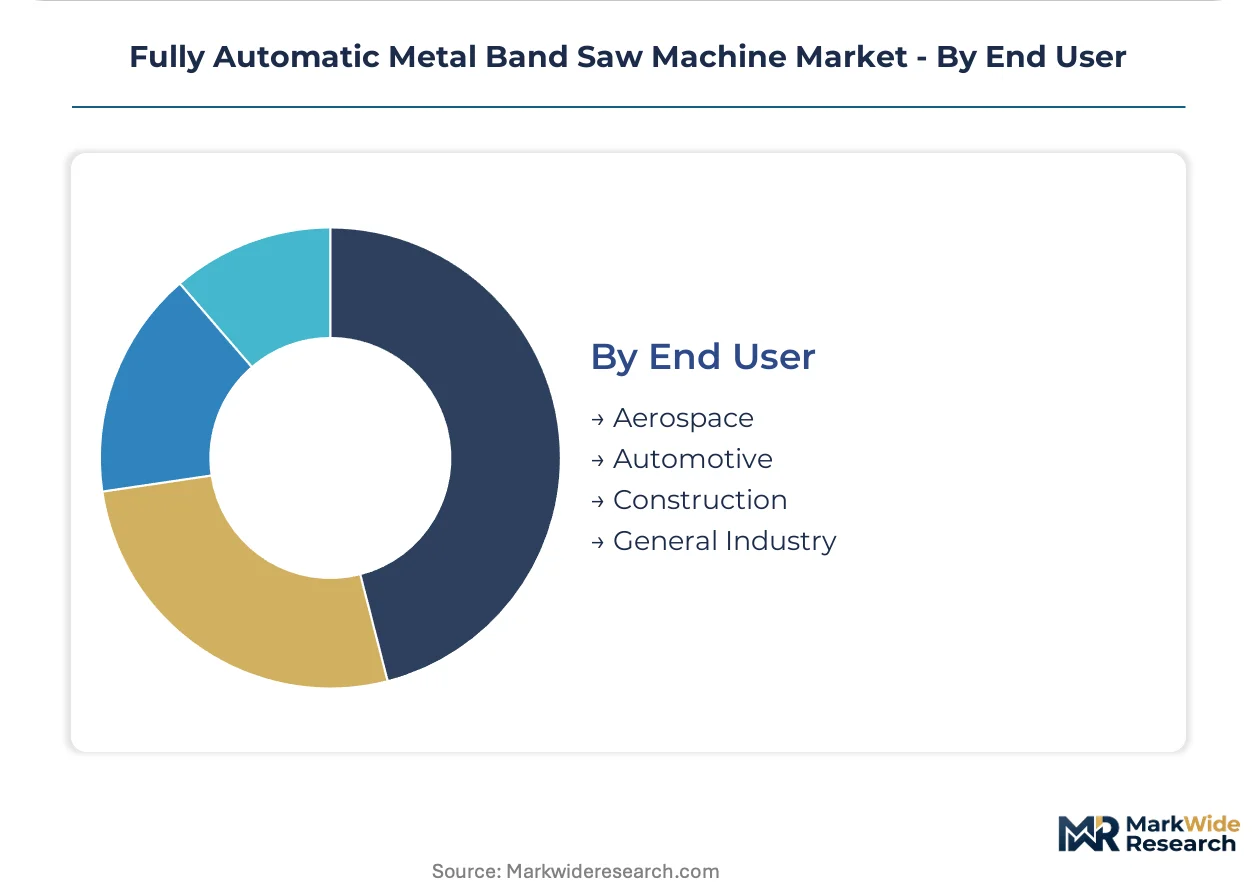
- Automotive:OEM stamping plants and Tier-1 suppliers specify high-throughput systems for chassis, drivetrain, and structural component production. Germany and Japan anchor demand as electric vehicle platforms require precision cutting of aluminum-intensive designs. The segment drives technology migration toward servo-electric feeds and integrated quality verification.
- Aerospace:AS9100 quality system mandates require material traceability, angle precision, and documented cutting parameters. Superalloy and titanium processing demands specialized blade materials and reduced cutting speeds that elevate equipment specification intensity.
- Construction:Structural steel processors and rebar fabrication facilities prioritize durability and low operating cost over precision features. Standard horizontal configurations dominate this price-sensitive segment.
- General Industry:Diverse manufacturing operations with mixed material requirements represent fragmented demand. Maintenance departments and small fabricators populate this catch-all category.
Automotive holds the steepest expansion trajectory. Aerospace sustains premium pricing power through regulatory compliance requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA machine guarding standards and EPA metalworking fluid discharge regulations anchor US market access requirements for equipment certification and operational compliance. Demand concentrates in industrial corridors where automotive and aerospace OEMs drive precision cutting specifications.
United States
Automotive OEM stamping plants in Detroit and Chicago manufacturing clusters scale automated cutting capacity for electric vehicle chassis production. OSHA and EPA regulations shape equipment certification and coolant system designs for operational compliance. The US Midwest industrial corridor sustains volume demand for horizontal band saw configurations in metal fabrication operations.
Germany
Automotive OEMs expand CNC-enabled band saw systems to meet precision tolerances for aluminum-intensive EV structural components. CE marking under the EU Machinery Directive and REACH substance restrictions influence blade material specifications and coolant system designs. Baden-Württemberg manufacturing bases anchor European supply dynamics for dual-column architectures in heavy steel processing.
China
MIIT energy efficiency mandates for metalworking equipment accelerate replacement of conventional hydraulic band saws with servo-driven alternatives. GB standards and dual carbon goals shape factory energy benchmarking protocols for industrial equipment procurement. Metalworking clusters concentrate demand in coastal provinces where state-owned automotive enterprises drive precision cutting specifications.
Japan
Automotive OEMs scale automated cutting capacity for electric vehicle chassis components requiring precision tolerances. METI industrial efficiency programs and JIS standards influence equipment specification criteria for factory energy reduction targets. Manufacturing bases concentrate procurement for high-throughput systems with integrated quality verification capabilities.
Vietnam
Metal fabrication sectors remain underpenetrated by fully automatic systems, presenting first-mover positioning for servo-driven horizontal configurations. The country's national industrial development programs incentivize workshop modernization in manufacturing zones. Ho Chi Minh City and Hanoi industrial corridors concentrate emerging demand as foreign direct investment expands automotive supplier networks.
Fully Automatic Metal Band Saw Machine Market Competitive Landscape
Capability concentration sits with German engineering specialists; scale advantage sits with Asia-Pacific volume fabricators. The vendor base organizes around three strategic archetypes: European precision-engineering houses with integrated material handling systems, Taiwanese and Chinese manufacturers competing on compact horizontal designs for workshop segments, and Japanese tool conglomerates with diversified metalworking portfolios. Competitive moves center on geographic expansion into Southeast Asian growth markets and technology licensing partnerships for servo-drive integration.
Among German-based precision engineering houses, Behringer GmbH and Kasto Maschinenbau GmbH & Co. KG exemplify the integrated-systems archetype, while Cosen Saws occupies a position representing Asia-Pacific competitiveness in compact horizontal configurations optimized for aluminum and brass cutting.
| Leading Market Players |
|---|
| Amada Machine Tools Co. Ltd. |
| Behringer GmbH |
| Cosen Saws |
| Kasto Maschinenbau GmbH & Co. KG |
| Everising Machine Co. |
| L.S. Starrett Company Limited |
| Mega Machine Co. Ltd |
| DoALL Sawing Products |
| MEBA Metall-Bandsagemaschinen GmbH |
| Others |
Pricing and Supply Chain Analysis
The Shanghai-Rotterdam maritime corridor's freight volatility compresses margins for European-bound servo-drive components while amplifying price spreads between German-engineered systems and Asian alternatives. This logistics dynamic concentrates pricing power with Austrian and Swedish specialty steel suppliers for bimetal blades, forcing OEMs to pass input volatility downstream through tiered equipment configurations.
Pricing Analysis
Price spreads between German-engineered CNC systems and Taiwanese compact horizontal units exceed three-to-one across comparable cutting capacities. Three-tier pricing structure across premium, standard, and economy levels separates CE-certified servo-drive configurations from hydraulic alternatives and basic workshop models. Cost compression in the mid-tier segment is intensifying because automotive OEMs unbundle after-sales service from initial equipment purchases. Workshop operators in Southeast Asia exhibit the highest price sensitivity, while aerospace suppliers facing AS9100 mandates demonstrate minimal elasticity for traceability-enabled systems.
Supply Chain Analysis
Bimetal and carbide-tipped blade feedstock draws from specialty steel producers concentrated in Austria, Sweden, and Japan. Servo motors, linear drives, and CNC control modules rest on supply networks anchored in Germany, Japan, and Taiwan. Single-source vulnerability concentrates in high-performance blade substrates subject to REACH substance restrictions. Distribution runs through manufacturer-direct channels for large automotive OEMs and tiered distributor networks serving fabrication shops and maintenance facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory certification entrenchment creates durable switching costs for installed equipment bases. OEMs and fabricators face high replacement barriers once integrated into production line quality systems.
For Market Incumbents: Harden competitive position by deepening captive blade rewelding capabilities and expanding remanufacturing service footprints to capture recurring revenue streams. Fiber laser substitution threats in thick-plate applications demand accelerated servo-drive cost reduction programs. Backward integration into blade substrate supply through offtake agreements with Austrian specialty steel producers secures input cost stability. For New Entrants and Emerging Players: Vietnam's metal fabrication sector offers first-mover positioning for compact servo-driven horizontal configurations targeting workshop modernization programs. Indonesia's automotive supplier corridors present parallel entry vectors through equipment-leasing partnerships with state industrial development agencies. A go-to-market strategy bundling blade supply contracts with equipment financing addresses capital-constrained fabricator price sensitivity. For Investors and Strategic Acquirers: Regional distributor networks with captive service capabilities represent the priority acquisition archetype for exposure to aftermarket revenue streams. Long-term viability centers on equipment-software convergence for predictive maintenance platforms. The inflection signal to watch is adoption velocity of digital twin integration among Tier-1 automotive stamping plants.| Strategic Initiative | Industry Significance |
|---|---|
| Servo-Drive Retrofit Program | Converts installed hydraulic base to MIIT-compliant efficiency standards in Chinese metalworking clusters. |
| Blade Rewelding Service Expansion | Captures recurring revenue from EU Green Deal circular economy incentives for remanufacturing. |
| Digital Twin Platform Integration | Enables outcome-based service contracts with Detroit and Chicago automotive fleet operators. |
| Southeast Asia Distributor Acquisition | Secures channel control in Vietnam and Indonesia workshop modernization growth corridors. |
| REACH-Compliant Coolant Reformulation | Maintains CE marking eligibility for European deployment amid substance restriction tightening. |
Research Methodology
Cross-validation between executive interviews at German precision engineering houses and customs trade data anchors the qualitative findings on supply concentration dynamics. Primary fieldwork with maintenance directors at US Midwest fabrication clusters, plant engineers at Japanese automotive OEMs, aftermarket service heads at Taiwanese distributors, and OEM procurement teams at Tier-1 suppliers generated operational demand signals. Secondary validation drew from SEC equipment manufacturer filings, EU Machinery Directive certification databases, MIIT energy efficiency standard disclosures, and Japanese industrial production surveys. Bottom-up equipment shipment analysis and top-down metalworking capital expenditure tracking triangulate market sizing.
Calibration against historical servo-drive adoption curves and automotive lightweighting investment cycles shapes the projection framework across the analysis window. Segmentation dimensions modeled include product architecture, material cut specification, use case intensity, and end-user industry regulatory exposure. CAGRs derive from regression analysis of equipment replacement cycles against factory automation indices and energy efficiency mandate compliance timelines. Forecast inputs incorporate MIIT enforcement trajectory for hydraulic equipment phase-out and AS9100 revision impacts on traceability system specifications.
Practitioners should monitor blade material cost volatility, CE certification backlog durations, and fiber laser substitution rates in thick-plate applications for early signals of forecast revision. Cross-checking against customs data for servo motor import volumes into Chinese coastal provinces is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Electric and Hybrid Construction Equipment Market
Construction Equipment
Smelting Furnace Equipment Market
Construction Equipment
Global Pile Driving Equipment Market
Construction Equipment
Europe Construction Equipment Market
Construction Equipment
Vietnam Crane Market
Construction Equipment
Middle-East and Africa Anchors and Grouts Market
Construction Equipment
Cement Consistometer Market
Construction Equipment
CNC Machine Tools Market
Construction Equipment
Skid Steer Loader Market
Construction Equipment
GCC Crane Market
Construction Equipment
Europe Construction Machinery Rental Market
Construction Equipment
PU Casting Machine Market
Construction Equipment
Concrete Testers Market
Construction Equipment
High Pressure Washer Market
Construction Equipment
Global Hydraulic Hammer Market
Construction Equipment
North America and Europe Snow Blowers Market