
 Surface Planer Market | 2026-2036
Surface Planer Market Size, Share, and Industry Trends Forecast 2026-2036
Surface Planer Market Analytics
Specialized industrial distributors is reconfiguring how surface planers reach mid-sized furniture workshops in North America and Southeast Asia. Makita leverages its battery-platform ecosystem to capture cordless job-site demand, while DeWalt anchors professional-grade stationary lines through big-box retail partnerships. JET competes in the premium hobbyist segment with cast-iron bed designs that differentiate on vibration dampening.
A surface planer is a woodworking machine that removes material from a board's face to create a flat, uniform surface through a rotating cutter head operating at speeds typically between 8,000 and 16,000 RPM. Stationary planers dominate commercial shops where 15-inch or wider capacity supports high-volume dimensioning, while portable electric units represent the fastest-growing technology segment as battery chemistry improvements extend runtime for mobile contractors. Professional woodworkers command the largest end-user margin pool due to replacement cycles tied to cutter-head wear and dust-collection integration requirements.
The Occupational Safety and Health Administration enforces machine-guarding standards that shape planer design in the United States, while the EU Machinery Directive mandates emergency-stop integration and noise-emission labeling for CE-marked equipment sold across Europe. China's Standardization Administration publishes GB standards for woodworking machinery safety that govern domestic manufacturing and export certification. Stakeholders must monitor how evolving silica-exposure limits and dust-collection mandates in multiple jurisdictions alter product specification sheets and installation requirements.
Market Dynamics
Automated milling capacity expansion in Vietnamese furniture manufacturing is compressing replacement cycles for precision surfacing equipment while forcing distributors to reconfigure service networks around just-in-time cutter-head logistics.
Growth Catalysts
- CE marking mandates:The EU Machinery Directive's tightened safety specifications are accelerating equipment turnover in European woodshops as legacy machines face compliance-driven obsolescence.
- Guangdong cabinetry clusters:Export-oriented furniture manufacturers in China's Guangdong province are upgrading precision surfacing tools to meet international dimensional tolerance requirements.
- Battery chemistry improvements:Lithium-ion energy density gains are extending runtime for cordless portable planers, opening mobile contractor segments previously captive to corded stationary units.
Market Restraints
- Cast-iron supply concentration:Vibration-dampening bed production depends on foundry capacity concentrated in specific industrial zones, creating input bottlenecks during demand surges.
- Silica-exposure compliance friction:OSHA's evolving dust-collection mandates are extending product development timelines and increasing certification costs for manufacturers targeting the United States.
- CNC machining substitution:Multi-axis milling centers are absorbing dimensioning tasks in high-volume commercial shops, compressing addressable market for standalone surface planers above 20-inch capacity.
Strategic Opportunities
- Indonesian furniture export zones:Underpenetrated automated surfacing capacity in Java-based manufacturing clusters presents first-mover advantage for precision equipment vendors.
- Dual carbon goals alignment:China's national emissions targets are creating regulatory tailwinds for energy-efficient variable-speed drive systems in woodworking machinery.
- Direct-to-workshop digital channels:Specialized industrial distributors are piloting configuration tools that bypass traditional dealer networks for mid-sized furniture workshops.
Industry Challenges
- Cutter-head alignment technician scarcity:Precision spiral cutter installation and calibration requires specialized skills that vocational programs are not producing at replacement rates.
- Legacy three-phase electrical infrastructure:Commercial shops in older industrial zones face capex barriers when upgrading to high-torque stationary planers requiring dedicated power drops.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surface Planer Market |
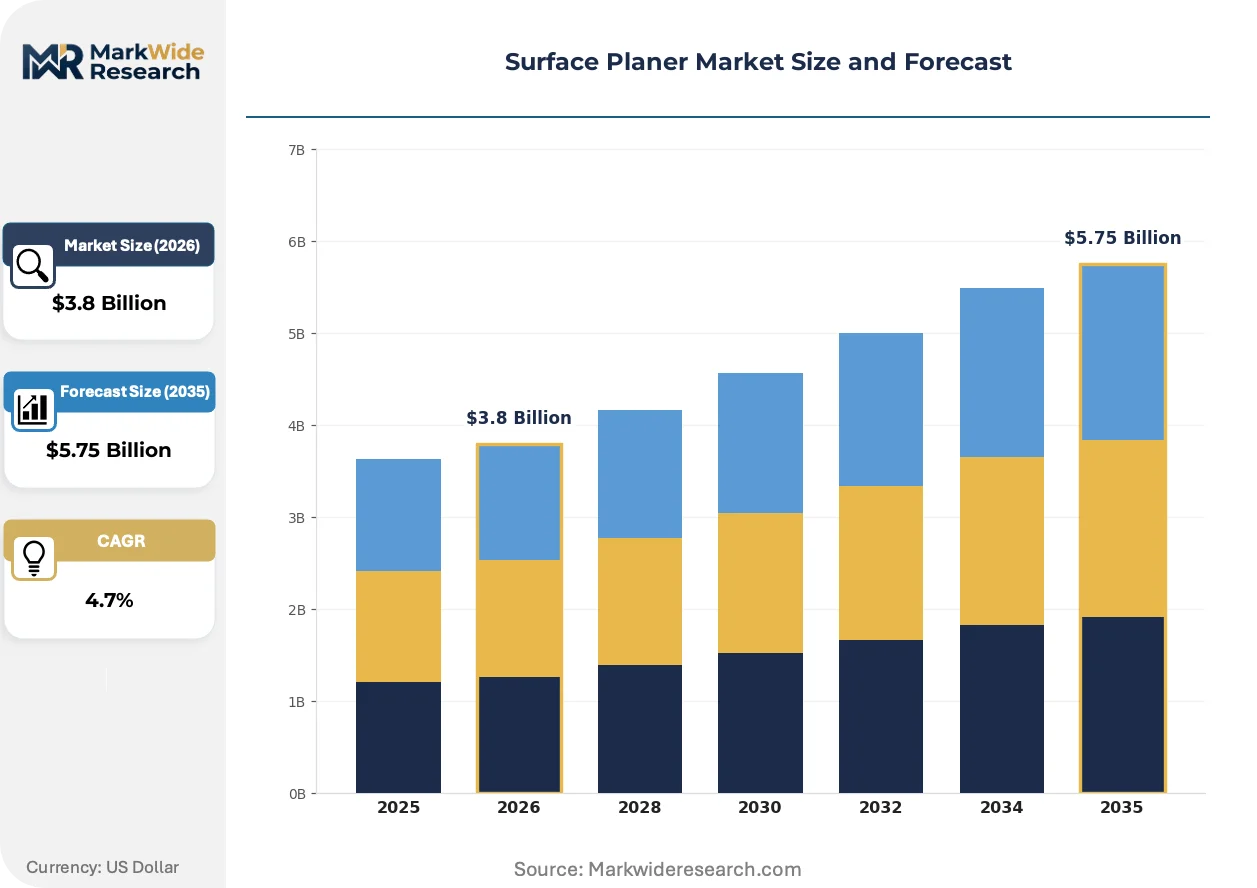
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Planers, Stationary Planers, Electric Planers, Handheld Planers End User: Professional Woodworkers, DIY Enthusiasts, Construction Companies, Furniture Manufacturers Technology: Electric, Hydraulic, Pneumatic, Manual Application: Woodworking, Construction, Renovation, Furniture Making |
| Companies Covered | DeWalt, Makita, Delta, Bosch, RIDGID, JET, Harbor Freight Tools, Baileigh Industrial, Woodmaster, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surface Planer Market Evolving Landscape
Woodshop equipment is converging around intelligent material-sensing systems and modular dust-collection integration, reshaping how surface planers are specified, installed, and maintained across professional and hobbyist segments.
Helical cutter-head technology is hybridizing traditional straight-knife dimensioning with shear-angle slicing action that reduces tear-out on figured grain. High-end furniture manufacturers in North America are specifying spiral cutter retrofits for existing cast-iron beds at accelerating pace. This hybridizing of old machine architecture with new cutting geometry is extending asset lifecycles while compressing aftermarket parts revenue for conventional knife sets.
REACH chemical restrictions on chromium plating processes are forcing European manufacturers to migrate toward ceramic-coated or plasma-nitrated bed surfaces. The regulation is elevating production costs for premium stationary units while creating competitive disadvantage for smaller fabricators lacking surface-treatment alternatives. German and Italian equipment producers are responding fastest, leveraging captive metallurgy expertise to maintain CE-marked product flow.
Certification-driven preference shifts are concentrating procurement authority in safety-compliance officers rather than shop-floor managers. Large commercial furniture operations are unbundling equipment specification from maintenance contracts, creating discrete vendor relationships for hardware, dust-collection integration, and ongoing cutter-head service. This pattern is most visible in export-oriented manufacturing clusters where buyer liability exposure drives documentation requirements beyond baseline regulatory minimums.
Surface Planer Market Segmentation
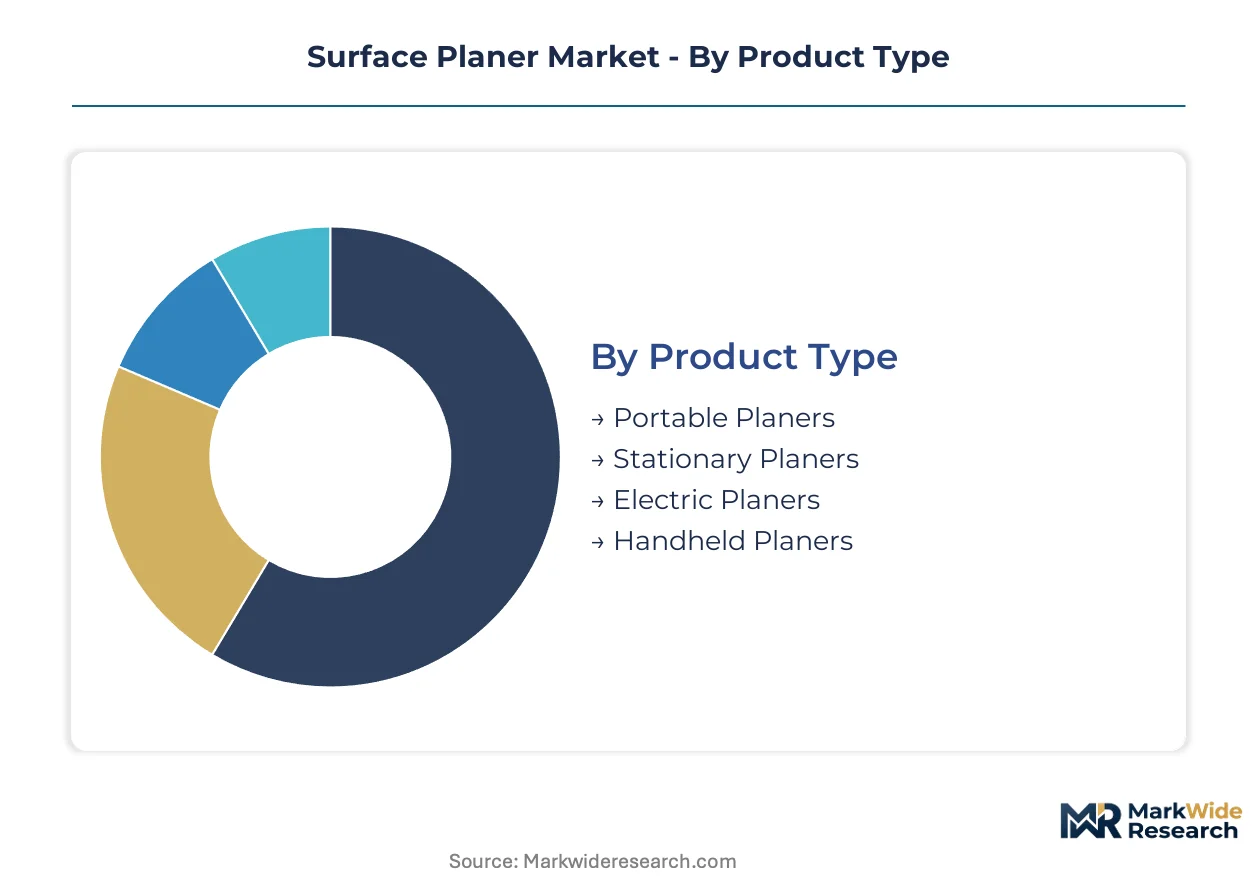
Surface planer segmentation reveals divergent service intensity across product architectures. Cutter-head replacement cycles, dust-collection integration complexity, and calibration requirements create distinct aftermarket revenue profiles that shape vendor strategy.
Product Type:
After-sales service intensity varies dramatically by product architecture, with stationary units demanding ongoing cutter-head alignment contracts while portable units concentrate warranty claims around battery-platform degradation.
- Stationary Planers:Heavy cast-iron bed designs with 15-inch or wider capacity dominate commercial furniture shops in Vietnam and Guangdong province. These units require quarterly spiral cutter calibration and dedicated dust-collection infrastructure, generating recurring service revenue that anchors distributor relationships. Professional woodworkers command the largest margin pool here due to replacement cycles tied to cutter-head wear.
- Portable Planers:Cordless lithium-ion units are expanding most quickly among mobile contractors as battery chemistry improvements extend runtime. Makita's battery-platform ecosystem captures this demand in North American job-site segments where mobility trumps surfacing width.
- Electric Planers:Corded handheld units serve mid-sized furniture workshops with moderate volume requirements and limited three-phase electrical infrastructure.
- Handheld Planers:Manual and basic electric units address hobbyist price sensitivity in premium segments where JET competes on cast-iron vibration dampening.
Stationary planers hold the largest share; momentum sits with portable units.
End User:
Customer type determines specification authority, with safety-compliance officers increasingly unbundling procurement from shop-floor managers in export-oriented manufacturing clusters.
- Professional Woodworkers:Commercial shops prioritize helical cutter-head retrofits for existing cast-iron beds, extending asset lifecycles while compressing conventional knife-set aftermarket revenue. OSHA machine-guarding standards and EU Machinery Directive CE marking requirements drive equipment turnover in this segment.
- Furniture Manufacturers:Automated milling capacity expansion in Vietnamese and Guangdong cabinetry clusters compresses replacement cycles for precision surfacing equipment. Export-oriented manufacturers upgrade tools to meet international dimensional tolerance requirements.
- Construction Companies:Mobile contractors favor cordless portable units for on-site dimensioning where power access is constrained.
- DIY Enthusiasts:Hobbyist demand concentrates in premium segments through big-box retail partnerships, with cast-iron bed designs differentiating on vibration dampening.
Professional woodworkers anchor revenue concentration; furniture manufacturers are climbing the fastest.
Technology:
Power source selection constrains installation requirements and determines regulatory compliance pathways across jurisdictions.
- Electric:Dominates both stationary and portable architectures, with variable-speed drive systems gaining share under China's dual carbon goals alignment.
- Hydraulic:High-torque industrial applications in legacy commercial shops with established three-phase infrastructure.
- Pneumatic:Niche job-site deployment where compressed air systems are pre-installed.
- Manual:Minimal share confined to hobbyist entry points with lowest service intensity.
Electric technology commands installed base; hydraulic faces substitution pressure from CNC machining centers.
Application:
Use case dictates dimensional tolerance requirements and dust-collection mandate exposure across regulatory jurisdictions.
- Woodworking:Encompasses both commercial dimensioning and fine furniture production, with helical cutter technology reducing tear-out on figured grain for high-end North American manufacturers.
- Furniture Making:Export-oriented clusters in Guangdong province drive precision surfacing tool upgrades to meet international buyer specifications.
- Construction:Mobile rough-dimensioning tasks favoring runtime-extended cordless units.
- Renovation:Mixed demand spanning portable job-site use and workshop-based restoration work.
Woodworking holds the largest share; furniture making shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Italian equipment producers commanding premium positioning for CE-marked stationary units, while Vietnamese and Chinese fabricators compete on throughput economics for export-oriented cabinetry clusters.
United States
Professional woodworkers and commercial furniture shops drive helical cutter-head retrofits for existing cast-iron beds. OSHA machine-guarding standards and evolving silica-exposure limits accelerate equipment turnover in legacy woodshops. Industrial distributors in the Midwest and Southeast reconfigure service networks around just-in-time cutter-head logistics for mid-sized workshops.
Germany
EU Machinery Directive mandates and REACH chemical restrictions on chromium plating elevate production costs for premium stationary units. German equipment producers leverage captive metallurgy expertise to maintain CE-marked product flow through ceramic-coated bed surface alternatives. Certification-driven procurement shifts concentrate authority in safety-compliance officers rather than shop-floor managers.
China
Export-oriented cabinetry clusters in Guangdong province upgrade precision surfacing tools to meet international dimensional tolerance requirements. Standardization Administration GB standards govern domestic manufacturing and export certification pathways. Dual carbon goals alignment creates regulatory tailwinds for energy-efficient variable-speed drive systems in woodworking machinery.
Vietnam
Automated milling capacity expansion in furniture manufacturing compresses replacement cycles for precision surfacing equipment. Furniture manufacturers demand dedicated dust-collection infrastructure and quarterly spiral cutter calibration services. Distributors face pressure to reconfigure service networks around compressed lead times for cutter-head logistics.
Italy
High-end furniture manufacturers specify spiral cutter retrofits for existing cast-iron beds at accelerating pace. Italian equipment producers respond fastest to REACH restrictions through plasma-nitrated bed surface alternatives. Premium hobbyist segments concentrate demand through specialized industrial distributors piloting direct-to-workshop digital channels.
Surface Planer Market Competitive Landscape
Battery-platform specialists and cast-iron stationary fabricators split the market across mobility-driven and precision-driven vectors. Makita anchors the cordless portable segment through battery-ecosystem lock-in, while JET and DeWalt compete for professional-grade stationary and premium hobbyist positioning. The vendor base organizes around three strategic archetypes: power-tool platform owners leveraging battery interchangeability, cast-iron bed specialists differentiating on vibration dampening, and industrial distributors unbundling equipment specification from maintenance contracts. Dominant competitive moves include big-box retail partnerships for professional-grade lines and direct-to-workshop digital channels bypassing traditional dealer networks.
Among Japanese power-tool platform owners, Makita represents the battery-ecosystem archetype. DeWalt exemplifies the professional-grade stationary positioning through retail partnership structures. JET occupies a position within the premium hobbyist tier where cast-iron vibration-dampening designs anchor product differentiation. These three companies illustrate how vendor strategy diverges across mobility requirements, price positioning, and service intensity vectors.
| Leading Market Players |
|---|
| DeWalt |
| Makita |
| Delta |
| Bosch |
| RIDGID |
| JET |
| Harbor Freight Tools |
| Baileigh Industrial |
| Woodmaster |
| Others |
Value Network & Pricing Analysis
Foundry capacity for vibration-dampening cast-iron beds clusters in Germany, Italy, and select Chinese industrial zones, concentrating margin capture with OEMs that control captive metallurgy expertise and ceramic-coated surface treatment alternatives. This upstream concentration forces mid-tier fabricators into price-taking positions while premium CE-marked producers maintain configured-to-order premiums through spiral cutter-head calibration bundling.
Pricing Analysis
Configured-to-order stationary planers with helical cutter retrofits and dust-collection integration command 40-60% premiums over standard portable units, with price differentiation anchored in CE certification tier and after-sales service intensity. Three-tier pricing structure separates premium cast-iron beds with ceramic coatings from standard cast-iron configurations and economy portable lithium-ion platforms. Cost compression in the economy portable tier intensifies as battery-platform commoditization erodes Makita's ecosystem lock-in. Furniture manufacturers in export-oriented clusters show least price sensitivity due to buyer liability exposure, while DIY enthusiasts in North America exhibit highest elasticity.
Supply Chain Analysis
Export-control friction around precision machining equipment and dual-use manufacturing technology restricts flows of high-torque spindle assemblies from German and Japanese suppliers into certain jurisdictions. Geographic supply concentration centers on China for lithium-ion battery cells and motor assemblies, Germany for cast-iron foundry components and precision bearings, and Italy for helical cutter-head fabrication. Raw material dependencies include high-grade pig iron for vibration-dampening beds, rare-earth magnets for variable-speed drives, and cobalt-nickel battery chemistry for cordless platforms. Single-source vulnerability in ceramic coating surface treatments creates bottlenecks during REACH compliance transitions. Distribution runs through specialized industrial distributors reconfiguring around direct-to-workshop digital channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The surface planer market functions as a service-attach play where cutter-head replacement cycles and quarterly calibration contracts expand faster than hardware shipments. Recurring revenue from spiral cutter logistics and dust-collection integration outpaces unit growth in Vietnamese and Guangdong manufacturing clusters.
For Market Incumbents: Build captive metallurgy expertise as a moat against REACH-driven surface treatment disruptions. German and Italian OEMs should deepen backward integration into plasma-nitrided bed production to maintain CE-marked product flow. Anchor distributor relationships through just-in-time cutter-head logistics contracts that compress lead times for mid-sized furniture workshops. Defend against cordless platform commoditization by bundling battery-ecosystem lock-in with professional-grade stationary cross-selling. For New Entrants and Emerging Players: Build out automated surfacing capacity in underpenetrated Indonesian furniture export zones before incumbent service networks solidify. Target Java-based manufacturing clusters with precision equipment offerings bypassing established Guangdong distributor relationships. Penetrate through direct-to-workshop digital configuration tools that unbundle procurement from traditional dealer markups. Prioritize mobile contractor segments with runtime-extended cordless units where Makita's ecosystem dominance remains incomplete. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed industrial distributors holding concentrated cutter-head logistics networks in North American Midwest and Southeast woodworking corridors. Five-to-ten year viability hinges on consolidation of fragmented aftermarket service capacity around spiral cutter calibration expertise. Watch for inflection signals in silica-exposure enforcement intensity that would accelerate replacement cycles in legacy commercial shops.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Coating | Captive surface treatment capacity insulates German producers from REACH chromium plating restrictions. |
| Battery Platform Ecosystem Expansion | Makita's lithium-ion interchangeability locks mobile contractors into cordless planer repeat purchases. |
| Direct-to-Workshop Digital Channel | Bypassing dealer networks captures margin from mid-sized furniture workshops in Vietnam and Indonesia. |
| Helical Cutter Retrofit Service Contracts | Quarterly calibration bundling extends asset lifecycles while anchoring recurring distributor revenue. |
| Indonesian Manufacturing Cluster Entry | First-mover positioning in Java export zones before automated milling capacity saturates. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of trade customs data, woodworking machinery safety standards, and OEM procurement disclosures. Primary interviews engaged maintenance directors at commercial furniture shops, aftermarket service heads at industrial distributors, plant engineers in Guangdong cabinetry clusters, and OEM procurement teams at German and Italian equipment producers. Secondary validation drew from OSHA machine-guarding enforcement records, EU Machinery Directive compliance databases, China GB standards publications, and Vietnamese furniture export association filings. Bottom-up unit shipment estimates triangulated against top-down addressable market sizing across the projection horizon.
Forecast inputs span product architecture segmentation by cutter-head type and power source, end-user categorization across professional woodworker and furniture manufacturer tiers, and geographic clustering by regulatory framework. Modeled dimensions include stationary versus portable platform mix, helical versus straight-knife cutter technology adoption, and dust-collection integration penetration. CAGRs derived from replacement cycle analysis tied to cutter-head wear rates and compliance-driven equipment turnover. Industry-specific inputs incorporate silica-exposure limit trajectories, battery chemistry energy density improvement curves, and CNC machining substitution pressure in high-volume commercial shops.
Stress conditions across foundry capacity utilization, REACH chemical restriction phase-in timelines, and Indonesian infrastructure buildout pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding cutter-head alignment technician availability and three-phase electrical infrastructure upgrade rates. Material shifts in OSHA silica-exposure enforcement intensity or EU Machinery Directive emergency-stop mandate expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Hacksaw Blades Market
Tools
Tile Saw Market
Tools
Mold Racks Market
Tools
Edge Banding Machine Market
Tools
Handheld Engraving Machine Market
Tools
Boring-Milling Machines Market
Tools
Brazing Torch Market
Tools
Steel Measuring Tape Market
Tools
Coil Fed Punching and Cutting Machines Market
Tools
Machine Vise Market
Tools
Cold and Hot Tool Steel Market
Tools
Grinding Discs Market
Tools
Hydraulic Tools Market
Tools
US Power Tools Market
Tools
Metal Cutting Tools Market
Tools
Collated Screws Market