
 Blowing Torch Market | 2026-2036
Blowing Torch Market Size, Share, and Industry Trends Forecast 2026-2036
Blowing Torch Market Outlook
The gap between premium precision torches and commodity propane units is expanding. Bernzomatic leverages its retail channel dominance across North American home improvement stores. Sievert AB anchors Scandinavian industrial distribution with specialized brazing equipment. Rothenberger differentiates through plumbing-trade loyalty built on German engineering reputation.
A blowing torch is a handheld combustion device that mixes fuel gas with atmospheric oxygen through a venturi nozzle to produce a directed flame exceeding 1,800°C for localized heating, cutting, or joining metals. Portable torch formats lead consumer and light-trade revenue due to mobility requirements in field construction and automotive repair. Workshop torch and industrial torch segments serve metalworking facilities where sustained duty cycles and precise flame control command higher equipment spend and aftermarket attachment sales.
OSHA workplace safety standards, EPA volatile organic compound emissions rules, and EU REACH chemical restrictions collectively shape fuel formulation, cylinder design, and ventilation requirements for torch manufacturers. The US FAA and EASA also influence aviation maintenance torch specifications through hot-work permitting protocols. Stakeholders must monitor evolving propane-butane blend regulations and assess fuel-type portfolio exposure against regional decarbonization timelines.
Market Dynamics
The EU F-Gas Regulation is compressing refrigerant-based heating alternatives and redirecting industrial procurement toward precision combustion equipment, particularly in German metalworking corridors where brazing accuracy requirements are tightening.
Growth Catalysts
- EU F-Gas Regulation Phase-Down:The refrigerant restriction regime is eliminating hydrofluorocarbon-dependent heating tools in European metal fabrication, forcing facility upgrades toward propane and MAP-gas torch systems.
- China Infrastructure Stimulus:State-directed spending on transportation and energy networks sustains bulk procurement of construction-grade propane torches across automotive supply chain welding operations.
- Aviation Maintenance Protocols:FAA hot-work permitting requirements for airframe repair are standardizing torch specifications across MRO facilities, driving replacement cycles in US aerospace clusters.
Market Restraints
- Steel Cylinder Cost Volatility:Raw material price swings for seamless steel pressure vessels compress margin structures for portable torch manufacturers dependent on Asian foundry supply.
- Supply Concentration in Propane Blending:US Gulf Coast petrochemical corridor dominance over propane-butane fractionation creates geographic vulnerability for North American fuel cartridge sourcing.
- Flame Temperature Ceiling:Atmospheric combustion physics limits oxy-fuel equivalence in handheld formats, constraining penetration into high-alloy cutting applications served by plasma systems.
Strategic Opportunities
- India Manufacturing Corridors:PLI scheme incentives for domestic appliance and automotive production are opening torch procurement channels previously served by informal fabrication methods.
- Electrification-Adjacent Servicing:EV battery pack thermal management repair protocols are creating demand for precision micro-torches in dealership service departments.
- Propane-MAPP Hybrid Formulations:Fuel chemistry advances enabling hotter flame temperatures without oxygen augmentation are capturing share in HVAC brazing applications.
Industry Challenges
- Certified Brazer Shortage:AWS SENSE and equivalent national welding certifications face training pipeline gaps in mature economies, limiting equipment utilization rates.
- Legacy Inventory Integration:Workshop torch attachment ecosystems built on proprietary quick-connect standards resist interoperability, complicating multi-brand fleet management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blowing Torch Market |
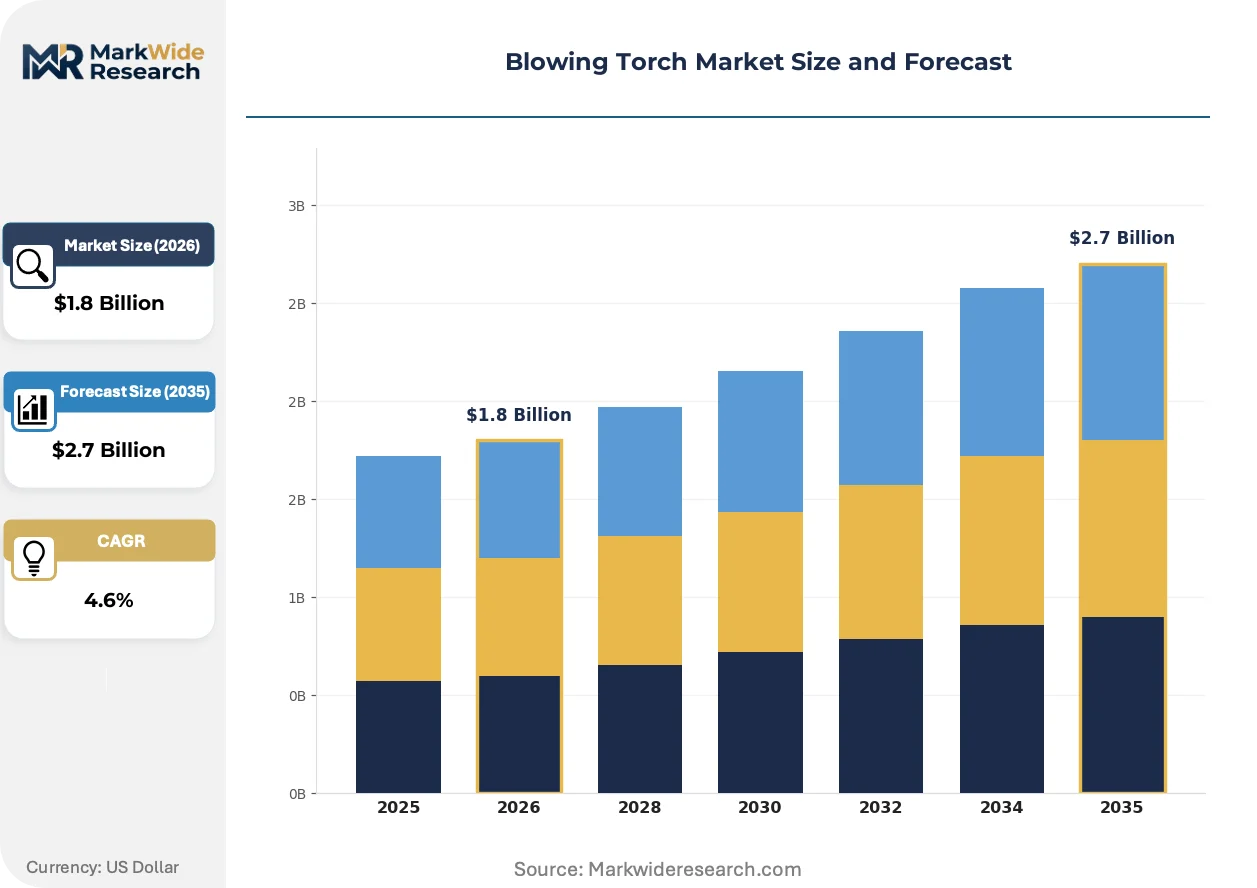
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Torch, Workshop Torch, Industrial Torch, Propane Torch Application: Welding, Soldering, Brazing, Propane Applications Fuel Type: Propane, Butane, Acetylene, Liquid Gas End User: Construction, Plumbing, Automotive, Metalworking |
| Companies Covered | Bernzomatic, Sievert AB, Rothenberger, ESAB, Iwatani Corporation, Blazer Products Inc., Lakeland, The Lenco Group, Campingaz, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blowing Torch Market Strategic Shifts
Flame control electronics and connected safety systems are redefining equipment specifications across industrial procurement channels, while fuel chemistry advances and distribution model compression reshape competitive positioning.
Microprocessor-regulated flame control is modularizing precision torch architectures. Electronic ignition modules with oxygen-sensor feedback now enable repeatable temperature profiles for aerospace brazing operations. German automotive suppliers are specifying these units for battery tab welding. The technology is modularizing what were previously integrated mechanical systems into swappable subassemblies.
REACH chemical restrictions are forcing reformulation of traditional propane additives across European distribution networks. ECHA substance evaluation processes have flagged specific odorant compounds used in leak detection, requiring substitution with compliant alternatives. Plumbing-trade distributors in Scandinavia are accelerating inventory turns to clear non-compliant stock ahead of enforcement deadlines.
Direct procurement from manufacturer digital platforms is compressing traditional wholesale markups in North American contractor supply. Independent HVAC technicians now configure torch specifications through online portals and receive cylinder replenishment via subscription logistics. This channel disintermediation is most pronounced in Sun Belt states where seasonal demand volatility previously strained distributor inventory planning.
Blowing Torch Market Segmentation
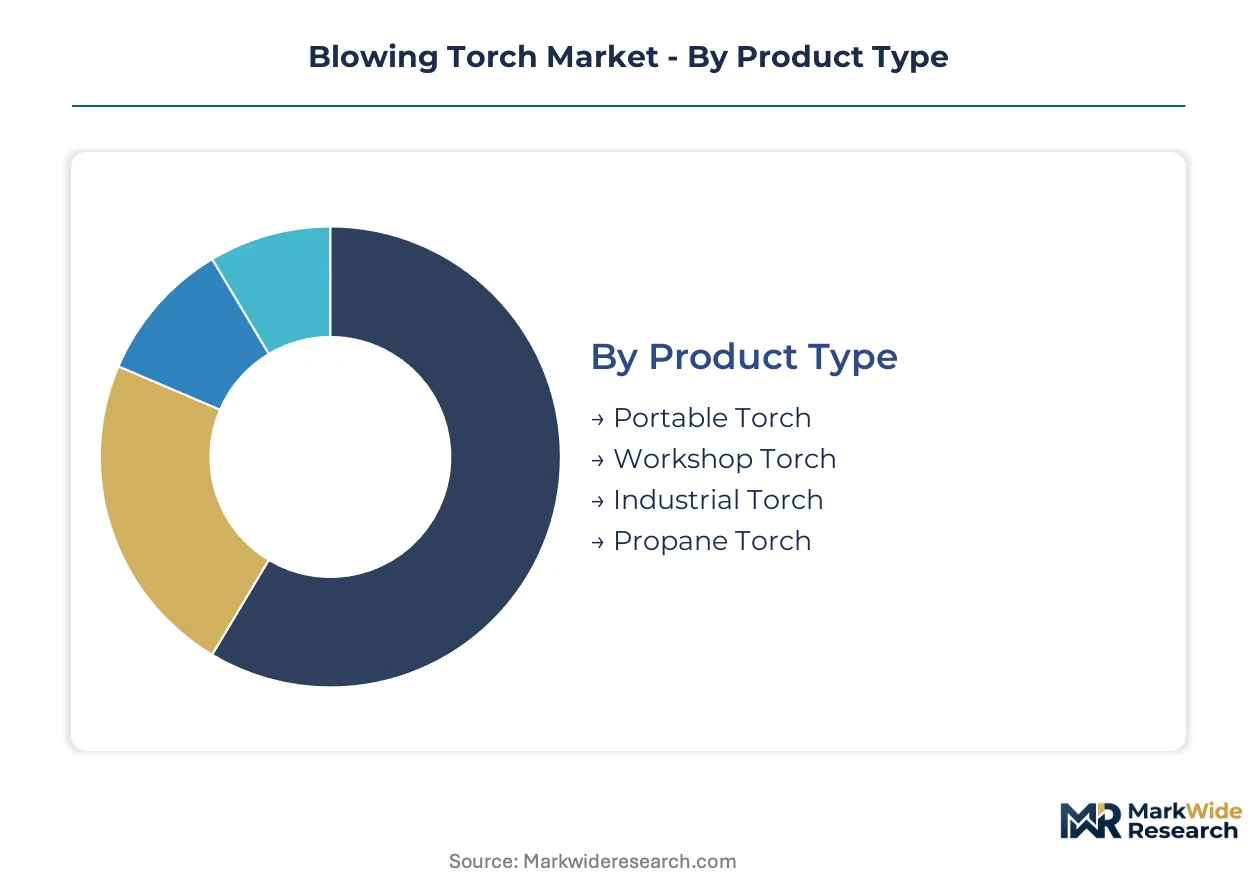
Equipment specification, fuel chemistry, and end-use thermal requirements create distinct procurement channels with incompatible performance standards and regulatory footprints. Segmentation in this market reveals where margin pools concentrate and which technology transitions are compressing legacy formats.
Product Type:
Buyer differentiation centers on duty cycle intensity and mobility requirements across field, workshop, and fixed industrial environments.
- Portable Torch:Handheld units with disposable fuel cylinders dominate field construction and automotive repair where mobility constraints override precision requirements. HVAC technicians across Texas and Florida procurement channels favor these formats for seasonal ductwork installation. This format leads volumes today; industrial torch configurations are gaining share fastest.
- Workshop Torch:Bench-mounted systems with refillable cylinder connections serve plumbing contractors and light metal fabrication where repeatable flame control justifies equipment investment. German plumbing-trade distributors specify these units for brazing certification programs.
- Industrial Torch:Heavy-duty systems with integrated flashback arrestors and oxygen-sensor feedback serve aerospace MRO facilities and automotive battery tab welding operations requiring documented temperature traceability.
- Propane Torch:Commodity-format combustion tools with basic venturi mixing serve developing market construction crews where capital constraints limit equipment spend.
Workshop torch specifications anchor mid-market revenue; industrial torch configurations are expanding most quickly.
Application:
Joint geometry, base metal properties, and thermal mass determine equipment selection and fuel chemistry requirements.
- Welding:Fusion joining of steel components demands higher flame temperatures than atmospheric torches deliver, limiting handheld penetration to thin-gauge repair work. Shipyard operators in Hamburg and Busan maintain oxy-fuel systems for structural steel.
- Soldering:Low-temperature joining of electronics and copper plumbing relies on precise, non-oxidizing flame control. Electric vehicle battery pack thermal management repair protocols are creating micro-torch demand in dealership service departments.
- Brazing:Capillary filler metal flow between close-tolerance joints requires repeatable temperature profiles and oxygen-free environments. FAA hot-work permitting for airframe repair standardizes torch specifications across US aerospace MRO clusters.
- Propane Applications:General heating, paint stripping, and bitumen work utilize basic flame tools without precision requirements. This application category carries the highest price sensitivity and lowest attachment revenue.
Brazing applications command premium equipment spend; soldering applications are climbing the fastest.
Fuel Type:
Flame temperature, storage pressure, and regional regulatory status segment fuel chemistry procurement decisions.
- Propane:C3H8 stored at moderate pressure delivers 1,980°C maximum flame temperature and dominates North American consumer and construction channels. US Gulf Coast petrochemical corridor concentration creates geographic sourcing vulnerability.
- Butane:Higher vapor pressure fuel preferred in compact lighter-style torches for electronics work and culinary applications where cylinder size constraints dominate. REACH chemical restrictions are forcing odorant reformulation across European distribution networks.
- Acetylene:C2H2 enables oxy-fuel cutting temperatures exceeding 3,000°C for steel severing operations beyond atmospheric torch capability. Industrial gas suppliers bundle cylinder exchange logistics with cutting equipment.
- Liquid Gas:Propane-butane blends and MAP-pro formulations optimize flame temperature for HVAC brazing without oxygen augmentation. Hybrid chemistry advances are capturing share in refrigeration system installation.
Propane formulations dominate unit volumes; liquid gas blends are expanding most quickly.
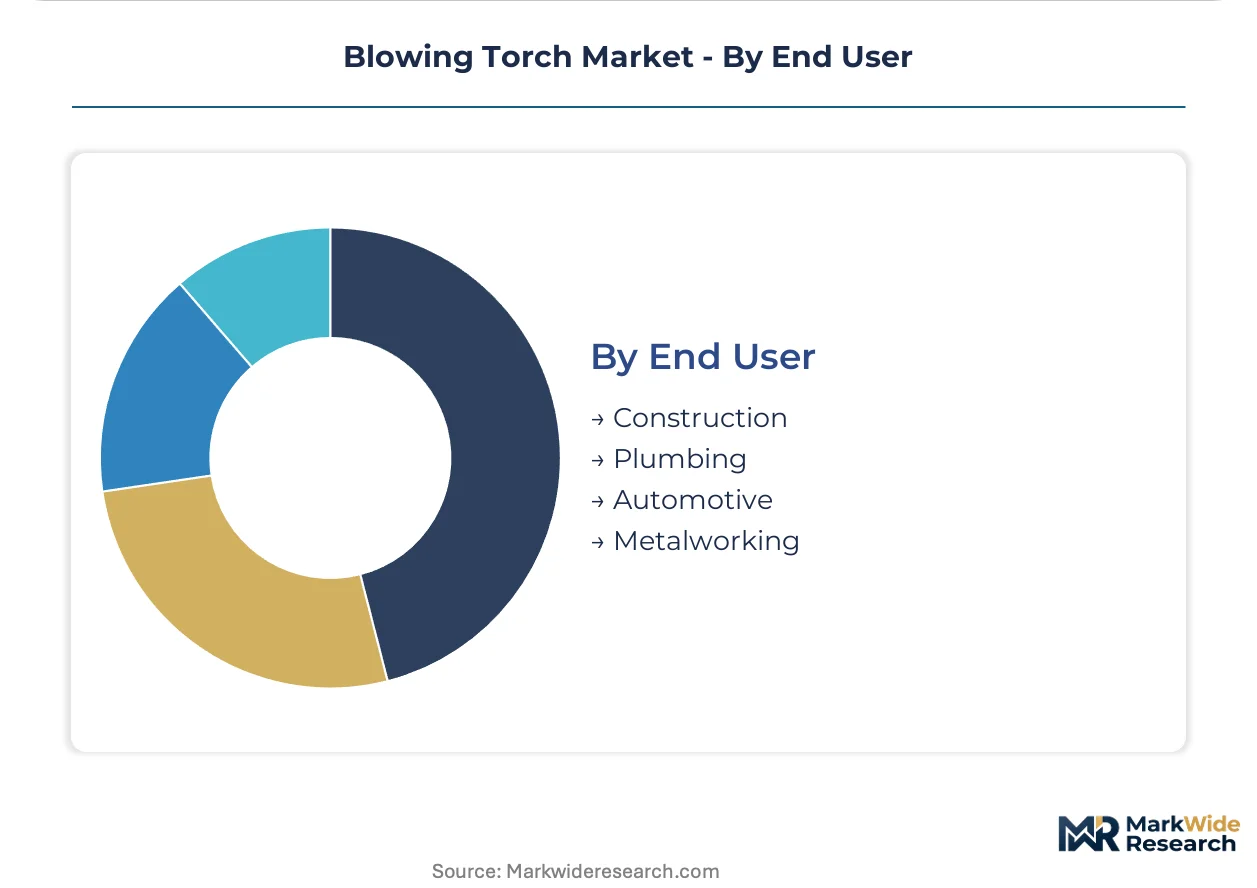
End User:
Certification requirements, fleet scale, and procurement centralization separate informal operators from institutional buyers.
- Construction:Decentralized crews with high equipment turnover favor disposable-cylinder portable formats. China's state-directed infrastructure spending sustains bulk procurement across transportation and energy networks.
- Plumbing:Trade-licensed contractors with recurring brazing workloads invest in workshop torch systems with quick-connect attachment ecosystems. Scandinavian distributors face inventory acceleration to clear non-compliant stock ahead of ECHA enforcement.
- Automotive:OEM service departments and independent repair shops balance mobility needs against precision requirements for aluminum and stainless joining. EV battery thermal management protocols are creating precision micro-torch demand.
- Metalworking:Certified brazing operations in German automotive supply chains specify microprocessor-regulated flame control with oxygen-sensor feedback for battery tab welding.
Construction channels move the highest unit volumes; automotive end-use specifications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German metalworking facilities outpace Chinese procurement in precision brazing equipment, while US aviation maintenance clusters drive specification standardization through FAA protocols.
United States
Aviation MRO facilities in Wichita and Seattle sustain torch replacement cycles through FAA hot-work permitting requirements. OSHA workplace safety standards govern ventilation and cylinder storage protocols across industrial facilities. Gulf Coast petrochemical concentration creates geographic vulnerability for propane-butane fuel cartridge sourcing.
Germany
Automotive battery tab welding operations in Stuttgart and Munich specify microprocessor-regulated flame control systems. EU F-Gas Regulation phase-down eliminates refrigerant-based heating alternatives in metal fabrication. North Rhine-Westphalia metalworking corridors anchor precision brazing equipment procurement across European supply chains.
China
State-directed infrastructure spending on transportation networks sustains bulk construction-grade torch procurement. MIIT industrial standards govern pressure vessel certification for refillable cylinder formats. Yangtze River Delta manufacturing clusters integrate propane torches into automotive supply chain welding operations.
India
PLI scheme incentives for domestic appliance production open torch procurement channels in emerging manufacturing corridors. BIS pressure equipment standards regulate cylinder design and testing protocols. Maharashtra and Gujarat automotive clusters transition from informal fabrication methods to certified brazing operations.
Japan
Precision electronics soldering demand in Osaka and Nagoya favors compact butane torch formats. METI energy efficiency guidelines influence combustion equipment specifications. Kanto region aerospace subcontractors adopt temperature-traceable systems for satellite component joining.
Blowing Torch Market Competitive Environment
Top-tier vendors anchor premium precision segments, while commodity propane specialists compete on cylinder volume and retail channel presence. The vendor base stratifies across German engineering heritage brands, Scandinavian industrial distributors, and North American retail channel dominators. Three archetypes predominate: precision brazing specialists with trade-certification loyalty, portable format mass marketers with home improvement store penetration, and industrial gas bundlers with captive cylinder exchange logistics. Competitive moves concentrate on fuel chemistry patenting and direct-to-technician digital platform launches that compress wholesale markups.
Among heritage engineering houses, Rothenberger exemplifies plumbing-trade loyalty built on German manufacturing reputation, while Sievert AB occupies a position within Scandinavian industrial distribution networks. Bernzomatic anchors North American retail dominance across home improvement store channels. These three represent distinct competitive vectors: precision workshop specification, regional industrial distribution, and consumer-format mass market penetration.
| Leading Market Players |
|---|
| Bernzomatic |
| Sievert AB |
| Rothenberger |
| ESAB |
| Iwatani Corporation |
| Blazer Products Inc. |
| Lakeland |
| The Lenco Group |
| Campingaz |
| Others |
Value Chain & Pricing Dynamics
Industrial gas bundlers with captive cylinder exchange logistics anchor pricing power in the premium tier, while independent HVAC technicians and construction crews face commodity pressure in portable formats. This bifurcation between bundled precision systems and transactional propane units defines margin capture across procurement channels.
Pricing Analysis
Bundled cylinder-exchange services versus unbundled equipment-only transactions split the pricing architecture. Three-tier pricing structure across premium microprocessor-regulated systems, standard workshop torches, and economy propane formats separates buyers by certification requirements and duty cycle intensity. Price differentiation centers on oxygen-sensor feedback modules and documented temperature traceability for aerospace specifications. Pricing pressure stems from REACH-mandated odorant reformulation costs cascading through European distribution networks. Construction-grade propane applications carry the highest price sensitivity; aviation MRO specifications show the least.
Supply Chain Analysis
Single-source vulnerability sits with the US Gulf Coast petrochemical corridor for propane-butane fractionation. Manufacturing draws from China for seamless steel pressure vessels, Germany for precision valve assemblies, and the US for fuel chemistry blending. Raw material dependencies include seamless steel cylinders, brass venturi components, and electronic ignition modules. Tariff exposure on Chinese steel imports threatens margin structures for portable torch manufacturers. Distribution runs through plumbing-trade distributors in Europe, home improvement retail chains in North America, and state-procurement channels in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on fuel chemistry patenting and the shift toward subscription-based cylinder logistics that capture recurring revenue from precision brazing operations.
For Market Incumbents: Acquire digital platform capabilities for direct-to-technician procurement to compress wholesale markups and capture subscription logistics revenue. Defend against plasma system substitution in high-alloy cutting by embedding temperature-traceable electronics into workshop torch specifications. Deepen backward integration into seamless steel cylinder production to offset Asian foundry cost volatility. For New Entrants and Emerging Players: The gap between premium precision torches and commodity propane units offers entry space for mid-tier hybrid formulations. Target India's PLI-subsidized automotive corridors where certified brazing operations are displacing informal fabrication methods. Pursue white-label partnerships with European plumbing-trade distributors clearing non-compliant REACH stock ahead of enforcement deadlines. For Investors and Strategic Acquirers: Industrial gas bundlers with captive cylinder logistics are the most active acquirer in this space, seeking to extend fuel chemistry patent portfolios. Long-term viability favors precision equipment manufacturers with embedded electronics and documented temperature traceability for aerospace and EV battery applications. Monitor FAA hot-work permitting protocol revisions as an inflection indicator for replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Fuel Chemistry Patenting | Propane-MAPP hybrid formulations capture HVAC brazing share without oxygen augmentation. |
| Direct-to-Technician Platform Launch | Subscription logistics compress wholesale markups in Sun Belt seasonal demand corridors. |
| Microprocessor-Regulated Flame Control Integration | German automotive suppliers specify these units for EV battery tab welding operations. |
| REACH-Compliant Odorant Reformulation | ECHA substance evaluation processes force substitution ahead of enforcement deadlines. |
| India Manufacturing Corridor Entry | PLI scheme incentives open procurement channels in Maharashtra and Gujarat clusters. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary interviews engaged equipment procurement managers at German automotive suppliers, HVAC contractors across Texas and Florida, aviation MRO facility engineers in Wichita and Seattle, and Scandinavian plumbing-trade distributors. Secondary validation drew from EPA volatile organic compound emissions filings, EU ECHA substance evaluation databases, FAA hot-work permitting protocols, and MIIT industrial standards documentation. Bottom-up equipment shipment tracking and top-down fuel consumption modeling provided triangulation across the analysis window.
Segment-weighting distributed value and volume across portable, workshop, and industrial torch formats by end-use intensity. The analytical framework modeled fuel type chemistry, application thermal requirements, and regional regulatory clusters throughout the forecast period. CAGRs derived from equipment replacement cycles, infrastructure spending trajectories, and certification program expansion rates. EV battery thermal management repair protocol adoption and aviation MRO facility counts served as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for electrification-adjacent precision heating would alter the outlook. Forecasts reflect assumptions regarding EU F-Gas Regulation phase-down timing, Chinese state infrastructure spending continuity, and REACH odorant reformulation compliance costs. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Global Table Saws Market
Tools
Sand Control Tools Market
Tools
Indexable Tool Inserts Market
Tools
Hydraulic Torque Wrench Market
Tools
Cordless Impact Wrench Market
Tools
Europe Power Tools Market
Tools
Electric Power Tools Market
Tools
Drywall Tool Market
Tools
Tooling Market
Tools
Shape Moulding Machines Market
Tools
Grabber Pole Market
Tools
Global Staple Gun Market
Tools
Brazing Torch Market
Tools
Vinyl Bending Machine Market
Tools
Handheld Engraving Machine Market
Tools
Bi-Metal Band Saw Blade Market