
 Level Floats Market | 2026-2036
Level Floats Market Size, Share, and Industry Trends Forecast 2026-2036
Level Floats Market Foresight
Industrial water utilities is bifurcating from traditional oil and gas buyers as the fastest-growing procurement archetype for level floats. Emerson Electric Co. leverages its digital automation portfolio to capture utility retrofit contracts across North American municipalities. ABB Ltd. anchors European demand through its process instrumentation division with integrated wireless telemetry. Quality Float Works specializes in custom stainless steel float fabrication for corrosive chemical environments.
Level floats are buoyant displacement devices that translate liquid surface position into mechanical, magnetic, or electronic signals, typically constructed from 316 stainless steel, polypropylene, or nitrile rubber with specific gravity ratings between 0.50 and 0.80 to ensure proper flotation. They serve primarily in tank level monitoring and pump control systems where continuous or point-level measurement prevents overflow, dry-running, or inventory variance. Hydrostatic and magnetic product types dominate current revenue due to their proven reliability in harsh process conditions, while ultrasonic variants are gaining traction in food and beverage applications where non-contact measurement eliminates contamination risk. Wireless technology is expanding fastest among technology segments as facilities retrofit hardwired analog installations to reduce cabling costs and enable remote diagnostics.
EPA enforces Safe Drinking Water Act provisions that mandate NSF/ANSI 61-certified materials for all level floats contacting potable water, directly restricting supplier eligibility and material choices in US municipal applications. IEC 61508 functional safety standards govern digital and pneumatic level float installations in European process industries, requiring SIL-rated components that elevate engineering costs but reduce liability exposure. REACH compliance through ECHA restricts certain elastomer formulations, pushing manufacturers toward fluoropolymer alternatives. Stakeholders must monitor regulatory divergence between North American material certification and European functional safety mandates when configuring product platforms for cross-border deployment.
Market Dynamics
Wireless telemetry retrofit cycles across municipal water infrastructure are compressing replacement timelines for legacy mechanical floats, while EPA and NSF material mandates are disqualifying incumbent suppliers lacking certified polymer portfolios.
Growth Catalysts
- Reservoir automation mandates:Municipal utilities in Germany and the Netherlands are accelerating procurement of smart level floats with integrated telemetry to meet EU Water Framework Directive monitoring obligations.
- NSF/ANSI 61 certification expansion:US potable water infrastructure spending is channeling demand exclusively toward suppliers with certified nitrile and EPDM formulations for direct human contact applications.
- Industry 4.0 retrofit cycles:Chemical processing corridors in Belgium and Switzerland are replacing pneumatic float systems with digital transmitters to enable predictive maintenance workflows.
Market Restraints
- Fluoropolymer feedstock volatility:PTFE and PVDF resin prices fluctuate with semiconductor demand cycles, compressing margins for corrosion-resistant float manufacturers.
- Regional supply concentration:Precision-machined 316 stainless steel float fabrication clusters heavily in Baden-Württemberg, creating single-source vulnerability for European process industries.
- Ultrasonic substitution pressure:Non-contact level sensors are capturing food-grade tank applications where CIP/SIP protocols favor zero-wetted-surface designs.
Strategic Opportunities
- India municipal water expansion:Smart Cities Mission funding is creating first-time demand for telemetry-enabled floats in tier-2 urban water distribution networks.
- CE marking harmonization:Unified EU machinery safety standards are reducing certification duplication costs for floats deployed across multiple member states.
- IIoT platform convergence:Edge computing integration with level floats is enabling real-time inventory optimization for bulk chemical distributors.
Industry Challenges
- SIL certification timelines:IEC 61508 functional safety validation for process industry floats extends product development cycles by 12-18 months.
- Legacy system integration friction:4-20mA analog infrastructure in aging US water treatment plants complicates digital float deployment without full SCADA replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Level Floats Market |
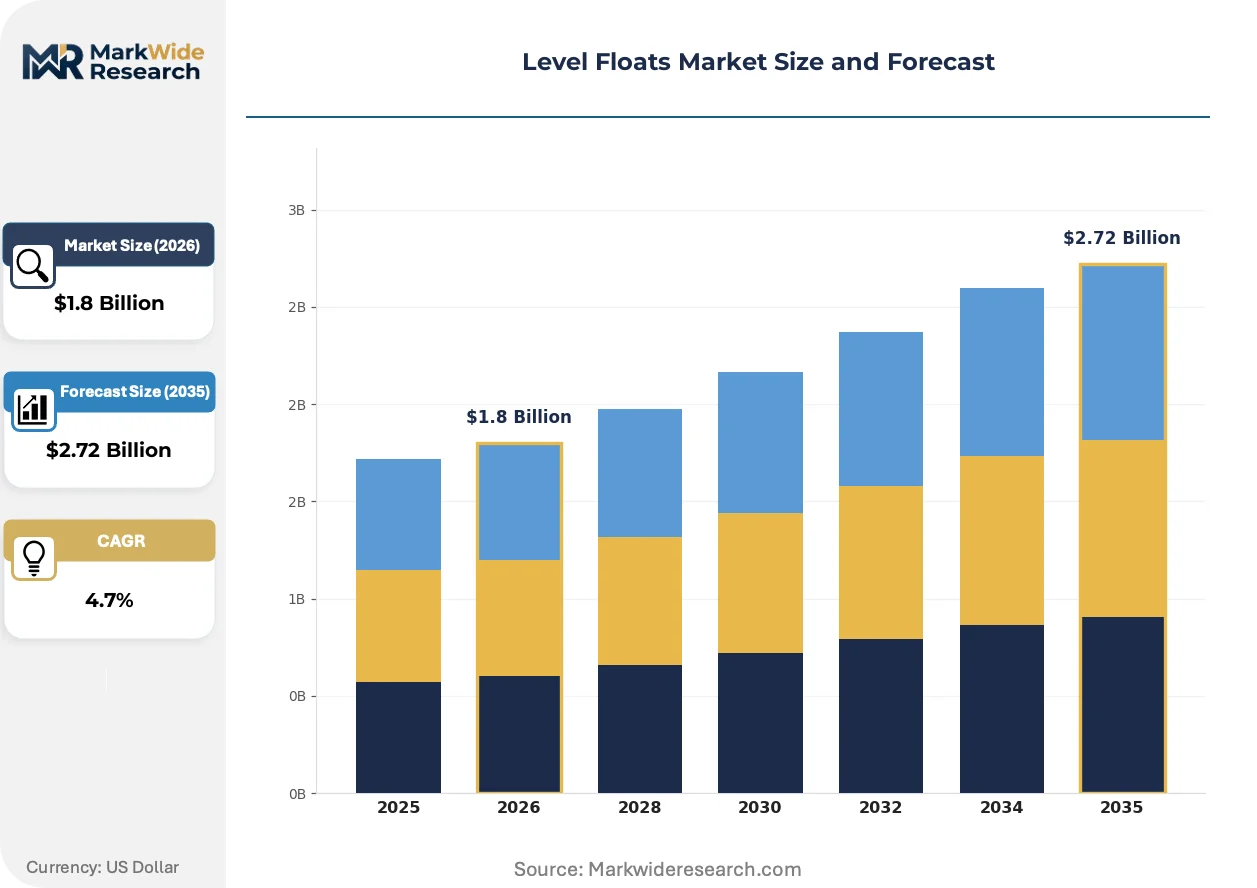
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrostatic, Magnetic, Capacitive, Ultrasonic End User: Chemical Industry, Water Treatment, Oil & Gas, Food & Beverage Technology: Wireless, Analog, Digital, Pneumatic Application: Tank Level Monitoring, Pump Control, Inventory Management, Process Control |
| Companies Covered | Rogers Corporation, SAICHEM Consolidated, Naigai Rubber Industry, Kecy Metal Technologies, Arthur Harris, Quality Float Works, Emerson Electric Co., ABB Ltd., Endress+Hauser, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Level Floats Market Shifts & Advancements
Magnetic reed switch technology is yielding to solid-state Hall effect sensors in hazardous area classifications, while REACH-driven material bans are accelerating fluoropolymer formulation R&D across European supply chains.
Hall effect sensing arrays are supplanting traditional magnetic reed switches in offshore oil and gas separators. Norwegian platform operators are specifying solid-state designs for SIL-rated safety loops. This transition is compressing maintenance intervals from quarterly to annual schedules while eliminating mechanical failure modes.
REACH authorization requirements through ECHA are restricting short-chain chlorinated paraffins in cable jacketing for submersible float assemblies. German cable suppliers are reformulating with bio-based polyurethane alternatives. Process industries in the Rhine-Ruhr corridor are absorbing 15-20% material cost premiums to maintain market access.
Integrated service contracts are displacing transactional hardware sales among North American municipal utilities. Chicago and Atlanta water departments now specify ten-year performance agreements bundling floats, calibration, and cloud telemetry. This model transfers obsolescence risk to suppliers while locking in multi-year revenue streams.
Level Floats Market Segmentation
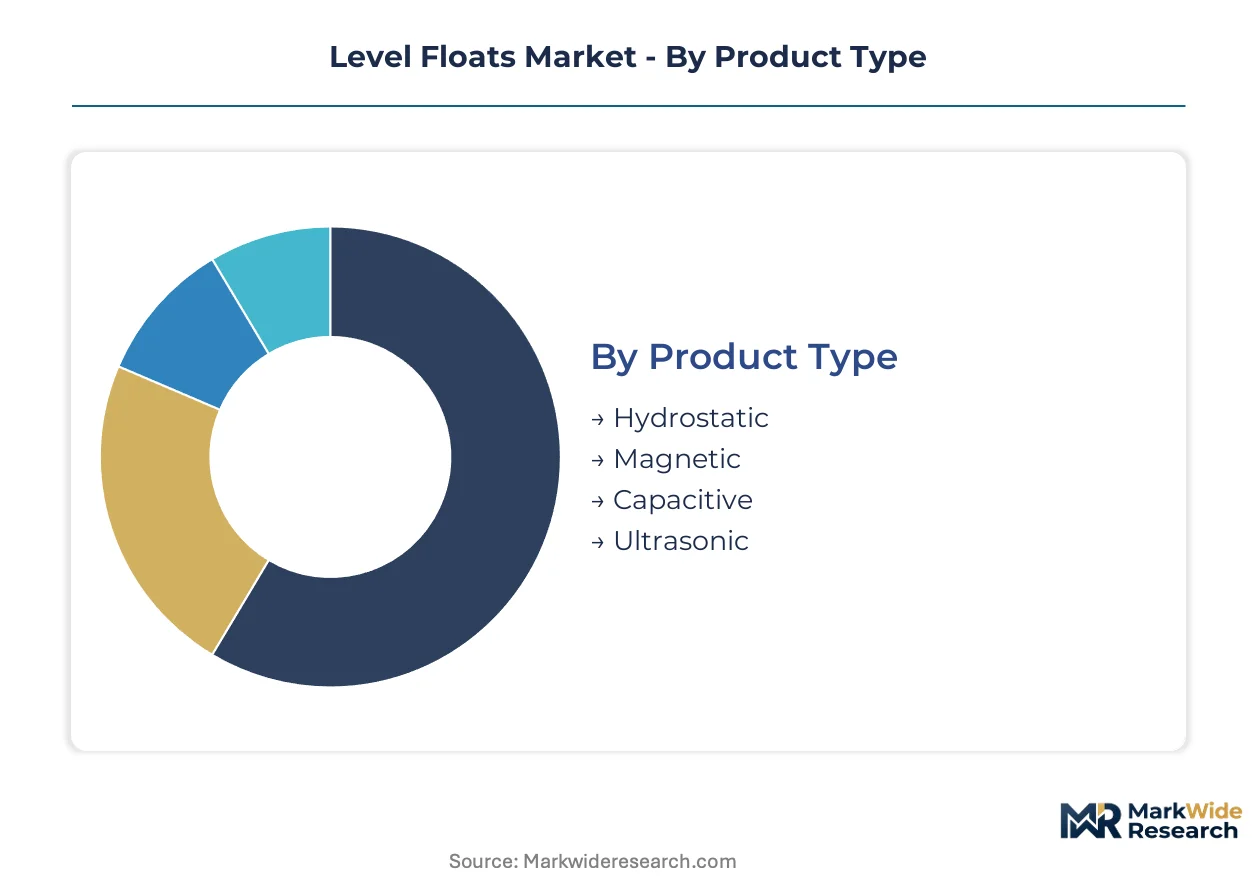
Level float procurement varies sharply across process environments. Material certification requirements from EPA and ECHA fragment supplier eligibility by end-use sector. Technology choices increasingly bifurcate between legacy analog infrastructure and telemetry-enabled retrofits.
Product Type:
EPA Safe Drinking Water Act enforcement and ECHA REACH material restrictions create divergent specification pathways for each product category.
- Hydrostatic:These pressure-based sensors measure liquid head through submerged transducers sealed in 316 stainless steel or ceramic housings. German chemical processors along the Rhine-Ruhr corridor specify hydrostatic floats for aggressive acid storage where diaphragm compatibility outweighs wireless convenience. IEC 61508 SIL ratings dominate procurement criteria here.
- Magnetic:Reed switch or Hall effect sensors detect float position via magnetic coupling through non-magnetic vessel walls. Municipal utilities in the Netherlands favor magnetic designs for drinking water reservoirs because NSF/ANSI 61-certified polymer floats eliminate wetted electronics while satisfying EU Water Framework Directive monitoring mandates.
- Capacitive:Dielectric measurement suits adhesive or coating-prone liquids in food processing.
- Ultrasonic:Non-contact time-of-flight sensors eliminate contamination risk for CIP/SIP protocols in Belgian dairy operations.
Established volume favors magnetic designs; emerging adoption favors ultrasonic alternatives.
End User:
Customer procurement maturity spans from transactional hardware purchases to decade-long performance contracts.
- Chemical Industry:Corrosion-resistant float specifications dominate capital expenditure decisions. Belgian and Swiss processors demand PTFE or PVDF wetted components for halogenated solvent handling. REACH compliance costs have compressed supplier margins by 15-20% while elevating fluoropolymer formulation expertise as a competitive barrier.
- Water Treatment:Smart Cities Mission funding in India is creating first-time demand for telemetry-enabled floats in tier-2 urban distribution networks. Chicago and Atlanta have shifted to ten-year service agreements bundling hardware, calibration, and cloud analytics.
- Oil & Gas:Offshore platform operators in Norway specify solid-state Hall effect arrays for SIL-rated safety loops.
- Food & Beverage:CIP/SIP sterilization protocols favor non-contact ultrasonic measurement to eliminate bacterial harborage points.
Contract structure diverges: chemical buyers transact; water utilities subscribe.
Technology:
Retrofit economics and infrastructure age determine adoption velocity across transmission protocols.
- Wireless:Battery-powered or energy-harvesting transmitters eliminate trenching and conduit costs in aging US treatment plants. Germany's Industry 4.0 retrofit cycles are accelerating replacement of pneumatic systems with wireless digital transmitters for predictive maintenance workflows.
- Analog:4-20mA current loops persist where SCADA replacement budgets remain constrained.
- Digital:IO-Link and HART protocols enable edge computing integration for real-time inventory optimization.
- Pneumatic:Compressed-air signaling retains niche presence in explosion-hazard zones lacking intrinsic safety barriers.
Wireless climbs the fastest; pneumatic retains hazard-zone incumbency.
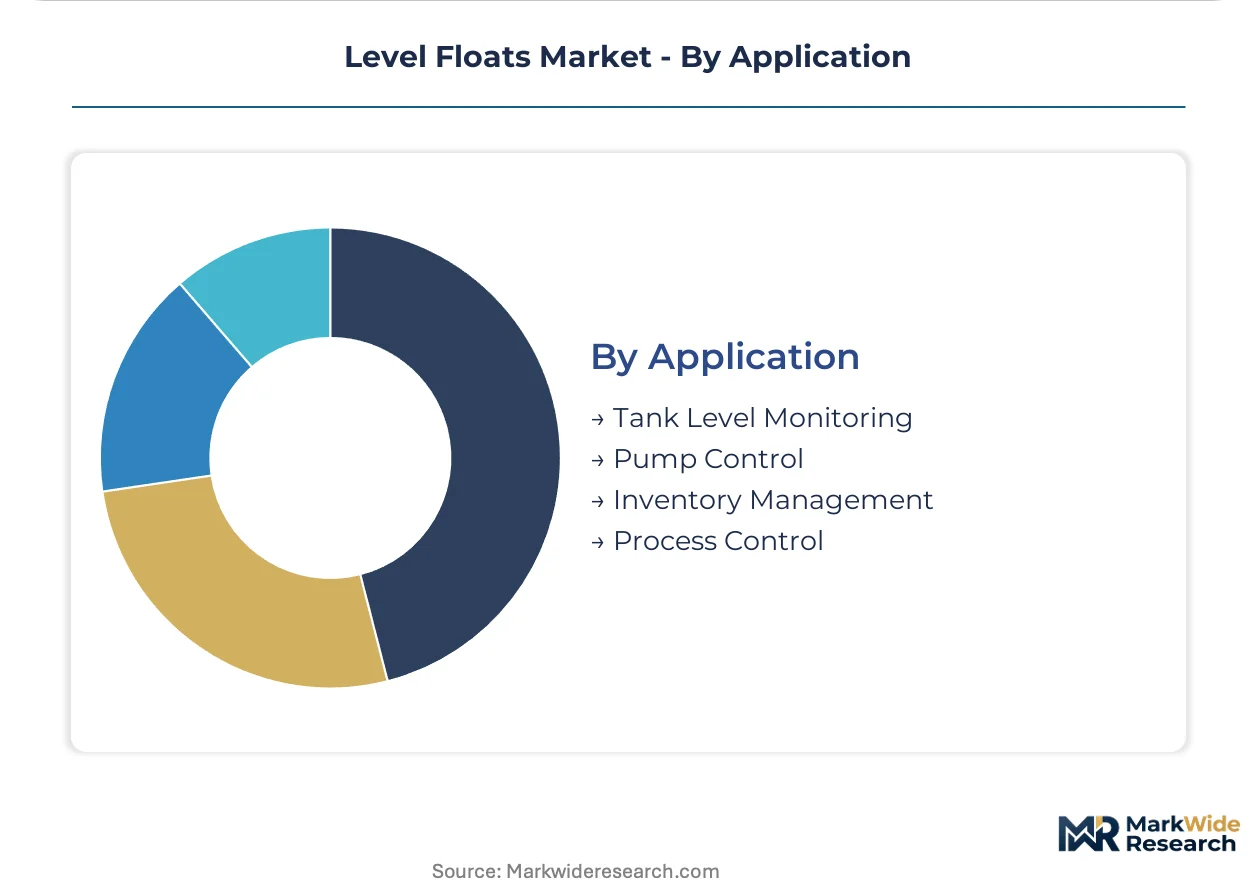
Application:
Functional criticality shapes specification rigor and supplier qualification depth.
- Tank Level Monitoring:Continuous measurement prevents overflow events in bulk chemical storage. German Baden-Württemberg fabrication clusters supply precision-machined stainless steel floats for this application, creating single-source vulnerability for European process industries.
- Pump Control:Point-level switches prevent dry-running damage in municipal lift stations. EPA enforcement of Safe Drinking Water Act provisions mandates NSF/ANSI 61-certified materials for all wetted components in US potable water contact.
- Inventory Management:Real-time volume tracking enables just-in-time chemical procurement for distributors.
- Process Control:Closed-loop level regulation demands SIL-rated components under IEC 61508, extending product development cycles by 12-18 months.
Safety-critical applications favor process control; cost-sensitive buyers prioritize tank monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision-machined 316 stainless steel float fabrication clusters heavily in Baden-Württemberg, creating single-source vulnerability for European process industries. Municipal utilities across the Netherlands and Germany are accelerating procurement of smart level floats with integrated telemetry. Chemical processors in Belgium and Switzerland are replacing pneumatic systems with digital transmitters.
United States
Chicago and Atlanta water departments now specify ten-year performance agreements bundling floats, calibration, and cloud telemetry. EPA enforcement of Safe Drinking Water Act provisions mandates NSF/ANSI 61-certified materials for all wetted components in potable water contact. Battery-powered wireless transmitters eliminate trenching costs in aging treatment plants across the Midwest and Southeast.
Germany
Rhine-Ruhr corridor chemical processors specify hydrostatic floats for aggressive acid storage where diaphragm compatibility outweighs wireless convenience. Industry 4.0 retrofit cycles are accelerating replacement of pneumatic systems with digital transmitters for predictive maintenance workflows. Baden-Württemberg fabrication clusters supply precision-machined stainless steel floats for tank level monitoring applications.
Netherlands
Municipal utilities favor magnetic designs for drinking water reservoirs because NSF/ANSI 61-certified polymer floats eliminate wetted electronics. EU Water Framework Directive monitoring obligations are driving smart float procurement with integrated telemetry. Rotterdam and Amsterdam water authorities are expanding reservoir automation to meet real-time monitoring requirements.
Belgium
REACH compliance costs have compressed supplier margins by 15-20% while elevating fluoropolymer formulation expertise as a competitive barrier. Belgian processors demand PTFE or PVDF wetted components for halogenated solvent handling. Antwerp chemical corridor buyers transact rather than subscribe, contrasting with North American municipal contracting patterns.
Switzerland
Process industries are absorbing material cost premiums to maintain market access under REACH authorization requirements. Swissmedic and federal chemical safety standards govern float specifications for pharmaceutical water systems. Basel and Zurich chemical clusters specify SIL-rated components under IEC 61508 for closed-loop level regulation.
Level Floats Market Competitive Landscape
Concentration sits with diversified industrial automation conglomerates and specialized precision fabricators. The vendor base spans three tiers: multinational instrumentation groups with digital automation portfolios, regional stainless steel machining specialists, and commodity polymer float suppliers. Strategic moves center on vertical integration into certified polymer supply chains and long-term service contract structures that transfer obsolescence risk to suppliers.
Within the diversified automation tier, Emerson Electric Co. and ABB Ltd. exemplify scale-driven positioning through process instrumentation divisions with integrated wireless telemetry capabilities. Quality Float Works anchors the specialized fabrication segment as a custom stainless steel float producer for corrosive chemical environments. These three companies represent the dominant competitive archetypes: multinational digital automation, regional precision machining, and application-specific material expertise.
| Leading Market Players |
|---|
| Rogers Corporation |
| SAICHEM Consolidated |
| Naigai Rubber Industry |
| Kecy Metal Technologies |
| Arthur Harris |
| Quality Float Works |
| Emerson Electric Co. |
| ABB Ltd. |
| Endress+Hauser |
| Others |
Supply & Pricing Matrix
Capacity utilization at Baden-Württemberg precision machining clusters shapes both supply concentration and price floors for 316 stainless steel floats. Scale economies in German fabrication create asymmetric pricing power against smaller polymer molders in fragmented Asian supply bases.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates NSF/ANSI 61-certified polymer floats from uncertified commodity alternatives and custom-fabricated stainless steel designs. Price differentiation hinges on certification grade and volume scale, with municipal utilities capturing 15-25% discounts on ten-year service contracts. Cost compression in the economy tier is intensifying because REACH-driven fluoropolymer reformulation has elevated material costs. Chemical processors show least price sensitivity due to corrosion-resistance requirements, while tier-2 Indian municipal buyers remain most cost-constrained.
Supply Chain Analysis
Strategic stockpiling of PTFE and PVDF resins dominates procurement behavior among European float manufacturers facing semiconductor demand cycles. Supply concentrates in Germany for precision-machined stainless steel, China for polymer injection molding, and India for emerging telemetry assembly. Raw material dependencies include 316 stainless steel bar stock, nitrile and EPDM elastomer formulations, and rare-earth magnets for Hall effect sensors. Single-source vulnerability runs through Baden-Württemberg fabrication clusters. Distribution runs through industrial automation distributors and direct municipal procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized fluoropolymer formulation expertise has emerged as the scarcest capability in this market, separating viable suppliers from disqualified incumbents. The gap between certified and uncertified material portfolios is widening faster than procurement teams can requalify alternative sources.
For Market Incumbents: Shield certified polymer supply positions through captive sourcing arrangements or long-term offtake agreements with ECHA-compliant resin suppliers. Ultrasonic substitution pressure in food-grade applications demands accelerated Hall effect sensor R&D to defend magnetic float market share. Vertical integration into NSF/ANSI 61-certified nitrile compounding reduces regulatory exposure. For New Entrants and Emerging Players: Telemetry-as-a-service bundling represents the most exploitable gap where Emerson and ABB under-serve mid-tier Indian municipal utilities. Target tier-2 cities under India's Smart Cities Mission with localized calibration partnerships and Hindi-language cloud dashboards. Cloud-first subscription models bypass capital-budget constraints that block hardware-only entrants. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among municipal water utilities adopting ten-year performance agreements. Long-term viability favors precision fabricators with dual-certified polymer portfolios and IIoT platform integration capabilities. Watch for fluoropolymer feedstock price stabilization as the inflection signal for margin recovery in corrosion-resistant float manufacturing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Polymer Supply | Captive NSF/ANSI 61 and REACH-compliant resin production locks out competitors from US and EU municipal procurement. |
| Wireless Telemetry Platform Convergence | IO-Link and HART protocol integration enables predictive maintenance contracts with German chemical processors. |
| Long-term Performance Contract Structuring | Ten-year service agreements with Chicago and Atlanta transfer obsolescence risk while securing revenue visibility. |
| Geographic Expansion into Indian Tier-2 Municipalities | Smart Cities Mission funding creates first-time demand for telemetry-enabled floats in underserved urban networks. |
| SIL Certification Investment for Process Industries | IEC 61508 validation opens Norwegian offshore and Swiss pharmaceutical safety-loop specifications. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with municipal water utility procurement directors, chemical plant maintenance engineers, and industrial automation distributors; and secondary validation through EPA enforcement records, ECHA REACH authorization databases, EU Water Framework Directive implementation reports, and customs trade data for 316 stainless steel and fluoropolymer resin flows. Bottom-up triangulation across product type, end-use sector, and technology segments anchored volume estimates against top-down macroeconomic indicators.
Across the analysis window, the forecasting framework modeled segmentation dimensions including product type (hydrostatic, magnetic, ultrasonic), end-use vertical (chemical, water treatment, oil and gas, food and beverage), and transmission technology (wireless, analog, digital, pneumatic). CAGRs derived from historical replacement cycle analysis, retrofit penetration curves, and regulatory compliance deadlines. Industry-specific inputs included municipal infrastructure spending flows, Industry 4.0 adoption indices, and REACH authorization timelines.
Forecasts assume regulatory continuity in EPA Safe Drinking Water Act enforcement and ECHA REACH material restrictions; material policy shifts would require re-modeling. Specific risks include fluoropolymer feedstock price volatility, single-source fabrication concentration in German industrial clusters, and ultrasonic substitution acceleration in food-grade applications. Revision becomes warranted when wireless telemetry retrofit penetration crosses critical mass thresholds in North American municipal infrastructure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Steel Measuring Tape Market
Tools
Turning Tools Market
Tools
Telescopic Tool Boxes Market
Tools
High-Speed Steel Metal Cutting Tools Market
Tools
Allen Key Market
Tools
Handheld Pipe Cutter Market
Tools
Pipe Alignment Clamps Market
Tools
Welding Products Market
Tools
Portable Heat Press Machine Market
Tools
Wire Cutters Market
Tools
Screw Fastener Market
Tools
Cutting Equipment Market
Tools
Global Swaging Machine Market
Tools
Spray Painting Machine Market
Tools
Fixed Cutter Bits Market
Tools
Handheld Engraving Machine Market