
 Welding Guns Market | 2026-2036
Welding Guns Market Size, Share, and Industry Trends Forecast 2026-2036
Welding Guns Market Analytics
Skilled welder availability is collapsing across advanced manufacturing economies, forcing OEMs to accelerate automatic and semi-automatic welding gun deployment. Lincoln Electric leverages its vertical integration in wire feed systems to capture replacement demand from aging manual fleets. Panasonic sustains technology leadership in robotic welding integration for automotive body-in-white lines. ESAB competes through its dense service network and localized spare parts logistics across European fabrication hubs.
Welding guns are precision thermal joining instruments engineered to deliver controlled electrical arcs through consumable or non-consumable electrodes, with duty cycles typically rated between 60% and 100% and current outputs spanning 150 to 600 amperes depending on industrial application. These systems execute structural bonds in metal fabrication by generating localized heat sufficient to melt base and filler materials while shielding molten pools from atmospheric contamination. MIG guns dominate volume in automotive stamping and frame assembly where speed governs line economics, while TIG equipment commands premium positioning in aerospace turbine component welding where joint integrity requirements exclude spatter-tolerant processes. Digital technology segments are expanding fastest as Industry 4.0 protocols embed arc monitoring and predictive maintenance into gun controllers, shifting margin pools from hardware sales toward software-enabled service contracts.
FDA oversight of medical device welding and FAA airworthiness directives for structural joint certification constrain product design parameters in high-integrity applications, while OSHA workplace exposure limits for hexavalent chromium and manganese fume drive demand for integrated extraction systems. The EU AI Act and MDR framework will impose algorithmic transparency requirements on adaptive welding controllers used in regulated medical and aerospace supply chains. Stakeholders must monitor how dual regulatory pressure from occupational safety and product liability standards reshapes R&D allocation between automation hardware and embedded compliance software.
Market Dynamics
Robotic welding gun deployment is accelerating across automotive OEMs as labor scarcity collides with electric vehicle platform complexity, forcing capital reallocation from manual stations to adaptive arc systems.
Growth Catalysts
- EU Green Deal F-Gas Regulation:Tightening emissions standards for welding shielding gases are compelling fabricators to upgrade to closed-loop MIG systems with integrated gas recovery, expanding replacement cycles for precision gun hardware.
- Automotive body-in-white automation:Electric vehicle manufacturers in Germany's manufacturing belt are commissioning robotic welding lines at triple the density of internal combustion platforms, concentrating demand for high-duty-cycle gun systems.
- Copper-chromium-zirconium electrode alloys:Advanced consumable materials are extending tip life by 40% in high-amperage applications, reducing downtime penalties that previously constrained automated line economics.
Market Restraints
- Copper price volatility:Electrode holder and contact tip fabrication depends on copper concentrates from Chilean and Peruvian mining operations, exposing gun manufacturers to LME price swings that compress margin buffers on fixed-price contracts.
- Technical limitation in aluminum arc stability:Pulsed MIG systems struggle with consistent arc initiation on 6xxx series aluminum alloys used in EV battery trays, forcing reliance on slower TIG processes that throttle line speed targets.
- Substitution threat from mechanical fastening:Automotive OEMs are qualifying flow-drill screw and self-piercing rivet systems for aluminum-intensive joints, bypassing thermal joining entirely in non-structural applications.
Strategic Opportunities
- Underpenetrated aerospace maintenance sector:MRO facilities in France and Italy still operate 60% manual TIG stations for turbine blade repair, creating retrofit demand for portable automated gun systems with adaptive waveform control.
- Technology convergence of arc monitoring and predictive maintenance:Embedding current signature analysis and thermal imaging into gun controllers enables shift from hardware sales to subscription-based uptime guarantees.
- Polish and Czech fabrication hubs:Central European metalworking clusters are modernizing Soviet-era equipment fleets, presenting first-mover advantage for vendors offering localized service networks and Polish-language HMI interfaces.
Industry Challenges
- Welding technician certification timelines:EN ISO 9606 qualification requirements for robotic gun operators extend training periods to 18 months, constraining deployment velocity for automotive line expansions.
- Integration complexity with legacy PLC architectures:Brownfield automotive plants in Stuttgart and Wolfsburg run Siemens S7-300 systems that lack native EtherCAT support, requiring costly gateway hardware for new gun controller integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Welding Guns Market |
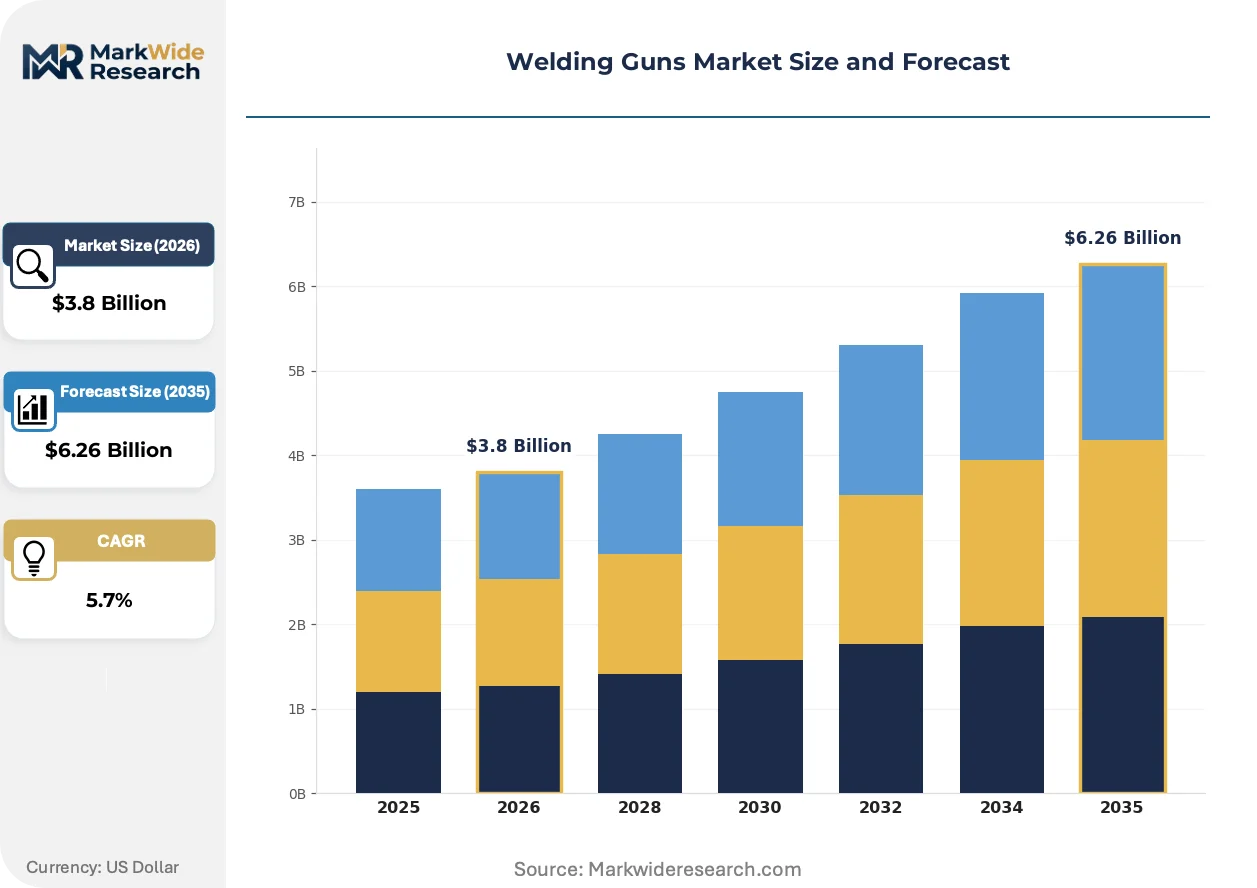
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: MIG, TIG, Stick, Plasma Technology: Manual, Automatic, Semi-Automatic, Digital Application: Automotive, Construction, Aerospace, Fabrication End User: Manufacturers, Contractors, DIY Enthusiasts, Service Providers |
| Companies Covered | Fronius International, Panasonic, Lincoln Electric, EWM AG, KUKA, Miller Electric, Illinois Tool Works, ARO Technologies, ESAB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Welding Guns Market Evolving Landscape
Digital arc control architectures are supplanting analog gun controllers, embedding real-time waveform modulation and cloud-connected diagnostics that transform welding guns from passive tools into data-generating production assets.
Friction stir welding gun systems are displacing conventional fusion processes in aluminum battery enclosure assembly. BMW and Volkswagen production engineers are specifying solid-state joining for EV underbody structures to eliminate solidification defects. This displacement is compressing the addressable market for traditional MIG equipment in automotive thermal joining by an estimated 15-20% in battery-adjacent applications.
The EU AI Act algorithmic transparency mandates are reshaping adaptive welding controller development. Manufacturers must now document decision logic for real-time parameter adjustment in medical device and aerospace supply chains. German welding gun vendors are responding by partitioning AI-driven arc control into explainable rule-based modules rather than opaque neural networks.
Fleet-based procurement models are consolidating welding gun purchasing authority from plant-level maintenance managers to corporate procurement centers. Tier-1 automotive suppliers in Bavaria and Baden-Württemberg are standardizing on single-vendor gun platforms across multiple stamping facilities, extracting volume discounts that squeeze regional distributor margins.
Welding Guns Market Segmentation
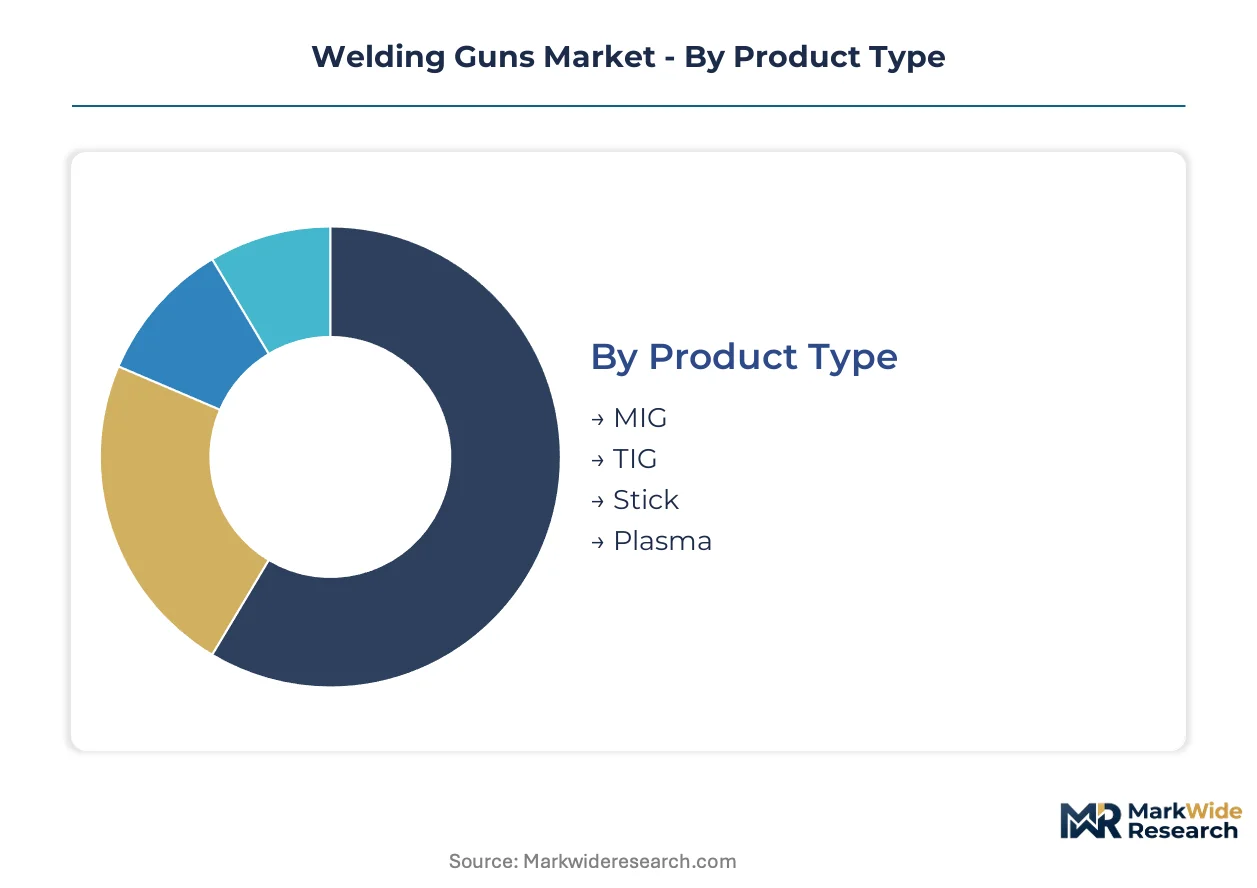
Welding gun segmentation reveals how margin pools migrate between hardware commoditization and software-enabled service contracts. Product type and technology divisions track the shift from manual replacement sales toward robotic integration packages.
Product Type:
MIG systems capture the largest margin pools through high-volume automotive contracts, while TIG commands premium positioning in regulated aerospace supply chains.
- MIG:Consumable electrode systems deliver continuous wire feed at 150-600 amperes for automotive stamping and frame assembly. Demand concentrates in Germany's automotive belt where EV manufacturers commission robotic lines at triple the density of combustion platforms.
- TIG:Non-consumable tungsten electrode systems provide precision arc control for aerospace turbine components and medical device welding. Joint integrity requirements in FAA-certified applications exclude spatter-tolerant processes, sustaining premium pricing.
- Stick:Shielded metal arc systems dominate field construction and repair applications where portability outweighs deposition efficiency.
- Plasma:High-velocity ionized gas cutting systems serve fabrication shops requiring precision severing of conductive materials.
MIG holds installed capacity across automotive OEMs. TIG is rotating up the share rankings as aerospace MRO facilities modernize manual stations.
Technology:
Technology tiers trace the automation gradient from skilled labor dependence toward predictive maintenance platforms.
- Manual:Operator-controlled systems with basic current adjustment dominate aging fabrication fleets in Central European metalworking clusters.
- Semi-Automatic:Wire feed automation with manual arc initiation bridges workforce scarcity constraints in mid-tier construction contractors.
- Automatic:Robotic integration with adaptive waveform control serves automotive body-in-white lines where EN ISO 9606 certification timelines constrain deployment velocity.
- Digital:Cloud-connected controllers embedding arc monitoring and current signature analysis are gaining share fastest as Industry 4.0 protocols shift margin pools toward subscription-based uptime guarantees.
Manual technology retains legacy installed base. Digital is climbing the fastest as EU AI Act transparency mandates reshape controller development.
Application:
Application segmentation maps how end-use requirements fragment between speed-driven volume and integrity-driven precision.
- Automotive:High-duty-cycle robotic systems for electric vehicle platform welding face displacement pressure from friction stir alternatives in battery enclosure assembly.
- Construction:Portable manual and semi-automatic systems serve infrastructure steel erection where site conditions preclude fixed automation.
- Aerospace:FAA airworthiness directives and MDR framework compliance constrain adaptive controller design for structural joint certification.
- Fabrication:General metalworking shops in Poland and Czech Republic drive replacement demand as Soviet-era equipment fleets modernize.
Automotive anchors current volume. Aerospace is expanding most quickly as MRO facilities retrofit portable automated systems.
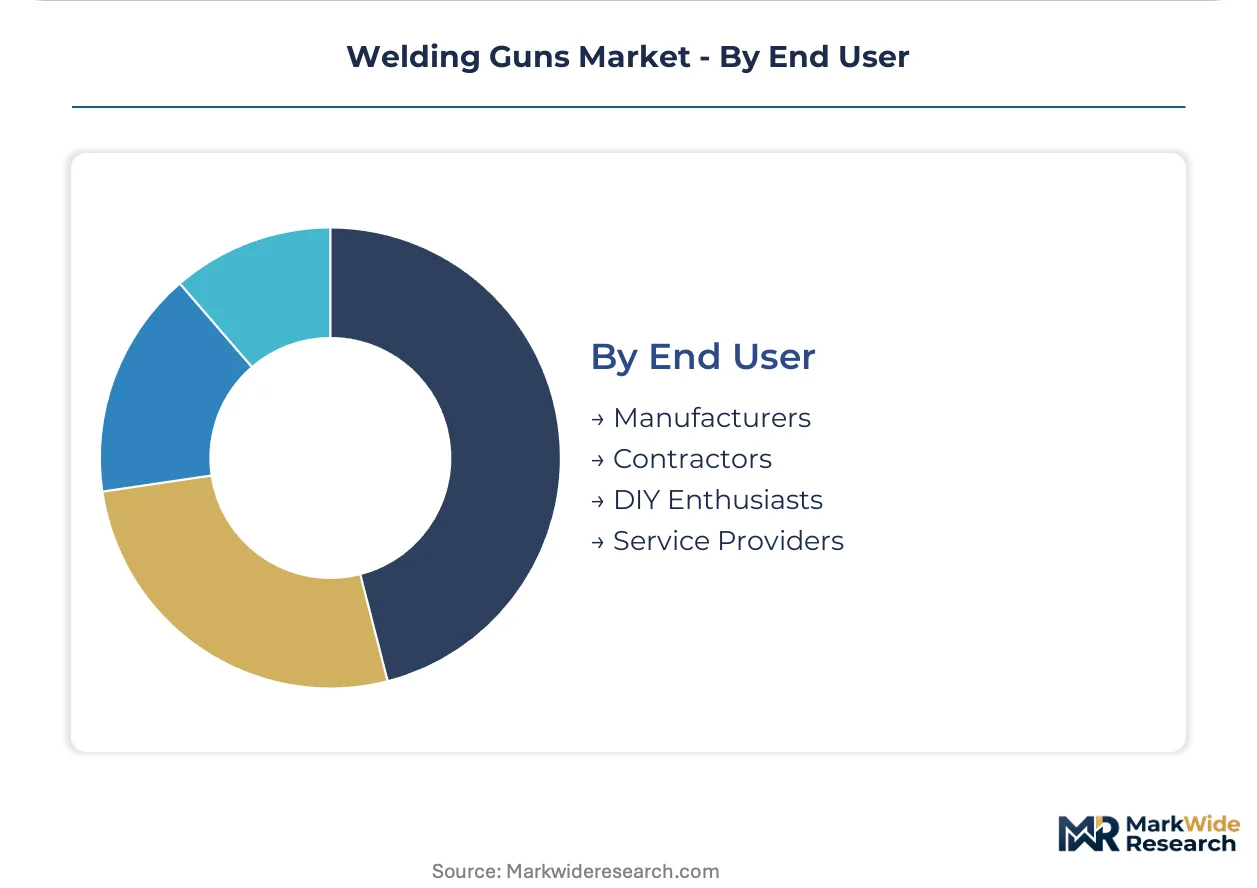
End User:
End user categories reflect procurement authority concentration from plant-level maintenance toward corporate fleet standardization.
- Manufacturers:Tier-1 automotive suppliers in Bavaria and Baden-Württemberg are consolidating gun purchasing across multiple stamping facilities to extract volume discounts.
- Contractors:Construction welding services depend on equipment rental networks and localized spare parts logistics for uptime assurance.
- DIY Enthusiasts:Hobbyist segment purchases entry-level MIG systems through distributor retail channels with minimal service attachment.
- Service Providers:Independent maintenance firms and welding equipment lessors capture recurring revenue through preventive maintenance contracts.
Manufacturers dominate capital expenditure. Service Providers are gaining share fastest as fleet-based procurement models expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal F-Gas Regulation anchors European demand for closed-loop welding systems. Germany's automotive belt concentrates robotic gun deployment for electric vehicle platforms. Fabrication clusters in Poland and Czech Republic drive replacement cycles as Soviet-era equipment modernizes.
Germany
Automotive OEMs in Stuttgart and Wolfsburg commission robotic welding lines at triple the density of combustion platforms. The EU AI Act imposes algorithmic transparency requirements on adaptive controllers used in medical device supply chains. Bavaria and Baden-Württemberg host Tier-1 suppliers consolidating gun purchasing across multiple stamping facilities.
United States
FAA airworthiness directives for structural joint certification constrain adaptive controller design in aerospace applications. OSHA workplace exposure limits for hexavalent chromium fume drive integrated extraction system demand. The Pacific Northwest and Midwest manufacturing corridors anchor MRO facility modernization for turbine blade repair.
China
MIIT industrial automation targets accelerate robotic welding deployment in automotive stamping operations. Dual carbon goals tighten emissions standards for shielding gas consumption in fabrication shops. The Yangtze River Delta and Pearl River Delta concentrate EV battery enclosure assembly lines qualifying friction stir alternatives.
Japan
METI Industry 4.0 subsidies support cloud-connected gun controller adoption in precision metalworking. JIS standards for arc monitoring equipment shape R&D allocation toward predictive maintenance platforms. The Nagoya automotive corridor and Osaka fabrication hub sustain demand for high-duty-cycle MIG systems.
Poland
Central European metalworking clusters modernize aging manual fleets with semi-automatic and automatic systems. EU cohesion funds finance equipment upgrades in post-industrial regions. The Silesian and Greater Poland voivodeships present first-mover advantage for vendors offering Polish-language HMI interfaces and localized service networks.
Welding Guns Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the welding guns landscape. The market structure fragments across three tiers: integrated industrial conglomerates with captive robotics divisions, specialized welding equipment manufacturers with dense service networks, and regional fabricators competing on price for standard manual systems. Strategic archetypes include full-stack automation providers, precision consumables specialists, and emerging digital controller developers. Competitive moves center on backward integration into electrode alloy production and technology licensing partnerships for adaptive arc control algorithms.
Among European-based specialists, Fronius International and EWM AG exemplify the precision-engineering archetype with Austrian and German origins respectively. Panasonic occupies a position representing the integrated industrial conglomerate model, anchoring the robotics-automation convergence vector. Lincoln Electric and Miller Electric sit within the North American fabrication equipment tier, with the former exemplifying vertical scope from wire feed systems to gun hardware. ESAB represents the service-network archetype with established logistics across European fabrication hubs.
| Leading Market Players |
|---|
| Fronius International |
| Panasonic |
| Lincoln Electric |
| EWM AG |
| KUKA |
| Miller Electric |
| Illinois Tool Works |
| ARO Technologies |
| ESAB |
| Others |
Value Network & Pricing Analysis
Thirty-to-forty-five-day lead times for copper-chromium-zirconium electrode alloys from Chilean concentrates now govern contract negotiations between gun manufacturers and automotive OEMs, compressing margin buffers when LME price spikes coincide with fixed-price annual agreements. This inventory-to-pricing coupling forces fabricators to choose between premium sourcing security and spot-market exposure that amplifies cost volatility across European stamping operations.
Pricing Analysis
German automotive OEMs pay 15-25% premiums over Polish fabrication shops for identical MIG gun specifications, reflecting after-sales service bundling and EN ISO 9606 certification support. Three-tier pricing structure across premium, standard, and economy levels separates robotic integration packages from manual replacement hardware. Cost compression in economy-tier manual systems is intensifying because Chinese imports flood Central European distributor channels. Tier-1 automotive suppliers exhibit lowest price sensitivity due to uptime guarantee requirements, while independent job shops in Silesian metalworking clusters drive hardest bargain on spare parts contracts.
Supply Chain Analysis
Container availability constraints on Hamburg-Rotterdam trade lanes inflate inbound logistics costs for Japanese and Korean controller components, forcing safety-stock builds that tie up working capital. Electrode holder fabrication draws from copper concentrates in Chile and Peru, with contact tip machining concentrated in Germany and China. Supply chain risk centers on single-source vulnerability for high-purity tungsten electrodes used in aerospace TIG applications. Distribution runs through authorized service networks for robotic systems, while manual guns flow through distributor retail channels with minimal technical attachment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified robotic welding technicians capable of programming adaptive arc controllers now represent the scarcest production asset in German automotive corridors, constraining deployment velocity regardless of capital availability. This capability gap favors vendors who bundle training certification with hardware contracts.
For Market Incumbents: Compound technology leadership in digital arc controllers by acquiring Polish-language HMI software specialists before competitors lock up Central European modernization contracts. Prioritize backward integration into copper-chromium-zirconium electrode production to buffer margin compression from Chilean concentrate price swings. Defensive moves must counter friction stir welding displacement in EV battery enclosure applications by embedding hybrid process compatibility into next-generation gun platforms. For New Entrants and Emerging Players: EN ISO 9606 fast-track certification partnerships with Bavarian technical institutes open immediate access to automotive line expansion projects stalled by operator qualification backlogs. Polish and Czech fabrication hubs present most penetrable geography, with Soviet-era equipment fleets requiring complete replacement rather than incremental upgrade. Go-to-market angle should emphasize localized spare parts logistics and Polish-speaking field service engineers, matching ESAB's network density at lower cost structure. For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates divesting non-core welding divisions amid portfolio rationalization pressures. Five-to-ten-year viability hinges on software-enabled service contract attachment rates overtaking hardware margin pools. Signal to monitor: adoption velocity of subscription-based uptime guarantees among Tier-1 automotive suppliers, indicating shift from transactional to recurring revenue models.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrode Alloys | Captive supply of copper-chromium-zirconium reduces exposure to Chilean concentrate price volatility. |
| Adaptive Controller Certification Fast-Track | EN ISO 9606 partnership accelerates deployment velocity for automotive line expansions in Stuttgart. |
| Polish-Language HMI Localization | Interface customization unlocks first-mover advantage in Silesian and Greater Poland voivodeships. |
| Friction Stir Welding Compatibility Layer | Hybrid process support defends against solid-state joining displacement in BMW battery enclosure specifications. |
| Predictive Maintenance Platform Launch | Current signature analysis shifts margin pools from hardware sales to subscription uptime guarantees. |
Research Methodology
Desk research of EU F-Gas regulatory filings, SEC 10-K disclosures from industrial equipment manufacturers, and automotive production databases preceded structured interviews with robotic welding line engineers, aftermarket service directors, and procurement leads at Tier-1 stamping suppliers. Primary fieldwork captured deployment timelines for EV platform welding lines across Germany's manufacturing belt. Secondary validation drew from customs trade data on copper concentrate flows and EN ISO certification body statistics. Bottom-up equipment unit estimates triangulated against top-down automotive production forecasts.
Variance decomposition across product type, technology tier, application segment, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from regression against automotive capital expenditure cycles and EV platform ramp schedules. Industry-specific forecast inputs included robotic welding line density ratios for electric versus combustion platforms, and friction stir welding penetration rates in battery enclosure assembly.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal enforcement and stable Chilean copper concentrate export volumes; material deviation would warrant model refresh. Specific risk factors include accelerated friction stir welding adoption, MIIT automation subsidy suspensions in China, and OSHA hexavalent chromium standard tightening. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Hydraulic Torque Wrench Market
Tools
Global Staple Gun Market
Tools
Global Tool Holder Adapters Market
Tools
Ultra Hard Material Cutting Machines Market
Tools
Tape Measure Market
Tools
Tool Pliers Market
Tools
Striking Tools Market
Tools
Digital Cutting Machine Market
Tools
L Allen Wrench Market
Tools
Global Cordless Power Tools Market
Tools
Technical Drawing Tools Market
Tools
Rotary Knife Cutters Market
Tools
Broaching Tools Market
Tools
Global Protractor Market
Tools
Cordless Long Neck Grinder Market
Tools
Total Station Market