
 Bandsaw Market | 2026-2036
Bandsaw Market Size, Share, and Industry Trends Forecast 2026-2036
Bandsaw Market Analytics
Buyer concentration across metalworking job shops is broadening as mid-sized fabricators replace aging equipment rather than rely on outsourced cutting services. Kalamazoo sustains strong brand recognition among North American maintenance departments through durable horizontal machine lines. WIKUS dominates specialized blade supply for European precision metalworking customers. Starrett differentiates through metrology-integrated cutting solutions that appeal to quality-critical manufacturers.
A bandsaw is a power tool employing a continuous looped blade with teeth along one edge to cut material via controlled feed pressure, typically operating at blade speeds between 40 and 15,000 surface feet per minute depending on workpiece composition. Horizontal bandsaw configurations occupy the largest installed base in industrial metalworking due to efficient gravity-fed cutting of structural sections and bar stock. Portable electric units represent the fastest-expanding product category as on-site construction and demolition contractors prioritize mobility over fixed-shop throughput. Woodworking applications remain mature with replacement-driven demand, while fabrication end users generate the strongest margin pools through consumable blade attachments and service contracts.
OSHA machine guarding standards and EU machinery directive CE marking requirements shape product design cycles and aftermarket retrofit demand across North America and Europe. China's GB standards for metal-cutting equipment and Japan's JIS certification protocols create additional compliance layers for exporters serving Asian manufacturing clusters. Stakeholders must monitor how evolving carbon-footprint disclosure rules under the EU Green Deal affect energy-intensive cutting equipment procurement criteria.
Market Dynamics
Machine replacement cycles in metalworking job shops are compressing as dual pressures from OSHA machine guarding enforcement and EU machinery directive compliance force capital deployment toward certified equipment rather than extended maintenance of aging assets.
Growth Catalysts
- OSHA machine guarding mandates:US metal fabricators face stepped-up inspection protocols for horizontal bandsaw guarding systems, accelerating equipment turnover in Great Lakes manufacturing corridors.
- Automotive component reshoring:Precision cutting demand from EV battery tray and structural component suppliers in Germany and Japan is pulling high-accuracy blade systems into expanded production lines.
- Carbide-tipped blade advancement:Extended cutting intervals from advanced tooth geometries reduce downtime costs for high-volume structural steel processors.
Market Restraints
- Alloy steel input volatility:Bi-metal blade substrate costs fluctuate with nickel and cobalt spot markets, squeezing margin predictability for consumable suppliers.
- CE marking compliance burden:European machinery directive documentation requirements extend product development timelines by four to eight months for non-EU exporters.
- Plasma cutting substitution:Thick-section metal processors above six-inch stock increasingly adopt plasma arc systems for speed advantages in non-precision applications.
Strategic Opportunities
- EU Green Deal procurement criteria:Energy disclosure mandates for industrial equipment create positioning advantages for variable-frequency drive bandsaw systems in public tender processes.
- India PLI scheme metalworking:Production-linked incentives for capital goods manufacturing attract blade and machine assembly investments serving domestic fabrication growth.
- IoT-enabled predictive maintenance:Blade wear sensors integrated with shop-floor management systems open recurring revenue streams through subscription-based consumable replenishment.
Industry Challenges
- CNC programming skill scarcity:Automated feed and angle control systems require operators trained in G-code adaptation, a competency gap acute in smaller US job shops.
- Legacy hydraulic system integration:Retrofitting digital control interfaces onto existing gravity-fed horizontal machines creates compatibility failures and extended commissioning periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bandsaw Market |
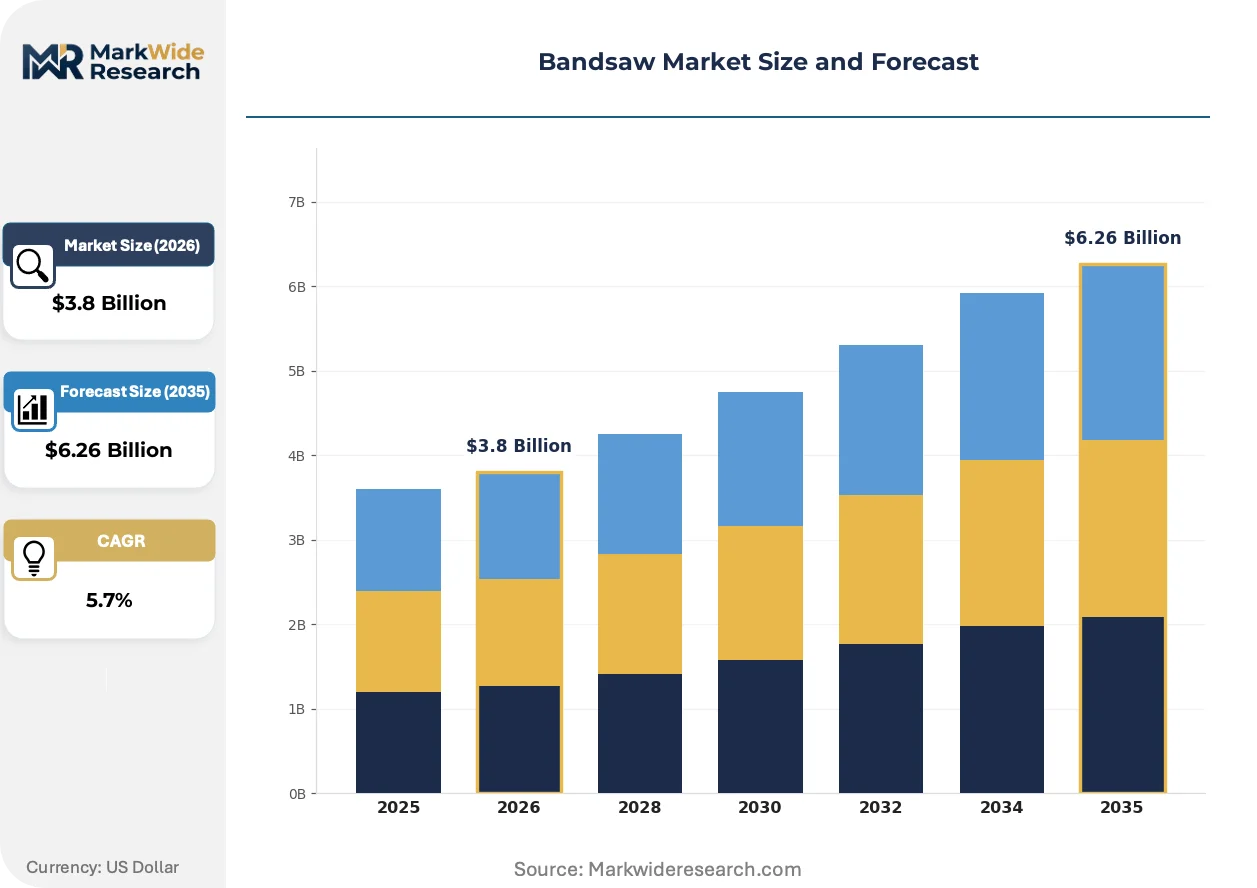
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Bandsaws, Vertical Bandsaws, Horizontal Bandsaws, Band Resaws Application: Woodworking, Metalworking, Construction, Fabrication End User: Manufacturers, Contractors, DIY Enthusiasts, Artisans Technology: Electric, Hydraulic, Pneumatic, Manual |
| Companies Covered | Kalamazoo, Morris, BAND-IT, Starrett, Parker, DoAll, Meyer, WIKUS, Hawker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bandsaw Market Evolving Landscape
Battery-powered portable bandsaw units are redrawing competitive boundaries between fixed-shop equipment and field-capable cutting tools, forcing established manufacturers to defend installed bases against mobility-first entrants.
Brushless DC motor architecture is decentralizing power delivery assumptions in portable cutting equipment. Construction contractors and demolition crews operating in Germany and Japan adopt cordless units for steel reinforcement cutting without generator tethering. This technology is decentralizing the traditional shop-floor versus job-site equipment segmentation that has structured distribution channels for decades.
The EU Green Deal carbon-footprint disclosure rules are reshaping procurement evaluation frameworks for energy-intensive metal-cutting equipment. Large automotive tier-one suppliers now require documented kWh-per-cut metrics in supplier qualification questionnaires. German and French fabricators respond by specifying variable-speed drive systems that reduce no-load energy consumption during batch changeovers.
Job shops increasingly unbundle blade supply from original equipment manufacturer capture. Direct procurement from specialized blade producers through industrial distributors displaces captive aftermarket programs. This pattern concentrates most visibly among mid-sized US fabricators in Ohio and Michigan who negotiate volume contracts with WIKUS and Starrett distributors rather than accepting OEM-specified consumable packages.
Bandsaw Market Segmentation
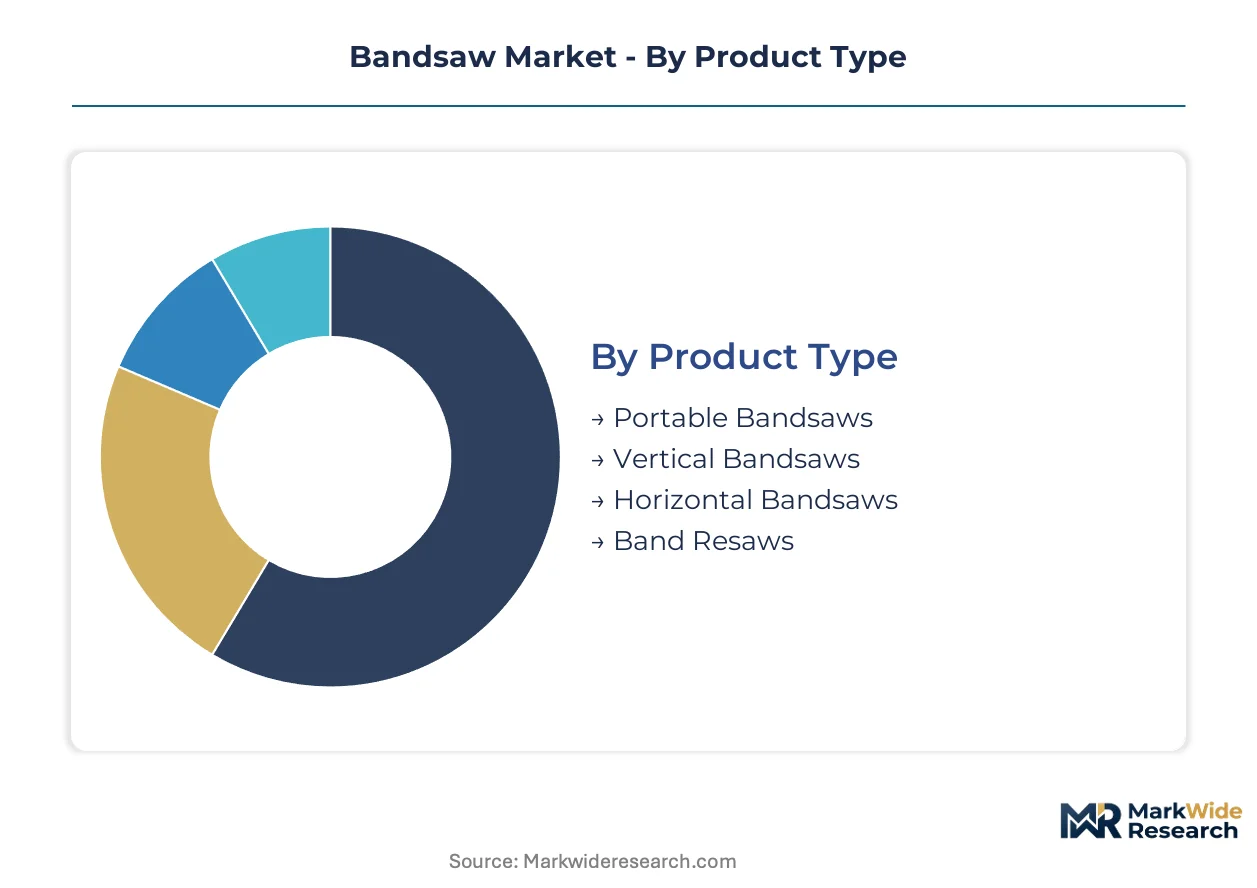
Equipment configuration and power source selection determine capital allocation patterns across metalworking job shops and construction sites. Segmentation reveals where standardization yields procurement efficiency versus where application-specific customization commands price premiums.
Product Type:
The customization-to-standardization spectrum runs from purpose-built industrial systems to interchangeable portable units that cross multiple job sites.
- Horizontal Bandsaws:Gravity-fed cutting platforms dominate structural steel and bar stock processing with fixed beds and adjustable vises. Metal fabrication facilities in Germany and the United States anchor installed capacity for this configuration amid OSHA machine guarding enforcement and EU machinery directive compliance cycles.
- Portable Bandsaws:Cordless brushless DC motor units are redrawing competitive boundaries between fixed-shop and field-capable cutting tools. Construction contractors operating in Japan and demolition crews across Germany adopt battery-powered systems for steel reinforcement cutting without generator tethering.
- Vertical Bandsaws:Stationary floor-standing machines with table-mounted workpiece positioning serve contour cutting and resawing applications in custom woodworking shops.
- Band Resaws:High-capacity timber processing systems with wide kerf blades handle primary breakdown of lumber stock in sawmill operations.
Most installed capacity flows through Horizontal Bandsaws. Expansion is steepest in Portable Bandsaws.
Application:
Cost tier stratification separates precision fabrication from rough-cut construction work, with blade consumable economics driving total cost of ownership calculations.
- Metalworking:Precision cutting of structural sections, tubing, and solid stock with carbide-tipped or bi-metal blades operating at controlled feed rates. EV battery tray suppliers in Japan and automotive component fabricators in Germany pull high-accuracy blade systems into expanded production lines.
- Fabrication:Job shop environments mixing batch production of custom metal components with variable material specifications. Mid-sized US fabricators in Ohio and Michigan increasingly unbundle blade supply from OEM capture through direct procurement from specialized distributors.
- Woodworking:Mature replacement-driven demand for primary and secondary timber processing in furniture manufacturing and millwork operations.
- Construction:Field-deployed cutting of structural steel, reinforcement bar, and demolition scrap with priority on portability over precision tolerances.
Margin pools concentrate in Metalworking through consumable blade attachments and service contracts. Fabrication climbs fastest as job shops replace aging equipment rather than rely on outsourced cutting services.
End User:
Customer type determines volume scale and support service intensity, from high-maintenance industrial accounts to price-sensitive occasional users.
- Manufacturers:Tier-one automotive suppliers and OEM production facilities with integrated cutting operations requiring documented kWh-per-cut metrics under EU Green Deal procurement criteria.
- Contractors:Construction and demolition firms prioritizing equipment mobility and rapid blade changeover for on-site steel processing.
- Artisans:Custom furniture makers and metal artists requiring precision control for prototype and limited-series production runs.
- DIY Enthusiasts:Hobbyist woodworkers and home shop operators driving entry-level portable electric unit sales through retail distribution.
Service revenue attaches most densely to Manufacturers. Contractor segment expansion outpaces other categories as on-site cutting displaces shop-based preprocessing.
Technology:
Power delivery architecture separates legacy hydraulic systems from electrification trends reshaping both fixed and portable equipment categories.
- Electric:AC induction and brushless DC motor systems ranging from fixed-shop three-phase installations to battery-powered portable units. Variable-frequency drive configurations reduce no-load energy consumption during batch changeovers for German and French fabricators responding to carbon-footprint disclosure rules.
- Hydraulic:Pressure-fed cutting systems in heavy-duty industrial horizontal machines requiring maintenance-intensive fluid power infrastructure.
- Pneumatic:Compressed-air powered units for explosive atmosphere environments and specific industrial safety protocols.
- Manual:Hand-cranked or foot-powered bandsaws for remote operations and educational woodworking programs.
Electric systems carry the majority of installed base. Brushless DC portable architectures gain share fastest as cordless performance converges with corded capability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United States operate divergent equipment procurement rhythms despite similar regulatory intensity, while Japan and China pull precision blade systems into automotive supply chains at contrasting velocity scales.
United States
Metalworking job shops in Ohio and Michigan compress replacement cycles amid stepped-up OSHA machine guarding enforcement. The Department of Labor inspection protocols target horizontal bandsaw guarding systems specifically. Fabrication clusters around Cleveland and Detroit accelerate capital deployment toward certified equipment rather than extended maintenance of aging assets.
Germany
Automotive component reshoring pulls high-accuracy blade systems into expanded EV battery tray production lines. EU machinery directive CE marking requirements extend product development timelines for non-EU exporters serving German manufacturers. Precision metalworking facilities in Stuttgart and Munich specify variable-frequency drive systems to meet carbon-footprint disclosure rules under the EU Green Deal.
Japan
EV structural component suppliers in Nagoya and Osaka integrate advanced carbide-tipped blade geometries for extended cutting intervals. METI certification protocols and JIS standards create compliance layers for equipment exporters. Construction contractors across Tokyo and Yokohama adopt cordless brushless DC portable units for steel reinforcement cutting without generator tethering.
China
GB standards for metal-cutting equipment govern procurement criteria for automotive tier-one suppliers in Shanghai and Shenzhen. Domestic fabrication growth attracts blade and machine assembly investments serving precision cutting demand. Yangtze River Delta manufacturing clusters prioritize documented energy metrics in supplier qualification questionnaires aligned with dual carbon goals.
India
Production-linked incentive schemes for capital goods manufacturing draw equipment assembly investments serving domestic metalworking expansion. Maharashtra and Gujarat fabrication facilities replace aging equipment rather than rely on outsourced cutting services. Mumbai and Pune job shops negotiate volume contracts with specialized blade distributors rather than accepting OEM-specified consumable packages.
Bandsaw Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across equipment configuration and consumable supply tiers. The vendor base organizes around three strategic archetypes: industrial machinery conglomerates with broad cutting portfolios, specialized blade manufacturers with metallurgical expertise, and portable equipment innovators exploiting cordless electrification trends. Competitive moves concentrate on geographic expansion through distributor network densification and technology licensing arrangements for brushless motor architectures.
Among North American maintenance-focused fabricators, Kalamazoo and DoAll occupy positions within the industrial horizontal machine tier, while WIKUS anchors the specialized blade supply archetype for European precision metalworking customers. Starrett exemplifies the metrology-integrated positioning that appeals to quality-critical manufacturers requiring documented cutting tolerances.
| Leading Market Players |
|---|
| Kalamazoo |
| Morris |
| BAND-IT |
| Starrett |
| Parker |
| DoAll |
| Meyer |
| WIKUS |
| Hawker |
| Others |
Value Network & Pricing Analysis
EU Green Deal carbon-footprint disclosure rules gate qualified supply and premium-tier pricing access for energy-intensive cutting equipment, forcing German and French fabricators to specify variable-frequency drive systems while excluding non-compliant vendors from public tender processes. This environmental mandate stratifies the supplier base between documented low-kWh-per-cut providers and legacy equipment manufacturers facing margin compression.
Pricing Analysis
Capacity additions in India are reshaping price floors for standard horizontal bandsaw configurations as production-linked incentive schemes attract assembly investments serving domestic metalworking expansion. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked variable-frequency drive systems from fixed-speed alternatives and entry-level portable units. Price differentiation rests on certification grade and after-sales service bundling, with OEM-captive blade packages commanding premiums over direct-procurement arrangements. Cost compression in economy-tier portable units is intensifying because brushless DC motor commoditization erodes hardware margins. DIY enthusiasts and occasional-use contractors exhibit highest price sensitivity, while tier-one automotive suppliers prioritize documented energy metrics over unit cost.
Supply Chain Analysis
Workforce availability constraints in Germany, Japan, and the United States limit expansion velocity for precision blade manufacturing and CNC-equipped machine assembly. Supply concentrates most heavily in Germany for specialized carbide-tipped blade production, China for bi-metal substrate forging and battery-powered portable unit assembly, and the United States for horizontal machine fabrication serving Great Lakes metalworking corridors. Raw material dependencies center on nickel and cobalt spot markets for bi-metal blade substrates, alloy steel bar stock for machine frames, and lithium-ion cells for cordless portable architectures. Single-source vulnerability in cobalt supply from the Democratic Republic of Congo exposes blade manufacturers to input cost volatility. Distribution runs through industrial equipment distributors with aftermarket service capabilities, though direct procurement patterns are displacing OEM-captive channels among mid-sized fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU machinery directive compliance costs in Germany and France exceed OSHA enforcement burdens in the United States, creating cost-structure advantages for North American equipment exporters serving price-sensitive segments.
For Market Incumbents: Anticipate plasma cutting substitution above six-inch stock by accelerating carbide-tipped blade advancement for precision applications where speed disadvantages are irrelevant. Defend installed bases against mobility-first entrants through backward integration into brushless DC motor architectures and variable-frequency drive system certification investments that satisfy EU Green Deal procurement criteria. For New Entrants and Emerging Players: Battery-powered portable units with brushless DC motor architecture offer a technology-first wedge into Japanese construction contractor segments where generator-tethered cutting creates field-deployment friction. Target on-site steel reinforcement cutting for demolition crews and infrastructure maintenance teams in Germany and Japan through distributor partnerships with industrial supply houses serving contractor mobility priorities. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized blade manufacturers with metallurgical expertise but limited geographic diversification beyond European precision metalworking clusters. Long-term viability over a five-to-ten year horizon hinges on unbundling resistance from OEM-captive aftermarket programs and IoT-enabled predictive maintenance subscription traction. Monitor blade wear sensor integration adoption rates among tier-one automotive suppliers as the inflection signal for recurring revenue model validation.| Strategic Initiative | Industry Significance |
|---|---|
| Variable-Frequency Drive Certification | CE marking and EU Green Deal compliance unlock premium-tier public tender access for German fabricators. |
| Backward Integration into Blade Metallurgy | In-house carbide-tipped production reduces nickel and cobalt spot market exposure for consumable suppliers. |
| IoT-Enabled Predictive Maintenance Launch | Blade wear sensors integrated with shop-floor management systems create subscription revenue from automotive tier-ones. |
| Battery-Powered Portable Expansion | Brushless DC cordless units penetrate Japanese demolition contractor segments without generator infrastructure. |
| Direct Procurement Channel Development | Volume contracts with Ohio and Michigan fabricators displace OEM-captive blade supply arrangements. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads with secondary validation against customs and trade data, SEC filings from diversified industrial machinery conglomerates, OSHA enforcement disclosure databases, and EU machinery directive CE marking registries. Bottom-up equipment shipment tracking and top-down fabrication capacity estimates were triangulated against blade consumable volume flows.
Segment-weighting approaches modeled horizontal versus portable versus vertical configuration splits, metalworking versus fabrication versus woodworking application tiers, and electric versus hydraulic versus pneumatic technology architectures across the projection horizon. CAGRs were derived from equipment replacement cycle compression rates and consumable attachment ratios by end-user category, with forecast inputs incorporating OSHA inspection protocol intensification timelines and EU Green Deal procurement criteria adoption curves among automotive tier-one suppliers.
The model holds under sustained regulatory enforcement in North America and Europe and stable alloy steel input costs; deviation in nickel and cobalt spot market volatility or plasma cutting technology cost reduction would shift equipment-versus-substitution economics. Material deviation in these triggers warrants pause and re-evaluation of capital deployment assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Portable Boring Machines Market
Tools
Industrial Ladder Market
Tools
Multi Wire Cutting Machine Market
Tools
Forging Press Market
Tools
Global Tool Holder Adapters Market
Tools
Woodworking Tools Market
Tools
Engraver Machine Market
Tools
Clamps Market
Tools
Tension Tester Market
Tools
Auger Drill Bits Market
Tools
Floor Scraper Market
Tools
Sand Control Tools Market
Tools
Coil Fed Punching and Cutting Machines Market
Tools
Automatic Lathe Machines Market
Tools
Cordless Impact Wrench Market
Tools
Rotary Tools Market