
 Vibratory Rammer Market | 2026-2036
Vibratory Rammer Market Size, Share, and Industry Trends Forecast 2026-2036
Vibratory Rammer Market Analysis
Modular attachment systems and configurable engine packages are broadening buyer choice in the vibratory rammer market. Wacker Neuson leverages its German manufacturing base to sustain premium positioning across European rental channels. Bomag GmbH anchors compaction technology leadership through deep specialization in oscillating drum integration. Mikasa Sangyo competes aggressively on portability and operator ergonomics across Asian construction markets.
A vibratory rammer is a compaction machine that uses reciprocating piston or eccentric weight mechanisms to generate high-frequency, low-amplitude impacts typically delivering 10-14 kN of centrifugal force to densify cohesive and semi-cohesive soils. Its primary industrial purpose is achieving specified Proctor densities in confined trenches, foundation footings, and backfill zones where larger rollers cannot maneuver. Gasoline rammers retain the largest installed base due to power-to-weight ratios and field refueling convenience, though electric variants are gaining fastest in urban utility work where emissions restrictions tighten. Spring-loaded technology dominates rental fleets for durability, while double-acting designs command margin premiums in railway maintenance contracts requiring higher blow frequencies.
EPA Tier 4 Final emissions standards and OSHA noise exposure limits in the United States compel engine redesigns and muffler investments that filter weaker suppliers from the market. The EU Green Deal and REACH chemical compliance add material disclosure burdens to European manufacturers sourcing cast components and anti-vibration mounts. Stakeholders must monitor battery energy density improvements and fast-charging infrastructure buildout to determine when electric rammers displace gasoline units in high-duty-cycle applications.
Market Dynamics
EPA Tier 4 Final emissions standards and OSHA noise exposure limits are forcing engine redesigns that filter weaker suppliers from the vibratory rammer market. Equipment rental fleets now prioritize spring-loaded durability over raw blow frequency.
Growth Catalysts
- Urban utility trenching:Dense commercial construction in Germany and the United States demands compact compaction equipment for confined foundation footings where rollers cannot maneuver.
- REACH chemical compliance:European material disclosure requirements accelerate cast component traceability investments among German manufacturers serving infrastructure renewal contracts.
- Battery energy density improvements:Fast-charging infrastructure buildout in urban construction zones enables electric rammers to penetrate high-duty-cycle applications previously reserved for gasoline units.
Market Restraints
- Cast component supply concentration:Anti-vibration mount sourcing depends on a limited supplier base concentrated in German industrial clusters, exposing procurement to regional disruption.
- Engine redesign capex:Tier 4 Final muffler investments and aftertreatment systems raise unit costs for gasoline rammers, compressing margins on standard fleet configurations.
- Electric range limitations:Battery thermal management constraints restrict continuous operation duration in summer railway maintenance contracts requiring sustained blow frequencies.
Strategic Opportunities
- Modular attachment systems:Configurable engine packages allow rental fleets to standardize chassis while swapping power units between gasoline, diesel, and electric variants.
- Indian infrastructure buildout:National highway expansion and urban metro projects create untapped demand for portable compaction equipment in semi-cohesive soil conditions.
- EU Green Deal procurement mandates:Public works contracts increasingly specify zero-emission equipment for urban utility work, advantaging early electric rammer adopters.
Industry Challenges
- Skilled technician scarcity:Oscillating drum integration and electronic fuel injection diagnostics require specialized training that rental fleet maintenance departments struggle to staff.
- Certification timeline compression:CE marking updates and EPA engine family approvals now run in parallel, extending new product introduction cycles by 8-14 months.
- Legacy fleet integration:Electric rammers require charging infrastructure incompatible with established gasoline refueling logistics at decentralized construction sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vibratory Rammer Market |
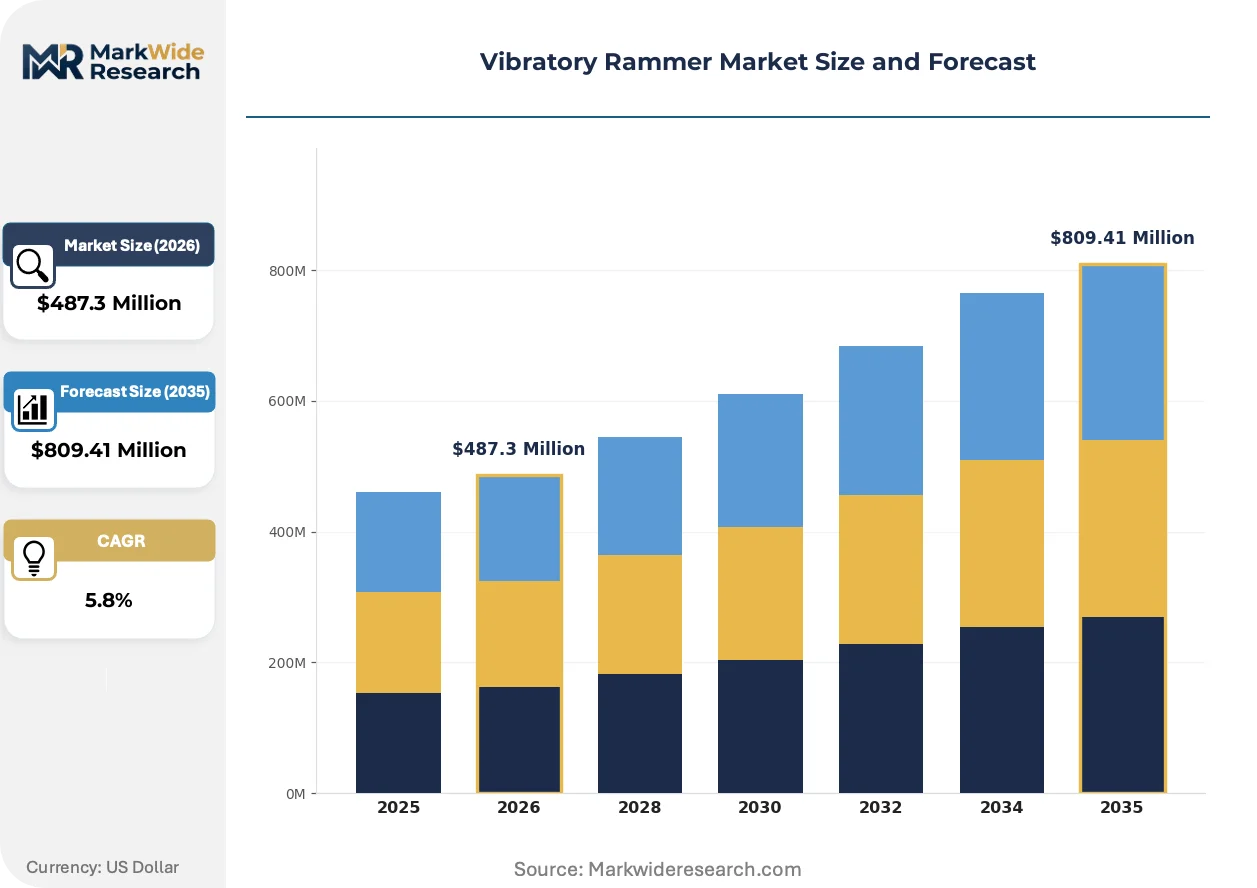
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gasoline Rammer, Diesel Rammer, Electric Rammer, Hydraulic Rammer Technology: Single-acting, Double-acting, Spring-loaded, Pneumatic Application: Road Construction, Foundation Compaction, Trench Compaction, Railway Maintenance End User: Construction Contractors, Civil Engineers, Infrastructure Firms, Utility Providers |
| Companies Covered | Wacker Neuson, Ammann Group, Weber MT, JCB, Toro Company, Mikasa Sangyo, Bomag GmbH, Atlas Copco, Multiquip Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vibratory Rammer Market Emerging Trajectories
Powertrain electrification and smart compaction telemetry are restructuring how contractors specify and deploy vibratory rammers across urban and remote job sites. Equipment intelligence now extends beyond hour meters to real-time density feedback.
Lithium iron phosphate battery packs are decentralizing fleet energy logistics by enabling on-site solar charging at remote trenching locations. Railway maintenance contractors in Germany adopt these systems fastest, replacing diesel refueling convoys with containerized charging stations. The shift compresses operating cost structures and reduces supply chain exposure to volatile fuel logistics.
OSHA noise exposure limits are compelling muffler redesigns that add mass without sacrificing power-to-weight ratios. Contractors in the United States face stricter enforcement of 85 dB eight-hour exposure thresholds, pushing rental fleets toward spring-loaded isolation systems. Equipment spec sheets now lead with decibel ratings rather than centrifugal force figures.
Rental channel consolidation is compressing manufacturer sales cycles as national fleet managers centralize procurement decisions. Independent dealers in the United States lose ground to direct OEM relationships with multi-state rental houses. The shift concentrates volume with fewer buyers who demand standardized telematics protocols across mixed equipment fleets.
Vibratory Rammer Market Segmentation
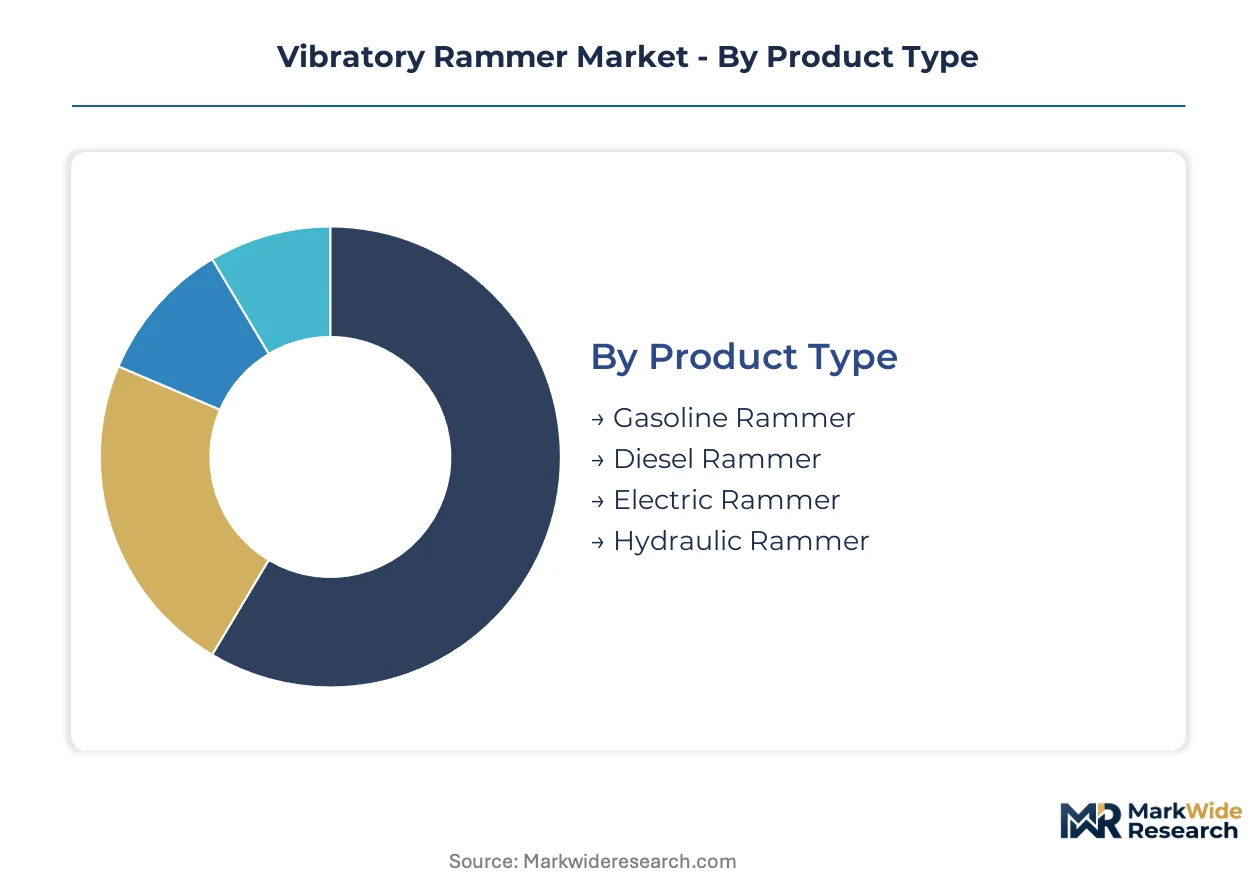
Vibratory rammer segmentation reveals how powertrain choices, compaction mechanisms, and end-use requirements fragment procurement patterns across construction verticals. Contractors specify equipment based on site access constraints, emissions regulations, and soil composition rather than generic performance metrics.
Product Type:
Integration depth varies sharply: gasoline and diesel rammers operate as standalone units with field refueling autonomy, while electric variants embed into charging infrastructure networks that reshape site logistics.
- Gasoline Rammer:Two-stroke and four-stroke engines deliver 10-14 kN centrifugal force with superior power-to-weight ratios for remote trenching without grid access. Demand concentrates in United States foundation compaction where EPA Tier 4 Final compliance costs filter marginal suppliers from rental fleet procurement.
- Diesel Rammer:Compression-ignition powertrains sustain continuous operation in high-duty-cycle railway maintenance with better fuel efficiency than gasoline equivalents. German infrastructure renewal contracts specify these units for heavy clay compaction where torque characteristics outweigh emissions penalties.
- Electric Rammer:Battery-powered units eliminate exhaust emissions for urban utility work under tightening municipal restrictions.
- Hydraulic Rammer:Carrier-mounted systems integrate with excavator auxiliaries for large-scale earthworks requiring sustained blow frequencies.
Gasoline rammers lead volumes today; electric rammers are gaining share fastest.
Technology:
Cost tier differentiation separates premium double-acting designs from standard spring-loaded configurations that dominate rental fleet specifications.
- Single-acting:Piston-driven impact mechanisms deliver one blow per engine cycle at lower manufacturing cost, saturating emerging market procurement in India where highway expansion prioritizes unit economics over blow frequency precision.
- Double-acting:Compressed air or hydraulic assist accelerates piston return for higher impacts per minute, commanding margin premiums in Japanese railway ballast compaction where specification density tolerances are tightest.
- Spring-loaded:Mechanical isolation systems reduce hand-arm vibration transmission for operator safety compliance.
- Pneumatic:Compressed air power eliminates combustion emissions for underground mining and tunneling applications with ventilation constraints.
Spring-loaded technology holds the largest installed base; double-acting designs climb the fastest in specification-sensitive contracts.
Application:
Geographic concentration of infrastructure investment determines which compaction scenarios absorb equipment volumes.
- Road Construction:Sub-base and shoulder compaction for asphalt paving operations requires rammers for edge work where rollers cannot reach. United States federal highway funding cycles drive replacement demand in state transportation departments.
- Foundation Compaction:Building footing and slab preparation in dense urban zones absorbs the highest equipment density per square kilometer of construction activity. German commercial building permits correlate directly with rammer rental fleet utilization rates.
- Trench Compaction:Utility backfill densification for water, gas, and electrical infrastructure employs portable units in confined excavations.
- Railway Maintenance:Ballast tamping and track bed stabilization demand specialized high-frequency units with reinforced frames.
Foundation compaction leads volumes today; trench compaction expands most quickly with urban utility buildout.
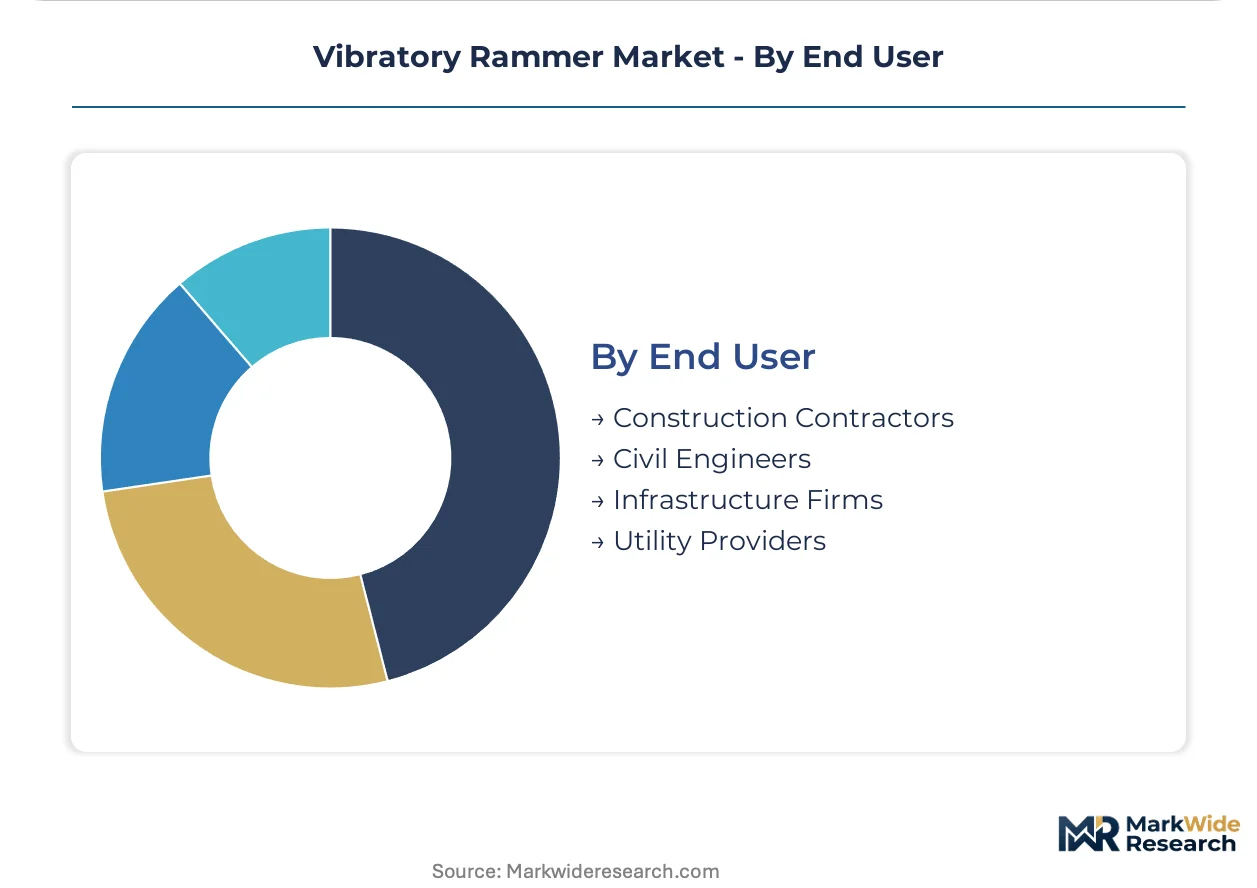
End User:
Customer type segmentation tracks procurement sophistication from decentralized contractor purchases to centralized fleet management.
- Construction Contractors:Small-to-mid-sized builders purchase or rent rammers for project-specific foundation and trench work. United States residential construction volatility creates boom-bust equipment utilization patterns that favor rental over ownership.
- Civil Engineers:Specification authority in public works contracts drives technology adoption through performance-based procurement criteria. German state infrastructure agencies mandate telematics integration for equipment visibility.
- Infrastructure Firms:National contractors maintain captive fleets for multi-year highway and rail projects with predictable utilization.
- Utility Providers:Water, electricity, and telecommunications operators deploy rammers for emergency repair and planned network expansion in urban rights-of-way.
Construction contractors lead volumes today; utility providers are gaining share fastest with grid modernization mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering traditions established vibratory rammer manufacturing excellence during post-war infrastructure reconstruction. Wacker Neuson and Bomag GmbH scaled production from Bavarian and North Rhine-Westphalian facilities to serve European compaction equipment demand. Manufacturing clusters in Munich and Boppard still anchor continental supply chains for railway maintenance and foundation construction equipment.
Germany
Bavarian manufacturers supply oscillating drum technology for railway ballast stabilization contracts across the Rhine-Ruhr corridor. EU Green Deal procurement mandates now require zero-emission equipment specifications for urban utility projects in Berlin and Hamburg. The Boppard industrial cluster concentrates casting expertise for anti-vibration mount components serving infrastructure renewal programs.
United States
Federal highway funding cycles drive state transportation department replacement demand for trench compaction equipment. EPA Tier 4 Final emissions standards compel muffler redesign investments that filter marginal gasoline rammer suppliers from rental fleet procurement. Equipment distribution concentrates through Midwest rental houses serving Chicago and Detroit construction markets.
Japan
Ballast tamping specifications for Shinkansen maintenance demand high-frequency double-acting rammer configurations with precise density tolerances. METI industrial standards govern hand-arm vibration exposure limits for operator safety compliance. Osaka-based fabricators specialize in portable compaction equipment for seismic retrofit foundation work in dense urban zones.
India
National highway expansion and metro rail construction create demand for cost-optimized single-acting rammers in semi-cohesive Deccan Plateau soils. BIS certification requirements for construction machinery safety accelerate formalization of previously fragmented equipment supply. Manufacturing activity clusters around Pune and Chennai serving contractor procurement for infrastructure buildout.
China
Urban subway construction absorbs electric rammers for tunnel ventilation compliance where combustion emissions face strict MEE enforcement. Dual carbon goals accelerate battery-powered equipment substitution in Beijing and Shanghai municipal contracts. Yangtze River Delta fabricators scale production for domestic rail maintenance and Southeast Asian export markets.
Vibratory Rammer Market Vendor Landscape
Premium-margin players sit above commodity-margin players across technology specialization and rental channel access. The vendor base organizes into three tiers: oscillating drum specialists commanding specification-sensitive railway contracts, spring-loaded durability leaders dominating rental fleet standardization, and regional fabricators competing on unit economics in emerging markets. Consolidation pressure intensifies as national rental houses centralize procurement decisions and demand standardized telematics protocols. Strategic moves concentrate on modular attachment systems and charging infrastructure partnerships for electric variants.
Among German-based specialists, Wacker Neuson and Bomag GmbH occupy positions anchoring European premium-tier supply. Mikasa Sangyo represents the portability-focused archetype competing across Asian construction markets. These three exemplify how geographic manufacturing heritage translates into distinct competitive positioning without requiring overlapping customer segments or technology portfolios.
| Leading Market Players |
|---|
| Wacker Neuson |
| Ammann Group |
| Weber MT |
| JCB |
| Toro Company |
| Mikasa Sangyo |
| Bomag GmbH |
| Atlas Copco |
| Multiquip Inc. |
| Others |
Supply Flow & Price Mechanics
Rental fleet consolidation across the United States and Germany is forcing manufacturers to absorb Tier 4 Final muffler costs while standardizing chassis platforms across powertrain variants, compressing margin flexibility for non-integrated suppliers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement, with oscillating drum specialists commanding specification premiums in Japanese railway contracts while spring-loaded durability leaders capture volume in European rental channels. Price differentiation rests on EPA certification tier and telematics integration depth, with Tier 4 Final compliance costs intensifying cost compression in standard fleet configurations. Utility providers show highest price sensitivity due to municipal budget cycles, whereas infrastructure firms accept premium positioning for multi-year contract security.
Supply Chain Analysis
Freight cost volatility from German industrial clusters to North American distribution hubs is reshaping inventory positioning strategies among anti-vibration mount suppliers. Manufacturing concentrates in Germany, Japan, and China, with casting expertise for engine housings anchored in Bavarian facilities and battery pack assembly scaling in Yangtze River Delta plants. Raw material dependencies include lithium iron phosphate cells, nodular cast iron, and specialized spring steel alloys. Single-source vulnerability in German anti-vibration component supply exposes procurement to regional disruption. Distribution runs through Midwest rental houses serving Chicago and Detroit construction markets alongside direct OEM relationships with multi-state fleet managers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vibratory rammer market functions as a stable compounder, with urban infrastructure renewal cycles in Germany and the United States generating predictable equipment replacement demand regardless of cyclical construction volatility.
For Market Incumbents: Anticipate electric powertrain substitution by securing lithium iron phosphate supply agreements and containerized charging station partnerships before municipal zero-emission mandates harden procurement specifications. Backward integration into cast component production insulates margin pressure from German supplier concentration risk. Prioritize telematics standardization to meet national rental house procurement consolidation. For New Entrants and Emerging Players: Battery thermal management innovation offers entry leverage into Indian highway expansion and metro rail projects where cost-optimized single-acting rammers face specification gaps in sustained high-frequency applications. Target utility provider procurement in urban rights-of-way where electric range limitations have delayed incumbent penetration. Pursue BIS certification early to accelerate formalization capture in previously fragmented supply. For Investors and Strategic Acquirers: Asymmetric upside sits with oscillating drum specialists holding railway maintenance specification authority and captive German casting expertise. Long-term viability favors manufacturers with modular chassis architectures capable of absorbing gasoline-to-electric powertrain transitions without platform redesign. Monitor fast-charging infrastructure buildout velocity in German urban construction zones as the inflection signal for electric rammer displacement timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Attachment System Development | Enables rental fleets to standardize chassis while swapping gasoline, diesel, and electric power units. |
| Charging Infrastructure Partnership | Containerized solar charging stations replace diesel refueling convoys in German railway maintenance contracts. |
| Telematics Protocol Standardization | Meets national rental house demands for cross-fleet equipment visibility and density feedback integration. |
| Cast Component Backward Integration | Captures Bavarian casting expertise for anti-vibration mounts, reducing exposure to single-source supply risk. |
| BIS Certification Investment | Accelerates market access in Indian highway expansion where formalization is displacing fragmented supply. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with maintenance directors at United States rental houses, OEM procurement teams in Germany, plant engineers at Japanese railway contractors, and aftermarket service heads with secondary validation. Secondary sources included customs and trade data for compaction equipment flows, SEC filings from listed construction equipment manufacturers, EPA engine family certification databases, and EU Green Deal procurement mandate documentation. Bottom-up equipment shipment tracking and top-down infrastructure investment flow analysis were triangulated against regional utilization rate surveys.
Segment-weighting approaches modeled powertrain type, compaction mechanism technology, end-use application intensity, and customer procurement sophistication across the analysis window. CAGRs were derived from equipment replacement cycle analysis correlated with infrastructure contract award timelines. Forecast inputs incorporated battery energy density improvement curves and municipal zero-emission equipment mandate adoption schedules.
The model holds under stable infrastructure funding continuity and gradual emissions regulation tightening; deviation in federal highway appropriation cycles or abrupt battery supply chain disruption would shift replacement demand timing. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Welding Fume Extraction Equipment Market
Construction Equipment
Ceramic Tile Printing Machine Market
Construction Equipment
ASEAN Construction Equipment Rental Market
Construction Equipment
Mobile Crushers and Screeners Market
Construction Equipment
Mexico Flexible Concrete Vibrator Market
Construction Equipment
Down-The-Hole (DTH) Hammer Bits Market
Construction Equipment
Draw Heat Setting Winder Market
Construction Equipment
Global Concrete Curing Equipment Market
Construction Equipment
Compressed Earth Block Machine Market
Construction Equipment
Core Drill Automatic Feeding Machine Market
Construction Equipment
Automotive Surface Heat Treatment Furnaces Market
Construction Equipment
PU Casting Machine Market
Construction Equipment
Plasma Cutting Equipment Market
Construction Equipment
Demolition Vessels Market
Construction Equipment
Welding and Cutting Equipment Market
Construction Equipment
Hexagonal Wire Netting Machine Market