
 Tool Storage Market | 2026-2036
Tool Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Tool Storage Market Analytics
The capital-intensity divergence between steel-fabrication heavyweights and plastic-molding specialists is unwinding competitive stability in tool storage. Stanley Black & Decker leverages integrated metal stamping capacity to dominate premium tool chest lines. Snap-on Incorporated sustains direct-to-mechanic channel control that anchors its automotive-grade positioning. Apex Tool Group competes through multi-brand portfolio breadth across price tiers.
Tool storage encompasses engineered enclosures, cabinets, and organizational systems fabricated from cold-rolled steel, high-density polyethylene, or engineered composites, designed to secure, classify, and protect hand tools, power tools, and accessories against environmental degradation and workplace hazards. Wall Organizer configurations lead residential installations where garage square footage constraints dictate vertical utilization, while Storage Cabinet demand accelerates fastest in industrial settings where OSHA-compliant lockout-tagout protocols require secure containment of energized equipment. Metal construction retains the largest margin pool due to raw material cost pass-through mechanisms and durability warranties that justify premium positioning.
FCC guidelines on warehouse RF equipment indirectly shape smart-storage integration requirements, while OSHA workplace safety standards mandate load-rated shelving and tip-resistant cabinet anchoring in commercial environments. EPA regulations on powder-coating emissions influence domestic metal-finishing capacity and regional sourcing patterns. Stakeholders must monitor evolving interoperability standards between modular storage systems and facility management software platforms.
Market Dynamics
OSHA workplace safety mandates and residential garage renovation cycles are compressing purchase timelines while fragmenting buyer specifications across professional and consumer segments.
Growth Catalysts
- OSHA Lockout-Tagout Mandates:Commercial fleet maintenance facilities in the United States face stepped-up enforcement of energized equipment containment protocols, forcing capital deployment into compliant cabinet systems.
- High-Density Polyethylene Formulation Advances:Injection-molding specialists have closed durability gaps with cold-rolled steel, opening residential entry-price tiers previously blocked by metal cost floors.
- Germany:The KBA's tightened commercial vehicle inspection standards cascade into tool accountability requirements for independent repair shops, stimulating organized storage adoption.
Market Restraints
- Cold-Rolled Steel Tariff Volatility:Section 232 duties and quota mechanisms in the United States compress margin buffers for metal-fabrication heavyweights unable to pass through input swings.
- China Powder-Coating Capacity Concentration:EPA emissions caps on domestic finishing operations force reliance on Chinese MEE-regulated facilities, exposing supply chains to carbon-border adjustment risks.
- Modular Interoperability Gaps:Absence of unified ISO standards for rail spacing and drawer dimensions locks buyers into single-vendor ecosystems, retarding replacement-cycle compression.
Strategic Opportunities
- India PLI Scheme for Auto Components:Component manufacturing clusters in Pune and Chennai lack mature tool accountability infrastructure, creating first-mover positioning for organized storage suppliers.
- FCC Warehouse RF Equipment Guidelines:Smart-storage integration with inventory management platforms opens subscription revenue streams from RFID-enabled cabinet systems.
- Direct-to-Mechanic Subscription Models:Mobile service van operators in Australia and Canada seek lease-based cabinet configurations that track with fleet expansion cycles rather than capital budgets.
Industry Challenges
- Welding Certification Bottlenecks:AWS D1.1-qualified fabricators command wage premiums that strain mid-tier manufacturers competing against automated stamping operations.
- Legacy Facility Management Software Integration:SOAP-based ERP systems in industrial end-uses resist API connectivity with IoT-enabled storage units, forcing costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tool Storage Market |
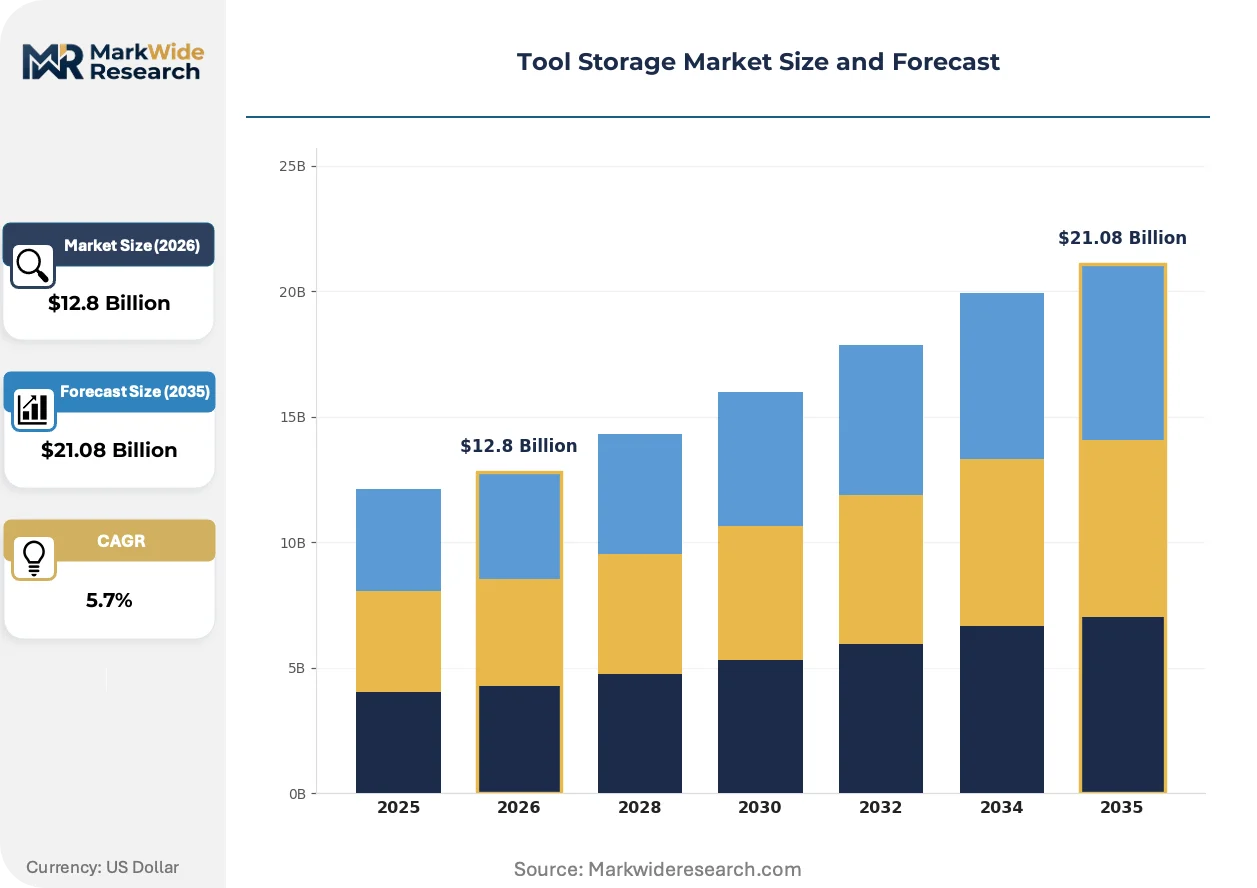
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tool Chest, Tool Box, Storage Cabinet, Wall Organizer Material: Metal, Plastic, Wood, Composite Application: Residential, Commercial, Industrial, Automotive Design Type: Portable, Fixed, Modular, Stackable |
| Companies Covered | Stanley Black & Decker, Snap-on Incorporated, Apex Tool Group, Techtronic Industries, DeWalt, Craftsman, Milwaukee Tool, Kennedy Manufacturing, Matco Tools, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tool Storage Market Evolving Landscape
Three distinct vectors are restructuring competitive advantage: material science breakthroughs, regulatory compliance digitization, and procurement model fragmentation between ownership and access.
Carbon-fiber-reinforced polymer drawer systems are decomposing the steel-dominant premium tier that Stanley Black & Decker has controlled through integrated stamping capacity. Aerospace maintenance divisions at Lufthansa Technik and Delta TechOps have piloted these configurations for mobile tool caddies, cutting weight by forty percent without load-rating sacrifice. The structural consequence is compressing the premium price umbrella that metal-fabrication incumbents have used to subsidize mid-tier positioning.
REACH Annex XVII restrictions on chromium trioxide in metal passivation are forcing European manufacturers toward trivalent chrome and zirconium-based alternatives. The industrial consequence extends coating cycle times and requires requalification of corrosion warranties that anchor premium positioning. German automotive OEM tool programs have responded by consolidating supplier lists to those with in-house REACH-compliant finishing, excluding smaller metal stampers dependent on job-shop coating.
Service-contract unbundling is fragmenting the traditional distributor-captive relationship that Snap-on has maintained through mobile franchise networks. Fleet maintenance managers at Penske and Ryder now separate cabinet procurement from tool financing, soliciting competitive bids through GPOs and reverse auctions. This pattern is most visible in the United States, where procurement centralization at national fleet operators has outpaced the direct-sales infrastructure that anchored automotive-grade positioning.
Tool Storage Market Segmentation
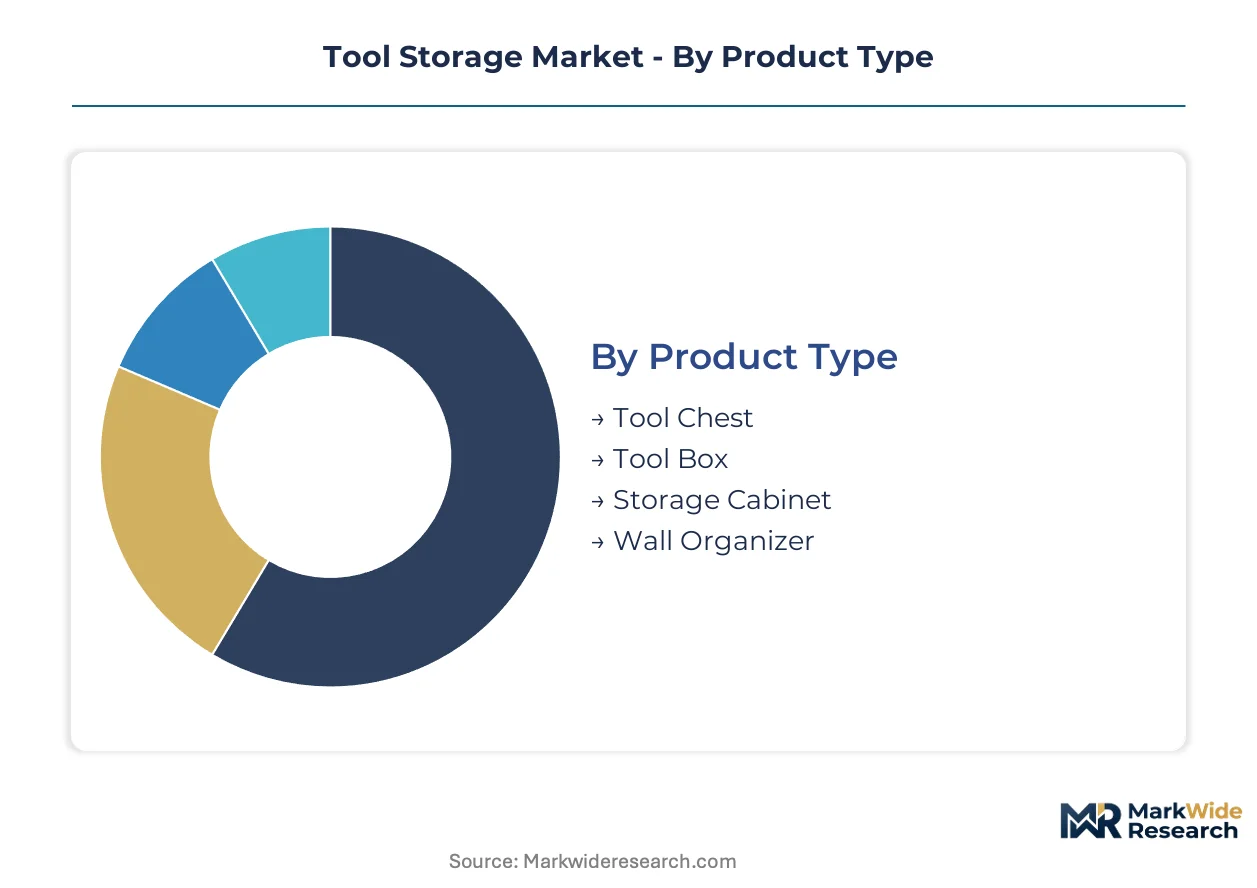
Tool storage segmentation reveals divergent durability requirements across professional and consumer tiers, with material substitution and regulatory compliance reshaping category boundaries. Understanding these fault lines exposes where margin pools concentrate and where commodification pressures intensify.
Product Type:
Substitution pressure from high-density polyethylene formulations is most acute in entry-level portable categories, while premium stationary segments retain steel dominance through warranty differentiation.
- Tool Chest:Multi-drawer rolling enclosures fabricated from cold-rolled steel with ball-bearing slides, typically 26-72 inch widths. Professional automotive technicians in United States fleet maintenance facilities drive specification toward OSHA-compliant lockout-tagout configurations with load-rated shelving.
- Tool Box:Portable hand-carry or vehicle-mounted containers ranging from 20-inch job-site boxes to cross-bed truck configurations. Mobile service van operators in Australia and Canada favor lease-based arrangements that align with fleet expansion cycles rather than capital deployment.
- Storage Cabinet:Vertical standing enclosures with single or double doors, engineered for secure containment of energized equipment. Industrial end-users in Germany face KBA-mandated tool accountability requirements that cascade from commercial vehicle inspection standards.
- Wall Organizer:Vertical mounting systems including pegboard, slatwall, and rail-based configurations optimized for garage square footage constraints. Residential renovation activity in United States suburban markets sustains category momentum.
Tool Chest retains volume leadership; Wall Organizer holds the steepest expansion curve.
Material:
Cost tier stratification separates premium metal fabrication from mass-market injection molding, with composite formulations attempting to bridge performance gaps at mid-tier price points.
- Metal:Cold-rolled steel and aluminum alloys dominate professional-grade fabrication, with powder-coat finishes subject to EPA emissions caps that force reliance on Chinese MEE-regulated finishing capacity. Raw material tariff volatility under Section 232 mechanisms compresses margin buffers for domestic stampers unable to pass through input swings.
- Plastic:High-density polyethylene and polypropylene injection-molded configurations have closed durability gaps with steel in residential applications. Formulation advances enable entry-price tier penetration previously blocked by metal cost floors.
- Wood:Niche positioning in aesthetic-focused residential workshops and custom garage installations where visual integration with cabinetry matters.
- Composite:Carbon-fiber-reinforced polymer drawer systems piloted at Lufthansa Technik and Delta TechOps for aerospace maintenance mobile caddies, cutting weight forty percent without load-rating sacrifice.
Metal commands the premium price umbrella; Composite formulations are climbing the fastest.
Application:
Customer type fragmentation separates capital-budget industrial procurement from discretionary residential purchasing, with divergent specification authority and replacement cycle dynamics.
- Residential:Garage renovation cycles and DIY tool accumulation drive demand for wall-mounted and modular configurations. United States suburban homeowners prioritize vertical space utilization where square footage constraints dominate.
- Commercial:Fleet maintenance facilities and independent repair shops face stepped-up OSHA enforcement of energized equipment containment protocols. Procurement centralization at national operators like Penske and Ryder fragments traditional distributor-captive relationships.
- Industrial:Manufacturing plants and warehouse operations require ISO-standard modular interoperability that current vendor ecosystems fail to deliver. Legacy SOAP-based ERP systems resist API connectivity with IoT-enabled storage units.
- Automotive:Professional technician workplaces anchor the most stringent durability and security specifications, with direct-to-mechanic channel control sustaining premium positioning.
Automotive commands specification authority; Residential is gaining share fastest.
Design Type:
Volume concentration in fixed installations contrasts with mobility requirements from distributed workforce models, pressuring modular standardization that remains vendor-locked.
- Portable:Rolling chests, job-site boxes, and vehicle-mounted configurations serving mobile technicians and contractors. Weight reduction from composite materials enables expanded payload capacity for service van operators.
- Fixed:Stationary cabinets and wall systems anchored to facility infrastructure, dominant in industrial OSHA compliance scenarios where tip-resistant anchoring is mandated.
- Modular:Rail-based and component systems permitting reconfiguration, constrained by absence of unified ISO standards for drawer dimensions and rail spacing that locks buyers into single-vendor ecosystems.
- Stackable:Interlocking container systems for parts and accessory organization, prevalent in residential and light commercial applications.
Fixed retains installation base; Modular shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price premiums in the United States compress entry-price tiers elsewhere, while German specification authority anchors European durability standards. This asymmetry fragments procurement patterns across major demand centers.
United States
Residential garage renovation cycles and commercial fleet expansion sustain category momentum. OSHA workplace safety mandates enforce lockout-tagout protocols in fleet maintenance facilities. Suburban markets across Texas and Florida concentrate demand for wall organizer configurations optimized for vertical space utilization.
Germany
Independent repair shops face cascading tool accountability requirements from tightened commercial vehicle inspection standards. The KBA's enforcement posture elevates organized storage to operational necessity. Automotive OEM supplier clusters in Baden-Württemberg consolidate procurement toward REACH-compliant finishing capabilities.
China
Powder-coating capacity concentration under MEE regulations supplies finishing services for domestic and export metal fabrication. Dual carbon goals accelerate emissions caps that reshape regional sourcing patterns. Manufacturing zones in Guangdong and Jiangsu province host contract finishing operations serving mid-tier fabricators.
India
Component manufacturing clusters in Pune and Chennai lack mature tool accountability infrastructure. The PLI scheme for auto components attracts capacity expansion without matching storage system deployment. First-mover positioning opportunities concentrate among suppliers establishing organized storage protocols alongside new production facilities.
Australia
Mobile service van operators seek lease-based cabinet configurations that align with fleet expansion cycles. Procurement centralization at national fleet operators fragments traditional distributor-captive relationships. Mining maintenance hubs in Western Australia generate demand for portable configurations serving distributed workforce models.
Tool Storage Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, fragmenting competitive stability across price tiers. Metal-fabrication heavyweights with integrated stamping capacity dominate premium stationary segments, while injection-molding specialists capture residential entry-price tiers through formulation advances. Three strategic archetypes structure rivalry: integrated steel fabricators, direct-channel specialists, and multi-brand portfolio operators. Capacity expansion in composite materials and strategic partnerships for smart-storage integration represent dominant competitive moves.
Among integrated metal-fabrication heavyweights, Stanley Black & Decker and Snap-on Incorporated exemplify divergent channel strategies that anchor their respective positions. Apex Tool Group occupies a position within the multi-brand portfolio tier, representing breadth-across-price-points as a competitive posture. These three entities collectively illustrate how technology access, channel control, and portfolio scope segment competitive advantage in tool storage.
| Leading Market Players |
|---|
| Stanley Black & Decker |
| Snap-on Incorporated |
| Apex Tool Group |
| Techtronic Industries |
| DeWalt |
| Craftsman |
| Milwaukee Tool |
| Kennedy Manufacturing |
| Matco Tools |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts for cold-rolled steel anchor price visibility for metal-fabrication heavyweights while locking in supply access against Section 232 tariff volatility. These arrangements compress margin buffers for mid-tier competitors lacking equivalent procurement scale or backward integration into stamping capacity.
Pricing Analysis
Configured-to-order pricing commands substantial premiums over standard SKUs in professional automotive segments where OSHA-compliant lockout-tagout specifications dominate. Three-tier pricing structure across premium, standard, and economy levels stratifies by material grade and warranty duration, with metal construction retaining the largest margin pool. Cost compression in entry-level portable categories intensifies as high-density polyethylene formulation advances displace steel cost floors. Residential renovation buyers exhibit highest price sensitivity, while fleet maintenance procurement centralization at national operators like Penske and Ryder prioritizes specification compliance over unit cost.
Supply Chain Analysis
China and the United States anchor powder-coating finishing capacity, with MEE-regulated facilities in Guangdong and Jiangsu provinces supplying domestic and export metal fabrication. Cold-rolled steel, high-density polyethylene resin, and ball-bearing slide hardware constitute critical input dependencies. Single-source vulnerability concentrates in Chinese finishing operations exposed to carbon-border adjustment risks. Distribution runs through mobile franchise networks for automotive-grade positioning and big-box retail channels for residential entry-price tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OSHA workplace safety digitization and smart-storage RFID integration constitute a regulatory-technology inflection reshaping competitive advantage. Procurement model fragmentation between ownership and access accelerates disruption velocity.
For Market Incumbents: Secure REACH-compliant finishing capabilities in-house to exclude smaller metal stampers dependent on job-shop coating. Defend against carbon-fiber-reinforced polymer substitution by extending durability warranties that anchor premium positioning. Channel control through direct-to-mechanic franchise networks requires reinforcement against GPO and reverse-auction procurement centralization. For New Entrants and Emerging Players: IoT-enabled inventory management integration represents a service-layer gap where legacy SOAP-based ERP systems resist API connectivity. Target component manufacturing clusters in Pune and Chennai lacking mature tool accountability infrastructure. Pursue lease-based cabinet configurations for mobile service van operators in Australia and Canada as the go-to-market angle. For Investors and Strategic Acquirers: Injection-molding specialists with formulation R&D capabilities and established residential retail distribution represent the acquisition target archetype. Long-term viability hinges on material science positioning that bridges steel durability at plastic cost structures. Watch for FCC warehouse RF equipment guideline enforcement as the signal indicating smart-storage subscription revenue inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Powder-Coating Finishing | EPA emissions caps force captive supply of REACH-compliant coating capacity. |
| Smart-Storage Platform Integration | RFID-enabled cabinet systems open subscription revenue from FCC-guided warehouse deployments. |
| Composite Material Capacity Expansion | Carbon-fiber-reinforced polymer production enables aerospace maintenance pilot programs at Lufthansa Technik. |
| Direct-to-Mechanic Subscription Launch | Lease-based configurations align with fleet expansion cycles rather than capital budgets. |
| India Manufacturing Footprint Establishment | PLI scheme auto component clusters in Pune and Chennai lack matching storage infrastructure. |
Research Methodology
Desk research of trade customs data, SEC filings from metal-fabrication and tool companies, and OSHA regulatory guidance documents preceded structured interviews with fleet maintenance procurement directors, automotive technician shop owners, injection-molding operations managers, and big-box retail category buyers. Primary fieldwork validated secondary findings through bottom-up demand estimation and top-down supply capacity assessment. Triangulation across these sources anchored segmentation-specific volume and value estimates.
Variance decomposition across material substitution rates, regulatory enforcement intensity, and procurement model adoption curves structured the analytical framework. Segmentation dimensions modeled include product type, material grade, application vertical, and design mobility class. CAGRs derived from fitted growth curves applied to base-year estimates, with input from capacity expansion announcements and facility investment tracking. Industry-specific forecast inputs incorporated OSHA inspection frequency data and residential building permit flows.
Forecasts assume regulatory continuity in OSHA workplace safety standards and EPA emissions enforcement regimes; material policy shifts would require re-modeling. Specific risks that could revise projections include Section 232 tariff rate modifications, REACH Annex XVII restriction expansions, and carbon-border adjustment mechanism implementation. Recalibration cycles align with material shifts in regulatory enforcement posture and raw material tariff policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Grinding Discs Market
Tools
Assembly Fastening Tool Market
Tools
Self-Clinching Fasteners Market
Tools
Cutting Equipment Market
Tools
Pipe Alignment Clamps Market
Tools
Press Machine Market
Tools
Global Flange Fasteners Market
Tools
US Power Tools Market
Tools
Hacksaw Blades Market
Tools
Bandsaw Market
Tools
Book Binding Machines Market
Tools
Drill Set Market
Tools
Woodworking Circular Saw Blades Market
Tools
Orbital Sanders Market
Tools
Vinyl Bending Machine Market
Tools
Global Table Saws Market