
 Nail Gun Market | 2026-2036
Nail Gun Market Size, Share, and Industry Trends Forecast 2026-2036
Nail Gun Market Outlook
Chinese pneumatic component manufacturing is consolidating around fewer forged-steel fastener suppliers. Stanley Black & Decker anchors North American retail distribution through big-box channel control. Hilti Corp. differentiates on direct-to-contractor service models with tool fleet management. Koki Holdings Co. Ltd. leverages deep motor technology from power tool adjacencies into cordless nailing systems.
A nail gun is a portable mechanical device that drives nails into wood or other building materials using compressed air, explosive powder charges, or electric motor actuation, typically operating at pressures between 70 and 120 PSI for pneumatic variants or 18-20 volts for battery platforms. Its primary purpose is to accelerate structural framing, sheathing, and finish carpentry by replacing manual hammering with rapid sequential fastening. Battery-powered nail guns now capture the fastest expansion as lithium-ion cell density improvements extend runtime beyond 1,000 fasteners per charge, while pneumatic tools retain dominance in high-volume commercial construction where air compressor infrastructure already exists. The collated fastener segment leads volume due to continuous loading efficiency on large-scale jobsites, whereas brad nailers command premium positioning in trim and cabinetry applications.
OSHA workplace safety standards and the EPA Clean Air Act shape product design requirements for emissions and noise exposure on U.S. construction sites. The EU Machinery Directive and CE marking requirements govern European market access, with REACH compliance affecting surface coating chemistry on metal fasteners. Stakeholders must monitor cordless battery interoperability standards and evolving lithium-ion transport regulations as electrification redefines fleet procurement decisions.
Market Dynamics
Cordless battery electrification is compressing pneumatic tool dominance as lithium-ion energy density improvements enable 1,000+ fastener runtime, forcing compressor infrastructure investments into obsolescence risk across residential job sites.
Growth Catalysts
- OSHA silica exposure rules:Tightened workplace safety mandates in the United States are accelerating pneumatic tool replacement with dust-reducing cordless alternatives on residential construction sites.
- Collated fastener loading systems:Continuous magazine feeding technology is compressing reloading downtime for high-volume framing crews in commercial building applications.
- United States:Standardized 18-20V battery platforms across major power tool ecosystems are forcing fleet-wide replacement cycles as contractors consolidate cordless inventory.
Market Restraints
- Lithium-ion cell cost volatility:Battery raw material price swings are compressing margin stability for cordless platform manufacturers dependent on cobalt and nickel supply chains.
- Forged-steel fastener concentration:Chinese pneumatic component consolidation around fewer suppliers is creating single-source vulnerability for collated nail production.
- Compressor infrastructure sunk costs:Existing air system investments in commercial construction create substitution friction against cordless migration despite operational advantages.
Strategic Opportunities
- Trim carpentry cordless penetration:Brad nailer categories in finish applications remain underpenetrated by battery platforms relative to framing segments.
- EU Machinery Directive compliance:CE marking and REACH surface coating requirements are creating certification barriers that favor established cordless suppliers with European regulatory expertise.
- Direct-to-contractor service models:Tool fleet management and outcome-based maintenance contracts are displacing traditional retail channel dependence for professional-grade procurement.
Industry Challenges
- Battery interoperability standardization:Proprietary voltage and connector systems across cordless platforms are fragmenting contractor fleet decisions and increasing total cost of ownership.
- Fastener coating chemistry compliance:REACH and EPA Clean Air Act surface treatment regulations are extending product qualification timelines for collated nail suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nail Gun Market |
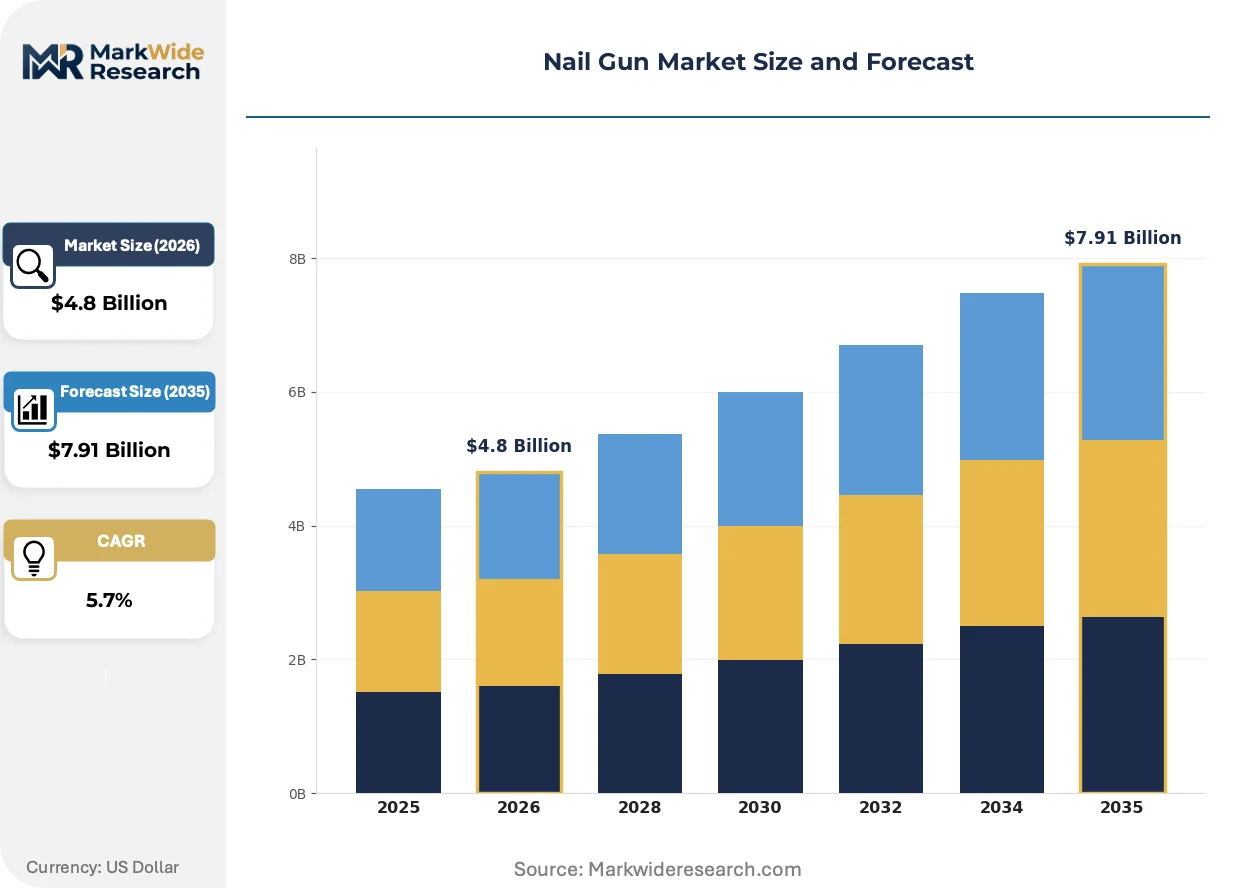
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pneumatic, Electric, Battery-Powered, Specialty End User: Construction, Carpentry, DIY, Manufacturing Operating Mechanism: Sequential, Contact, Automatic, Manual Fastener Type: Collated, Brad, Boxed, Others |
| Companies Covered | Emerson Electric Co., Hilti Corp., Illinois Tool Works Inc., Stanley Black & Decker Inc., Robert Bosch GmbH, Koki Holdings Co. Ltd., Techtronic Industries Co. Ltd., Makita USA Inc., Puma Industrial Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nail Gun Market Strategic Shifts
Three intersecting forces are restructuring competitive positioning: battery chemistry advances are electrifying product architectures, regulatory frameworks are mandating emission and noise reductions, and procurement patterns are shifting toward integrated fleet solutions.
Brushless motor technology paired with high-density lithium-ion cells is electrifying cordless nailing system performance to pneumatic-equivalent driving force. Residential contractors in North America are adopting these platforms at accelerating pace as runtime exceeds full workday thresholds. The technology is compressing air compressor rental and maintenance revenue streams while expanding addressable market for battery-native suppliers.
OSHA workplace noise exposure standards and EPA Clean Air Act emissions thresholds are mandating pneumatic tool displacement in enclosed construction environments. These rules are forcing equipment procurement officers to specify cordless alternatives for indoor framing and finishing operations. United States commercial builders are responding by amortizing battery platform investments across multi-tool fleets to spread compliance costs.
Integrated tool fleet management with predictive maintenance scheduling is displacing transactional equipment purchasing among large contracting operations. Professional construction firms are consolidating vendor relationships to capture volume pricing and standardized training protocols. This pattern is most visible in United States metropolitan construction markets where labor productivity metrics drive procurement centralization.
Nail Gun Market Segmentation
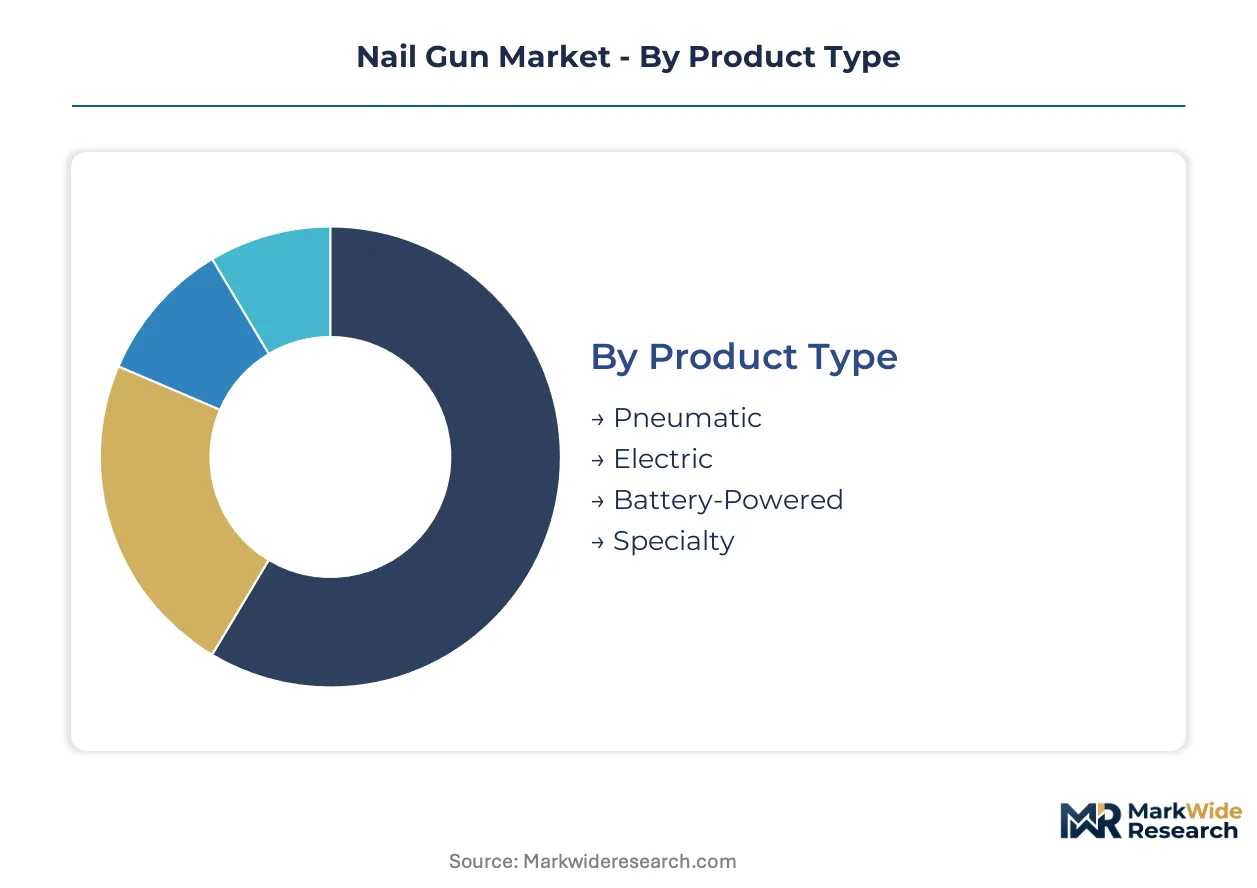
Nail gun segmentation reveals divergent technology adoption curves across professional and consumer tiers. Product architecture choices directly determine jobsite compatibility with OSHA silica rules and compressor infrastructure economics.
Product Type:
Volume concentration favors established pneumatic installations while premium growth concentrates in cordless electrification.
- Pneumatic:Compressed air systems operating at 70-120 PSI dominate commercial construction where existing compressor infrastructure amortizes across large crews. Demand concentrates in high-volume framing applications across the United States where sunk equipment costs create substitution friction despite cordless advances.
- Battery-Powered:Lithium-ion platforms at 18-20 volts are displacing pneumatic dominance as cell density improvements push runtime past 1,000 fasteners per charge. Residential contractors in the United States are consolidating fleet procurement around standardized battery ecosystems to reduce total cost of ownership.
- Electric:Corded AC motor systems occupy a narrowing niche in stationary workshop environments where power consistency outweighs portability requirements.
- Specialty:Powder-actuated and gas-powered variants serve concrete fastening and remote off-grid applications where conventional power sources prove impractical.
Mature deployment sits with Pneumatic systems. Newer deployment is concentrated in Battery-Powered platforms.
End User:
Professional-grade procurement patterns diverge sharply from consumer purchasing behavior across channel and service expectations.
- Construction:General contractors and framing crews drive bulk volume through fleet management contracts with direct vendor relationships. OSHA silica exposure compliance is forcing cordless migration on residential jobsites where dust suppression requirements tighten.
- Carpentry:Finish carpenters and trim specialists command premium pricing for precision brad nailers in cabinetry and millwork applications. Battery platform penetration remains underdeveloped relative to framing segments, creating vendor opportunity.
- DIY:Home improvement consumers purchase through big-box retail channels with price sensitivity driving private-label and entry-tier brand selection.
- Manufacturing:Industrial pallet and crate producers utilize high-cycle pneumatic systems in fixed production lines where continuous operation demands compressed air reliability.
Revenue concentration aligns with Construction procurement scale. Margin expansion is climbing the fastest in Carpentry specialty applications.
Operating Mechanism:
Safety certification requirements and productivity metrics shape mechanism selection across professional tiers.
- Sequential:Trigger-actuated firing requiring deliberate user action dominates commercial construction where OSHA workplace safety mandates restrict contact-trip alternatives. United States framing crews accept slower cycle rates in exchange for reduced liability exposure.
- Contact:Bump-fire modes enabling rapid sequential fastening retain position in high-volume roofing and sheathing where experienced operators prioritize speed over safety interlocks.
- Automatic:Sensor-triggered and programmable systems are emerging in manufacturing automation lines where robotic integration demands hands-free operation.
- Manual:Spring-powered and single-strike mechanisms persist in specialty restoration and heritage carpentry where precise depth control outweighs productivity.
Regulatory compliance favors Sequential deployment. Productivity optimization drives Contact mechanism retention.
Fastener Type:
Loading efficiency and application specificity determine fastener format economics across construction verticals.
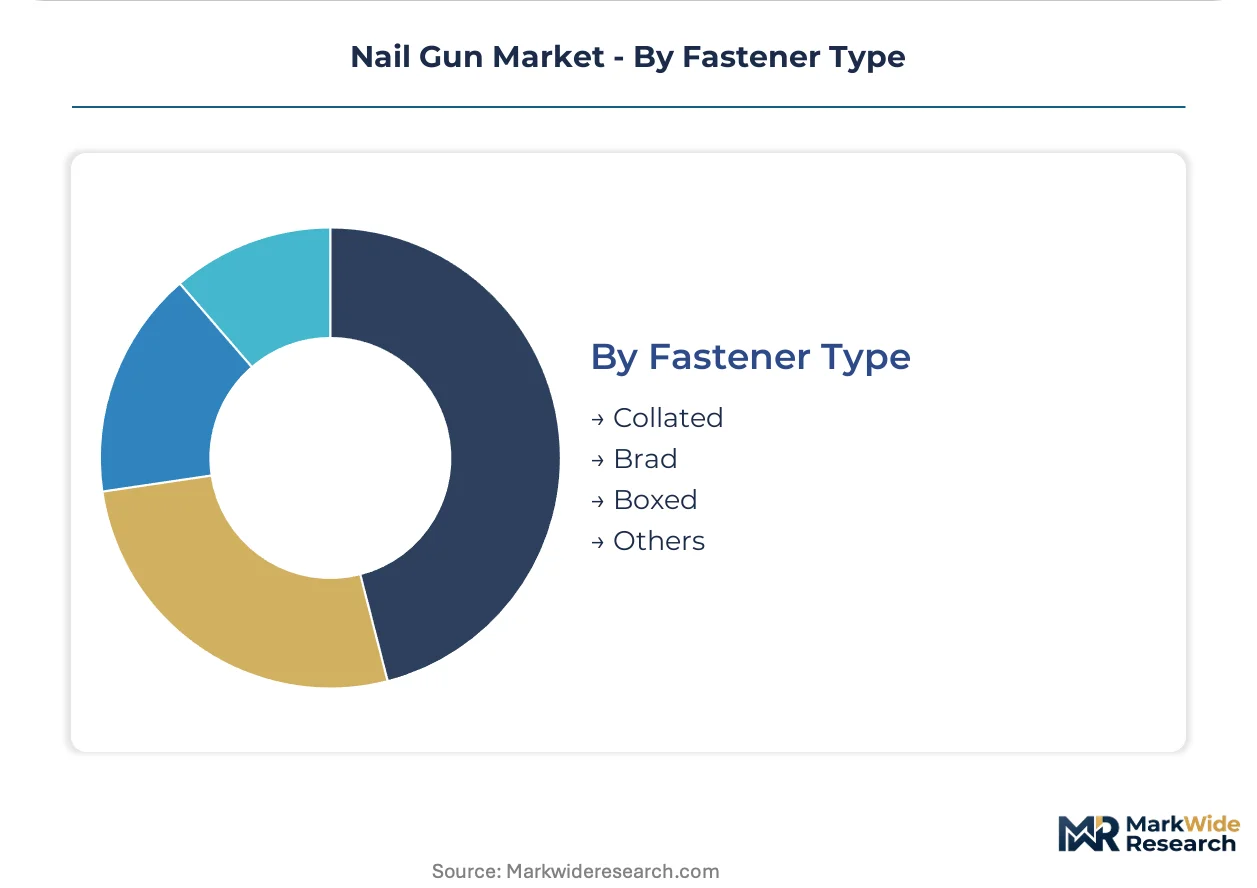
- Collated:Strip and coil magazine systems enable continuous feeding with minimal reloading interruption. Commercial building contractors in the United States specify collated formats for high-volume framing crews where downtime compression directly impacts labor cost structures.
- Brad:Thin-gauge finish nails in adhesive strips command premium positioning for trim and cabinetry where surface visibility demands minimal hole diameter. Cordless brad nailer adoption is accelerating among residential finish carpenters seeking jobsite mobility without compressor logistics.
- Boxed:Bulk loose fasteners serve pneumatic users with manual feed systems and cost-conscious operations where magazine compatibility is secondary to per-fastener economics.
- Others:Specialty formats including screw-shank ring nails and coated structural fasteners address engineered lumber and hurricane-rated framing specifications in coastal United States building codes.
Volume leadership resides with Collated systems. Premium positioning is expanding most quickly in Brad applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Forged-steel fastener production clusters in China's Zhejiang and Jiangsu provinces supply collated nail formats worldwide, while battery cell manufacturing concentrates in South Korean and Japanese facilities that power cordless platform expansion.
United States
Residential construction contractors drive cordless nail gun procurement as OSHA silica exposure rules tighten dust suppression mandates on jobsites. The EPA Clean Air Act shapes indoor framing equipment specifications in enclosed commercial builds. Dallas-Fort Worth and Phoenix construction corridors concentrate fleet replacement demand as metropolitan housing starts accelerate.
Germany
Commercial builders specify pneumatic systems for high-volume timber framing where existing compressor infrastructure amortizes across large crews. The EU Machinery Directive and CE marking requirements govern tool certification for professional-grade procurement. Bavarian and Baden-Württemberg industrial zones anchor precision fastening equipment manufacturing for European distribution.
China
Pneumatic component manufacturing consolidates around fewer forged-steel fastener suppliers serving export markets and domestic construction growth. GB standards and MIIT industrial policy shape local product safety and energy efficiency benchmarks. Yangtze River Delta manufacturing clusters in Shanghai and Suzhou dominate collated nail and compressor component export production.
Japan
Deep motor technology expertise from power tool adjacencies feeds cordless nailing system development for precision carpentry applications. METI industrial standards and JIS certification requirements structure professional equipment procurement protocols. Nagoya and Osaka industrial corridors concentrate brushless motor and lithium-ion battery pack integration facilities.
India
Infrastructure investment and urban housing expansion drive pneumatic tool demand where compressor economics favor established air-system deployment. BIS certification and construction safety codes shape equipment import and local assembly requirements. Maharashtra and Gujarat industrial zones concentrate distribution networks for South Asian commercial construction supply.
Nail Gun Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue battery-native architectures and direct-to-contractor service models. The market structures around three concentration nodes: diversified industrial conglomerates with power tool portfolios, specialized fastening equipment manufacturers, and regional pneumatic component suppliers. Strategic moves center on cordless platform standardization to lock fleet procurement decisions and vertical integration into battery cell and fastener supply to compress margin exposure.
Among diversified industrial conglomerates, Stanley Black & Decker Inc., Robert Bosch GmbH, and Hilti Corp. exemplify contrasting channel strategies. Stanley Black & Decker anchors North American retail distribution through big-box channel control. Robert Bosch GmbH represents European engineering-led positioning with professional-grade equipment certification. Hilti Corp. occupies a position emphasizing direct-to-contractor relationships and tool fleet management services over transactional retail placement.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Hilti Corp. |
| Illinois Tool Works Inc. |
| Stanley Black & Decker Inc. |
| Robert Bosch GmbH |
| Koki Holdings Co. Ltd. |
| Techtronic Industries Co. Ltd. |
| Makita USA Inc. |
| Puma Industrial Co. Ltd. |
| Others |
Value Chain & Pricing Dynamics
Horizontal integration across battery platform ecosystems anchors both supply security and pricing power for cordless nail gun manufacturers consolidating fleet procurement decisions. Captive fastener production and in-house motor assembly compress cost exposure while proprietary battery interoperability locks contractor switching costs.
Pricing Analysis
Warranty and service bundling separates professional-grade cordless platforms from unbundled pneumatic alternatives in contractor fleet decisions. Three-tier pricing structure across premium, standard, and economy levels reflects brushless motor certification, battery cell density ratings, and after-sales maintenance contracts. Pricing pressure stems from lithium-ion raw material volatility compressing margin stability in battery-native tiers. DIY consumers through big-box channels exhibit highest price sensitivity; commercial construction procurement officers prioritize total cost of ownership over unit economics.
Supply Chain Analysis
Reverse logistics for battery pack refurbishment and tool trade-in programs flow through manufacturer-direct service networks and authorized dealer channels. Forged-steel fastener production concentrates in China, South Korea, and Taiwan; lithium-ion cell manufacturing clusters in Japan and South Korea. Supply chains draw from cobalt and nickel mining operations, precision-machined aluminum housings, and injection-molded polymer components. Single-source vulnerability concentrates in Chinese pneumatic component consolidation. Distribution runs through big-box retail, direct-to-contractor fleet management, and industrial supply distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nail gun market sits in a technology-transition phase as brushless motor lithium-ion platforms displace legacy pneumatic compressor infrastructure across residential construction.
For Market Incumbents: Cement cordless platform standardization to lock contractor fleet replacement cycles and defend against battery-native entrants. Acquire captive fastener manufacturing capacity in Zhejiang or Jiangsu provinces to compress single-source exposure from Chinese supplier consolidation. Invest in OSHA silica compliance certification to capture regulatory-driven substitution demand. For New Entrants and Emerging Players: Begin with trim carpentry brad nailer segments where cordless penetration lags framing applications and compressor logistics burden finish crews. Target metropolitan United States construction corridors where labor productivity metrics drive procurement centralization. Pursue direct-to-contractor fleet management contracts displacing traditional retail channel dependence. For Investors and Strategic Acquirers: Exit pathways concentrate in diversified industrial conglomerates seeking cordless platform scale and battery ecosystem consolidation. Long-term viability favors suppliers with backward integration into motor technology and captive fastener production. Monitor lithium-ion transport regulation evolution and REACH surface coating compliance timelines as inflection signals for margin compression risk.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Standardization | Proprietary 18-20V ecosystems lock contractor fleet decisions and increase switching costs across multi-tool procurement. |
| Backward Integration into Fasteners | Captive collated nail production in Yangtze River Delta clusters compresses supply vulnerability and margin exposure. |
| Direct-to-Contractor Service Model | Outcome-based maintenance contracts displace transactional retail placement for professional-grade cordless platforms. |
| OSHA Compliance Certification Investment | Silica exposure rule alignment accelerates pneumatic displacement on residential jobsites in United States metropolitan markets. |
| Brushless Motor R&D Expansion | High-density lithium-ion pairing with precision motor control enables pneumatic-equivalent driving force in cordless architectures. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this nail gun market analysis. Primary interviews with equipment procurement officers at general contracting firms, fleet managers at commercial construction operations, aftermarket service directors at power tool distributors, and regulatory compliance leads supplemented field intelligence. OSHA enforcement databases, EPA Clean Air Act guidance documents, EU Machinery Directive certification registries, and import-export trade statistics provided validation layers. Bottom-up segment sizing triangulated against top-down industry revenue estimates.
Product-type granularity modeled pneumatic, battery-powered, electric, and specialty architectures separately across end-user categories. Operating mechanism adoption curves and fastener format preferences were projected across the analysis window. CAGRs derived from segment-level growth trajectories weighted by regional construction activity indices and regulatory enforcement intensity. Lithium-ion cell density improvement curves and compressor infrastructure depreciation schedules informed technology substitution assumptions.
Raw material price swings, regulatory enforcement delays, and construction cycle downturns are the dominant revision risks to nail gun market projections. Forecasts reflect documented assumptions about battery platform interoperability evolution and fastener coating chemistry compliance timelines. Practitioners should monitor lithium transport regulation proposals and REACH amendment proceedings for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
DIY Ball Mill Market
Tools
Handheld Blower Market
Tools
Drill Presses Market
Tools
Cordless Impact Wrench Market
Tools
Woodworking Tools Market
Tools
Automotive Torque Tools Market
Tools
Overload Protection Tools Market
Tools
CNC Leather Cutting Machine Market
Tools
Tooling Market
Tools
Woodworking Router Bits Market
Tools
Foam Engraving Machines Market
Tools
Cordless Bandsaw Sander Market
Tools
Europe Woodworking Power Tools Market
Tools
Portable Pressure Washer Market
Tools
Riveting Tools Market
Tools
Construction Nails Market