
 Hand Tools Market | 2026-2036
Hand Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Hand Tools Market Intelligence
Buyer concentration among professional maintenance fleets is hardening as fleet operators consolidate vendor lists and demand calibrated tool sets. Stanley Black & Decker anchors its position through broad channel control across retail and industrial distributors. Snap-on Incorporated specializes in mobile van distribution that locks in automotive technician loyalty. Wera differentiates through precision-engineered screwdriving systems that command premium positioning in European industrial accounts.
Hand tools encompass manually operated implements fabricated from alloy steel, aluminum, or polymer composites, typically heat-treated to specific hardness ratings for torque transmission and wear resistance. These instruments enable mechanical fastening, material deformation, and component manipulation across construction, repair, and assembly operations. Wrenches and pliers constitute the mature volume core where margin compression is most acute, while composite-material tool lines represent the fastest-expanding margin pool as weight-sensitive aerospace and automotive applications multiply. Application demand through electrical work is outpacing construction in growth velocity as electrification projects expand across residential and utility infrastructure.
OSHA workplace safety mandates in the United States and CE marking requirements under the EU Machinery Directive establish baseline performance and ergonomic standards that filter non-compliant imports from distribution channels. EPA regulations on hexavalent chromium plating and REACH substance restrictions in Europe are accelerating material substitutions toward nickel-tungsten and physical vapor deposition finishes. Stakeholders must monitor evolving alloy composition rules and ergonomic certification thresholds as regulatory divergence between North American and European frameworks complicates unified product platform strategies.
Market Dynamics
Vehicle electrification is compressing tool replenishment cycles across automotive maintenance networks, forcing distributors to recalibrate inventory depth and technician training programs around high-voltage safety protocols.
Growth Catalysts
- REACH substance restrictions:European chemical regulations are accelerating chrome-free plating adoption, opening premium positioning for compliant manufacturers in German industrial maintenance channels.
- Composite material tooling:Aerospace assembly lines in France and the United States are specifying carbon-fiber-reinforced polymer wrenches to reduce technician fatigue during extended fastening operations.
- Utility electrification infrastructure:Residential solar and grid-scale battery installations across Australia and South Korea are expanding demand for insulated hand tools certified to IEC 60900 standards.
Market Restraints
- Alloy steel price volatility:Nickel and molybdenum input cost swings are compressing margins for mid-tier forged tool producers in Chinese manufacturing clusters.
- Concentrated forging capacity:Heat-treatment and drop-forge operations remain concentrated in Taiwan and Zhejiang Province, creating single-source vulnerability for Western distributors.
- Hexavalent chromium substitution limits:EPA plating restrictions and REACH Annex XVII limitations are delaying surface-finish qualification timelines for corrosion-resistant tool lines.
Strategic Opportunities
- Indonesian manufacturing expansion:Automotive assembly plant construction in Java is creating first-mover advantage for calibrated torque tool suppliers establishing local calibration laboratories.
- Physical vapor deposition convergence:PVD coating technology is integrating with titanium-aluminum-nitride formulations to extend cutting edge retention in aviation maintenance environments.
- OSHA ergonomic mandates:Revised workplace safety guidelines are mandating anti-vibration handle designs, creating replacement demand across US construction contractor fleets.
Industry Challenges
- Metallurgical certification timelines:Third-party hardness verification and torque calibration accreditation for new alloy formulations are extending product launch cycles by 8-14 months.
- High-voltage safety competency gaps:Technician certification for insulated tool handling under NFPA 70E standards is creating training bottlenecks for distributor field service teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hand Tools Market |
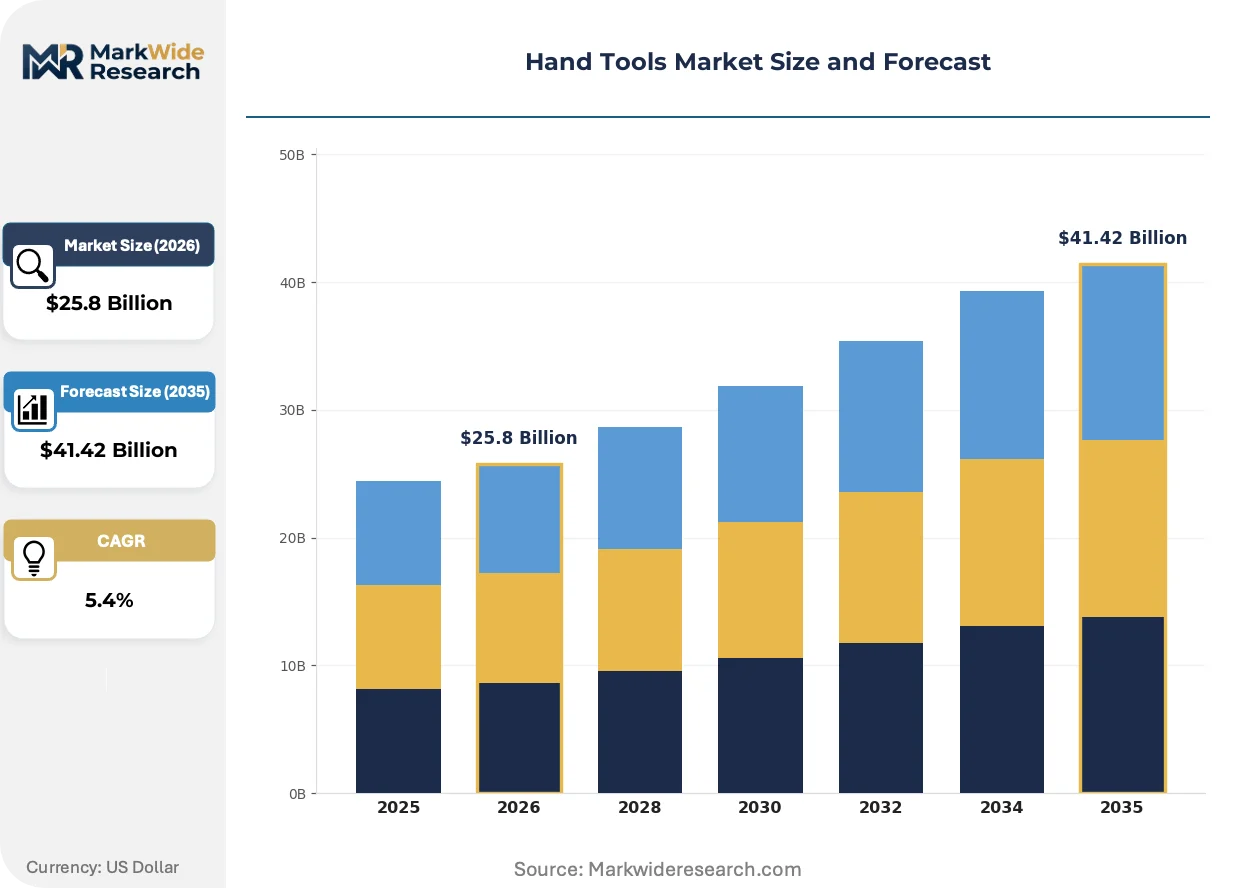
| Market Size in 2026 | $25.8 Billion |
| Market Size in 2035 | $41.42 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Tool Type: Wrenches, Pliers, Screwdrivers, Hammers Material: Steel, Aluminum, Plastic, Composite Application: Construction, Automotive Repair, Plumbing, Electrical Work End User: DIY Enthusiasts, Contractors, Maintenance Technicians, Electricians |
| Companies Covered | Snap-on Incorporated, Wera, Stanley Black & Decker, TOPTUL, Makita, Apex Tool Group, Knipex, Stahlwille, Techtronic Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hand Tools Market Strategic Shifts & Innovations
Digital torque measurement is embedding into manual fastening tools, transforming quality assurance protocols across precision assembly environments from automotive powertrain to medical device manufacturing.
Smart torque wrenches with Bluetooth-enabled angle and force logging are integrating into manufacturing execution systems, enabling aerospace assembly plants in Toulouse and Wichita to eliminate paper torque records and compress audit preparation cycles. Tier-one suppliers are mandating these connected tools for critical fastener applications, creating specification lock-in that disadvantages analog tool competitors.
EPA hexavalent chromium regulations and REACH Annex XIV authorization requirements are forcing plating shop conversions to trivalent chrome and nickel-tungsten alternatives, extending lead times for corrosion-resistant tool finishes by 30-45 days. German automotive OEMs are accelerating supplier qualification for chrome-free surfaces ahead of 2027 sunset dates, compressing the window for process validation.
Maintenance fleet operators are consolidating vendor lists and demanding calibrated tool sets with embedded asset tracking, displacing fragmented procurement across multiple distributor relationships. This concentration is most visible in US commercial aviation maintenance, where MRO providers are standardizing on single-source calibrated tool programs to reduce Foreign Object Debris risk and simplify audit trails.
Hand Tools Market Segmentation
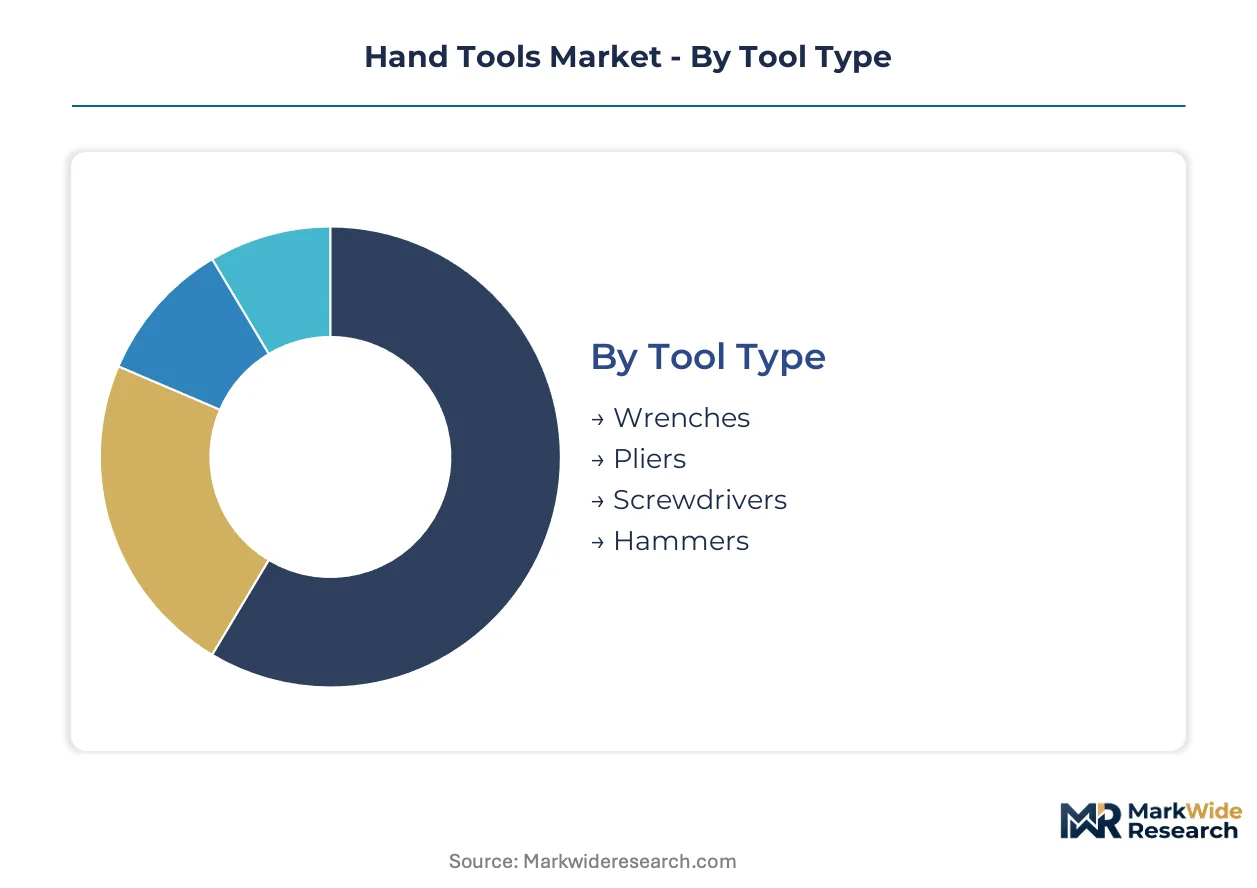
Segmentation in hand tools reveals how replacement cycles, material substitution mandates, and end-user certification requirements reshape procurement patterns. Tool manufacturers calibrate product lines to distinct performance tiers while distributors manage inventory depth against fragmented demand signals.
Tool Type:
Upgrade and replacement cycles vary dramatically across manual fastening categories, with fleet operators timing refreshes to calibration expiration schedules and ergonomic mandate compliance windows.
- Wrenches:Forged alloy steel implements with heat-treated jaws deliver calibrated torque transmission for mechanical fastening. Demand clusters in German automotive maintenance channels where OEMs mandate chrome-free plating ahead of regulatory deadlines.
- Pliers:Leveraged gripping tools with induction-hardened cutting edges manipulate wire and fasteners. Volume concentrates in US electrical contractor fleets where OSHA ergonomic mandates are accelerating handle redesign procurement.
- Screwdrivers:Precision-engineered instruments with hardened tips engage threaded fasteners across assembly operations. European industrial accounts specify precision-engineered systems for critical fastening applications.
- Hammers:Striking tools with differentially hardened faces deform material and drive fasteners. Construction contractors in Australia and South Korea specify composite handles for extended-use fatigue reduction.
Volume placements concentrate in wrenches and pliers; the faster expansion belongs to screwdrivers as digital torque measurement embeds into precision fastening protocols.
Material:
Cost tier differentiation separates commodity forged products from premium lightweight specifications, with aerospace and automotive OEMs driving material substitution toward weight-reduction targets.
- Steel:Chrome-vanadium and nickel-molybdenum alloy formulations provide hardness ratings exceeding 55 HRC for torque-intensive applications. REACH Annex XVII restrictions are compressing margins as plating shops convert to trivalent chrome alternatives.
- Composite:Carbon-fiber-reinforced polymer and glass-filled nylon structures reduce tool weight by 40-60 percent versus steel equivalents. Toulouse and Wichita aerospace assembly lines specify these for technician fatigue reduction during extended fastening operations.
- Aluminum:Lightweight alloy castings and extrusions serve non-sparking requirements in hazardous environments. Oil and gas maintenance operators in the Gulf Coast specify aluminum tools for refinery turnaround work.
- Plastic:Glass-filled polymer handles and insulated grips provide dielectric protection and ergonomic cushioning. IEC 60900 certification requirements are expanding specification for insulated plastic components in utility electrification projects.
Steel dominates unit placements; composite materials are climbing the fastest as weight-sensitive applications multiply across aviation and electric vehicle assembly.
Application:
Application-driven demand fragmentation forces distributors to maintain specialized inventory pools, with electrification infrastructure outpacing traditional construction in current procurement velocity.
- Electrical Work:Insulated hand tools with dielectric ratings protect technicians from arc flash and shock hazards. Grid-scale battery installations across Australia and South Korea are expanding IEC 60900-certified tool procurement.
- Automotive Repair:Calibrated torque instruments and high-voltage safety equipment service electrified powertrains. Vehicle complexity is compressing tool replenishment cycles as technicians require new competency certifications under NFPA 70E.
- Construction:General-purpose fastening and demolition tools serve building erection and renovation. OSHA ergonomic mandates are mandating anti-vibration handle replacements across US contractor fleets.
- Plumbing:Pipe wrenches, tube cutters, and basin wrenches manipulate threaded fittings and tubing. Residential construction cycles drive replacement demand in North American housing markets.
Construction maintains the largest installed base; electrical work is gaining share fastest as residential solar and utility-scale storage deployments accelerate.
End User:
Customer-type concentration shapes channel strategy, with professional maintenance fleets consolidating vendor lists while DIY procurement fragments across retail formats.
- Maintenance Technicians:Industrial asset caretakers specify calibrated tool sets with embedded asset tracking for audit compliance. US commercial aviation MRO providers are standardizing on single-source programs to reduce Foreign Object Debris risk.
- Contractors:Construction and trades businesses purchase through distributor relationships with volume pricing and field service support. Fleet consolidation is hardening buyer concentration as operators reduce vendor counts.
- Electricians:Licensed electrical workers require insulated tools and high-voltage safety equipment certified to workplace standards. Training bottlenecks for NFPA 70E competency are delaying tool deployment in some markets.
- DIY Enthusiasts:Home improvement consumers purchase through retail and e-commerce channels with price-sensitive preferences. This segment shows highest sensitivity to alloy steel price volatility transmitted through finished goods pricing.
Contractor volume leads current placements; maintenance technicians show the steepest expansion trajectory as industrial fleet standardization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tool procurement concentrates where automotive electrification, aerospace assembly, and utility infrastructure projects overlap. German industrial maintenance standards and US aviation MRO consolidation drive premium specification adoption.
United States
Commercial aviation MRO providers in Wichita and Seattle standardize on single-source calibrated tool programs to reduce Foreign Object Debris risk. OSHA ergonomic mandates accelerate anti-vibration handle replacements across construction contractor fleets. EPA hexavalent chromium regulations push plating shops toward trivalent chrome alternatives, extending qualification timelines for corrosion-resistant finishes.
Germany
Automotive OEMs in Stuttgart and Munich mandate chrome-free plating ahead of 2027 REACH sunset dates, compressing supplier validation windows. REACH Annex XVII restrictions on cobalt and nickel compounds force alloy reformulation in drop-forge operations. Industrial maintenance channels in the Ruhr Valley specify precision-engineered torque instruments for powertrain assembly compliance.
China
Heat-treatment and drop-forge capacity clusters in Zhejiang Province supply Western distributors with alloy steel implements. SAMR quality certification requirements for hand tools tighten export documentation standards. Nickel and molybdenum input cost volatility compresses margins for mid-tier forged tool producers serving domestic construction markets.
France
Aerospace assembly plants in Toulouse specify carbon-fiber-reinforced polymer wrenches to reduce technician fatigue during extended fastening operations. ECHA substance authorization timelines delay surface-finish qualification for aviation-grade tool lines. ANSM workplace safety guidelines reinforce ergonomic certification thresholds for maintenance technician procurement.
Australia
Grid-scale battery installations and residential solar deployments across New South Wales expand demand for IEC 60900-certified insulated hand tools. TGA-equivalent electrical safety standards mandate dielectric testing for utility contractor equipment. Construction activity in Queensland and Victoria drives composite-handle hammer specifications for fatigue reduction.
Hand Tools Market Key Industry Players
German precision specialists anchor one tier; Taiwanese forging clusters and US industrial distributors hold volume positions. The vendor base separates into three layers: premium calibrated instrument providers, mid-tier forged product suppliers, and retail-channel commodity producers. Strategic archetypes include mobile van distribution networks, precision screwdriving system engineers, and broad-channel industrial distributors. Competitive moves center on vendor list consolidation by fleet operators and chrome-free plating qualification races ahead of regulatory deadlines.
Within the premium-tier vector, Snap-on Incorporated and Wera exemplify divergent specialization strategies. Stanley Black & Decker occupies a position spanning retail and industrial channels through scale-driven distribution control. These three anchors illustrate how geographic origin and organizational structure shape competitive positioning: the US-based mobile distribution specialist, the German precision-engineering GmbH, and the diversified industrial holding company.
| Leading Market Players |
|---|
| Snap-on Incorporated |
| Wera |
| Stanley Black & Decker |
| TOPTUL |
| Makita |
| Apex Tool Group |
| Knipex |
| Stahlwille |
| Techtronic Industries |
| Others |
Cost & Logistics Intelligence
Captive integration into chrome-free plating capabilities anchors premium pricing power for REACH-compliant manufacturers while locking out non-qualifying competitors from German automotive channels. This vertical control over surface-finish technology simultaneously secures supply security and commands price premiums as regulatory deadlines compress qualification windows.
Pricing Analysis
Volume placements cluster in wrenches and pliers where margin compression runs deepest; premium-mid-economy pricing differentiation separates calibrated torque instruments from commodity forged products. Price differentiation rests on certification grade and after-sales calibration service bundling. Cost compression in mid-tier forged lines is intensifying because nickel and molybdenum input volatility transmits directly through Chinese manufacturing clusters. DIY enthusiasts through retail channels exhibit highest price sensitivity; maintenance technicians specifying asset-tracked calibrated sets show least sensitivity.
Supply Chain Analysis
Dual-sourcing requirements from US aviation MRO providers mandate multi-supplier qualification for torque calibration standards, fragmenting procurement across qualified vendors. Heat-treatment and drop-forge capacity concentrates in Taiwan and Zhejiang Province; alloy steel feedstock draws from Australian nickel and Chilean molybdenum extraction. Single-source vulnerability in forging operations creates supply chain risk. Distribution runs through mobile van networks for automotive technicians and industrial distributors for contractor fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hand tools procurement sits in a technology-transition phase as digital torque measurement with Bluetooth logging displaces analog fastening instruments across precision assembly environments.
For Market Incumbents: To counter specification lock-in by tier-one aerospace suppliers mandating connected torque tools, accelerate backward integration into sensor calibration capabilities and deepen channel control through embedded asset-tracking service contracts. Prioritize chrome-free plating qualification ahead of REACH sunset deadlines to defend German automotive positioning. For New Entrants and Emerging Players: Capture white-space in Indonesian automotive assembly plant construction by establishing local torque calibration laboratories ahead of incumbent qualification cycles. Target utility electrification contractors in Australia and South Korea requiring IEC 60900-certified insulated tools. Lead with direct field service relationships rather than distributor intermediation. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified industrial holding companies seeking calibrated instrument capabilities. Five-to-ten-year viability favors precision-engineered specialists with regulatory qualification moats. Watch for inflection in NFPA 70E training completion rates as signal for insulated tool deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Chrome-Free Plating Qualification | REACH Annex XVII compliance secures German automotive OEM supply positions ahead of regulatory deadlines. |
| Digital Torque Integration | Bluetooth-enabled measurement tools lock in aerospace assembly plant specifications and eliminate analog competitors. |
| Local Calibration Laboratory Buildout | Indonesian automotive plant construction creates first-mover advantage for torque tool verification services. |
| Insulated Tool Certification Investment | IEC 60900 qualification opens utility electrification procurement across Australian grid-scale battery installations. |
| Mobile Van Network Expansion | Field service density reinforces automotive technician loyalty against distributor-channel competitors. |
Research Approach
Multi-period observation of alloy steel pricing volatility, regulatory qualification timelines, and fleet consolidation patterns anchored the trend analysis, supplemented by interviews with maintenance directors at commercial aviation MRO providers, procurement leads at German automotive OEMs, calibration service managers, and industrial distributor executives. Secondary validation drew from EPA plating regulation filings, ECHA substance restriction updates, SAMR certification standards, SEC 10-K disclosures from tool manufacturers, and customs trade data from Zhejiang Province export clusters. Bottom-up segment sizing and top-down macroeconomic triangulation cross-checked volume and value estimates.
Segment-weighting across tool type, material composition, application end-use, and customer archetype shaped the analytical framework. CAGRs were derived from fitted growth curves against historical replacement cycle data and projected regulatory compliance windows. Industry-specific forecast inputs included REACH sunset timeline assumptions and NFPA 70E training penetration rates for high-voltage safety competency.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to nickel and molybdenum commodity price swings, ECHA substance authorization delays, and aviation production rate adjustments. A model refresh is warranted upon material change in regulatory qualification timelines or alloy input cost volatility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Fatigue Testing Machine Market
Tools
Cordless Blind Rivet Gun Market
Tools
Press Machine Market
Tools
End Milling Machine Market
Tools
Fine Blanking Tools Market
Tools
Handheld Pipe Cutter Market
Tools
Cordless Planer Market
Tools
Portable Boring Machines Market
Tools
CNC Metal Cutting Machine Tools Market
Tools
Woodworking Circular Saw Blades Market
Tools
Global Protractor Market
Tools
Cordless Long Neck Grinder Market
Tools
Core Shooter Machine Market
Tools
Vinyl Bending Machine Market
Tools
Coil Fed Punching and Cutting Machines Market
Tools
Pruning Saw Market