
 Grader Blades Market | 2026-2036
Grader Blades Market Size, Share, and Industry Trends Forecast 2026-2036
Grader Blades Market Foresight
Mining fleet renewal is decoupling from traditional construction cycles as commodity producers prioritize uptime over capital deferral. Caterpillar Inc. leverages its integrated foundry network to control boron steel supply for high-wear applications. Komatsu Ltd. competes through telematics-linked blade monitoring that predicts replacement intervals. John Deere anchors its position in municipal road maintenance through dedicated dealer service contracts.
Grader blades are hardened steel or carbide-tipped cutting edges bolted to motor grader moldboards, engineered to Rockwell C 45-55 hardness for abrasion resistance and impact tolerance during road profiling and material spreading. Replaceable blades command expanding share as contractors minimize downtime through segmented changeouts rather than full-edge replacement. Carbide-tipped variants capture premium positioning in mining and quarrying where silica-laden aggregate accelerates wear rates, while standard steel blades dominate municipal budgets constrained by cyclical tax revenue.
EPA Tier 4 Final and OSHA silica exposure limits in the United States, plus REACH substance restrictions in Europe, are elevating documentation requirements for blade alloy compositions and worker safety during changeout procedures. Equipment Rental Companies face compliance cost pressure as regulatory scope widens from engine emissions to ground-engaging tool material traceability. Stakeholders must weigh captive blade production against specialist supplier partnerships as durability standards tighten and aftermarket data becomes a competitive barrier.
Market Dynamics
Emission standards are compressing equipment replacement cycles while simultaneously extending blade life requirements, creating tension between OEMs' foundry investments and contractor uptime demands.
Growth Catalysts
- EPA Tier 4 Final compliance:US contractors face accelerated fleet turnover timelines, pulling forward blade replacement demand as older graders retire ahead of enforcement deadlines.
- Silica-laden aggregate mining:Australian and Chilean copper operations prioritize carbide-tipped blade procurement to minimize unplanned downtime in high-abrasion extraction environments.
- Telematics integration:Predictive wear monitoring systems enable condition-based replacement scheduling, reducing emergency procurement and locking in supplier relationships.
Market Restraints
- Boron steel supply concentration:Integrated foundry networks control premium alloy feedstock, limiting specialist blade manufacturers' access to Rockwell C 50+ hardness material.
- REACH substance documentation:European alloy traceability requirements impose compliance costs that disproportionately burden small-scale aftermarket suppliers.
- Segmented blade substitution:Bolt-on carbide inserts threaten full-edge replacement volumes in municipal maintenance budgets.
Strategic Opportunities
- Western US infrastructure stimulus:State-level road maintenance contracts are expanding blade procurement volumes beyond traditional federal funding cycles.
- OSHA silica exposure alignment:Blade changeout procedure standardization creates certification service revenue streams for dealer networks.
- Telematics-to-procurement linkage:Real-time wear data integration with enterprise resource planning systems enables automated replenishment contracts.
Industry Challenges
- Weld repair technician scarcity:Moldboard rebuilding expertise is concentrating at OEM-authorized facilities, extending turnaround times for independent service providers.
- Legacy fleet interoperability:Proprietary blade mounting patterns from pre-Tier 4 equipment complicate aftermarket standardization efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grader Blades Market |
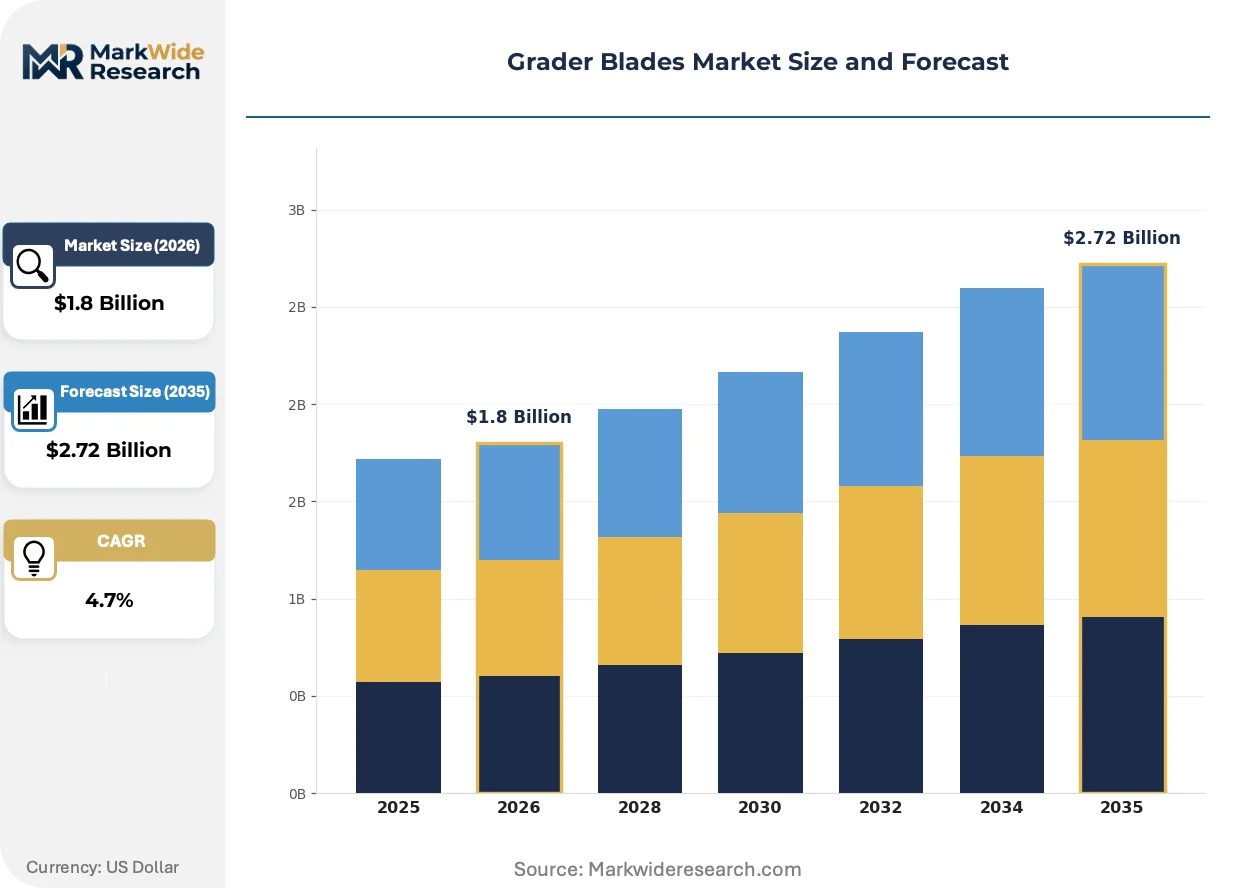
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Blades, Adjustable Blades, Replaceable Blades, Specialized Blades Material: Steel, Carbide, Alloy, Plastic Application: Construction, Mining, Agriculture, Landscaping End User: Contractors, Municipalities, Farmers, Equipment Rental Companies |
| Companies Covered | Caterpillar Inc., Komatsu Ltd., John Deere, Volvo Construction Equipment, Deere & Company, NMC CAT, MCE, Fortus, Kennametal Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grader Blades Market Shifts & Advancements
Blade lifecycle management is migrating from calendar-based replacement to data-driven intervention, compressing traditional procurement cycles while elevating supplier technical service obligations.
Carbide overlay deposition systems are automating localized hardfacing repair at mine-site workshops. Major copper producers in Chile and Australia deploy portable plasma-transferred arc units to rebuild cutting edges without moldboard removal. This capability is automating blade life extension decisions, shifting volume from new-blade procurement toward consumable overlay wire and technical service contracts.
EU Stage V emission standards are tightening documentation requirements for ground-engaging tool material composition. Equipment lessors face expanded traceability obligations under ECHA REACH substance restrictions, forcing alloy certification investments that favor integrated manufacturers over import-dependent distributors. Municipal fleets in Germany and France are consolidating procurement around suppliers with verified supply chain documentation.
Performance-based maintenance agreements are displacing transactional blade sales in Western US road maintenance contracts. State transportation departments in California and Texas unbundle blade supply from grader lease agreements, paying per linear mile graded rather than per edge installed. This model concentrates procurement authority with telematics-enabled fleet managers and compresses supplier margins on standardized steel blades while expanding carbide-tipped premium positioning.
Grader Blades Market Segmentation
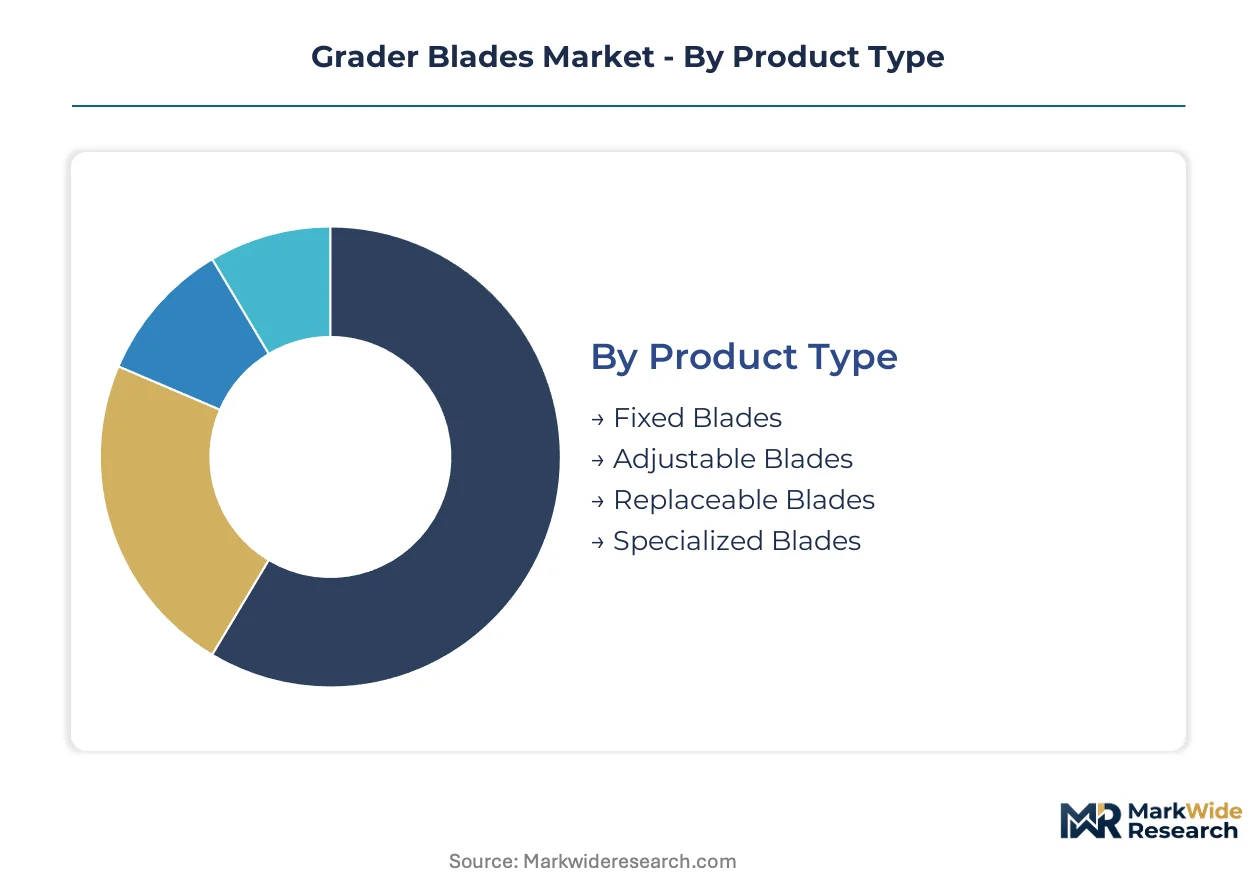
Grader blade procurement patterns diverge sharply between integrated fleet operators and independent contractors, with material specifications and replacement protocols reflecting distinct uptime economics across mining, municipal, and agricultural deployment contexts.
Product Type:
Standalone blade systems dominate high-wear mining environments where moldboard removal is impractical, while embedded adjustable configurations anchor municipal fleets requiring rapid profile changes.
- Fixed Blades:Permanently welded cutting edges engineered to Rockwell C 45-50 hardness specifications. Australian copper operations in Queensland and Western Australia specify fixed configurations for 24-hour extraction cycles where moldboard downtime exceeds blade replacement costs.
- Adjustable Blades:Mechanically variable attack-angle systems enabling real-time profile adaptation. State transportation departments in California and Texas deploy adjustable configurations across multi-terrain maintenance contracts where road crown specifications shift within single shifts.
- Replaceable Blades:Bolt-on segmented edges minimizing field service intervals. Contractors facing OSHA silica exposure limits during changeout procedures favor segmented replacement over full-edge handling.
- Specialized Blades:Custom-contoured edges for snow removal, ditching, and slope finishing applications. Municipalities in snow-belt regions specify carbide-enhanced specialized variants for ice-encrusted roadway rehabilitation.
Fixed blades lead volumes today; replaceable configurations are gaining share fastest.
Material:
Cost tier stratification separates premium wear-resistant alloys from commodity steel procurement, with carbide positioning commanding 3-4x unit economics in silica-intensive extraction environments.
- Steel:Standard carbon and boron-alloyed grades at Rockwell C 45-48 hardness. Municipal road maintenance budgets in cyclical tax-revenue environments anchor procurement around steel variants despite shorter replacement intervals.
- Carbide:Tungsten carbide inserts or overlay deposition systems delivering Rockwell C 65+ surface hardness. Chilean copper producers in the Atacama Desert prioritize carbide-tipped procurement where aggregate silica content accelerates wear rates by 40-60% versus standard construction materials.
- Alloy:Proprietary boron-manganese formulations from captive foundry networks. Equipment OEMs restrict premium alloy supply to authorized distribution channels, constraining independent aftermarket access.
- Plastic:Polymer-based edges for specialized finishing applications and spark-sensitive environments. Underground mining operations with methane exposure limits specify plastic variants for final-grade surface preparation.
Steel dominates unit volumes; carbide is climbing the fastest on value-weighted metrics.
Application:
Volume concentration in construction and mining masks divergent procurement rhythms, with agricultural demand exhibiting seasonal spike patterns distinct from infrastructure maintenance cycles.
- Construction:Road profiling, subgrade preparation, and material spreading across commercial and residential development. Western US state-level infrastructure stimulus programs are accelerating construction blade procurement beyond traditional federal funding timelines.
- Mining:Haul road maintenance, stockpile management, and pit floor grading in surface extraction operations. Australian and Chilean fleet renewal programs are decoupling mining blade demand from construction cyclicality.
- Agriculture:Field leveling, irrigation channel maintenance, and feedlot surface management. North American grain belt operations concentrate agricultural blade replacement in pre-planting and post-harvest windows.
- Landscaping:Golf course construction, residential estate grading, and commercial property development. Equipment rental companies serving landscaping contractors face compressed margins on standardized steel blade procurement.
Construction leads absolute volumes; mining is expanding most quickly on per-unit value terms.
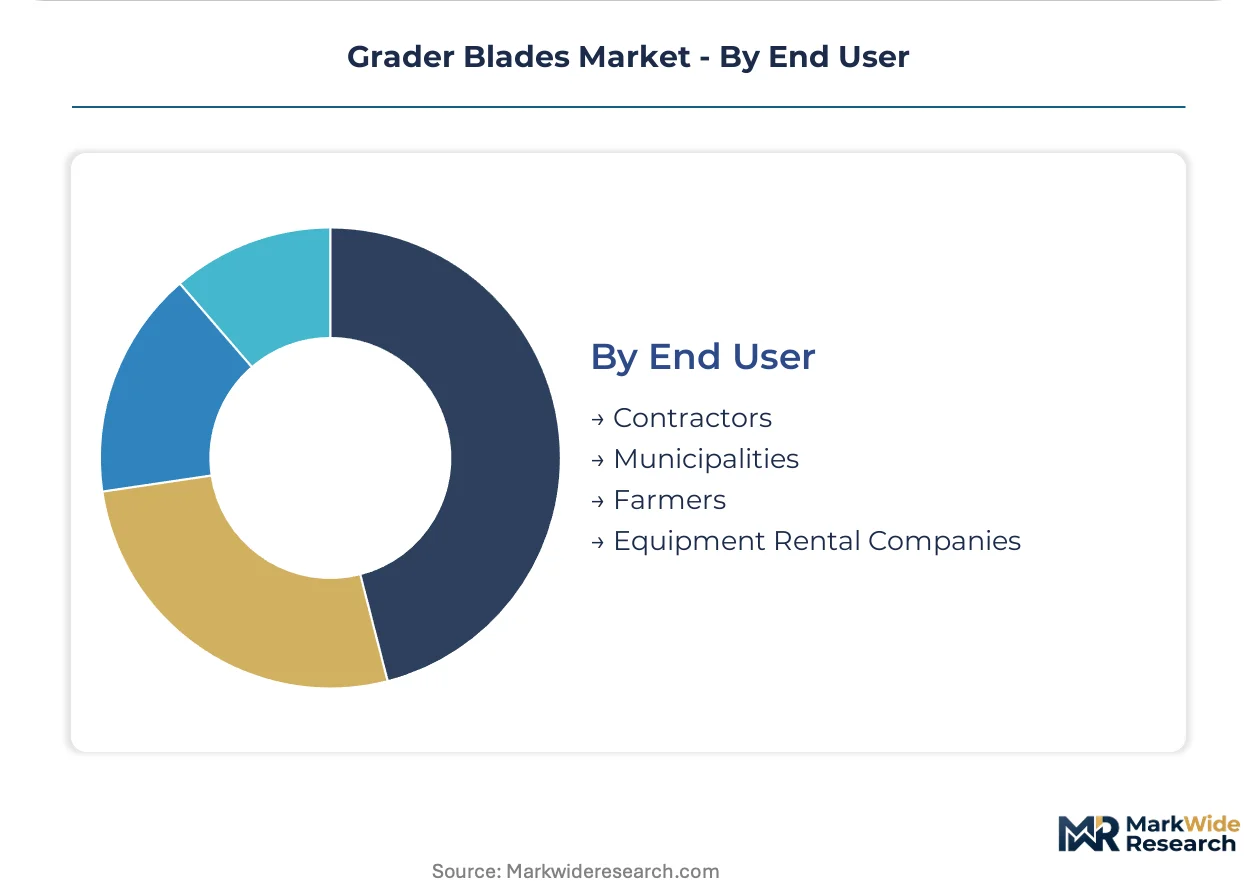
End User:
Customer type determines service integration depth, with municipalities and rental fleets demanding telematics-linked procurement systems unavailable to fragmented agricultural operators.
- Contractors:Independent construction and mining operators purchasing through dealer networks or direct OEM relationships. EPA Tier 4 Final compliance deadlines are accelerating contractor fleet turnover and blade replacement pull-forward.
- Municipalities:State and local transportation departments with performance-based maintenance agreements. California and Texas transportation departments unbundle blade supply from equipment leases, paying per linear mile graded rather than per edge installed.
- Farmers:Owner-operators and agricultural cooperatives with seasonal, price-sensitive procurement patterns. Agricultural blade demand correlates with commodity price cycles and equipment utilization rates.
- Equipment Rental Companies:National and regional fleet lessors facing expanded regulatory scope under OSHA silica exposure and REACH substance documentation requirements. Rental operators consolidate procurement around suppliers with verified alloy traceability to minimize compliance cost burden.
Contractors anchor current volumes; equipment rental companies are gaining share fastest through fleet consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping grader blade sourcing as EU REACH documentation costs push procurement toward jurisdictions with lighter alloy traceability burdens. Foundry investments are concentrating where emission standards remain less stringent than Stage V or Tier 4 Final thresholds.
United States
Western state infrastructure stimulus programs in California and Texas are accelerating road maintenance blade procurement beyond traditional federal funding cycles. EPA Tier 4 Final compliance deadlines are pulling forward fleet turnover and replacement demand. Arizona and Nevada mining operations concentrate carbide-tipped blade consumption for silica-intensive aggregate extraction.
Australia
Queensland and Western Australian copper producers prioritize 24-hour extraction uptime, driving fixed-blade specifications with Rockwell C 50+ hardness requirements. The country's national environmental regulator enforces strict mine site rehabilitation standards that extend blade life expectations. Perth-based fleet managers are consolidating procurement around telematics-linked predictive maintenance systems.
Chile
Atacama Desert copper operations command premium carbide-tipped positioning where aggregate silica content accelerates wear rates. The country's mining ministry enforces progressive closure obligations that elevate equipment durability standards. Antofagasta and Calama industrial clusters anchor South American blade demand for surface extraction haul road maintenance.
Germany
ECHA REACH substance restrictions impose alloy documentation costs that disadvantage import-dependent distributors against integrated foundry networks. Municipal fleets in Bavaria and North Rhine-Westphalia consolidate procurement around suppliers with verified supply chain certification. The KBA enforces equipment type-approval standards that complicate aftermarket blade interoperability.
China
Domestic boron steel production capacity supports captive supply chains for emerging OEM foundry networks. The Ministry of Ecology and Environment tightens dual carbon goals that elevate blade longevity requirements in state-owned mining operations. Shanxi and Inner Mongolia coal provinces concentrate domestic demand for high-wear ground-engaging tools.
Grader Blades Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated OEM foundry networks controlling premium alloy supply while independent fabricators serve price-sensitive municipal budgets. The vendor base organizes around three archetypes: captive foundry operators with backward integration into boron steel sourcing, telematics-enabled fleet service providers, and regional hardfacing specialists with portable repair capabilities. Dominant competitive moves include strategic partnerships linking wear data to automated procurement systems and capacity expansion in carbide overlay deposition technology.
Among diversified construction equipment manufacturers, Caterpillar Inc. and Komatsu Ltd. occupy positions exemplifying integrated foundry-to-fleet control, while John Deere anchors the agricultural and municipal maintenance archetype with dedicated dealer service networks. Kennametal Inc. represents the materials science specialist tier focused on carbide and advanced alloy solutions. These three named entities collectively illustrate how competitive positioning stratifies across alloy access, telematics integration depth, and regional service density.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Komatsu Ltd. |
| John Deere |
| Volvo Construction Equipment |
| Deere & Company |
| NMC CAT |
| MCE |
| Fortus |
| Kennametal Inc. |
| Others |
Supply & Pricing Matrix
Boron steel index movements cascade through foundry gate prices into three distinct procurement tiers: captive OEM supply, authorized dealer networks, and independent aftermarket channels. Australian mining operators absorb premium alloy costs through uptime guarantees, while municipal fleets in the western United States negotiate volume contracts that compress distributor margins on standardized carbon grades.
Pricing Analysis
Distributor margins separate carbide-tipped premium positioning from commodity steel procurement. Three-tier pricing structure across premium, standard, and economy levels reflects Rockwell hardness certification, with carbide variants commanding multiples over boron-alloyed grades. Price differentiation rests on foundry integration depth and telematics-enabled service bundling. Cost compression in municipal steel segments intensifies as state transportation departments unblade supply from equipment leases. Equipment rental companies exhibit highest price sensitivity due to compliance documentation burdens, while Chilean copper producers prioritize wear resistance over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale mining fleet demand, while dealer networks serve fragmented contractor markets. Geographic concentration centers on China for domestic boron steel production, the United States for integrated foundry networks, and Germany for REACH-compliant alloy certification. Raw material sourcing draws from Australian iron ore, Chilean copper concentrate, and domestic scrap steel recovery streams. Single-source vulnerability concentrates in captive OEM foundries controlling Rockwell C 50+ hardness formulations. Distribution runs through authorized service centers for telematics-linked procurement, with independent fabricators filling price-sensitive municipal gaps.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards geographic arbitrage between EU REACH documentation costs and lighter traceability regimes in Australia and Chile. Regulatory cost differentials of 15-20 percentage points separate compliant integrated manufacturers from import-dependent distributors.
For Market Incumbents: Extend telematics-to-procurement linkages into automated replenishment contracts before portable carbide overlay systems displace new-blade volumes. Deepen backward integration into boron steel sourcing to constrain independent aftermarket access to premium alloys. Lock in western US state transportation departments through performance-based per-mile agreements that standardize carbide-tipped specifications. For New Entrants and Emerging Players: Begin with portable hardfacing service contracts at Australian and Chilean mine-site workshops, where carbide overlay wire demand outpaces OEM blade replacement. Target equipment rental companies facing OSHA silica documentation burdens with certified changeout procedure packages. Penetrate through technical service partnerships rather than commodity blade manufacturing. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH compliance costs exceed 8% of revenue for import-dependent distributors. Long-term viability favors integrated foundry networks with captive alloy supply and telematics-enabled fleet relationships. Watch for inflection when western US infrastructure stimulus contracts convert from emergency procurement to multi-year performance agreements.| Strategic Initiative | Industry Significance |
|---|---|
| Carbide Overlay Deposition Capacity | Mine-site hardfacing automation shifts volume from new blades to consumable wire and technical contracts. |
| Telematics-ERP Integration | Real-time wear data linkage enables automated replenishment and locks in supplier relationships. |
| REACH Compliance Certification | Verified alloy traceability separates integrated manufacturers from burdened import distributors. |
| Performance-Based Maintenance Agreements | Per-mile pricing in California and Texas concentrates procurement with data-enabled fleet managers. |
| Portable Repair Service Networks | Plasma-transferred arc deployment at Chilean copper mines extends blade life without moldboard removal. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement covered maintenance directors at Australian copper operations, OEM procurement teams, aftermarket service heads, dealer network managers, and municipal fleet supervisors. Secondary validation drew from EPA Tier 4 Final enforcement timelines, ECHA REACH substance databases, state transportation department contract disclosures, and mining ministry closure obligation filings. Bottom-up blade volume estimates triangulated against top-down equipment fleet models.
Segment-weighting approaches distributed value across material tiers, product configurations, and end-user archetypes. The analytical framework modeled fixed, adjustable, replaceable, and specialized blade systems across construction, mining, agriculture, and landscaping applications. CAGRs derived from equipment replacement cycle compression, infrastructure stimulus timing, and fleet telematics penetration curves. Forecast inputs incorporated boron steel supply constraints and silica-laden aggregate wear coefficients.
Several conditions sit outside the modeled scope, including hypothetical relaxation of EPA emission enforcement, breakthroughs in polymer blade materials, and geopolitical disruption of Chilean copper concentrate flows. Forecasts reflect assumptions about regulatory compliance cost trajectories and OEM foundry capacity expansion. Periodic stress-testing of base assumptions is recommended against OSHA silica rulemaking progress and western US state budget continuity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Asia-Pacific Completion Equipment and Services Market
Construction Equipment
Track Mounted Gangway Market
Construction Equipment
GCC Mini Cranes Market
Construction Equipment
Earthing Equipment Market
Construction Equipment
Cold Forming Equipment Market
Construction Equipment
Robotic Total Stations (RTS) Market
Construction Equipment
Heavy Construction Equipment Rental Market
Construction Equipment
Collating Machinery Market
Construction Equipment
Automotive Surface Heat Treatment Furnaces Market
Construction Equipment
3-Wheel Sit-Down Counterbalance Forklift Market
Construction Equipment
Laser Beam Welding Equipment Market
Construction Equipment
Americas Hydraulic Submersible Pumps Market
Construction Equipment
Tunnel Boring Machines Market
Construction Equipment
Shotcrete Sprayer Market
Construction Equipment
Heating Roller Press Calender Machine Market
Construction Equipment
Hydraulic Shearing Machine Market