
 Manual Cutting Equipment Market | 2026-2036
Manual Cutting Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Manual Cutting Equipment Market Outlook
Carbon fiber composite blades is recalibrating cost-performance tradeoffs across premium manual cutting lines. Stanley Black & Decker leverages captive sourcing of hardened steel alloys to sustain margin stability in industrial shears. Robert Bosch GmbH anchors European distribution through certified dealer networks for professional-grade knives. Makita Corporation specializes in battery-compatible saw platforms that compete against traditional hand tools in Japanese construction.
Manual cutting equipment encompasses hand-operated tools engineered with Rockwell hardness ratings between 54 and 64 HRC, designed to sever materials through mechanical force without external power. These instruments serve primary industrial purposes in metal fabrication, woodworking, and textile processing where precision control exceeds automated throughput. Saws dominate volume flows in construction end-use channels where blade replacement cycles generate recurring revenue. Shears capture expanding share in automotive upholstery as OEMs specify ergonomic designs for repetitive assembly tasks. Titanium-grade material segments command premium positioning in food service applications requiring corrosion resistance under FDA sanitation protocols.
OSHA workplace safety mandates in the United States compel employers to specify cut-resistant gloves alongside certified blades, directly influencing procurement specifications. REACH substance restrictions in Europe constrain chromium plating processes, redirecting manufacturers toward ceramic coating alternatives for corrosion protection. BIS tool safety standards in India block uncertified imports, creating protected territory for domestic assemblers meeting IS 9873 test protocols. Stakeholders must monitor evolving alloy composition rules across multiple jurisdictions to anticipate supply chain requalification costs and certification lead times.
Market Dynamics
Carbon fiber composite blade technology is fragmenting traditional premium positioning in manual cutting equipment, forcing established suppliers to requalify sourcing strategies while specialty material entrants capture margin pools in automotive and aerospace upholstery channels.
Growth Catalysts
- OSHA workplace safety mandates:United States employers must specify cut-resistant gloves alongside certified blades, expanding bundled procurement specifications and driving replacement cycle frequency in industrial settings.
- Automotive upholstery specification:OEM assembly lines in Germany and Japan now require ergonomic shear designs for repetitive tasks, pulling carbon fiber reinforced models into high-volume production environments.
- BIS certification tightening:India's tool safety standards under IS 9873 protocols block uncertified imports, creating protected territory for domestic assemblers meeting workplace safety requirements.
Market Restraints
- Hardened steel alloy volatility:Captive sourcing dependencies concentrate input cost risk among suppliers lacking backward integration into specialty metallurgy supply chains.
- REACH substance restrictions:European chromium plating process bans redirect manufacturers toward ceramic coating alternatives, extending requalification timelines and compressing margin structures during transition periods.
- Battery-powered tool substitution:Makita Corporation's battery-compatible saw platforms compete directly against traditional hand tools in Japanese construction channels, eroding volume in core saw segments.
Strategic Opportunities
- Food service corrosion resistance:Titanium-grade material segments command premium positioning where FDA sanitation protocols require corrosion-resistant blade performance under aggressive cleaning regimens.
- Textile processing precision control:Shear manufacturers can penetrate garment district clusters in Bangladesh and Vietnam where automated throughput exceeds required precision tolerances for specialty fabric cutting.
- Dealer network certification:Robert Bosch GmbH's European distribution model through certified professional-grade knife dealers offers template for margin-protected channel control in fragmented markets.
Industry Challenges
- Multi-jurisdiction alloy requalification:Stakeholders face supply chain friction from evolving composition rules across OSHA, REACH, and BIS jurisdictions, extending certification lead times and inventory risk.
- Rockwell hardness calibration expertise:Blade production requires specialized metallurgical knowledge for 54-64 HRC rating consistency, constraining workforce availability in emerging manufacturing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Manual Cutting Equipment Market |
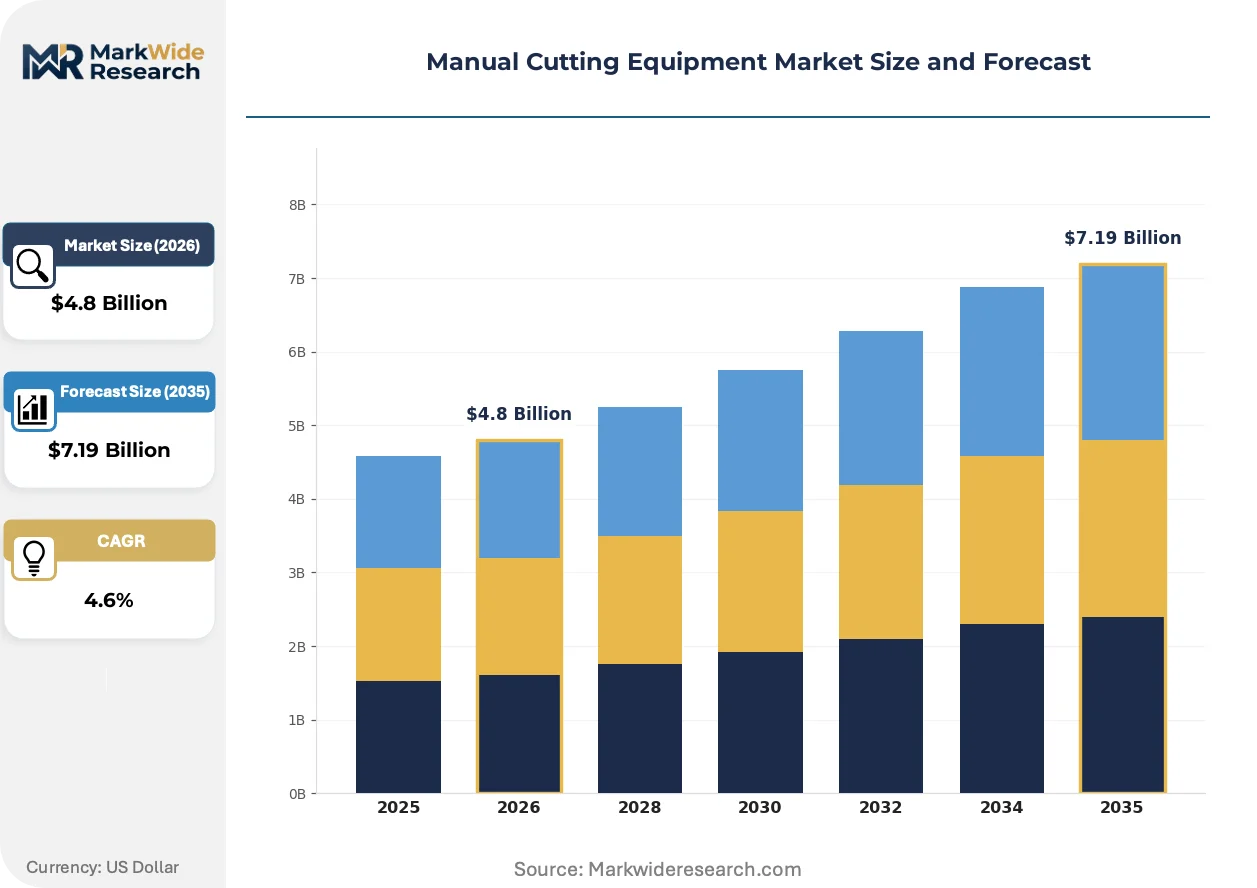
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scissors, Knives, Saws, Shears Material: Steel, Titanium, Carbon Fiber, Plastic End User: Construction, Food Service, Automotive, Arts & Crafts Application: Woodworking, Upholstery, Metal Fabrication, Gardening |
| Companies Covered | Stanley Black & Decker, Inc., Robert Bosch GmbH, Makita Corporation, Hilti Corporation, Illinois Tool Works Inc., Snap-on Incorporated, Techtronic Industries, Lincoln Electric Company, Hypertherm, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Manual Cutting Equipment Market Strategic Shifts
Material science advances and regulatory chemistry restrictions are actively restructuring competitive advantage in blade manufacturing, separating suppliers capable of rapid coating substitution from those locked in legacy metallurgy investments.
Carbon fiber reinforced shear construction is modularizing product architecture across premium manual cutting lines. Automotive upholstery OEMs in Germany specify these platforms for repetitive assembly tasks requiring reduced operator fatigue. The technology is modularizing cost-performance tradeoffs by enabling blade replacement without full tool retirement.
REACH substance restrictions in Europe constrain chromium plating processes for corrosion protection. Manufacturers redirect toward ceramic coating alternatives that satisfy ECHA compliance timelines while maintaining blade longevity. Professional-grade knife distribution channels face compressed margin recovery periods during this coating transition.
Certified dealer networks now dominate procurement preferences for high-specification cutting tools in European construction. Traditional wholesale distributors lose share to authorized service channels that bundle blade replacement programs with original equipment sales. This channel consolidation concentrates most visibly in German and French metropolitan construction supply clusters.
Manual Cutting Equipment Market Segmentation
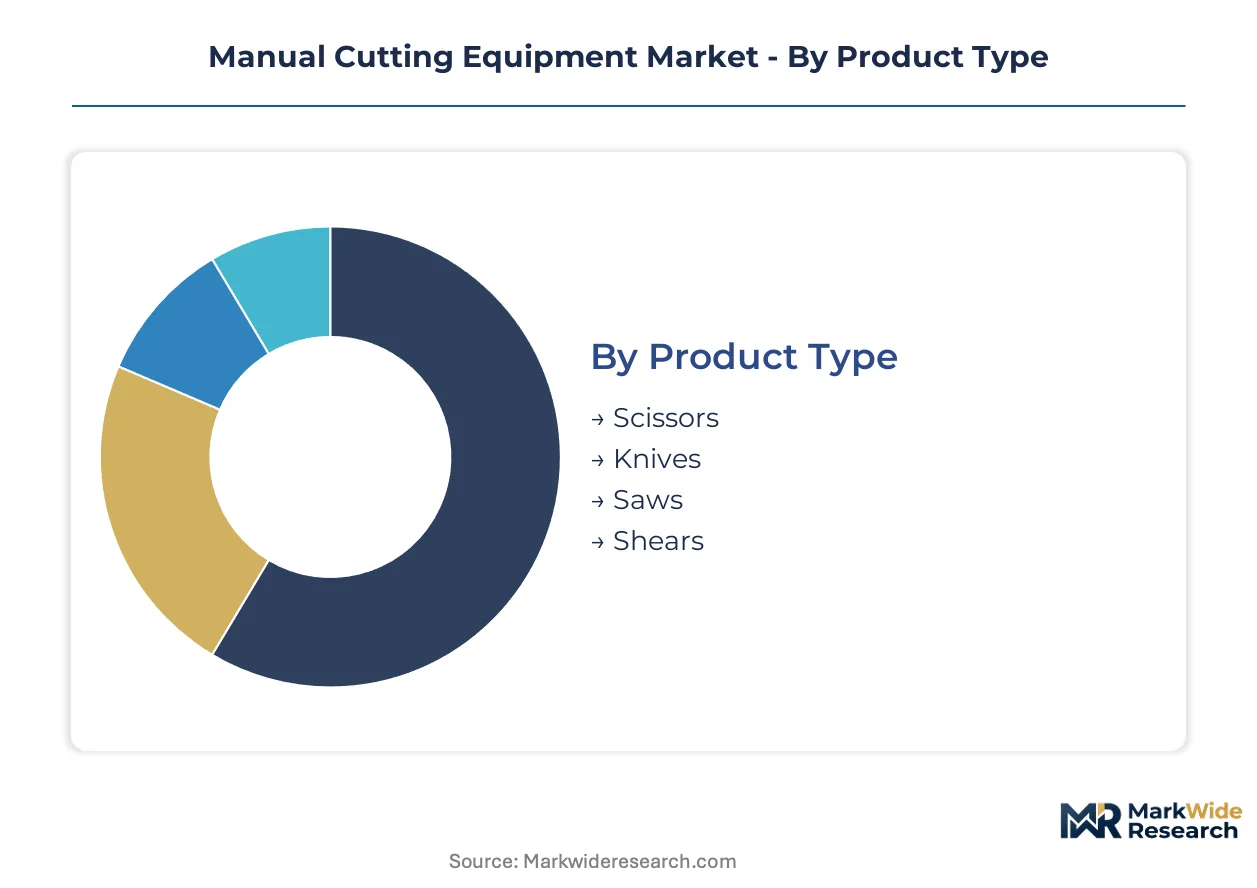
Manual cutting equipment manufacturers calibrate product portfolios across four distinct category axes. Each segmentation dimension reveals divergent margin structures, certification requirements, and procurement channel preferences that shape competitive positioning.
Product Type:
Buyers differentiate primarily by replacement cycle economics and blade reconditioning service availability.
- Saws:Construction trades favor these for structural material severing where blade replacement programs generate recurring revenue. Volume concentrates in Japanese and German metropolitan supply clusters where certified dealer networks bundle maintenance contracts with original equipment.
- Shears:Ergonomic carbon fiber reinforced models serve automotive upholstery assembly lines in Germany and Japan. OEM specifications for repetitive task efficiency pull premium variants into high-volume production environments.
- Knives:Professional-grade variants distribute through authorized service channels in European construction markets. Rockwell hardness ratings between 54 and 64 HRC distinguish industrial from consumer tiers.
- Scissors:Textile processing applications in Bangladesh and Vietnam demand precision control where automated throughput exceeds required tolerances for specialty fabric cutting.
Saws lead volumes today; shears are gaining share fastest.
Material:
Raw material selection determines corrosion resistance thresholds and regulatory compliance pathways across jurisdictions.
- Steel:Hardened alloy variants dominate industrial shears through captive sourcing strategies that sustain margin stability. REACH substance restrictions in Europe constrain traditional chromium plating processes, redirecting manufacturers toward ceramic coating alternatives.
- Carbon Fiber:Composite blade construction modularizes cost-performance tradeoffs by enabling replacement without full tool retirement. Automotive upholstery OEMs in Germany specify these platforms for reduced operator fatigue in repetitive assembly tasks.
- Titanium:Food service applications command premium positioning where FDA sanitation protocols require corrosion-resistant performance under aggressive cleaning regimens.
- Plastic:Consumer-grade disposable variants serve arts and crafts segments where Rockwell hardness calibration is unnecessary.
Steel dominates installed base; carbon fiber shows steepest expansion trajectory.
End User:
Procurement specifications vary sharply by workplace safety mandate intensity and bundled PPE requirements.
- Construction:OSHA workplace safety mandates in the United States compel cut-resistant glove pairing with certified blades, expanding bundled procurement specifications.
- Automotive:Assembly line ergonomics specifications in Germany and Japan drive carbon fiber reinforced shear adoption for repetitive tasks.
- Food Service:FDA corrosion resistance requirements under aggressive sanitation regimens favor titanium-grade material segments.
- Arts & Crafts:Price-sensitive hobbyist demand concentrates in plastic and standard steel variants through mass retail channels.
Construction anchors volume; automotive is climbing the fastest.
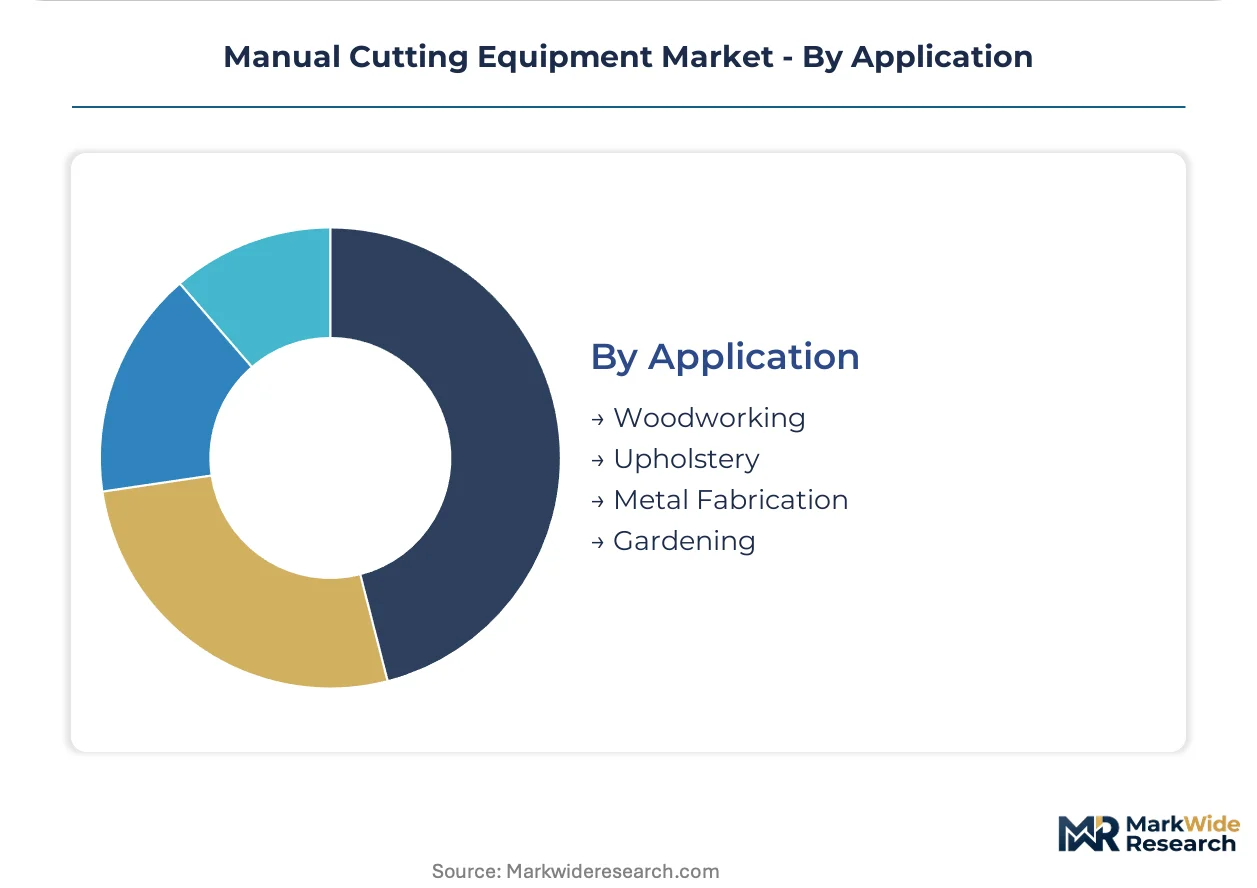
Application:
Precision tolerance requirements and material hardness determine tool specification intensity across use cases.
- Metal Fabrication:Rockwell hardness ratings between 54 and 64 HRC prove essential for severing hardened alloys without edge deformation.
- Upholstery:Automotive OEMs in Germany and Japan specify ergonomic shear designs for repetitive fabric and composite material cutting.
- Woodworking:Saw platforms compete against Makita Corporation battery-compatible alternatives in Japanese construction channels.
- Gardening:Seasonal replacement cycles characterize this segment where corrosion resistance requirements remain modest.
Metal fabrication leads volumes today; upholstery is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive upholstery clusters anchor regional demand concentration for ergonomic carbon fiber shears. OSHA workplace safety mandates in the United States expand bundled procurement specifications. India's BIS certification tightening creates protected territory for domestic assemblers.
United States
Construction contractors drive saw replacement cycles through certified dealer networks bundling maintenance contracts. OSHA mandates compel cut-resistant glove pairing with certified blades in industrial settings. Midwest metropolitan supply clusters concentrate volume flows where blade replacement programs generate recurring revenue.
Germany
Automotive OEM assembly lines specify ergonomic shear designs for repetitive upholstery tasks. REACH substance restrictions redirect manufacturers toward ceramic coating alternatives for corrosion protection. Stuttgart and Munich metropolitan construction supply clusters favor authorized service channels over traditional wholesale distribution.
Japan
Battery-compatible saw platforms compete against traditional hand tools in construction channels. METI industrial standards guide procurement specifications for professional-grade cutting instruments. Osaka and Nagoya automotive upholstery clusters pull carbon fiber reinforced models into high-volume production environments.
India
Domestic assemblers capture protected territory as BIS tool safety standards block uncertified imports under IS 9873 protocols. Construction contractors drive adoption amid tightening workplace safety requirements. Maharashtra and Gujarat industrial corridors concentrate demand for certified workplace safety tools.
China
Textile processing applications in garment district clusters demand precision control where automated throughput exceeds required tolerances. GB standards govern blade hardness ratings for industrial applications. Yangtze River Delta manufacturing hubs concentrate shear production for export markets.
Manual Cutting Equipment Market Competitive Environment
Global majors compete with regional champions across distribution channel certification and metallurgical sourcing strategies. The vendor base organizes around three tiers: diversified industrial conglomerates with captive alloy supply, specialized cutting tool manufacturers with dealer network control, and regional fabricators serving protected domestic markets. Strategic differentiation centers on backward integration into specialty steel supply chains and certified dealer network expansion.
Among diversified industrial conglomerates, Stanley Black & Decker, Inc. and Robert Bosch GmbH occupy positions defined by scale-driven sourcing advantages and European distribution infrastructure. Makita Corporation exemplifies the specialist tier with battery-compatible platform development. These three anchors represent distinct competitive vectors: captive metallurgy, certified channel control, and power tool convergence.
| Leading Market Players |
|---|
| Stanley Black & Decker, Inc. |
| Robert Bosch GmbH |
| Makita Corporation |
| Hilti Corporation |
| Illinois Tool Works Inc. |
| Snap-on Incorporated |
| Techtronic Industries |
| Lincoln Electric Company |
| Hypertherm, Inc. |
| Others |
Value Chain & Pricing Dynamics
Ceramic coating substitution for REACH-compliant corrosion protection is simultaneously elevating production costs and redistributing manufacturing capacity toward European suppliers with in-house coating capabilities. This technology transition compresses margin recovery timelines while concentrating supply leverage among metallurgical specialists capable of rapid process requalification.
Pricing Analysis
Input-cost pass-through from hardened steel alloy volatility and ceramic coating requalification expenses is intensifying margin pressure across mid-tier suppliers lacking captive metallurgy sourcing. Pricing stratifies across premium certified tiers, standard professional-grade, and economy consumer levels, with certification grade and after-sales service bundling as primary differentiation drivers. Cost compression in standard tiers reflects battery-powered tool substitution from Makita Corporation platforms. Construction contractors demonstrate highest price sensitivity, while automotive OEMs in Germany and Japan exhibit lowest sensitivity due to ergonomic specification mandates.
Supply Chain Analysis
Workforce availability constraints in Bangladesh and Vietnam garment districts limit shear production scaling for textile processing applications. Manufacturing concentrates in China, Germany, and India, with supply chains drawing from specialty steel mills, carbon fiber composite suppliers, and ceramic coating chemical providers. Single-source vulnerability persists in hardened alloy supply chains where captive sourcing dominates. Distribution runs through certified dealer networks in European construction markets and traditional wholesale channels in price-sensitive segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where OSHA workplace safety mandates, REACH substance restrictions, and BIS certification tightening collectively expand replacement cycle frequency and specification intensity across multiple jurisdictions.
For Market Incumbents: Acquire ceramic coating process expertise to offset REACH-driven chromium plating obsolescence. Secure backward integration into hardened steel alloy supply chains to neutralize input cost volatility threatening margin stability. Expand certified dealer network coverage in German and French metropolitan construction clusters to defend against battery-powered platform substitution from Makita Corporation. For New Entrants and Emerging Players: Certified dealer partnerships in fragmented European construction markets offer channel access with lower capital requirements than direct distribution buildout. Target food service titanium-grade segments in North America where FDA corrosion resistance protocols create specification barriers for established steel-centric suppliers. Pursue white-label manufacturing arrangements with domestic Indian assemblers leveraging BIS certification protected territory. For Investors and Strategic Acquirers: Roll-up economics work for regional cutting tool specialists with established BIS, OSHA, or REACH certification portfolios because regulatory compliance creates customer switching costs and extends competitive moats. Mid-cap targets with captive metallurgy sourcing and dealer network density in automotive upholstery clusters present strongest long-term viability over a multi-year holding period. Monitor battery-powered platform adoption rates in Japanese construction channels as inflection indicator for traditional hand tool demand erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Coating Process Investment | REACH compliance enables continued European market access for corrosion-protected blade lines. |
| Certified Dealer Network Expansion | Authorized service channels in Stuttgart and Munich bundle replacement programs with original equipment sales. |
| Carbon Fiber Composite Sourcing | Automotive OEM specifications in Germany and Japan demand ergonomic shear platforms for repetitive assembly tasks. |
| BIS Certification Acquisition | IS 9873 protocol compliance creates protected territory for domestic assemblers in Maharashtra and Gujarat industrial corridors. |
| Battery-Compatible Platform Development | METI-guided procurement specifications in Japanese construction channels favor power tool convergence strategies. |
Study Parameters
Bottom-up construction and automotive upholstery modeling reconciled against top-down hardened steel alloy and carbon fiber composite supply tracking forms the analytical core of this study. Primary interviews with maintenance directors at metal fabrication facilities, procurement leads at German automotive OEMs, aftermarket service heads at European distributor networks, and plant engineers at Indian domestic assemblers combined with secondary validation from OSHA enforcement databases, ECHA substance restriction filings, BIS certification registries, and customs trade flow records. Triangulation between demand-side specification tracking and supply-side capacity mapping ensures coverage of both procurement pattern evolution and manufacturing concentration shifts.
Input-output matrices linking Rockwell hardness rating requirements to alloy composition costs, ceramic coating process economics to REACH compliance timelines, and dealer network density to regional construction supply cluster characteristics structured the projection framework across the analysis window. Segmentation dimensions modeled include product type, material grade, end-user industry, and application precision requirements. CAGRs derived from replacement cycle frequency analysis, regulatory mandate implementation schedules, and technology substitution elasticity parameters. Forecast inputs incorporated BIS certification penetration rates in Indian industrial corridors and battery-powered platform adoption curves in Japanese construction channels.
Revisions become necessary when REACH substance restriction scope expands beyond chromium plating, OSHA mandates extend to additional PPE bundling requirements, or BIS certification protocols tighten testing standards for workplace safety tools. Forecasts reflect assumptions regarding regulatory implementation timelines, alloy supply chain stability, and technology substitution rates. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Surface Levelling Equipment Market
Tools
Pneumatic Bolting Tools Market
Tools
Fixed Cutter Bits Market
Tools
Mechanical Springs Market
Tools
Fastening Power Tools Market
Tools
Powder Compacting Pressers Market
Tools
Saw Blades Market
Tools
Hand Saw Market
Tools
Tile Cutter Market
Tools
Scroll Saws Market
Tools
Ripper Market
Tools
Air Hammer Market
Tools
Foam Engraving Machines Market
Tools
Europe Power Tools Market
Tools
Digital Laser Levels Market
Tools
Shredder Blades Market