
 Rivet Gun Market | 2026-2036
Rivet Gun Market Size, Share, and Industry Trends Forecast 2026-2036
Rivet Gun Market Analysis
Aerospace assembly is broadening its share of premium rivet gun procurement as narrow-body production schedules tighten. Stanley Black & Decker leverages its battery platform crossover from construction to aviation maintenance. GESIPA Blindniettechnik GmbH anchors German industrial demand with specialized blind rivet systems. Atlas Copco AB dominates factory-automation channels with integrated pneumatic feed systems.
A rivet gun is a mechanical or powered fastening tool that applies controlled impact force to deform rivet bodies and create permanent joints, typically operating at stroke pressures between 80 and 120 PSI for pneumatic variants or 18-20V lithium-ion outputs for cordless units. Its primary purpose spans structural assembly in airframes, vehicle chassis, and steel building frameworks where welded or threaded connections prove impractical. Pneumatic rivet guns still occupy the majority of factory-floor installations due to raw torque density and tool longevity, though battery-powered rivet guns are capturing mobile maintenance and construction sites where hose tethering limits access. Among end users, manufacturers sustain the deepest replacement cycles while contractors and maintenance providers drive shorter-horizon purchasing.
FAA airworthiness directives and OSHA workplace noise exposure limits shape product certification and workplace deployment requirements for rivet gun manufacturers serving North American aviation and construction. REACH substance restrictions in Europe constrain lubricant formulations and surface coatings used in pneumatic tool maintenance, pushing vendors toward dry-component redesigns. Stakeholders must monitor how dual carbon goals in China and the EU Green Deal's embodied-carbon tracking extend from steel rivets to the tools that install them.
Market Dynamics
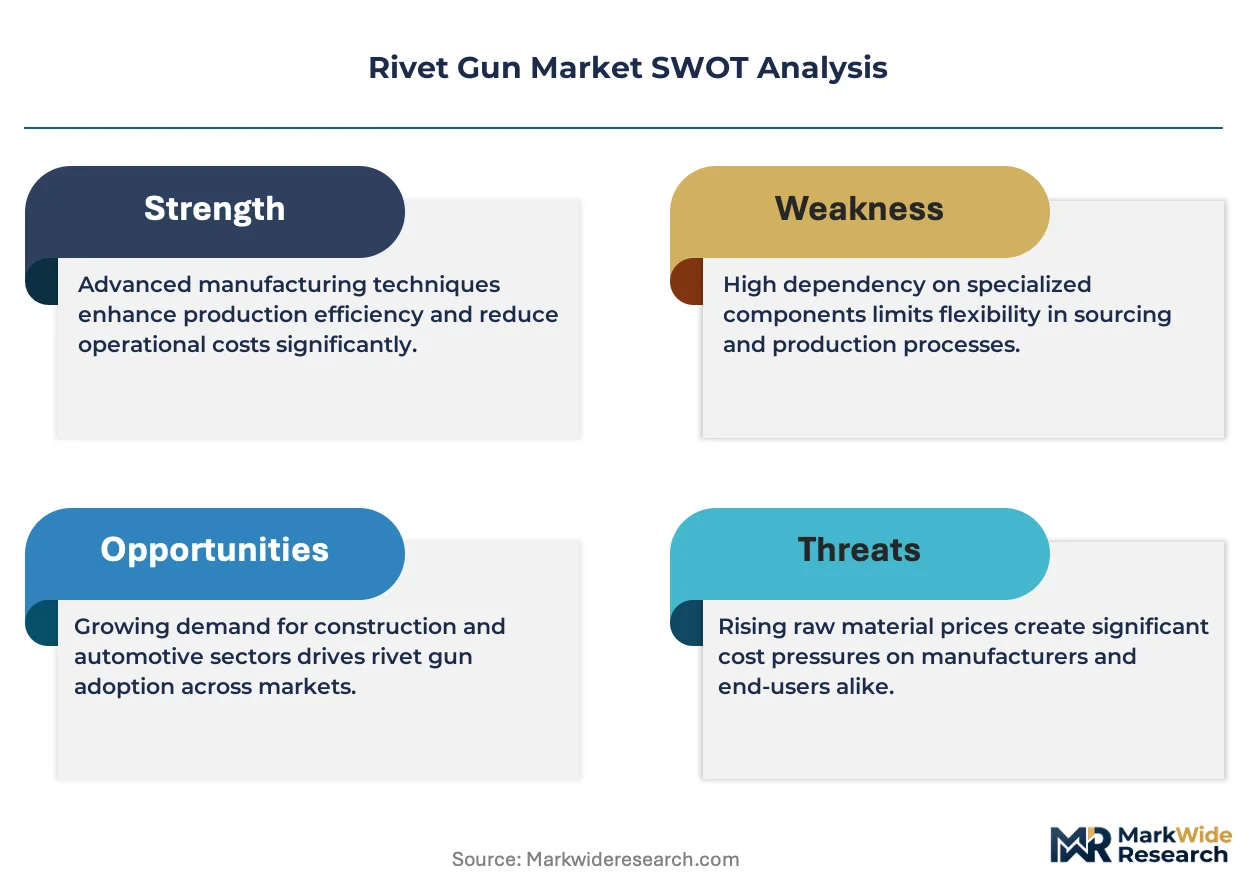
Battery-powered rivet gun platforms are consolidating factory and maintenance floor deployments as REACH compliance on compressed air oil mist forces European operators toward cordless alternatives. This technological pivot reshapes procurement patterns across aerospace, automotive, and construction verticals.
Growth Catalysts
- Narrow-body aerospace production:OEM assembly line expansion in North America and Asia-Pacific drives premium tool procurement for aluminum and composite fastening operations.
- REACH substance restrictions:ECHA lubricant formulation limits on pneumatic maintenance push German and French operators toward dry-component battery systems.
- Lithium-ion energy density:18-20V battery platforms now deliver torque parity with 80-120 PSI pneumatic equivalents, enabling untethered access in shipyard and wind tower applications.
Market Restraints
- Lithium cell cost volatility:Raw material price swings for cobalt and nickel concentrate input cost risk for cordless platform manufacturers.
- Pneumatic infrastructure lock-in:Existing compressed air networks in US Midwest automotive plants create switching friction and extend replacement cycles.
- Specialized fastener geometries:Blind rivet systems for composite airframes require tool calibration precision that generic platforms cannot replicate.
Strategic Opportunities
- Indian defense manufacturing:PLI scheme incentives for indigenous aerospace component production create demand for precision fastening tools in Bengaluru and Hyderabad clusters.
- EU Green Deal embodied-carbon tracking:Tool lifecycle certification requirements favor repairable modular designs over sealed disposable units.
- Telematics-enabled fleet management:IoT sensor integration in contractor tool pools allows usage-based rental pricing and predictive maintenance scheduling.
Industry Challenges
- Aviation maintenance technician certification:FAA airworthiness directive compliance for power tool calibration demands specialized training programs that lag tool technology evolution.
- Legacy pneumatic system integration:Battery platform retrofits in European maintenance hangars require hose-routing reconfiguration and workspace redesign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rivet Gun Market |
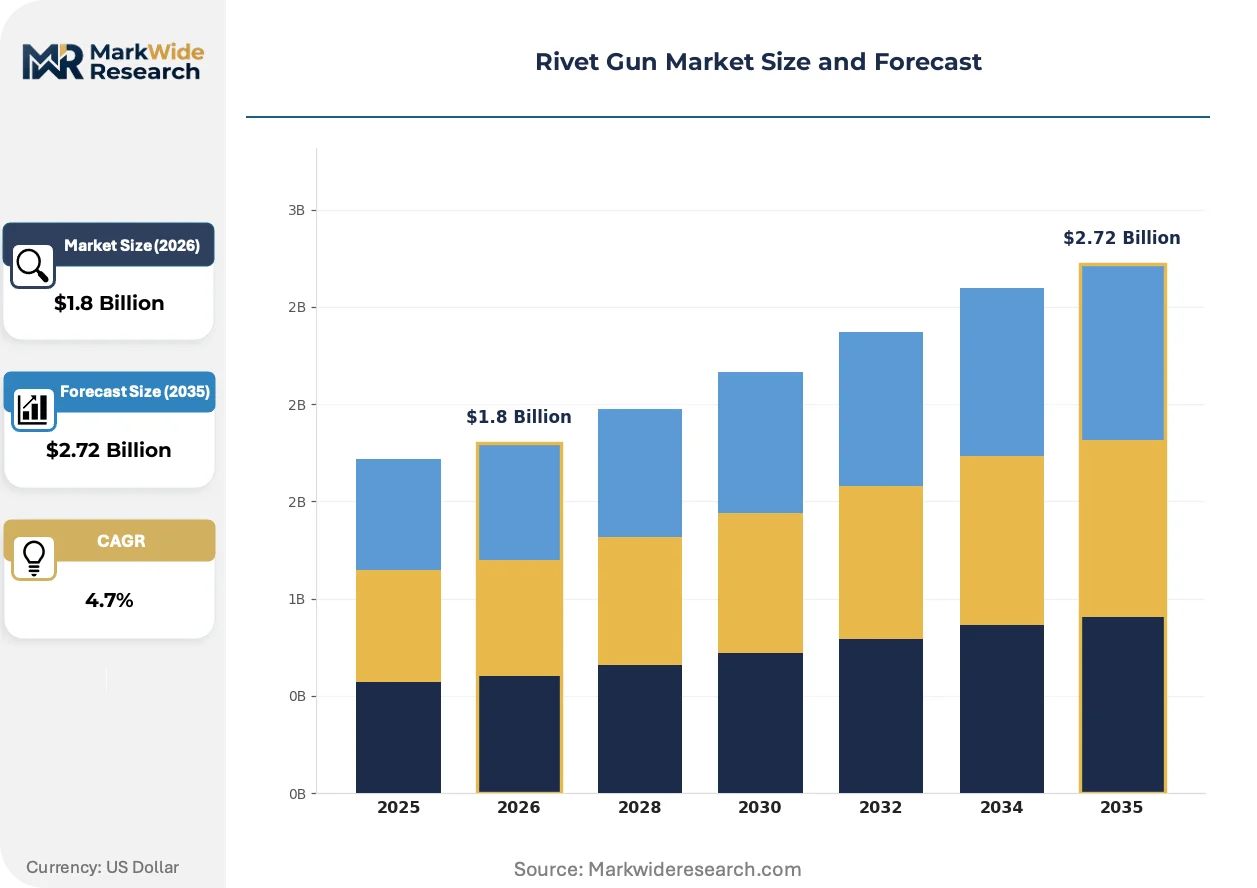
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pneumatic Rivet Guns, Electric Rivet Guns, Manual Rivet Guns, Battery-Powered Rivet Guns Application: Aerospace, Automotive, Construction, Machinery Assembly End User: Manufacturers, Contractors, DIY Enthusiasts, Maintenance Providers Technology: Hydraulic, Mechanical, Ultrasonic, Laser |
| Companies Covered | Stanley Black & Decker, Inc., Malco Products, GESIPA Blindniettechnik GmbH, Honsel Umformtechnik GmbH, Fastening Systems International Inc., Arconic Inc., Degometal, Campbell Hausfeld, Atlas Copco AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rivet Gun Market Emerging Trajectories
Tool intelligence and energy platform convergence are redefining competitive differentiation in rivet gun manufacturing. Three developments are compressing traditional hardware margins while opening service-revenue streams.
Brushless DC motor architectures with integrated torque feedback are consolidating mid-duty fastening applications previously split between pneumatic and manual tools. Aerospace MRO providers in Germany and France are standardizing on these platforms for A320 and B737 line maintenance. The technology is consolidating supplier tiers as motor-controller module sourcing becomes decisive for performance parity.
OSHA workplace noise exposure limits and EU machinery directive updates are mandating sub-85 decibel operation for eight-hour shift compliance. Pneumatic tool manufacturers face acoustic engineering investments or market exit in regulated jurisdictions. North American construction contractors are preemptively specifying low-noise battery units to avoid citation exposure and hearing conservation program costs.
Maintenance providers are unbundling tool ownership from fastener supply, shifting toward per-rivet service agreements with guaranteed joint quality metrics. This consumption-pattern shift compresses capital expenditure for regional airlines and contract assembly shops. The model is most visible in Scandinavian markets where sustainability reporting requirements favor operational expenditure treatment over asset-heavy balance sheets.
Rivet Gun Market Segmentation
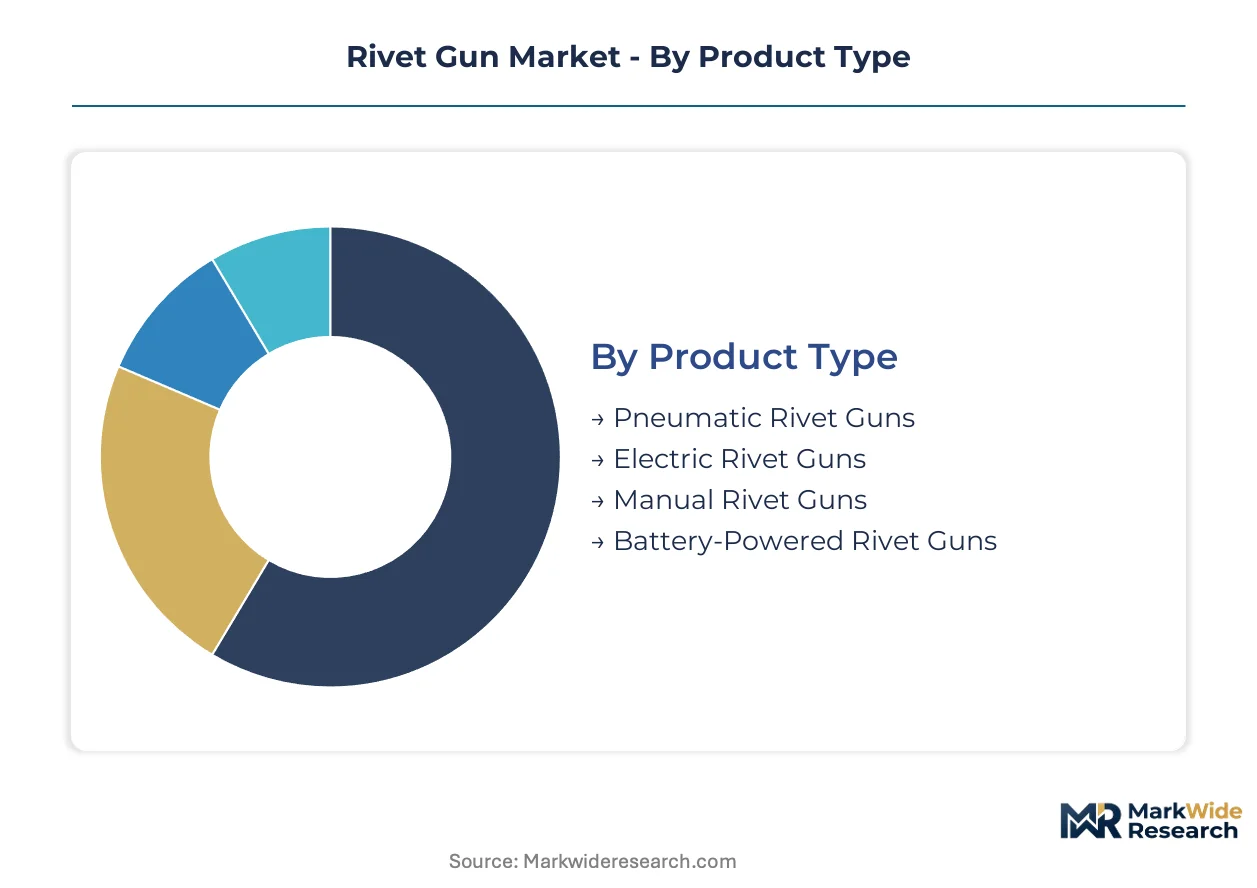
Rivet gun procurement patterns diverge sharply between factory-floor standardization and field-service customization. Aerospace OEMs demand calibrated precision platforms, while construction contractors prioritize interchangeability across job sites. Understanding these fault lines reveals where margin pools concentrate and which technology transitions will reshape supplier economics.
Product Type:
Customization intensity ranges from sealed pneumatic systems requiring plant infrastructure to modular battery platforms adaptable across maintenance scenarios.
- Battery-Powered Rivet Guns:Lithium-ion 18-20V platforms deliver torque parity with legacy pneumatic units while eliminating hose tethering. German MRO hangars under ECHA REACH oil-mist restrictions are converting entire fleets to cordless systems for A320 line maintenance access.
- Pneumatic Rivet Guns:Compressed air systems operating at 80-120 PSI dominate high-volume factory installations where raw torque density and tool longevity outweigh mobility needs. US Midwest automotive plants retain deep infrastructure lock-in, extending replacement cycles despite efficiency penalties.
- Electric Rivet Guns:Corded AC-motor units serve fixed-station assembly where power consistency trumps portability requirements.
- Manual Rivet Guns:Hand-operated lever tools persist in low-volume repair and confined-space applications where power tool access proves impractical.
Leading the category by volume: Pneumatic Rivet Guns. Expanding most quickly: Battery-Powered Rivet Guns.
Application:
Cost tier stratification separates premium aerospace certification requirements from price-sensitive construction bulk procurement.
- Aerospace:Structural airframe fastening demands calibrated stroke control and FAA airworthiness directive traceability. Narrow-body production ramp rates in North America and Asia-Pacific are accelerating premium tool procurement for aluminum and composite rivet geometries.
- Construction:Steel framework and facade assembly drives high-volume, shorter-lifecycle purchasing where contractor fleet turnover outlasts precision specifications. OSHA sub-85 decibel mandates are preemptively shifting specifications toward low-noise battery alternatives.
- Automotive:Chassis and body-in-white applications balance cycle-time pressure with joint quality consistency across mixed-material platforms.
- Machinery Assembly:Industrial equipment production favors standardized fastening platforms with rapid bit-change capability for mixed fastener populations.
Deepest margin capture: Aerospace. Steepest volume expansion: Construction.
End User:
Customer type determines procurement rhythm — capital-intensive manufacturers versus operational-expenditure contractors.
- Manufacturers:OEM assembly lines sustain 7-10 year replacement cycles with integrated pneumatic feed systems and predictive maintenance scheduling. Factory automation investments favor vendor-managed inventory and guaranteed uptime contracts.
- Contractors:Construction and MRO service providers drive 18-36 month refresh rates, prioritizing tool pool telematics and usage-based rental pricing over ownership. Scandinavian markets exhibit strongest per-rivet service agreement adoption.
- Maintenance Providers:Aviation MRO specialists require calibration-certification documentation aligned with FAA directive compliance, creating training program dependencies that lag tool technology evolution.
- DIY Enthusiasts:Consumer-grade cordless platforms serve home improvement and hobbyist applications with limited specification demands.
Longest replacement horizon: Manufacturers. Fastest procurement velocity: Contractors.
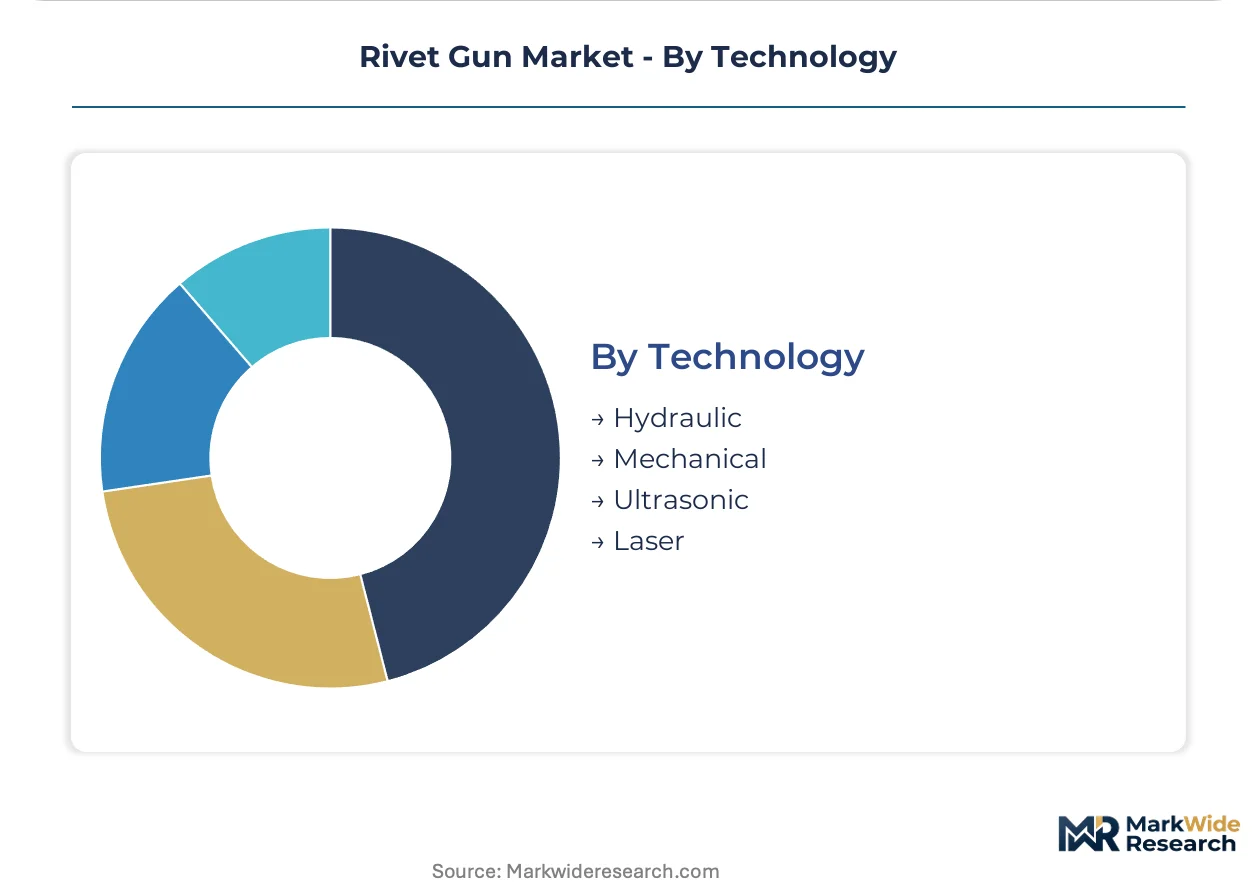
Technology:
Maturity gradient spans century-old mechanical systems to emerging solid-state joining methods with unproven scale economics.
- Mechanical:Impact and squeeze riveting systems retain dominance across legacy airframe and structural steel applications where process familiarity outweighs innovation incentives.
- Hydraulic:Fluid-power systems deliver controlled force application for large-diameter rivets in shipyard and heavy machinery contexts.
- Ultrasonic:High-frequency vibration welding of thermoplastic composites is penetrating aerospace secondary structures where metal fastener corrosion risks mandate material transition.
- Laser:Directed-energy rivetless joining remains developmental for thin-gauge aluminum panels, constrained by capital intensity and joint accessibility limitations.
Widest installed base: Mechanical. Gaining share fastest: Ultrasonic.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany produces the majority of precision fastening systems exported worldwide, while the United States and China absorb the largest import volumes for aerospace and construction applications respectively. Domestic manufacturing capacity concentrates in industrial clusters with deep automotive and aviation supplier networks. Regulatory divergence between ECHA REACH restrictions and FAA airworthiness directives shapes regional procurement specifications.
United States
Boeing's 737 MAX production recovery and narrow-body assembly expansion in Renton, Washington drive premium tool procurement for aluminum airframe fastening. FAA airworthiness directives mandate calibration traceability for power tools used in commercial aviation maintenance. Midwest automotive plants in Michigan and Ohio retain pneumatic infrastructure lock-in, delaying battery platform conversion despite efficiency penalties.
Germany
GESIPA and Honsel anchor industrial riveting clusters in Sauerland and North Rhine-Westphalia, supplying blind rivet systems for European aerospace MRO operations. ECHA REACH compliance on compressed air oil mist forces maintenance hangars in Hamburg and Frankfurt toward cordless battery platforms. The country's dual carbon goals under EU Green Deal frameworks accelerate embodied-carbon tracking requirements for tool lifecycle certification.
China
COMAC C919 narrow-body production ramp-up in Shanghai drives domestic procurement of calibrated fastening equipment for composite and aluminum joint assemblies. The country's dual carbon targets constrain energy-intensive pneumatic compressor operations in Yangtze River Delta manufacturing zones. Tianjin and Xi'an aviation clusters import precision riveting systems to meet civil aviation regulator certification requirements for indigenous aircraft programs.
India
PLI scheme incentives for indigenous aerospace component production create demand for precision fastening tools in Bengaluru and Hyderabad defense manufacturing clusters. The country's national aviation regulator mandates tool calibration documentation aligned with international airworthiness standards. Tata Advanced Systems and Mahindra Aerospace assembly operations in Karnataka and Telangana states drive import substitution for previously sourced European riveting equipment.
France
Airbus A320 final assembly lines in Toulouse and Hamburg-sourced component integration sustain premium rivet gun procurement for narrow-body production schedules. EU machinery directive updates mandating sub-85 decibel workplace exposure accelerate battery platform adoption in Bordeaux and Nantes maintenance facilities. Safran and Thales supplier networks in Occitanie and Île-de-France regions standardize on brushless DC motor architectures with integrated torque feedback systems.
Rivet Gun Market Vendor Landscape
Top-tier vendors anchor premium aerospace certification tiers, while mid-scale fabricators compete on construction and automotive volume contracts. The vendor base stratifies across three functional layers: diversified industrial conglomerates with battery platform crossover capabilities, specialized blind rivet system engineers with German engineering heritage, and pneumatic equipment specialists serving factory automation channels. Competitive moves concentrate on modular battery architecture licensing and predictive maintenance service bundling.
Among German-based precision engineers, GESIPA Blindniettechnik GmbH and Honsel Umformtechnik GmbH occupy positions exemplifying specialized fastening technology heritage. Stanley Black & Decker, Inc. represents the diversified conglomerate archetype with construction-to-aviation platform crossover capabilities. Atlas Copco AB sits within the factory automation tier, anchoring integrated pneumatic feed system deployments for high-volume manufacturing environments.
| Leading Market Players |
|---|
| Stanley Black & Decker, Inc. |
| Malco Products |
| GESIPA Blindniettechnik GmbH |
| Honsel Umformtechnik GmbH |
| Fastening Systems International Inc. |
| Arconic Inc. |
| Degometal |
| Campbell Hausfeld |
| Atlas Copco AB |
| Others |
Supply Flow & Price Mechanics
Backward integration into brushless DC motor and lithium-ion cell production anchors supply positioning and pricing power for cordless platform vendors competing against legacy pneumatic incumbents. German MRO providers under ECHA REACH oil-mist restrictions absorb premium pricing for certified battery systems while US Midwest automotive plants retain cost advantages through existing compressed air infrastructure.
Pricing Analysis
Lead-time-driven pricing stratification separates aerospace-grade calibrated platforms commanding premiums for FAA traceability documentation from spot-market construction units moving through distributor inventory. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service bundling. Pricing pressure stems from cobalt and nickel raw material volatility compressing margins in cordless tiers. Construction contractors exhibit highest price sensitivity through fleet turnover economics, while aviation OEMs accept premium positioning for joint quality guarantees.
Supply Chain Analysis
Reverse-logistics flows for battery pack refurbishment and tool remanufacturing are gaining scale in European markets where EU Green Deal embodied-carbon tracking favors modular repairable designs over sealed disposable units. Component sourcing concentrates in Germany for precision fastening systems, China for lithium-ion cell production, and Japan for brushless motor controllers. Supply chains draw from aluminum forgings, rare-earth magnets, and specialty lubricants facing REACH formulation constraints. Single-source vulnerability sits with cobalt cell chemistry dependencies. Distribution runs through authorized dealer networks for aviation certification tiers and mass retail channels for construction contractor procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as battery platform vendors pursue captive control over motor-controller module sourcing to defend performance parity against pneumatic incumbents.
For Market Incumbents: Lock in aviation MRO certification tiers through FAA airworthiness directive compliance investments that create switching costs against emerging battery competitors. Consolidate factory automation channels by embedding predictive maintenance telemetry into integrated pneumatic feed systems before cordless platforms achieve torque density parity in high-volume automotive applications.
For New Entrants and Emerging Players: Capture Indian defense manufacturing clusters in Bengaluru and Hyderabad where PLI scheme incentives for indigenous aerospace production create demand for precision fastening tools with limited incumbent penetration. Target per-rivet service agreement models in Scandinavian markets where sustainability reporting requirements favor operational expenditure treatment and modular battery architectures enable usage-based rental pricing.
For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified industrial conglomerates seeking construction-to-aviation platform crossover capabilities. Long-term viability hinges on battery chemistry evolution and regulatory acceleration of oil-mist restrictions across European maintenance operations. Monitor ECHA REACH expansion timelines and COMAC C919 production certification milestones as inflection indicators for cordless platform adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motor-Controller Modules | Captive sourcing of brushless DC architectures secures torque feedback calibration precision for aerospace certification tiers. |
| Per-Rivet Service Agreement Launch | Consumption-based pricing models align with Scandinavian sustainability reporting requirements favoring operational expenditure treatment. |
| Aviation MRO Certification Investment | FAA airworthiness directive traceability documentation creates defensive moats against generic cordless platform encroachment. |
| Indian Defense Manufacturing Partnership | PLI scheme incentives in Bengaluru and Hyderabad clusters open import substitution opportunities for previously European-sourced equipment. |
| Modular Battery Architecture Licensing | Cross-brand platform standardization enables telematics-enabled fleet management and predictive maintenance service bundling. |
Methodological Framework
Trade association filings, customs import records, and aviation regulator certification databases formed the secondary backbone for demand quantification and competitive positioning assessment. Primary interviews with MRO maintenance directors, OEM procurement managers, plant engineers at automotive Tier 1 suppliers, and aftermarket service heads validated tool replacement cycle assumptions and technology transition timelines. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the analysis window.
Historical trendline analysis of pneumatic and cordless platform shipment volumes established baseline growth trajectories before applying segment-specific adjustment factors. The analytical framework modeled product type, application vertical, end-user procurement rhythm, and technology maturity gradient throughout the forecast period. CAGRs derived from regression analysis of replacement cycle compression rates and regulatory compliance acceleration curves. Forecast inputs included narrow-body production schedules, ECHA REACH enforcement timelines, and lithium-ion energy density improvement curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to battery chemistry breakthroughs and aviation regulator certification reciprocity agreements. Projections reflect assumptions on cordless torque parity achievement and European maintenance hangar conversion rates. Practitioners should monitor cobalt price volatility indices and COMAC C919 delivery certification milestones for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
GCC Machine Tools Market
Tools
Machine Tools Market
Tools
Tapping Machine Market
Tools
Drilling Tools Market
Tools
Orbital Sanders Market
Tools
United States Machine Tools Market
Tools
Europe Power Tools Market
Tools
Edge Banders Market
Tools
Grabber Pole Market
Tools
Entrenching Tool Market
Tools
Lathe Machines Market
Tools
Telescopic Tool Boxes Market
Tools
Portable Milling Machine Market
Tools
3D Milling Machines Market
Tools
Trim Press Market
Tools
Hydraulic Tools and Equipment Market