
 Global Zero Point Clamping System Market | 2026-2036
Global Zero Point Clamping System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Zero Point Clamping System Market Foresight
The distributor network for zero point clamping systems is fragmenting as direct-to-factory digital channels erode traditional machine-tool dealer relationships. SCHUNK leverages its captive sales force across German automotive clusters to sustain premium positioning. EROWA anchors its European installed base through proprietary taper-interface ecosystems that lock in repeat purchases. LANG Technik GmbH competes on modular magnetic clamping kits tailored to small-batch job shops.
A zero point clamping system is a precision workholding fixture that locates and secures workpieces or pallets via a standardized reference point with repeatability typically below 0.005 mm, enabling rapid changeover across CNC machining centers without re-measuring. Its primary industrial purpose is to eliminate setup time in multi-operation manufacturing, converting spindle idle hours into productive cutting cycles. Hydraulic clamping dominates installed base value where high-force retention secures heavy aerospace forgings during aggressive material removal. Quick-change systems represent the fastest-expanding technology segment as CAD/CAM-integrated toolpath automation demands seamless pallet handoff between machining stages. Manual clamping retains share in prototype shops and toolrooms where capital constraints limit pneumatic or electro-mechanical upgrades.
Germany's Machinery Directive and CE marking framework mandate documented safety validation for automated clamping cycles, while China's GB standards through SAMR impose dimensional certification for imported workholding equipment. These dual compliance regimes force vendors to maintain parallel testing protocols, raising barriers for unvalidated entrants. Stakeholders must monitor divergence between EU machinery safety updates and China's evolving GB standards for intelligent manufacturing equipment, as misalignment risks segmented product architectures.
Market Dynamics
The zero point clamping system market is undergoing structural compression as CAD/CAM-integrated automation eliminates spindle idle time across multi-axis machining workflows. Aerospace OEMs and automotive tier suppliers now mandate sub-0.005 mm repeatability as a baseline specification, forcing fixture vendors to recalibrate R&D priorities toward real-time position verification.
Growth Catalysts
- Aerospace multi-axis machining mandates:Commercial aircraft programs require rapid pallet changeover between roughing and finishing operations. Hydraulic quick-change systems capture this demand by securing heavy forgings during aggressive material removal cycles.
- CE marking under Machinery Directive:Germany's safety validation requirements for automated clamping cycles push manufacturers toward certified quick-change architectures. This regulatory pressure accelerates replacement of uncertified legacy fixtures.
- Precision manufacturing cluster concentration:Stuttgart, Shenzhen, and Detroit deepen investment in automated workholding. These three hubs collectively absorb the majority of new system installations.
Market Restraints
- Alloy steel price volatility:Hardened clamping modules depend on specialty alloy feedstock. Input cost swings compress margin predictability for mid-tier fixture assemblers.
- Proprietary interface lock-in:EROWA's taper-interface ecosystem dominates European installed base. This concentration limits interoperability and raises switching costs for multi-vendor shops.
- GB certification timeline friction:China's SAMR dimensional certification requirements for imported workholding equipment extend product launch cycles by 8-14 months.
Strategic Opportunities
- Indian precision component export hubs:Bangalore and Pune machine shops remain underpenetrated by automated clamping. First-mover vendors can establish specification influence before local competitors mature.
- Magnetic-pneumatic hybrid convergence:LANG Technik's modular magnetic kits demonstrate feasibility for small-batch flexibility. Combining magnetic quick-release with pneumatic force amplification opens die-mold and prototype segments.
- EU Green Deal manufacturing incentives:Energy efficiency audits now favor reduced setup waste. Zero point systems qualify by eliminating repeated workpiece measurement cycles.
Industry Challenges
- Metrology-integrated programming talent scarcity:Shops lack operators who can synchronize clamping macros with machine tool probe routines. Training pipelines for this cross-functional skill remain underdeveloped.
- Legacy pallet pool incompatibility:Brownfield facilities face capital-intensive retrofit requirements when integrating new reference-point systems with existing FMS infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Zero Point Clamping System Market |
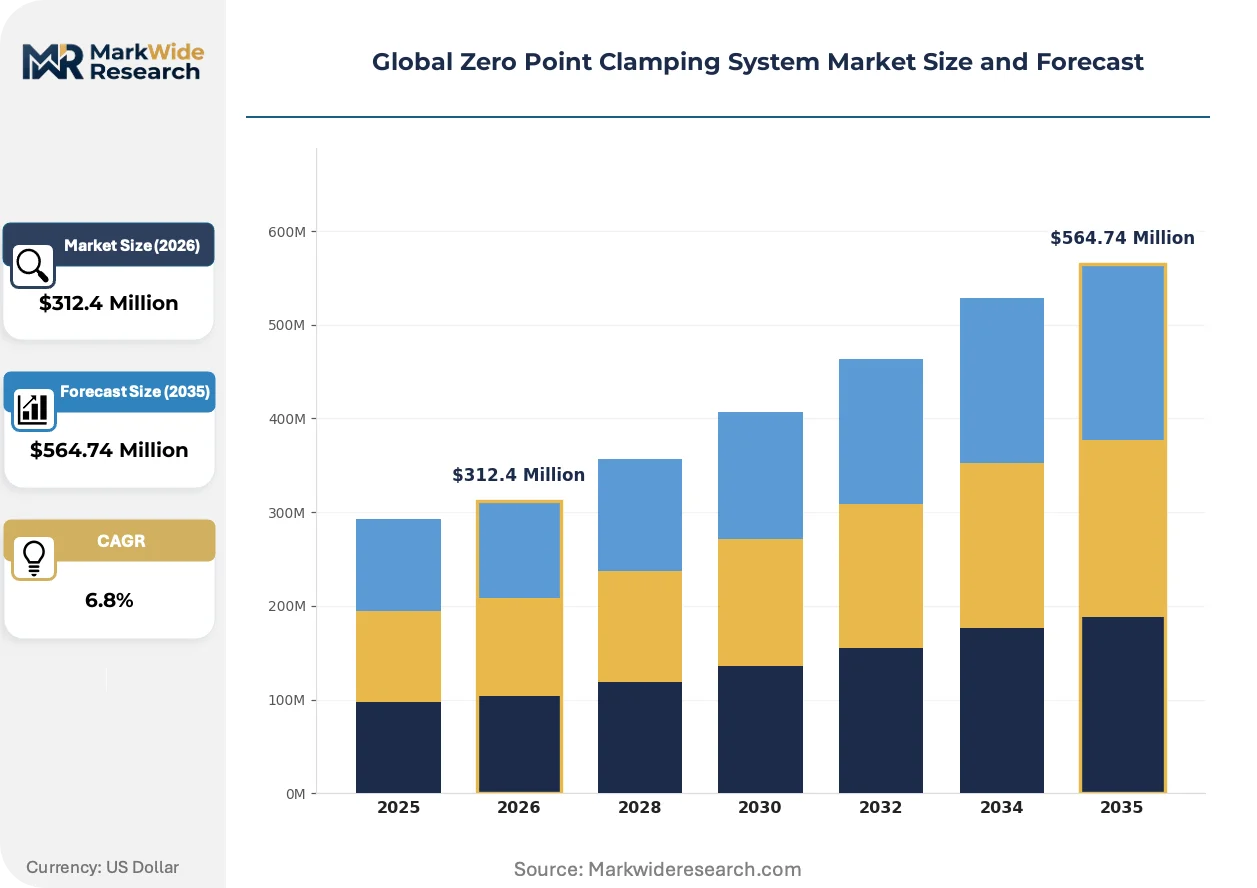
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic, Mechanical, Pneumatic, Magnetic, Electro-Mechanical Technology: CAD/CAM Integration, Automated Clamping, Manual Clamping, Quick-Change Systems, Modular Clamping Application: CNC Machining, Metal Fabrication, Precision Engineering, Aerospace Component Assembly, Electronics Manufacturing End User: Machine Shops, Aerospace OEMs, Electronics Manufacturers, Automotive Tier-1 Suppliers, Medical Device Producers |
| Companies Covered | SCHUNK, EROWA, LANG Technik GmbH, Roemheld GmbH, AMF Andreas Maier GmbH, Zeroclamp, Piranha Clamp GmbH, Spreitzer GmbH, Jergens Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Zero Point Clamping System Market Shifts & Advancements
Fixture intelligence is migrating from passive mechanical retention toward sensor-embedded active monitoring. Real-time clamping force telemetry and thermal drift compensation are becoming standard specifications rather than premium options.
Electro-mechanical clamping actuation is migrating from niche prototype applications into production aerospace workflows. Tier 1 suppliers at Airbus and Boeing subcontractors now specify servo-driven clamping for its programmable force curves and energy efficiency. This migration from hydraulic dominance is compressing the installed base upgrade cycle from seven years toward four.
REACH substance restrictions and RoHS recast directives are forcing re-engineering of hydraulic clamping fluids and surface coatings. European vendors must reformulate seal compounds and replace cadmium-plated components. Germany's KBA and France's ANSM coordinate enforcement, so aerospace suppliers with dual EU manufacturing footprints face synchronized compliance deadlines.
Buyer consolidation among automotive tier suppliers is reshaping procurement authority. Large contract manufacturers now mandate enterprise-wide fixture standardization across their German, Chinese, and US plants. This behavior compresses vendor negotiation cycles and favors suppliers with multi-continent service networks. The pattern is most visible in powertrain machining, where platform commonality drives specification uniformity.
Global Zero Point Clamping System Market Segmentation
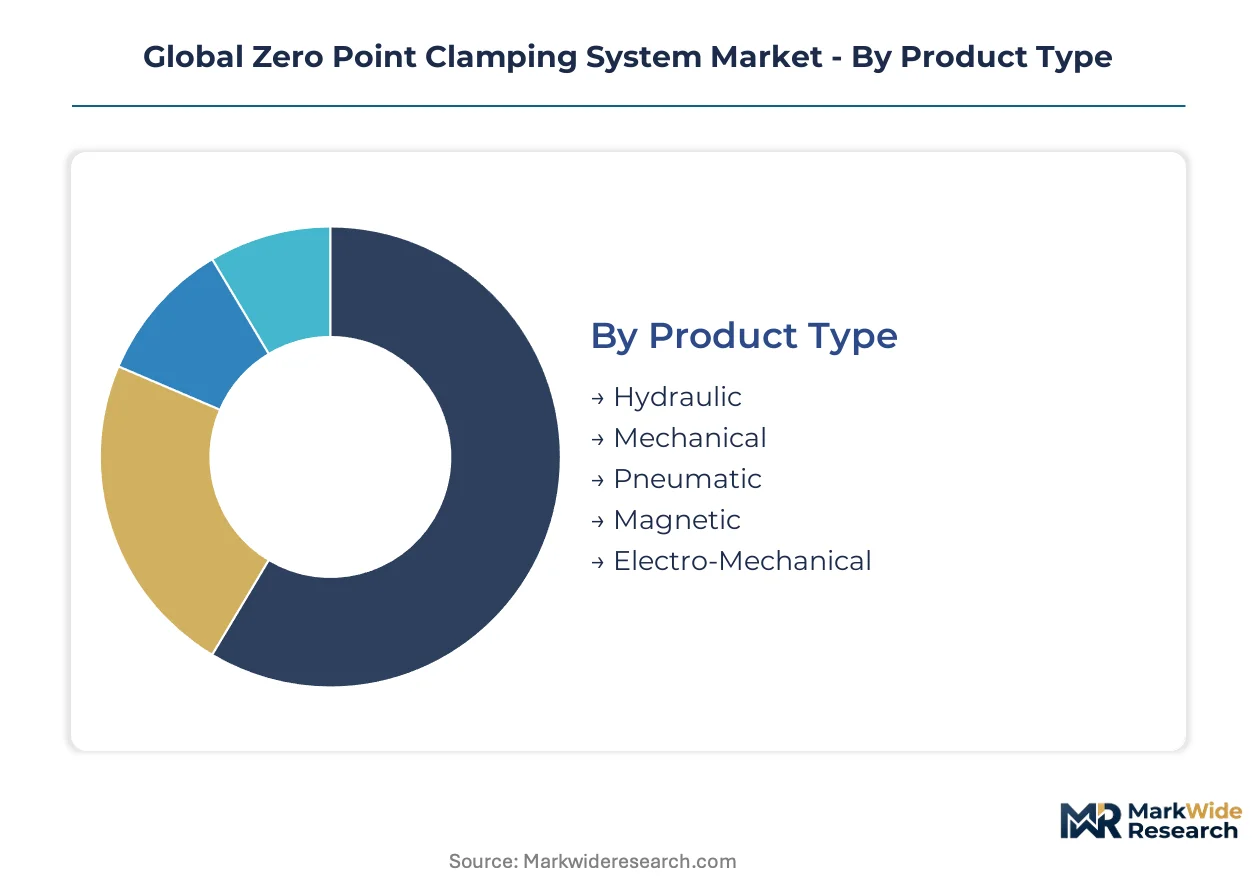
Zero point clamping systems fragment across actuation technologies, automation levels, and end-use precision requirements. Each segmentation axis reveals distinct procurement patterns and specification thresholds that vendors must address.
Product Type:
Actuation mechanisms span the force spectrum from heavy aerospace retention to delicate electronics handling.
- Hydraulic:Delivers clamping forces exceeding 50 kN through mineral-oil or water-glycol circuits. Aerospace OEMs in Germany and the United States specify hydraulic modules for titanium and Inconel roughing operations where vibration dampening is critical.
- Electro-Mechanical:Servo-driven ball screw mechanisms enable programmable force curves and energy recovery during release cycles. Airbus and Boeing tier-1 suppliers in Toulouse and Seattle are migrating production lines toward electro-mechanical systems for their audit trail compatibility and reduced maintenance intervals.
- Mechanical:Wedge or cam-actuated designs with manual torque input serve cost-constrained job shops.
- Pneumatic:Compressed-air diaphragm clamping suits cleanroom electronics manufacturing where hydraulic fluid contamination is prohibited.
- Magnetic:Permanent-electro hybrid systems from LANG Technik enable rapid fixtureless workholding for ferrous blanks in small-batch die-mold operations.
Established volume favors hydraulic; emerging adoption favors electro-mechanical.
Technology:
Automation depth determines integration complexity and operator skill requirements.
- Quick-Change Systems:Standardized taper or ball-lock interfaces achieve sub-0.005 mm repeatability across pallet exchanges. Stuttgart automotive clusters and Shenzhen precision manufacturing hubs drive demand for these systems as CAD/CAM-integrated toolpath automation eliminates manual touch-off procedures.
- CAD/CAM Integration:Macro-programmed clamping sequences synchronize with machine tool probe routines for lights-out operation. Aerospace subcontractors in Wichita and Hamburg now mandate this capability for multi-axis machining cells.
- Modular Clamping:Grid-based fixture building blocks adapt to varying workpiece geometries without custom fabrication.
- Automated Clamping:Sensor-embedded force feedback and thermal drift compensation enable real-time process control.
- Manual Clamping:Hand-operated reference point fixtures retain share in prototype shops and toolrooms with limited capital budgets.
Quick-change systems are climbing the fastest as automation mandates harden across aerospace and automotive specifications.
Application:
Precision requirements and throughput intensity vary sharply across manufacturing processes.
- CNC Machining:Multi-axis milling and turning centers constitute the core installed base, with pallet-based zero point systems enabling 90-second changeover between roughing and finishing operations. Machine shops in Detroit and Pune concentrate demand for mid-tier hydraulic configurations.
- Aerospace Component Assembly:Wing rib and landing gear machining demands certified repeatability under CE marking and FAA production approval requirements. Tier-1 suppliers in Everett and Broughton specify force-verified clamping cycles for traceability.
- Metal Fabrication:Laser and plasma cutting tables adopt magnetic zero point grids for sheet metal nesting flexibility.
- Precision Engineering:Watchmaking and optical component manufacturing specify sub-micron locating repeatability.
- Electronics Manufacturing:Semiconductor equipment frames and heat sink machining favor pneumatic clamping in cleanroom environments.
Volume concentrates in CNC machining; specification intensity peaks in aerospace component assembly.
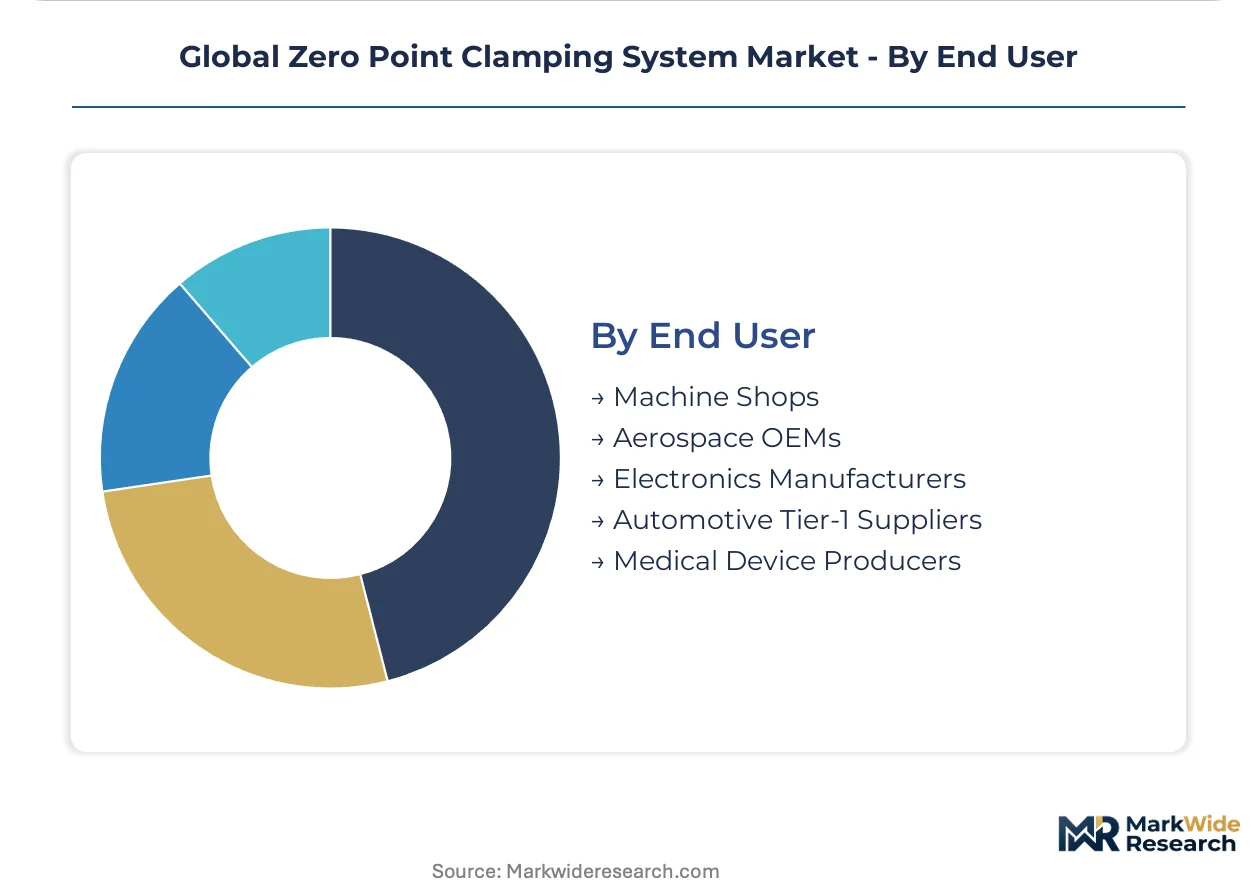
End User:
Procurement authority and standardization scope differ across organizational scale.
- Machine Shops:Independent job shops in Bangalore and Chicago prioritize modular systems with rapid ROI payback on changeover time reduction. These buyers dominate unit volume but negotiate aggressively on price.
- Aerospace OEMs:Airbus, Boeing, and their certified subcontractors mandate enterprise-wide fixture standardization across German, Chinese, and United States manufacturing footprints. Procurement teams specify multi-continent service networks and documented safety validation.
- Automotive Tier-1 Suppliers:Powertrain contract manufacturers in Stuttgart and Shanghai drive platform-common specifications across transmission and engine block machining lines.
- Electronics Manufacturers:Semiconductor capital equipment producers in Hsinchu and Dresden specify contamination-resistant pneumatic systems.
- Medical Device Producers:Orthopedic implant machining in Warsaw and Minneapolis requires validated clamping cycles under FDA and MDR frameworks.
Specification authority concentrates with aerospace OEMs; volume disperses across machine shops.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German aerospace OEMs extract premium pricing for CE-certified quick-change systems, while Indian machine shops in Bangalore and Pune negotiate aggressively on mid-tier hydraulic configurations. This pricing-power asymmetry reflects divergent regulatory burdens and automation maturity across manufacturing clusters.
Germany
Stuttgart automotive clusters and Hamburg aerospace subcontractors drive specification intensity for sub-0.005 mm repeatability. The Machinery Directive and KBA enforcement of CE marking for automated clamping cycles force documented safety validation. Bavarian powertrain machining lines now mandate enterprise-wide fixture standardization across transmission and engine block operations.
China
Shenzhen precision manufacturing hubs absorb significant quick-change system volume as CAD/CAM-integrated automation eliminates manual touch-off procedures. SAMR's GB standards impose dimensional certification timelines that extend product launches by 8-14 months for imported workholding equipment. Yangtze River Delta machine shops concentrate demand for pneumatic clamping in semiconductor capital equipment frames.
United States
Wichita and Seattle aerospace tier-1 suppliers migrate production lines toward electro-mechanical systems for audit trail compatibility with FAA production approval requirements. Detroit automotive powertrain contract manufacturers drive platform-common specifications across multi-continent manufacturing footprints. FDA validation requirements for orthopedic implant machining in Minneapolis reinforce specification discipline in medical device segments.
India
Bangalore and Pune precision component export hubs remain underpenetrated by automated clamping relative to their machining capacity. BIS certification pathways for imported workholding equipment create friction for first-mover vendors establishing specification influence. Tamil Nadu automotive component suppliers concentrate mid-tier hydraulic demand as platform commonality spreads from German and Japanese OEM partnerships.
Japan
Nagoya aerospace subcontractors and Osaka precision engineering clusters specify contamination-resistant pneumatic systems for cleanroom electronics manufacturing. METI industrial policy supports energy efficiency audits that favor reduced setup waste through zero point systems. Kanto region machine tool builders integrate reference-point fixtures into export-configured machining centers bound for Southeast Asian markets.
Global Zero Point Clamping System Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying hardened modules and standardized interfaces. The vendor base organizes around three archetypes: captive sales force operators sustaining premium positioning through direct factory relationships, proprietary interface ecosystem builders locking in repeat purchases via taper-lock architectures, and modular kit assemblers competing on flexibility for small-batch job shops. Consolidation pressure intensifies as automotive tier supplier buyer concentration mandates multi-continent service networks. Dominant competitive moves include strategic partnerships with machine tool OEMs for pre-integrated fixture packages and geographic expansion into underpenetrated Indian precision component hubs.
Among German GmbH-structured specialists, SCHUNK, EROWA, and LANG Technik GmbH occupy distinct positioning vectors. SCHUNK exemplifies the captive sales force archetype through sustained direct engagement with automotive clusters. EROWA represents the proprietary ecosystem model with taper-interface architectures that anchor European installed base loyalty. LANG Technik GmbH sits within the modular flexibility tier, demonstrating feasibility for magnetic-pneumatic hybrid configurations in die-mold and prototype segments. These three entities collectively illustrate how vendor strategy fragments across automation depth and customer scale rather than converging on uniform technology platforms.
| Leading Market Players |
|---|
| SCHUNK |
| EROWA |
| LANG Technik GmbH |
| Roemheld GmbH |
| AMF Andreas Maier GmbH |
| Zeroclamp |
| Piranha Clamp GmbH |
| Spreitzer GmbH |
| Jergens Inc |
| Others |
Supply & Pricing Matrix
Stuttgart's hardened alloy steel forging capacity anchors upstream module production, concentrating cost leverage among German specialists who supply aerospace-certified quick-change systems at premium configured-to-order pricing. This geographic clustering of heat-treatment and precision grinding infrastructure amplifies pricing power for CE-validated architectures while compressing margins for mid-tier fixture assemblers dependent on spot alloy procurement.
Pricing Analysis
Configured-to-order pricing for CE-certified quick-change systems commands substantial premiums over standard hydraulic configurations, with certification grade and after-sales service bundling as primary differentiation drivers. Three-tier pricing structure across aerospace-validated, automotive-standard, and job-shop economy levels stratifies procurement authority. Pricing pressure stems from alloy steel feedstock volatility and Indian machine shop negotiation aggression. Machine shops in Bangalore and Pune exhibit highest price sensitivity; aerospace OEMs in Hamburg and Seattle demonstrate lowest.
Supply Chain Analysis
Specialty alloy feedstock draws from German, Japanese, and Swedish metallurgical suppliers, with hardened clamping modules resting on precision-ground taper interfaces and sensor-embedded force verification components. Single-source vulnerability concentrates in EROWA's proprietary taper-interface ecosystem, which locks European installed base loyalty. Distribution runs through machine tool OEM pre-integration channels and direct factory sales forces serving Stuttgart, Shenzhen, and Detroit manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through CE marking and Machinery Directive compliance creates durable switching costs for validated system architectures.
For Market Incumbents: Insulate European installed base loyalty by deepening proprietary taper-interface ecosystems and accelerating certification investments under evolving EU machinery safety updates. Threat from magnetic-pneumatic hybrid substitutes in small-batch segments demands counter-positioning through modular kit expansion. Vertical integration into hardened alloy forging secures margin control against feedstock volatility.
For New Entrants and Emerging Players: Build out specification influence in Bangalore and Pune precision component export hubs before local competitors mature, targeting mid-tier hydraulic configurations with rapid ROI positioning. India's BIS certification friction creates first-mover windows for patient capital. Go-to-market angle should emphasize CAD/CAM-integrated macro programming partnerships with regional machine tool distributors.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-entrenchment play because CE marking and FAA production approval requirements create decade-scale validation barriers. Acquisition target archetype: German GmbH-structured specialists with captive automotive cluster relationships and documented safety validation libraries. Signal to watch is divergence between EU machinery safety updates and China's evolving GB standards, which would force segmented product architectures and favor multi-protocol vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| Machine Tool OEM Pre-Integration Partnership | SCHUNK and EROWA secure specification authority through captive sales force alignment with Stuttgart automotive clusters. |
| Magnetic-Pneumatic Hybrid Convergence | LANG Technik demonstrates feasibility for die-mold flexibility, opening prototype segments previously closed to hydraulic dominance. |
| Indian Hub Geographic Expansion | First-mover vendors establish BIS certification pathways before local competitors mature in Bangalore and Pune. |
| Sensor-Embedded Force Verification R&D | Real-time clamping force telemetry migrates from premium option to standard specification across aerospace mandates. |
| Regulatory Protocol Harmonization Investment | Parallel CE marking and SAMR GB testing capabilities raise barriers for unvalidated entrants in dual-jurisdiction supply. |
Research Methodology
Desk research of trade customs data, SEC filings from publicly listed machine tool OEMs, and ECHA REACH substance restriction databases preceded structured interviews with maintenance directors at aerospace tier-1 suppliers, plant engineers at Stuttgart automotive powertrain facilities, and aftermarket service heads at German workholding specialists. Bottom-up volume triangulation from installation records across Detroit, Shenzhen, and Hamburg manufacturing clusters converged with top-down value estimates derived from procurement database analysis.
Fixed assumptions across the modeling period held alloy steel price indices within observed volatility bands and regulatory divergence between EU machinery safety frameworks and China's GB standards within current trajectory ranges. Segmentation dimensions spanned actuation technology, automation depth, end-use precision requirements, and regional manufacturing cluster maturity. CAGRs were synthesized from trend extrapolation of CAD/CAM integration penetration rates and aerospace multi-axis machining capital expenditure patterns.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-supported machine tool builders or accelerated magnetic clamping substitution would shift outcomes. Cross-checking against customs import records for workholding equipment and machine tool accessory trade flows is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Portable Boring Machines Market
Tools
Painting Tools Market
Tools
Wood Router Market
Tools
Extensometer Market
Tools
Sand Control Tools Market
Tools
Drill Bit Market
Tools
Reamer Market
Tools
Cold and Hot Tool Steel Market
Tools
Circular Saw Blades Market
Tools
Cutting Equipment Market
Tools
Hacksaw Blades Market
Tools
Mechanical Springs Market
Tools
Multi Spindle Machines Market
Tools
Global Cutting Discs Market
Tools
Assembly Fastening Tool Market
Tools
Crimping Tool Market