
 Suction Catheters Market | 2026-2036
Suction Catheters Market Size, Share, and Industry Trends Forecast 2026-2036
Suction Catheters Market Intelligence
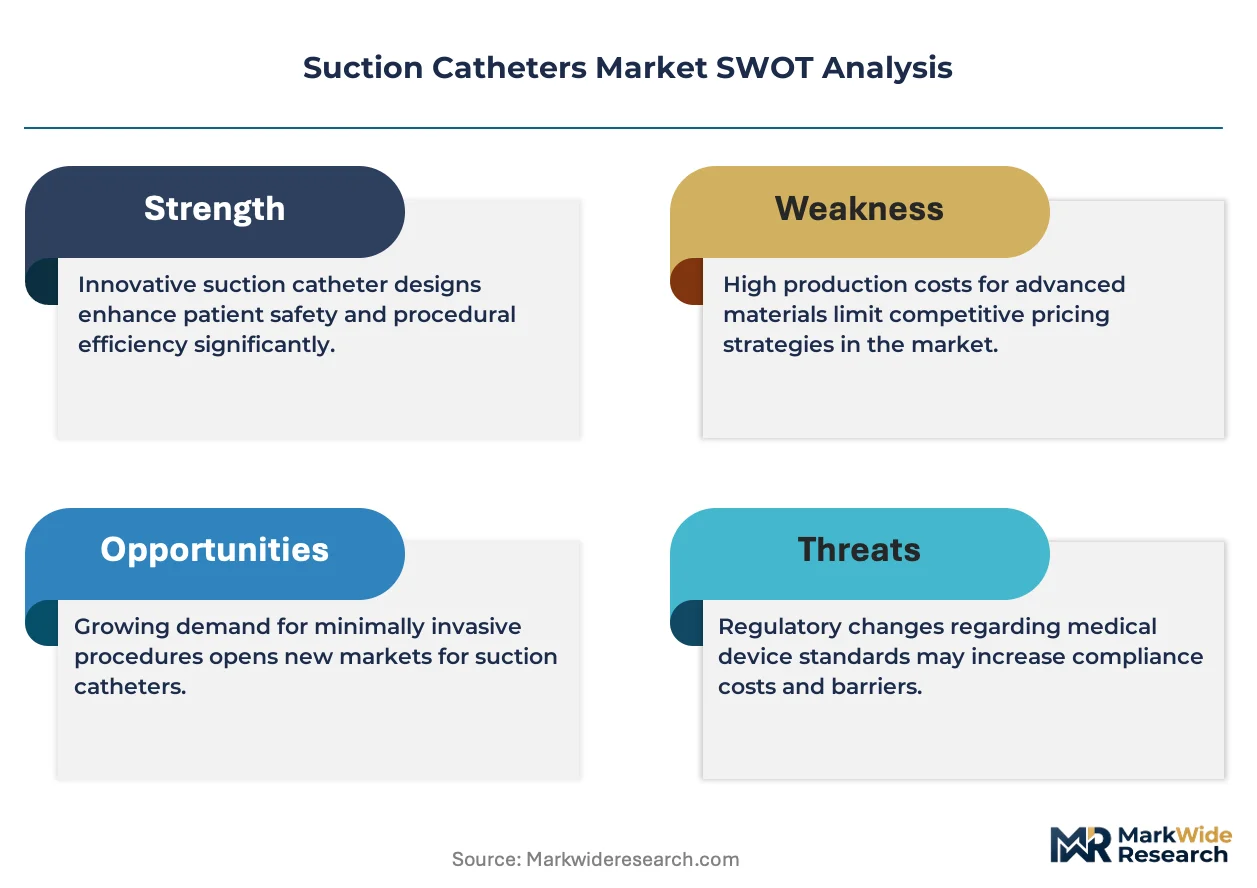
The gap between premium closed-system suction catheters and commodity open-system designs is rebalancing as infection-control economics tilt hospital procurement toward higher-sterility products. Medtronic plc leverages its cardiovascular and minimally invasive therapy infrastructure to sustain dominant positioning in closed-system segments. Cardinal Health competes through distribution scale and private-label flexibility across acute-care networks. B. Braun Melsungen AG anchors European supply with specialized manufacturing for latex-free and silicone catheter lines.
Suction catheters are hollow, flexible or rigid tubes manufactured from polyvinyl chloride, silicone, or latex, typically 6-18 French in diameter, designed to aspirate secretions from the airway or surgical field through controlled vacuum application. The device maintains patent airways during respiratory distress, postoperative recovery, or mechanical ventilation weaning. Flexible catheters lead volume in respiratory therapy applications where patient mobility and tracheal access precision matter most. Yankauer suction instruments dominate emergency care and surgical settings where rapid, high-volume fluid evacuation is critical. Silicone material formulations represent the fastest-growing segment as biocompatibility requirements and latex allergy protocols displace traditional polyvinyl chloride in neonatal and long-term care applications.
FDA 510(k) clearance pathways and EU MDR conformity assessments shape product development timelines and sterilization validation requirements for suction catheter manufacturers. ISO 80369 small-bore connector standards are forcing design modifications to prevent misconnections with enteral or neuraxial devices. Health Canada and Japan's PMDA maintain parallel biocompatibility testing protocols that add regulatory layers for multinational suppliers. Stakeholders must monitor how regional sterility classification rules and single-use device reprocessing bans redistribute margin pools between disposable and semi-reusable system architectures.
Market Dynamics
Hospital infection-control economics are compressing procurement cycles toward closed-system architectures, forcing manufacturers to revalidate sterilization protocols and connector compatibility across multiple regulatory jurisdictions simultaneously.
Growth Catalysts
- EU MDR sterility mandates:The Medical Device Regulation's enhanced biocompatibility requirements are accelerating hospital conversion from open-system to closed-system suction catheter platforms across German, French, and Italian acute-care networks.
- Neonatal silicone adoption:Latex-allergy protocols in pediatric intensive care units are displacing polyvinyl chloride formulations, expanding addressable volume for medical-grade silicone catheter lines.
- Japan's surgical volume concentration:Tokyo, Osaka, and Nagoya metropolitan hospital clusters sustain per-capita suction catheter utilization rates that exceed other OECD markets by substantial margins.
Market Restraints
- Medical-grade silicone price volatility:Petrochemical feedstock fluctuations and specialized polymer purification requirements compress gross margins for premium catheter formulations.
- Single-use device reprocessing bans:FDA guidance and EU national implementations of single-use labeling enforcement eliminate semi-reusable system architectures that previously captured mid-market price points.
- ISO 80369 connector transition costs:Small-bore connector standardization forces mold retooling and inventory obsolescence across legacy product lines.
Strategic Opportunities
- Home respiratory care expansion:Post-acute discharge protocols in the United States and Germany are creating demand for patient-operated suction systems with simplified sterilization workflows.
- India's hospital infrastructure buildout:Central government health scheme expansion and private hospital chain consolidation in tier-2 cities open distribution channels for standardized catheter SKUs.
- Digital supply chain integration:Direct-to-hospital e-procurement platforms and consignment inventory models are compressing distributor markups while capturing demand signals closer to point-of-care.
Industry Challenges
- Regulatory submission timeline compression:FDA 510(k) clearance pathways and EU MDR notified body queue congestion extend product launch windows and consume technical documentation resources.
- Cleanroom manufacturing capacity constraints:ISO 14644 Class 7 and Class 8 facility expansion requires capital deployment that mid-tier manufacturers struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Suction Catheters Market |
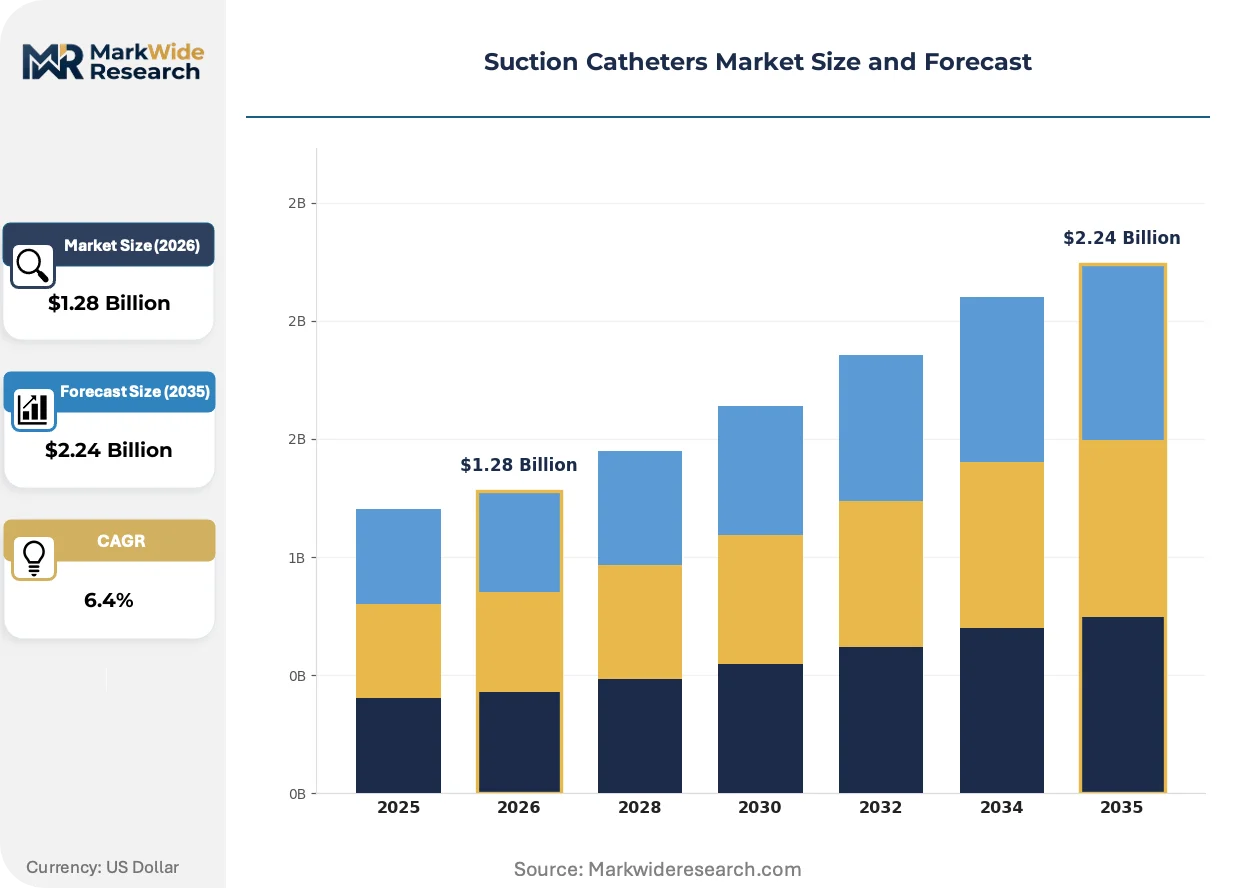
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $2.24 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yankauer, Flexible, Rigid, Vacuum End User: Hospitals, Clinics, Ambulatory Surgical Centers, Homecare Application: Emergency Care, Surgical Procedures, Respiratory Therapy, Neonatal Care Material: Polyvinyl Chloride, Silicone, Latex, Others |
| Companies Covered | Medline Industries, Smiths Medical, Medtronic plc, Terumo Corporation, B. Braun Melsungen AG, Teleflex Incorporated, Cardinal Health, ConvaTec Group plc, Becton Dickinson and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Suction Catheters Market Strategic Shifts & Innovations
Material science convergence with digital manufacturing is fragmenting traditional catheter supply relationships, while regulatory harmonization pressures force simultaneous multi-jurisdiction compliance investments.
Closed-system suction catheter architecture is modularizing around interchangeable manifold and suction control components. Hospital systems in the United States and Germany are standardizing on platform designs that accommodate multiple French sizes through common connection interfaces. This standardization is compressing SKU proliferation and enabling volume consolidation with preferred suppliers.
EU MDR Article 10 technical documentation requirements and Annex I general safety and performance specifications are extending conformity assessment timelines for suction catheter manufacturers. The regulation forces recertification of legacy products that previously operated under MDD certificates. Neonatal and long-term care applications face the steepest compliance burden due to biocompatibility testing stringency for extended-duration tissue contact.
Hospital procurement departments are consolidating suction catheter purchasing into broader airway management category contracts. Group purchasing organizations and integrated delivery networks in the United States are displacing standalone product negotiations with multi-year supply agreements that bundle suction catheters with endotracheal tubes and closed suction systems. This concentration is most visible in the southeastern and midwestern United States where hospital system consolidation has advanced furthest.
Suction Catheters Market Segmentation
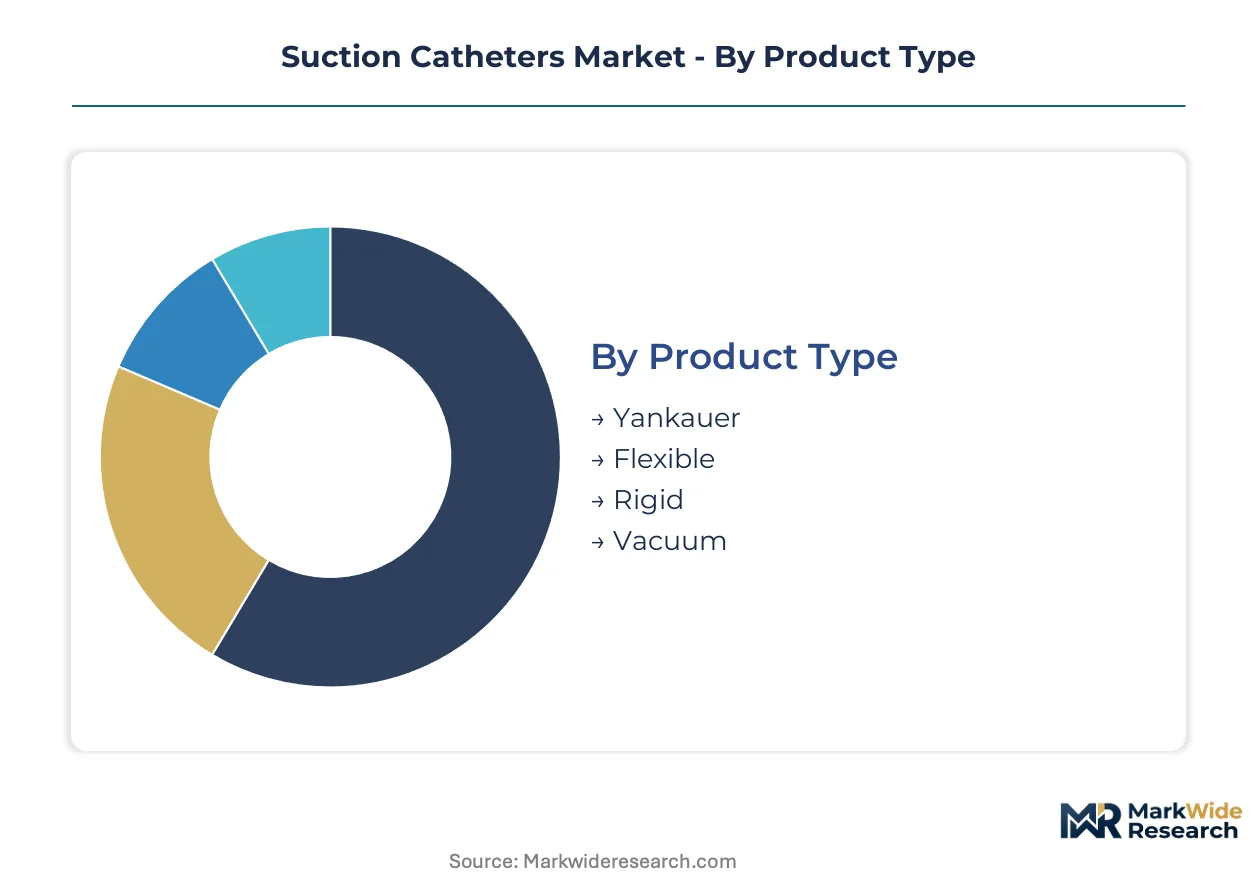
Suction catheter segmentation reveals divergent manufacturing economics across product architectures and material formulations. Hospital procurement consolidation and regulatory sterility mandates are reshaping volume distribution across end-use channels and application settings.
Product Type:
Capital intensity varies sharply across catheter architectures, with closed-system flexible designs requiring ISO 14644 cleanroom investment that open-system Yankauer instruments avoid.
- Flexible:These polyvinyl chloride or silicone catheters navigate tortuous airway anatomy through tracheostomy or endotracheal tube access. Demand concentrates in United States and German intensive care units where mechanical ventilation weaning protocols mandate frequent suctioning cycles.
- Yankauer:Rigid, angled suction instruments with large-bore openings enable rapid oropharyngeal and surgical field evacuation. Emergency departments in Tokyo and Osaka metropolitan clusters sustain disproportionate per-capita utilization for trauma and acute respiratory failure management.
- Rigid:Straight or curved metal or polymer shafts serve operative suction needs where instrument rigidity ensures precise tip placement.
- Vacuum:Integrated pump-catheter systems combine suction generation with aspiration function for point-of-care deployment.
Flexible catheters absorb the bulk of installed capacity; silicone flexible variants are expanding most quickly.
End User:
Customer-type segmentation tracks reimbursement economics and sterility protocol stringency, with acute-care facilities commanding premium pricing against price-sensitive homecare channels.
- Hospitals:Tertiary acute-care networks in the United States, Germany, and Japan drive procurement volume through centralized purchasing and infection-control committee mandates. EU MDR sterility requirements and FDA 510(k) clearance pathways elevate supplier qualification barriers.
- Homecare:Post-acute discharge growth in United States Medicare and German statutory health insurance programs creates demand for simplified, patient-operated suction systems with disposable canister designs.
- Clinics:Outpatient respiratory therapy and minor surgical settings utilize standardized catheter SKUs with lower sterility classification requirements.
- Ambulatory Surgical Centers:Same-day procedure volumes in United States freestanding facilities concentrate demand for single-use Yankauer and rigid suction instruments.
Hospitals command dominant procurement volume; homecare channels are gaining share fastest as post-acute protocols lengthen.
Application:
Application segmentation aligns with clinical workflow intensity and reimbursement tier, separating high-acuity emergency and surgical use from scheduled respiratory maintenance.
- Surgical Procedures:Operating room suction demands rapid fluid evacuation capacity and compatibility with sterile field protocols. German and Japanese surgical volume concentration sustains premium catheter utilization.
- Respiratory Therapy:Scheduled airway maintenance in intensive care and step-down units drives recurring flexible catheter consumption. United States ventilator-associated pneumonia reduction protocols mandate closed-system designs.
- Emergency Care:Trauma and acute respiratory failure management requires immediate suction availability with Yankauer dominance.
- Neonatal Care:Premature infant airway management demands small-French silicone catheters with biocompatibility certification for delicate mucosal tissue.
Respiratory therapy absorbs the bulk of recurring demand; neonatal applications are climbing the fastest as silicone formulations displace polyvinyl chloride.
Material:
Material selection governs margin structure and regulatory testing burden, with medical-grade silicone requiring specialized polymer purification that polyvinyl chloride avoids.
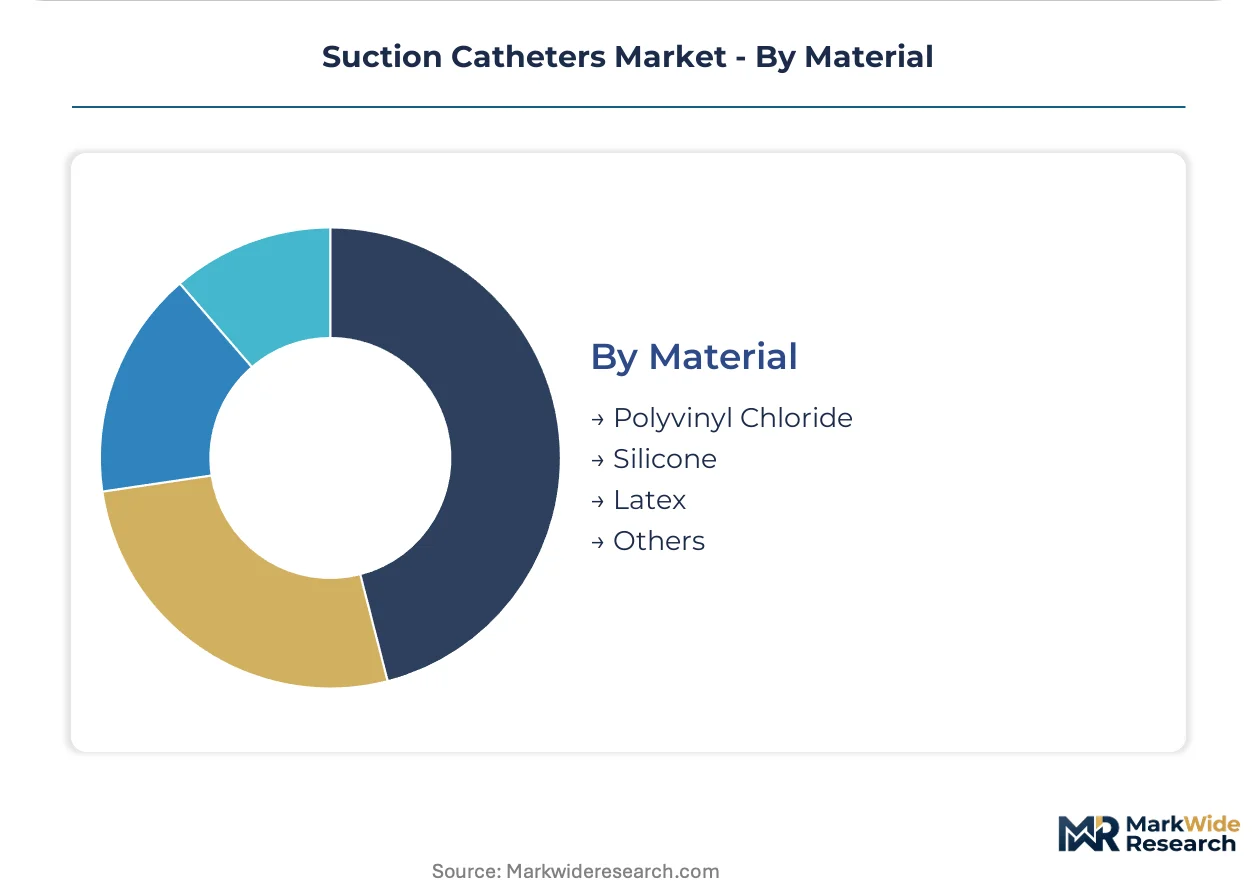
- Silicone:Medical-grade formulations offer superior biocompatibility, kink resistance, and temperature stability for extended-duration tissue contact. Latex-allergy protocols in United States and Japanese pediatric intensive care units accelerate displacement of alternative materials.
- Polyvinyl Chloride:Cost-optimized polymer dominates high-volume disposable applications where short-duration use limits biocompatibility requirements. Price pressure from group purchasing organizations sustains commodity-grade procurement.
- Latex:Natural rubber formulations persist in select emerging markets despite allergy risk labeling requirements.
- Others:Thermoplastic elastomers and specialty polymers address niche performance requirements.
Polyvinyl Chloride retains dominant volume share; Silicone represents the fastest-growing trajectory as regulatory biocompatibility standards tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo's metropolitan hospital clusters sustain per-capita suction catheter utilization rates that exceed comparable OECD markets, anchoring demand concentration for closed-system respiratory devices across Japan's acute-care networks.
United States
Medicare post-acute discharge protocols and ventilator-associated pneumonia reduction mandates drive procurement of closed-system flexible catheters in intensive care units. FDA 510(k) clearance pathways elevate supplier qualification barriers for domestic and imported devices. The southeastern and midwestern hospital consolidation corridors concentrate purchasing volume through group purchasing organization contracts.
Germany
EU MDR sterility mandates accelerate conversion from open-system to closed-system platforms across German, French, and Italian acute-care networks. Statutory health insurance post-acute coverage expansions create demand for patient-operated home suction systems. The Baden-Württemberg and Bavaria medical technology manufacturing belts anchor European supply chain infrastructure for latex-free silicone catheter lines.
Japan
Tokyo, Osaka, and Nagoya metropolitan hospital clusters sustain disproportionate per-capita utilization for trauma and acute respiratory failure management. PMDA biocompatibility testing protocols parallel FDA and EU MDR requirements, adding regulatory layers for multinational suppliers. The Kanto region's aging demographic concentration drives recurring respiratory therapy catheter consumption in long-term care facilities.
India
Central government health scheme expansion and private hospital chain consolidation in tier-2 cities open distribution channels for standardized catheter SKUs. The country's national pharmaceutical regulator enforces biocompatibility documentation for imported medical devices. Maharashtra and Gujarat industrial corridors host emerging domestic manufacturing capacity for polyvinyl chloride disposable catheters.
Suction Catheters Market Key Industry Players
Premium-margin players sit above commodity-margin players across material-grade and sterility-certification dimensions, with medical-grade silicone formulations commanding pricing separation from polyvinyl chloride commodity lines. The vendor base organizes into three strategic archetypes: diversified medical device conglomerates with cardiovascular infrastructure, specialized airway management suppliers with cleanroom manufacturing assets, and distribution-scale health systems with private-label flexibility. Dominant competitive moves include strategic partnerships with group purchasing organizations and portfolio diversification into integrated closed-suction systems.
Within the diversified conglomerate tier, Medtronic plc and Cardinal Health occupy positions that exemplify scale-driven platform consolidation across acute-care networks. Among European specialized manufacturers, B. Braun Melsungen AG anchors the latex-free and silicone catheter segment with manufacturing depth in German industrial clusters. Teleflex Incorporated and Smiths Medical represent the airway management specialist archetype, sitting within regulatory-intensive product categories where FDA and EU MDR compliance investments create qualification barriers.
| Leading Market Players |
|---|
| Medline Industries |
| Smiths Medical |
| Medtronic plc |
| Terumo Corporation |
| B. Braun Melsungen AG |
| Teleflex Incorporated |
| Cardinal Health |
| ConvaTec Group plc |
| Becton Dickinson and Company |
| Others |
Cost & Logistics Intelligence
EU MDR biocompatibility mandates gate qualified supply for premium-tier catheter lines, forcing manufacturers to absorb specialized polymer purification costs that separate medical-grade silicone from commodity polyvinyl chloride pricing tiers. Cleanroom manufacturing capacity constraints in Germany and the United States prop pricing power for incumbent suppliers while compressing margins for mid-tier competitors attempting sterility-certification upgrades.
Pricing Analysis
Value-based pricing anchored to ventilator-associated pneumonia reduction outcomes dominates hospital procurement negotiations for closed-system flexible catheters. Pricing stratifies across premium silicone formulations, standard polyvinyl chloride disposables, and economy latex alternatives, with FDA 510(k) clearance tier and ISO 14644 cleanroom certification grade serving as primary differentiation drivers. Cost compression in commodity polyvinyl chloride segments is intensifying because group purchasing organization volume consolidation rewards scale suppliers, while neonatal intensive care units demonstrate least price sensitivity due to biocompatibility non-negotiability.
Supply Chain Analysis
Direct-to-hospital e-procurement channels and consignment inventory models are displacing traditional distributor markups across United States acute-care networks. Manufacturing concentration centers on Germany, the United States, and Japan for medical-grade silicone catheter lines, with Malaysia and China hosting polyvinyl chloride disposable capacity. Supply chains draw from specialized petrochemical feedstocks, medical-grade polymer resins, and ISO 80369-compliant connector components, exposing producers to single-source vulnerability in medical silicone purification technology.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 14644 cleanroom manufacturing capacity scarcity props pricing power for qualified suppliers, creating supply-constrained conditions that favor incumbents with certified infrastructure over aspirant competitors.
For Market Incumbents: To counter group purchasing organization volume consolidation threatening standalone product margins, Medtronic plc and Cardinal Health should deepen backward integration into medical-grade silicone polymer supply while accelerating hospital system partnership lock-in through multi-year closed-suction system category contracts. For New Entrants and Emerging Players: Capture India's tier-2 city hospital infrastructure buildout by targeting standardized polyvinyl chloride catheter SKUs through distribution partnerships with central government health scheme procurement channels, leveraging price-sensitive demand unaddressed by premium silicone specialists. For Investors and Strategic Acquirers: FDA 510(k) clearance queue congestion extending product launch timelines is the leading indicator that regulatory-intensive manufacturing assets will command scarcity premiums; target specialized airway management suppliers with existing EU MDR certificates and cleanroom infrastructure in the Kanto or Baden-Württemberg clusters.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Annex I Technical Documentation Investment | Accelerates recertification timelines for legacy products previously operating under MDD certificates. |
| Hospital System Category Contract Consolidation | Bundles suction catheters with endotracheal tubes through integrated delivery network purchasing committees. |
| Silicone Polymer Backward Integration | Captures margin compression from petrochemical feedstock volatility in medical-grade formulations. |
| ISO 80369 Connector Platform Standardization | Enables French size modularity through common manifold interfaces across United States and German networks. |
| Home Respiratory Care Disposable System Launch | Addresses Medicare and German statutory health insurance post-acute discharge protocol demand. |
Research Approach
FDA 510(k) premarket notification database, EU MDR notified body conformity assessment records, and hospital procurement contract filings formed the secondary backbone, supplemented by primary interviews with biomedical engineers, intensive care clinicians, GPO contracts managers, and regulatory affairs specialists at catheter manufacturers. Bottom-up volume modeling triangulated against top-down spending analysis across product type, material formulation, end-user channel, and application setting dimensions.
Historical trendline analysis of suction catheter utilization rates in mechanical ventilation weaning protocols informed the projection framework across the analysis window, with segmentation modeling spanning flexible versus Yankauer architectures, silicone versus polyvinyl chloride material grades, and hospital versus homecare channels. CAGRs derived from surgical volume trajectories, aging demographic respiratory disease incidence curves, and infection-control protocol adoption elasticity parameters.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU MDR implementation pacing, medical-grade silicone supply disruptions, and single-use device reprocessing ban enforcement variations across national jurisdictions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Airway Stent/Lung Stent Market
Medical Devices
Global Interspinous Spacers Market
Medical Devices
Global Breast Implants Market
Medical Devices
Smart Infusion Pump Market
Medical Devices
Interatrial Shunt Devices Market
Medical Devices
Adult Water Flosser Market
Medical Devices
Global Intravenous (IV) Equipment Market
Medical Devices
Middle East and Africa Refractive Surgery Devices Market
Medical Devices
Wearable Artificial Kidney Market
Medical Devices
Transradial Access Devices Market
Medical Devices
Neurostimulation Devices Market
Medical Devices
Global Spinal Motion Preservation Device Market
Medical Devices
Oxygen Delivery Systems Market
Medical Devices
Nerve Locator Stimulator Market
Medical Devices
PET-CT Scanner Device Market
Medical Devices
Prefilled Syringes Market