
 Global Airway Stent/Lung Stent Market | 2026-2036
Global Airway Stent/Lung Stent Market Size, Share, and Industry Trends Forecast 2026-2036
Global Airway Stent/Lung Stent Market Foresight
The shift from inpatient thoracic surgery toward outpatient pulmonology clinics is collapsing traditional site-of-care boundaries for airway stent procedures. Boston Scientific Corporation leverages its bronchoscopic deployment portfolio to sustain institutional contracts across academic medical centers. Taewoong Medical Co., Ltd. anchors its position through specialized metallic stent geometries designed for malignant airway compression. Micro-Tech (Nanjing) Co., Ltd. competes on manufacturing scale for silicone stent production serving cost-sensitive hospital systems.
An airway stent is a tubular prosthesis inserted into the trachea or bronchus to maintain patency, typically manufactured from silicone, nitinol, or hybrid polymers with wall thicknesses of 1–2 mm and diameters ranging 6–18 mm to accommodate adult and pediatric anatomies. Its primary purpose is to relieve obstructive pathology from malignancy, inflammation, or postoperative stricture while preserving mucociliary function. Metallic stents dominate current procedural volume due to their radial force and conformability, yet drug-eluting stents represent the fastest-expanding margin pool as localized chemotherapy delivery gains clinical validation. Biodegradable stents remain nascent, constrained by unpredictable degradation kinetics in hyperplastic airway environments.
FDA premarket notification requirements and EMA Medical Device Regulation conformity assessments shape product development timelines and clinical trial obligations for manufacturers seeking transatlantic market access. China's NMPA issued updated nitinol device standards that mandate extended biocompatibility testing, raising barriers for imported hybrid stent platforms. Stakeholders must monitor evolving reimbursement decisions from CMS and Germany's G-BA, as these determinations will dictate whether bronchoscopic stent placement migrates fully to ambulatory settings or remains concentrated in specialty hospitals.
Market Dynamics
Outpatient migration of bronchoscopic stent procedures from inpatient thoracic surgery suites is collapsing traditional site-of-care boundaries and forcing manufacturers to redesign deployment systems for ambulatory clinical workflows.
Growth Catalysts
- CMS reimbursement expansion:United States ambulatory surgical center payment codes for bronchoscopic interventions now cover metallic stent placement, accelerating procedural volume shifts away from hospital settings.
- Nitinol superelasticity advances:Improved shape-memory alloys enable thinner-walled stent designs with equivalent radial force, reducing insertion trauma and expanding eligible patient populations.
- China's thoracic surgery center buildout:Provincial hospital systems in Sichuan and Guangdong are establishing dedicated interventional pulmonology units, concentrating demand for hybrid stent platforms.
Market Restraints
- Silicone raw material volatility:Medical-grade silicone supply chains face petrochemical feedstock price swings that compress margins for disposable stent manufacturers.
- EMA MDR conformity costs:Extended clinical evidence requirements for metallic airway stents under the Medical Device Regulation are stretching European market entry timelines to 18-24 months.
- Biodegradable polymer unpredictability:Poly-lactic acid degradation kinetics in hyperplastic airway tissue remain insufficiently controlled for reliable clinical deployment.
Strategic Opportunities
- India's underpenetrated interventional pulmonology:CDSCO streamlined medical device registration pathways create first-mover potential for metallic stent platforms in tertiary care expansion zones.
- Drug-eluting stent convergence:Combination products integrating paclitaxel or sirolimus matrices with nitinol scaffolds open localized chemotherapy delivery applications in malignant obstruction.
- Germany's G-BA innovation reimbursement:Germany's Federal Joint Committee pilot programs for bronchoscopic interventions create preferential coding for next-generation hybrid stents with enhanced mucociliary preservation.
Industry Challenges
- Interventional pulmonology fellowship scarcity:Specialized bronchoscopic stent placement training programs remain concentrated in United States academic medical centers, limiting procedural capacity expansion.
- FDA premarket notification timelines:510(k) pathway documentation for novel stent geometries requires extensive bench testing and animal studies that strain R&D budgets.
- Legacy EMR integration friction:Ambulatory pulmonology clinics face workflow disruption when deploying stent-specific procedure documentation modules within hospital information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Airway Stent/Lung Stent Market |
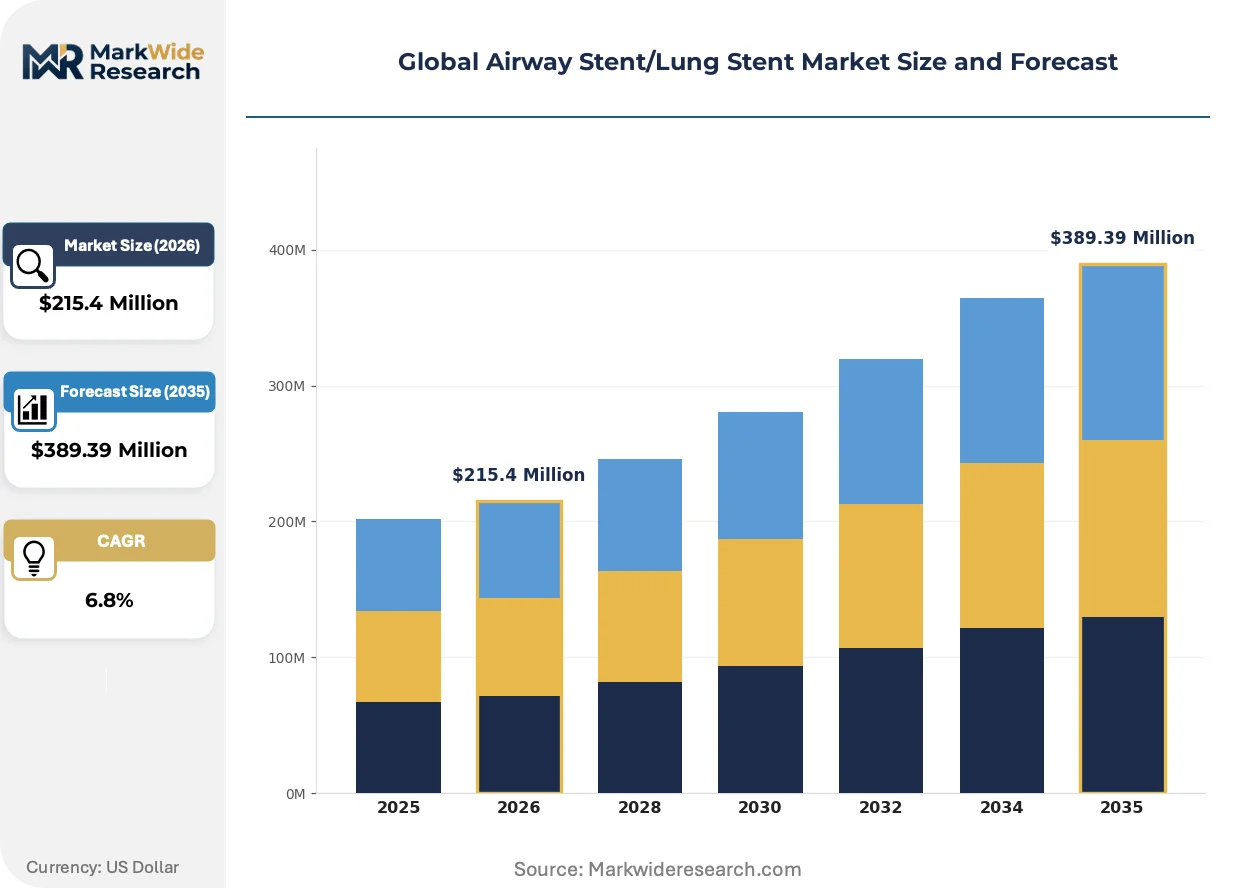
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $389.39 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Stents, Metallic Stents, Hybrid Stents, Drug-Eluting Stents, Biodegradable Stents Application: Tracheal Obstruction, Bronchial Stenosis, Malignant Airway Compression, Postoperative Airway Support, Pediatric Airway Management End User: Pulmonology Clinics, Specialty Hospitals, Thoracic Surgery Centers, Respiratory Therapy Units, Ambulatory Care Centers Deployment: Bronchoscopic Placement, Surgical Implantation, Minimally Invasive Techniques, Emergency Airway Management, Image-Guided Procedures |
| Companies Covered | Boston Scientific Corporation, Taewoong Medical Co., Ltd., Micro-Tech (Nanjing) Co., Ltd., Novatech SA, Cook Group, Merit Medical Systems, Inc., EFER ENDOSCOPY, ENDO-FLEX GmbH, Boston Medical Products, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Airway Stent/Lung Stent Market Shifts & Advancements
Digital bronchoscopy integration and personalized stent geometries are redefining procedural precision standards, while regulatory convergence pressures are compressing development-to-commercialization windows across major markets.
Drug-eluting nitinol stents are fragmenting the traditional metallic-silicone dichotomy by enabling localized therapeutic delivery alongside mechanical patency maintenance. Academic medical centers in the United States and Germany are piloting these combination products for recurrent malignant obstruction cases. The technology is fragmenting manufacturer R&D priorities away from pure mechanical engineering toward pharmaceutical-device hybrid expertise.
EMA Medical Device Regulation Annex XVI expansion now captures certain airway stent accessories previously classified as procedure kits, triggering new conformity assessment obligations for European market participants. Manufacturers must submit updated technical documentation and clinical evaluation reports for stent delivery system components. Smaller European distributors are consolidating procurement relationships to share notified body consulting costs.
Hospital purchasing committees are consolidating supplier contracts for bronchoscopic devices into single-source frameworks that bundle stents, forceps, and electrocautery accessories. This behavior compresses vendor margins while privileging manufacturers with full interventional pulmonology portfolios. The shift is most visible in United States integrated delivery networks and German hospital federations seeking procurement standardization.
Global Airway Stent/Lung Stent Market Segmentation
Airway stent procurement patterns diverge sharply across clinical settings, with regulatory pathways and reimbursement codes dictating which stent geometries gain institutional preference. Manufacturers must align product portfolios to these segment-specific commercial logics.
Product Type:
FDA 510(k) clearance timelines and EMA MDR conformity assessments create divergent market access conditions for each material platform.
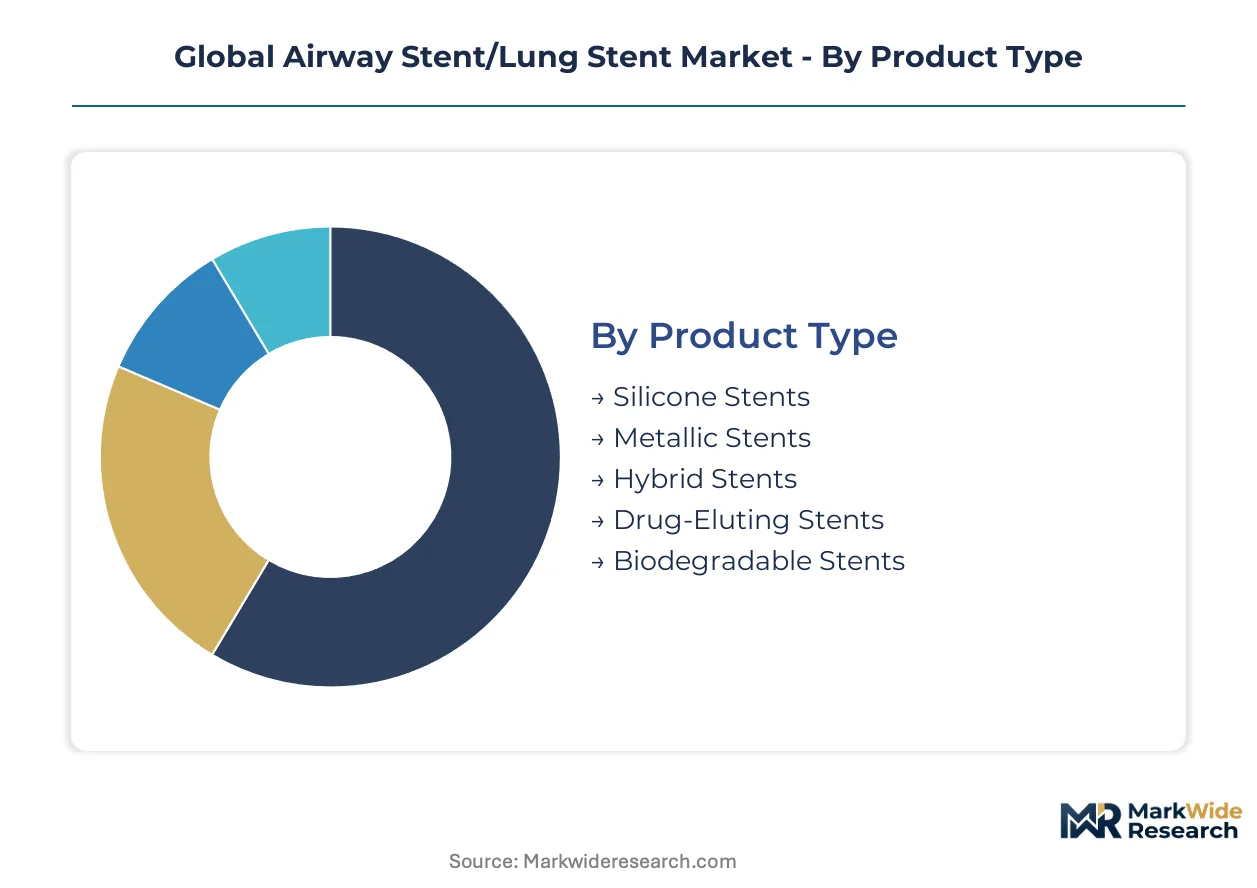
- Metallic Stents:Nitinol superelastic scaffolds deliver radial force and conformability for malignant airway compression. United States thoracic surgery centers concentrate demand for these devices due to CMS reimbursement coverage in ambulatory settings.
- Silicone Stents:Medical-grade polymer tubes with 1–2 mm wall thickness enable removability and mucociliary preservation. Cost-sensitive hospital systems in China favor silicone for benign stricture management where stent exchange protocols apply.
- Hybrid Stents:Polymer-coated metal frameworks balance radial strength with tissue compatibility.
- Drug-Eluting Stents:Paclitaxel or sirolimus matrices integrated with nitinol scaffolds enable localized chemotherapy delivery.
- Biodegradable Stents:Poly-lactic acid constructs face unpredictable degradation kinetics in hyperplastic airway environments.
Metallic stents handle the majority of throughput; drug-eluting stents are climbing the fastest on share.
Application:
Procedure volume concentrates where interventional pulmonology fellowship training and bronchoscopic infrastructure overlap.
- Malignant Airway Compression:Tumor-induced obstruction from lung cancer or metastatic disease demands rapid patency restoration. Academic medical centers in Germany and the United States drive procedural innovation for these urgent cases.
- Bronchial Stenosis:Inflammatory or post-infectious narrowing requires durable stent placement with granulation tissue management. China's provincial hospital systems in Sichuan and Guangdong are expanding interventional capacity for this indication.
- Tracheal Obstruction:Intrinsic or extrinsic compression of the central airway.
- Postoperative Airway Support:Anastomotic stricture following lung transplantation or sleeve resection.
- Pediatric Airway Management:Congenital tracheal anomalies and acquired stenosis in neonatal populations.
Bronchial stenosis accounts for the largest procedure base; malignant airway compression is gaining share fastest.
End User:
Site-of-care migration from inpatient suites to outpatient clinics is reshaping deployment system requirements and purchasing committee structures.
- Pulmonology Clinics:Outpatient bronchoscopic suites are expanding stent placement volumes as reimbursement frameworks shift. United States ambulatory surgical center payment codes now cover metallic stent procedures, accelerating this migration.
- Specialty Hospitals:Dedicated thoracic institutions maintain complex case referral networks and fellowship training programs. These centers concentrate demand for hybrid and drug-eluting platforms in malignant obstruction.
- Thoracic Surgery Centers:Inpatient surgical suites handle emergent airway compromise and combined procedures.
- Respiratory Therapy Units:Critical care settings manage temporary airway stabilization.
- Ambulatory Care Centers:Same-day discharge facilities require streamlined deployment systems.
Pulmonology clinics capture the steepest expansion trajectory; specialty hospitals retain the highest case complexity.
Deployment:
Technique selection determines capital equipment requirements and operator training pathways.
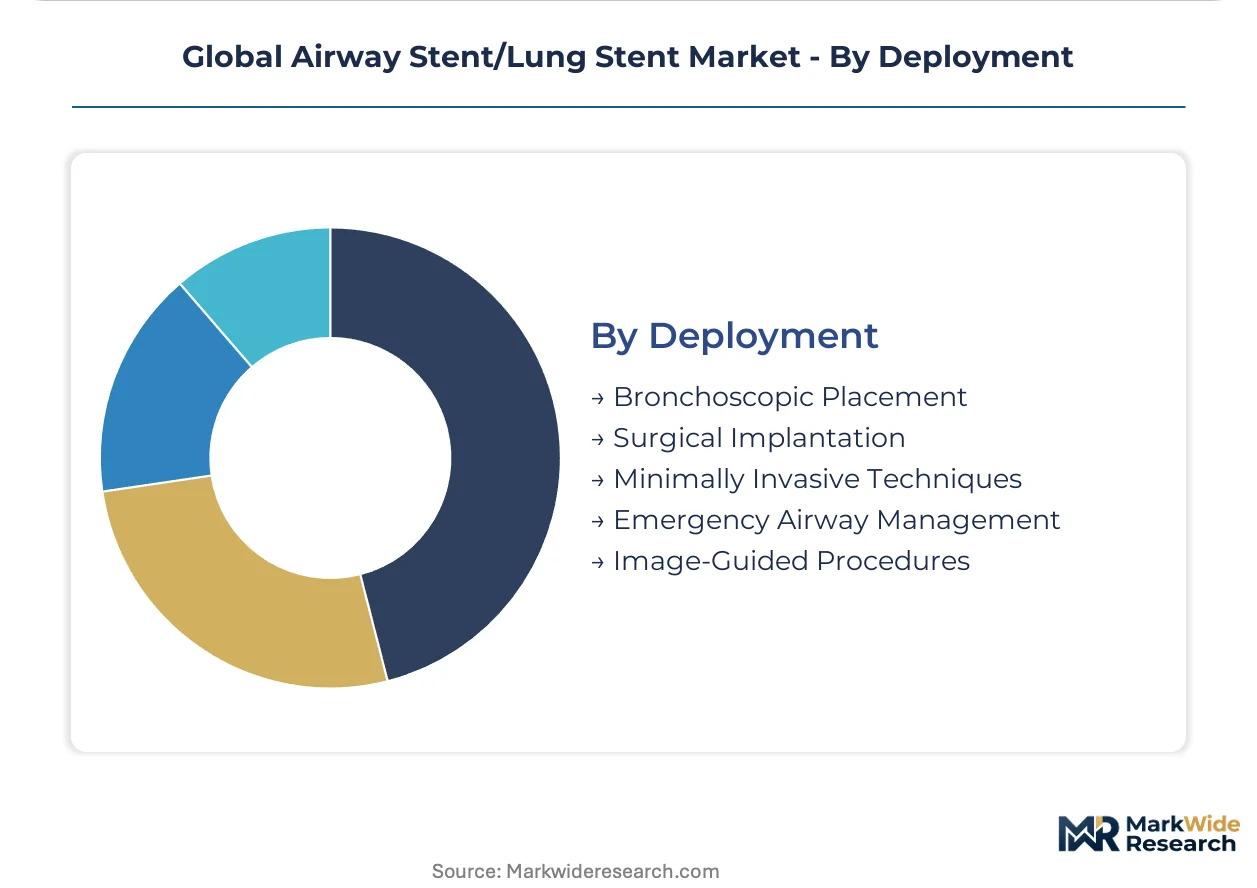
- Bronchoscopic Placement:Flexible bronchoscopy with fluoroscopic or electromagnetic navigation enables outpatient stent delivery. This technique dominates United States and German procedural volumes due to reimbursement alignment.
- Image-Guided Procedures:Cone-beam CT and electromagnetic navigation systems enable precise stent positioning in distorted airways. Academic centers in the United States are piloting these technologies for complex malignant cases.
- Surgical Implantation:Open or video-assisted thoracoscopic approaches for permanent stent fixation.
- Minimally Invasive Techniques:Rigid bronchoscopy with stent deployment under general anesthesia.
- Emergency Airway Management:Urgent stent placement for life-threatening obstruction.
Bronchoscopic placement commands the largest volume share; image-guided procedures are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device manufacturers concentrate supply-side capacity across three continents, with thoracic surgery center density and reimbursement frameworks dictating regional demand distribution. FDA and EMA regulatory pathways shape transatlantic market access timelines, while China's NMPA standards increasingly influence nitinol device specifications.
United States
CMS reimbursement expansion for ambulatory surgical center bronchoscopic procedures accelerates outpatient stent placement volumes. FDA 510(k) premarket notification requirements mandate extensive bench testing for novel stent geometries. Academic medical centers in Boston and New York anchor interventional pulmonology fellowship training networks.
Germany
G-BA pilot programs for bronchoscopic interventions create preferential reimbursement coding for next-generation hybrid stents. EMA Medical Device Regulation conformity assessments extend European market entry timelines to 18-24 months. Hospital federations in North Rhine-Westphalia consolidate procurement contracts into single-source frameworks.
China
Provincial hospital systems in Sichuan and Guangdong establish dedicated interventional pulmonology units, concentrating demand for hybrid platforms. NMPA updated nitinol device standards mandate extended biocompatibility testing for imported products. Manufacturing clusters in Nanjing scale silicone stent production for cost-sensitive domestic systems.
India
CDSCO streamlined medical device registration pathways create first-mover potential in tertiary care expansion zones. Central government hospital procurement programs prioritize domestically manufactured stents for public sector supply. Metropolitan hospital networks in Mumbai and Delhi build bronchoscopic infrastructure for malignant airway cases.
Japan
PMDA regulatory reviews emphasize long-term biocompatibility data for metallic implantable devices. METI industrial policy supports domestic medical device manufacturing competitiveness against imported platforms. Tokyo and Osaka academic centers concentrate specialized training for rigid bronchoscopy techniques.
Global Airway Stent/Lung Stent Market Competitive Landscape
Concentration sits with diversified medical technology conglomerates and specialized interventional pulmonology device manufacturers. The vendor base spans three tiers: multinational platform holders with full bronchoscopic portfolios, regional specialists in metallic or silicone geometries, and emerging Asian manufacturers competing on production scale. Dominant competitive moves include portfolio diversification into drug-eluting combination products and geographic expansion through distributor consolidation in underpenetrated markets.
Among United States-based platform holders, Boston Scientific Corporation exemplifies the diversified conglomerate archetype with institutional contract leverage across academic medical centers. Taewoong Medical Co., Ltd. anchors the specialized metallic stent manufacturer tier, while Micro-Tech (Nanjing) Co., Ltd. occupies the scale-driven manufacturing position for silicone platforms. These three entities collectively represent the competitive vectors shaping procurement committee decisions: full portfolio bundling, malignant airway specialization, and cost-optimized production respectively.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Taewoong Medical Co., Ltd. |
| Micro-Tech (Nanjing) Co., Ltd. |
| Novatech SA |
| Cook Group |
| Merit Medical Systems, Inc. |
| EFER ENDOSCOPY |
| ENDO-FLEX GmbH |
| Boston Medical Products, Inc. |
| Others |
Supply & Pricing Matrix
Silicone stent manufacturing scale in Nanjing and nitinol alloy processing in Germany establish divergent cost floors that segment global pricing tiers. High-volume Chinese production anchors economy-grade silicone platforms, while precision nitinol fabrication in European and United States facilities commands premium positioning for malignant airway applications.
Pricing Analysis
Volume-discount tiering structures separate academic medical center consortiums from standalone pulmonology clinics across procurement negotiations. Three-tier pricing stratifies across premium drug-eluting platforms, standard metallic scaffolds, and economy silicone tubes, with FDA 510(k) certification tier and after-sales deployment training bundling as primary differentiation levers. Cost compression in silicone segments intensifies as Nanjing-based manufacturers expand export capacity, while specialty hospitals exhibit lowest price sensitivity for combination-product platforms.
Supply Chain Analysis
China and Germany anchor nitinol wire drawing and superelastic alloy processing for metallic stent scaffolds, with medical-grade silicone polymer production concentrating in Jiangsu province and select European chemical clusters. Raw material dependencies span nickel-titanium feedstock, platinum-iridium marker bands, and pharmaceutical-grade polymer resins. Single-source vulnerability in nitinol alloy supply creates exposure to export licensing restrictions. Distribution runs through hospital purchasing committees and group purchasing organizations in integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around FDA 510(k) and EMA MDR conformity assessments constructs formidable defensive moats for established manufacturers. Switching costs for hospital systems—stemming from bronchoscopic deployment system standardization and fellowship training program alignment—cement incumbent positioning.
For Market Incumbents: Shield institutional contract leverage by deepening backward integration into nitinol alloy supply and accelerating drug-eluting stent pipeline submissions. Emerging Asian manufacturers with government-subsidized production capacity threaten margin compression in silicone segments. Prioritize certification investment for next-generation hybrid platforms with enhanced mucociliary preservation features.
For New Entrants and Emerging Players: Anchor in India's CDSCO-streamlined registration pathways and underpenetrated tertiary care expansion zones where bronchoscopic infrastructure buildout outpaces specialist supply. Malignant airway compression applications in metropolitan hospital networks offer the most penetrable entry point. Pursue direct hospital system partnerships bypassing distributor consolidation in German and United States markets.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors combination-product specialists with pharmaceutical-device hybrid expertise over pure mechanical engineering platforms. Long-term viability rests on regulatory approval velocity for localized chemotherapy delivery applications. Watch FDA breakthrough device designations for drug-eluting stent candidates as inflection indicators for portfolio rebalancing toward oncology-interventional convergence.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates market access for nitinol scaffold geometries in United States ambulatory settings. |
| CE Marking Pathway | Unlocks German G-BA pilot program reimbursement for hybrid stent platforms. |
| Hospital System Partnership | Secures bundled procurement contracts across interventional pulmonology device portfolios. |
| Software Companion Development | Enables EMR integration for stent-specific procedure documentation in outpatient clinics. |
| Reimbursement Strategy | Aligns CMS coding expansion with bronchoscopic placement volume migration. |
Research Methodology
A spread of perspectives from interventional pulmonologists, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers converged on the working assumptions shaping this analysis. Primary field engagement combined with secondary validation from FDA 510(k) filings, EMA MDR technical documentation, CMS Medicare reimbursement databases, and hospital procurement records. Bottom-up procedure volume estimates and top-down market sizing triangulated across the analytical framework.
Segmentation dimensions modeled span product type, application indication, end-user site-of-care, and deployment technique across the projection horizon. CAGRs derived from procedure volume trajectories, reimbursement code expansion timelines, and interventional pulmonology fellowship program growth. Forecast inputs incorporated nitinol alloy supply elasticity and NMPA regulatory pathway evolution for imported hybrid platforms.
Underlying assumptions cover stable CMS ambulatory surgical center reimbursement and EMA notified body capacity, with deviation risk concentrated in biodegradable stent clinical validation failures and silicone raw material petrochemical volatility. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Distal Embolic Filters Market
Medical Devices
Transcranial Doppler Ultrasounds System Market
Medical Devices
North America Ambulatory Infusion Pumps Market
Medical Devices
Bowel Stimulators Market
Medical Devices
Direct-Skin Wearable Medical Devices Market
Medical Devices
Artificial Vital Organs and Medical Bionics Market
Medical Devices
Global Medical Device Cleaning Market
Medical Devices
Transcatheter Bioprosthesis Market
Medical Devices
Global Medical Device Labeling Market
Medical Devices
Chordal Suture Systems Market
Medical Devices
Extended Wear Contact Lens Market
Medical Devices
United Kingdom General Surgical Devices Market
Medical Devices
Spinal Fusion Bone Graft Substitutes Market
Medical Devices
Saudi Arabia Anesthesia Devices Market
Medical Devices
Reprocessed Medical Devices Market
Medical Devices
Arteriosclerosis Detector Market