
 PET-CT Scanner Device Market | 2026-2036
PET-CT Scanner Device Market Size, Share, and Industry Trends Forecast 2026-2036
PET-CT Scanner Device Market Intelligence
Hospital procurement consortiums is reconfiguring how PET-CT scanner contracts are negotiated across integrated delivery networks. Siemens Healthineers leverages its digital imaging ecosystem to lock in multi-year service agreements with large health systems. GE Healthcare anchors its position through in-house cyclotron production and radiopharmaceutical supply chain control. Philips Healthcare differentiates via spectral detector technology that reduces patient radiation dose while preserving image fidelity.
A PET-CT scanner device fuses positron emission tomography with computed tomography into a single gantry, detecting gamma rays from radiotracer decay while simultaneously capturing high-resolution anatomical maps through x-ray tomography; the combined modality enables metabolic activity localization within millimeter-scale structural context for cancer staging, cardiac viability assessment, and neurodegenerative disease tracking. Fixed systems dominate installed base value due to their higher sensitivity detectors and throughput capacity for busy academic medical centers, while mobile configurations represent the fastest-expanding segment as rural hospitals seek to avoid capital expenditure through lease-based deployment models. Software-driven technology platforms concentrate margin pools where artificial intelligence reconstruction algorithms reduce scan times and radiologist interpretation burden.
The FDA regulates PET-CT devices as Class II medical devices under 510(k) premarket notification pathways, while the EMA's Medical Device Regulation imposes stricter clinical evidence requirements for new installations across European member states. China's NMPA accelerates review timelines for domestically manufactured systems under innovation priority channels, reshaping competitive access for United Imaging Healthcare and Neusoft Medical Systems. Stakeholders must monitor reimbursement code valuations for PET radiopharmaceuticals, as these determine hospital capital allocation cycles more directly than equipment hardware pricing alone.
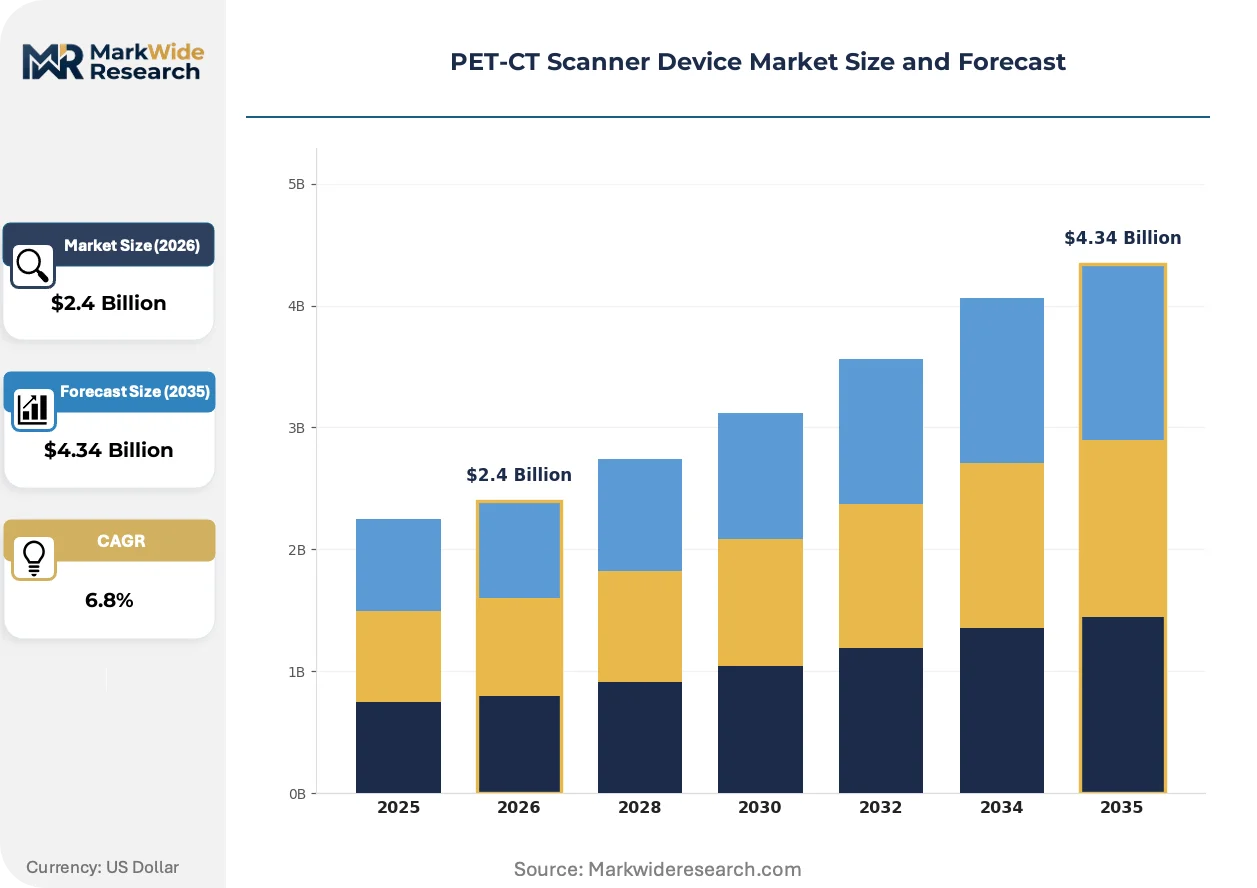
Market Dynamics
Hybrid molecular imaging systems are reshaping hospital capital allocation cycles as oncology departments prioritize metabolic-anatomical fusion capabilities over standalone modalities. The FDA's breakthrough device designation pathway accelerates reimbursement code establishment, compressing the timeline between regulatory clearance and clinical revenue generation.
Growth Catalysts
- 21st Century Cures Act Framework:The FDA's expedited review pathway for breakthrough devices shortens premarket notification timelines for novel detector technologies. PET-CT manufacturers leverage this to secure reimbursement codes faster than traditional 510(k) routes.
- Oncology Department Expansion:Tertiary hospitals in the United States and China are consolidating cancer care into dedicated towers, driving bundled procurement of hybrid imaging suites with cyclotron facilities.
- Digital Reconstruction Algorithms:Artificial intelligence-powered image reconstruction reduces scan acquisition times by half while maintaining diagnostic confidence, allowing academic medical centers to double daily throughput without gantry expansion.
Market Restraints
- Fluorine-18 Supply Concentration:Regional cyclotron capacity limits radiopharmaceutical availability for rural hospitals, creating geographic service deserts outside major metropolitan clusters.
- EMA Medical Device Regulation:Stricter clinical evidence requirements for new PET-CT installations across European member states extend certification timelines and inflate documentation costs for manufacturers.
- Helium-3 Scarcity:Detector cooling requirements depend on constrained noble gas supplies, exposing installed base maintenance costs to commodity price volatility and export restriction risks.
Strategic Opportunities
- Mobile Deployment Models:Rural hospitals in Germany and the United States are adopting lease-based mobile PET-CT services to avoid capital expenditure while maintaining referral network competitiveness.
- Cardiac Viability Assessment:Myocardial perfusion imaging represents an underpenetrated application segment as cardiology departments seek alternatives to invasive catheterization for ischemia evaluation.
- China NMPA Innovation Priority:Domestic manufacturers United Imaging Healthcare and Neusoft Medical Systems benefit from accelerated review timelines, creating procurement preference for locally produced systems in public hospital tenders.
Industry Challenges
- Radiopharmaceutical Synthesis Expertise:Qualified nuclear pharmacists and cyclotron operators remain scarce, constraining operational readiness for newly installed systems regardless of hardware availability.
- Legacy PACS Integration:Hybrid imaging data volumes overwhelm outdated picture archiving systems, forcing hospitals to undertake costly infrastructure upgrades parallel to scanner procurement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PET-CT Scanner Device Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed, Mobile, Hybrid, Portable End User: Hospitals, Imaging Centers, Research Institutes, Outpatient Facilities Technology: Digital, Analog, Software-Driven, Advanced Imaging Application: Oncology, Cardiology, Neurology, Clinical Research |
| Companies Covered | Siemens Healthineers, GE Healthcare, Philips Healthcare, Canon Medical Systems, Hitachi, United Imaging Healthcare, Neusoft Medical Systems, Mediso, Bruker Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PET-CT Scanner Device Market Strategic Shifts & Innovations
Spectral detector architectures and cloud-native reconstruction platforms are converging to reduce radiation exposure while accelerating diagnostic workflows. Software-defined imaging capabilities are shifting value capture from hardware sales toward recurring service and algorithm licensing revenue streams.
Digital photon counting detector technology is digitizing signal acquisition at the sensor level, eliminating analog-to-digital conversion noise that degrades low-dose image quality. Academic medical centers in the United States and Germany are prioritizing these systems for pediatric and repeat-scan oncology protocols. The technology is digitizing procurement criteria, making detector quantum efficiency a primary evaluation metric over traditional spatial resolution specifications.
The EMA's Medical Device Regulation imposes post-market surveillance obligations that force manufacturers to maintain clinical registries for installed systems across European member states. This creates ongoing evidence generation costs that favor established vendors with dedicated regulatory affairs infrastructure. Smaller equipment manufacturers are responding by limiting European market entry to focus on United States and Asia-Pacific registrations.
Hospital procurement consortiums are consolidating contract negotiation power across integrated delivery networks, unbundling hardware acquisition from multi-year service agreements. Large health systems now demand outcome-based performance guarantees for detector uptime and radiopharmaceutical supply continuity. This concentration is most visible in the United States, where group purchasing organizations command pricing leverage that individual hospitals cannot replicate.
PET-CT Scanner Device Market Segmentation
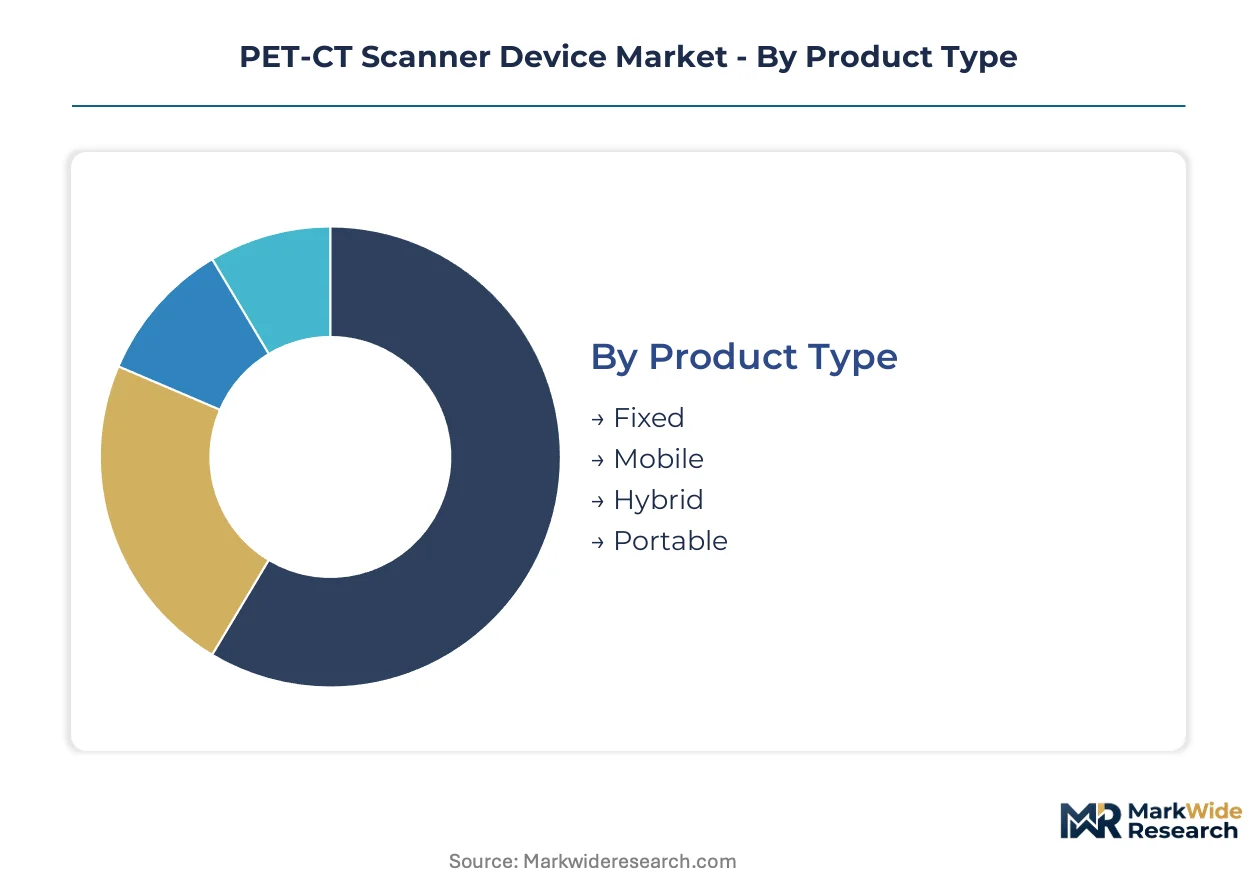
PET-CT scanner segmentation reveals how hardware configuration, clinical setting, and detector technology align with specific metabolic imaging demands. Each dimension carries distinct procurement logic, reimbursement pathways, and operational constraints that shape vendor positioning.
Product Type:
Fixed installations anchor academic medical centers with high throughput requirements; mobile units penetrate rural markets through lease-based deployment.
- Fixed:Permanent gantry installations integrate high-sensitivity detector arrays and dedicated radiopharmaceutical synthesis suites. Tertiary hospitals in the United States and Germany prioritize these systems for oncology staging protocols where daily scan volumes exceed 40 patients.
- Mobile:Trailer-mounted configurations travel between rural hospitals on weekly rotation schedules, eliminating capital expenditure barriers for facilities below 150 beds. Community health systems in the United States Midwest and German federal states deploy these to maintain referral network competitiveness without cyclotron investment.
- Hybrid:Dual-modality architectures combine PET metabolic mapping with MRI soft-tissue contrast for brain and pelvic imaging applications.
- Portable:Compact cart-based systems serve bedside cardiac viability assessment in intensive care settings where patient transport risks outweigh mobility constraints.
Established volume favors Fixed; emerging adoption favors Mobile.
End User:
Procurement authority concentrates differently across institutional types, with capital allocation cycles varying from annual hospital budgets to multi-year research grants.
- Hospitals:Integrated delivery networks negotiate enterprise-wide contracts bundling hardware, service, and radiopharmaceutical supply. United States health systems exceeding 500 beds leverage group purchasing organization leverage to extract uptime guarantees and dose optimization consulting.
- Imaging Centers:Independent diagnostic facilities compete on appointment availability and report turnaround speed. Freestanding centers in Germany's ambulatory care sector emphasize same-day scheduling for FDG-PET oncology referrals from regional oncologists.
- Research Institutes:Academic medical centers prioritize novel radiotracer development capabilities and protocol flexibility for investigator-initiated trials.
- Outpatient Facilities:Limited-service clinics focus on high-margin cardiac perfusion studies with streamlined patient throughput models.
Capital deployment tilts toward Hospitals; margin capture concentrates in Imaging Centers.
Technology:
Detector signal processing architectures determine quantum efficiency, dose reduction potential, and algorithmic reconstruction compatibility.
- Digital:Photon-counting detectors digitize gamma ray detection at the sensor level, eliminating analog noise floors that degrade low-dose image quality. Pediatric oncology departments in the United States and Germany specify these systems for repeat-scan protocols where cumulative radiation exposure limits drive detector selection criteria.
- Software-Driven:AI-powered reconstruction platforms reduce acquisition times while maintaining diagnostic confidence, allowing throughput expansion without physical gantry upgrades. Siemens Healthineers and GE Healthcare anchor subscription revenue models on these algorithm licenses.
- Analog:Legacy scintillation crystal systems persist in installed bases where replacement cycles extend beyond 12 years.
- Advanced Imaging:Spectral detector architectures separate photon energy levels to reduce scatter artifacts and improve lesion conspicuity in obese patients.
Replacement demand sustains Analog; upgrade cycles accelerate Digital.
Application:
Clinical indication determines radiotracer selection, scan protocol duration, and reimbursement code valuation.
- Oncology:FDG-PET dominates cancer staging, response assessment, and recurrence detection across solid tumor types. United States Medicare reimbursement rates for PET-guided radiation therapy planning drive hospital capital allocation toward hybrid systems with 4D respiratory gating capabilities.
- Cardiology:Myocardial perfusion imaging with rubidium-82 or ammonia-13 tracers offers non-invasive ischemia evaluation alternatives to invasive catheterization. Cardiology departments in Germany and the United States are expanding PET-CT adoption as coronary CT angiography volumes strain catheterization lab capacity.
- Neurology:Amyloid and tau imaging for Alzheimer's disease progression tracking requires specialized radiochemistry expertise and extended scan durations.
- Clinical Research:Novel therapeutic trial endpoints demand customized acquisition protocols and centralized image analysis workflows.
Revenue concentration rests in Oncology; expansion opportunity concentrates in Cardiology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Cincinnati/Northern Kentucky International Airport cargo hub anchors North American radiopharmaceutical distribution networks, enabling just-in-time Fluorine-18 delivery to Midwestern hospital systems. Dense cyclotron clustering around Boston, Houston, and Los Angeles creates metropolitan service radii that exclude rural facilities.
United States
Academic medical centers in Boston and Houston drive detector technology procurement through NIH-funded research consortia. The FDA's 21st Century Cures Act breakthrough device designation compresses reimbursement timelines for novel systems. The Cleveland Clinic and MD Anderson Cancer Center anchor hybrid imaging adoption through bundled cyclotron-PET-CT capital programs.
Germany
Charité Berlin and Heidelberg University Hospital prioritize digital photon-counting detectors for pediatric oncology protocols under national radiation protection standards. The EMA's Medical Device Regulation imposes post-market surveillance registries that extend certification timelines. Bavarian medical device manufacturing clusters around Erlangen supply detector components to domestic installers.
China
Public hospital tier-3 expansion in Shanghai and Guangzhou drives domestic system procurement through centralized provincial tenders. The NMPA's innovation priority channel accelerates review timelines for United Imaging Healthcare and Neusoft Medical Systems. The Yangtze River Delta concentration of cyclotron facilities enables same-day radiopharmaceutical delivery to Suzhou and Hangzhou cancer centers.
Japan
National Health Insurance reimbursement revisions for amyloid imaging expand neurology application demand at Tokyo and Osaka university hospitals. The PMDA's streamlined review for predicate devices accelerates replacement cycles. The Kobe biomedical cluster integrates PET-CT procurement with proton therapy center construction.
United Kingdom
NHS England's specialized commissioning framework concentrates PET-CT capacity in London, Manchester, and Newcastle tertiary centers. The MHRA's post-Brexit regulatory autonomy enables faster adoption of AI reconstruction algorithms cleared under FDA pathways. The Cambridge-Oxford biomedical corridor drives research system procurement through Cancer Research UK infrastructure grants.
PET-CT Scanner Device Market Key Industry Players
On the supply side, the industry is consolidated around three dominant imaging conglomerates with integrated radiopharmaceutical supply chains and multi-decade service infrastructure. Siemens Healthineers, GE Healthcare, and Philips Healthcare anchor the premium tier through detector manufacturing scale and algorithm development ecosystems. Mid-tier competition emerges from Japanese and Chinese manufacturers with regional cost advantages. Dominant competitive moves include cyclotron supply chain vertical integration and AI reconstruction platform licensing.
Within the premium-tier vector, Siemens Healthineers and GE Healthcare exemplify integrated-systems archetypes with captive radiopharmaceutical production and decade-long service agreements. Philips Healthcare occupies a differentiated position emphasizing detector dose-reduction technologies. Among Asia-Pacific challengers, United Imaging Healthcare and Neusoft Medical Systems represent state-supported domestic champions benefiting from NMPA procurement preferences in China's public hospital sector. These five entities collectively span the pricing and technology spectrum from research-grade digital photon-counting systems to cost-optimized configurations for emerging market volume deployment.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| Philips Healthcare |
| Canon Medical Systems |
| Hitachi |
| United Imaging Healthcare |
| Neusoft Medical Systems |
| Mediso |
| Bruker Corporation |
| Others |
Cost & Logistics Intelligence
Helium-3 scarcity and export restriction exposure from Russia and Qatar determines both detector maintenance cost spreads and radiopharmaceutical supply chain geography. Buyers face tiered service pricing that separates academic medical centers with captive cyclotron facilities from rural hospitals dependent on mobile lease arrangements.
Pricing Analysis
Volume-discount tiering separates enterprise health systems commanding multi-year bundled contracts from independent imaging centers negotiating per-scan service agreements. Three-tier pricing structure across premium digital photon-counting systems, standard analog-detector platforms, and economy mobile configurations reflects detector quantum efficiency and radiopharmaceutical synthesis bundling. Cost compression in the mobile segment intensifies as Siemens Healthineers and GE Healthcare compete for rural hospital lease contracts. Group purchasing organizations exhibit lowest price sensitivity due to consolidated negotiation leverage, while standalone outpatient clinics face acute margin pressure from Medicare reimbursement code fluctuations.
Supply Chain Analysis
Contract manufacturing concentration rests with Siemens Healthineers' Erlangen fabrication complex, GE Healthcare's Waukesha detector foundry, and Philips Healthcare's Best component assembly for spectral detector arrays. Detector crystal growth draws from Japan and the United States for lutetium-yttrium oxyorthosilicate feedstock, while superconducting magnet winding centers on Germany and China. Single-source vulnerability concentrates in helium-3 cooling gas, where Russian export quotas and Qatari production bottlenecks threaten detector maintenance continuity. Distribution runs through radiopharmaceutical synthesis networks anchored to regional cyclotron clusters, with just-in-time Fluorine-18 delivery constraining effective service radii to 150 kilometers from production facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The PET-CT scanner market sits at a post-pandemic capital replacement upswing driven by NIH-funded oncology research infrastructure grants. Hospital procurement cycles are reaccelerating as deferred detector upgrades clear budget committees.
For Market Incumbents: Build cyclotron supply chain moats through backward integration into radiopharmaceutical production and regional isotope distribution networks. Siemens Healthineers and GE Healthcare should lock multi-year service agreements with integrated delivery networks before United Imaging Healthcare captures tier-3 hospital tenders in China. Detector uptime guarantees and AI reconstruction algorithm subscriptions represent the primary defensive lever against Philips Healthcare's dose-reduction differentiation.
For New Entrants and Emerging Players: Mid-market mobile PET-CT services in the United States Midwest and German federal states represent the most penetrable entry point where capital expenditure constraints exclude fixed gantry procurement. Neusoft Medical Systems should leverage NMPA innovation priority channels to undercut premium-tier pricing in provincial Chinese hospital tenders. A lease-based go-to-market angle with per-scan revenue sharing minimizes rural hospital adoption friction.
For Investors and Strategic Acquirers: The market sits at a mid-cycle expansion phase that favors radiopharmaceutical supply chain specialists over pure hardware manufacturers. Long-term viability across the next decade hinges on software-defined imaging revenue streams and recurring service contract attach rates. Acquisition targets should display cyclotron facility ownership or AI reconstruction platform development capabilities. The signal to watch is CMS reimbursement code valuation shifts for novel amyloid and tau imaging tracers, which would reallocate hospital capital toward neurology-capable systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Cyclotron Supply Chain Integration | Captive Fluorine-18 production secures radiopharmaceutical continuity for MD Anderson and Cleveland Clinic networks. |
| AI Reconstruction Platform Licensing | Subscription revenue from Siemens Healthineers' Deep Resolve algorithms reduces customer acquisition cost per academic medical center. |
| Mobile Deployment Model Expansion | Lease-based trailer configurations penetrate rural German and United States markets without capital expenditure barriers. |
| Digital Photon-Counting Detector Scale-Up | Manufacturing scale at Erlangen and Best fabrication facilities lowers unit cost for pediatric oncology protocols. |
| Reimbursement Strategy Alignment | FDA breakthrough device designation compresses timelines between regulatory clearance and Medicare code establishment. |
Research Approach
Cross-validation between hospital procurement database analysis and GPO contract documentation anchors the qualitative findings. Primary interviews with biomedical engineers, hospital purchasing committee chairs, cyclotron facility operators, and GPO contracts managers combined with secondary validation from FDA 510(k) filings, EMA Medical Device Regulation submissions, CMS Medicare reimbursement schedules, and hospital capital expenditure disclosures. Bottom-up installed base modeling and top-down revenue triangulation across detector technology tiers and geographic clusters ensured methodological robustness.
Calibration against historical replacement cycles and cyclotron facility expansion timelines shaped the analytical framework. Segmentation dimensions across the projection horizon include product configuration, detector signal processing architecture, clinical application, and institutional procurement authority. CAGRs derived from weighted average of equipment shipment volumes and service revenue streams, with sensitivity testing for radiopharmaceutical supply disruption scenarios and reimbursement code revision risks.
Practitioners should monitor helium-3 export quota announcements, NMPA innovation priority channel expansion, and CMS PET radiopharmaceutical reimbursement valuations for early signals of forecast revision. Quarterly review of cyclotron facility commissioning rates and hospital capital budget approval velocities is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Aortic Valve Replacement Devices Market
Medical Devices
High Viscosity Bone Cement Market
Medical Devices
Global Defibrillators Market
Medical Devices
Neurostimulation Devices Market
Medical Devices
Urinary Incontinence Devices Market
Medical Devices
Medical Tricorder Market
Medical Devices
Global Nebulizers Market
Medical Devices
Metered Dose Squeeze Dispenser Market
Medical Devices
Medical Machine Battery Market
Medical Devices
MRI Motion Tracking Systems Market
Medical Devices
Non-Invasive Intracranial Pressure Monitoring Device Market
Medical Devices
Breast Biopsy Marker Market
Medical Devices
Cardiac Catheters and Guidewires Market
Medical Devices
Global Automated External Defibrillators Market
Medical Devices
Global Cardiopulmonary Bypass Accessory Equipment Market
Medical Devices
Capsule Endoscope Systems Market