
 Smart Infusion Pump Market | 2026-2036
Smart Infusion Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Infusion Pump Market Outlook
Homecare is pivoting toward ambulatory smart infusion systems as payors push for reduced hospital length of stay. ICU Medical Inc leverages specialized drug library databases to differentiate its platform across acute and post-acute settings. Fresenius Kabi AG anchors its position through manufacturing scale in parenteral nutrition delivery systems. Baxter International Inc sustains channel control via long-term hospital supply agreements that bundle pumps with disposable sets.
A smart infusion pump is a programmable electromechanical device that delivers fluids, medications, or nutrients into a patient's circulatory system at controlled rates, typically with flow precision measured in milliliters per hour and integrated dose-error reduction software that cross-references provider orders against institutional drug libraries. Its primary commercial purpose is to reduce adverse drug events in high-risk infusion therapy while generating operational data for quality improvement and liability reduction. Volumetric pumps occupy the largest installed base in hospitals due to their versatility across fluid types and flow ranges, though ambulatory pumps represent the fastest-growing category as home-based chemotherapy and pain management protocols expand. Software integration captures disproportionate margin attention because recurring license fees and drug library update subscriptions generate predictable revenue streams that hardware sales alone cannot match.
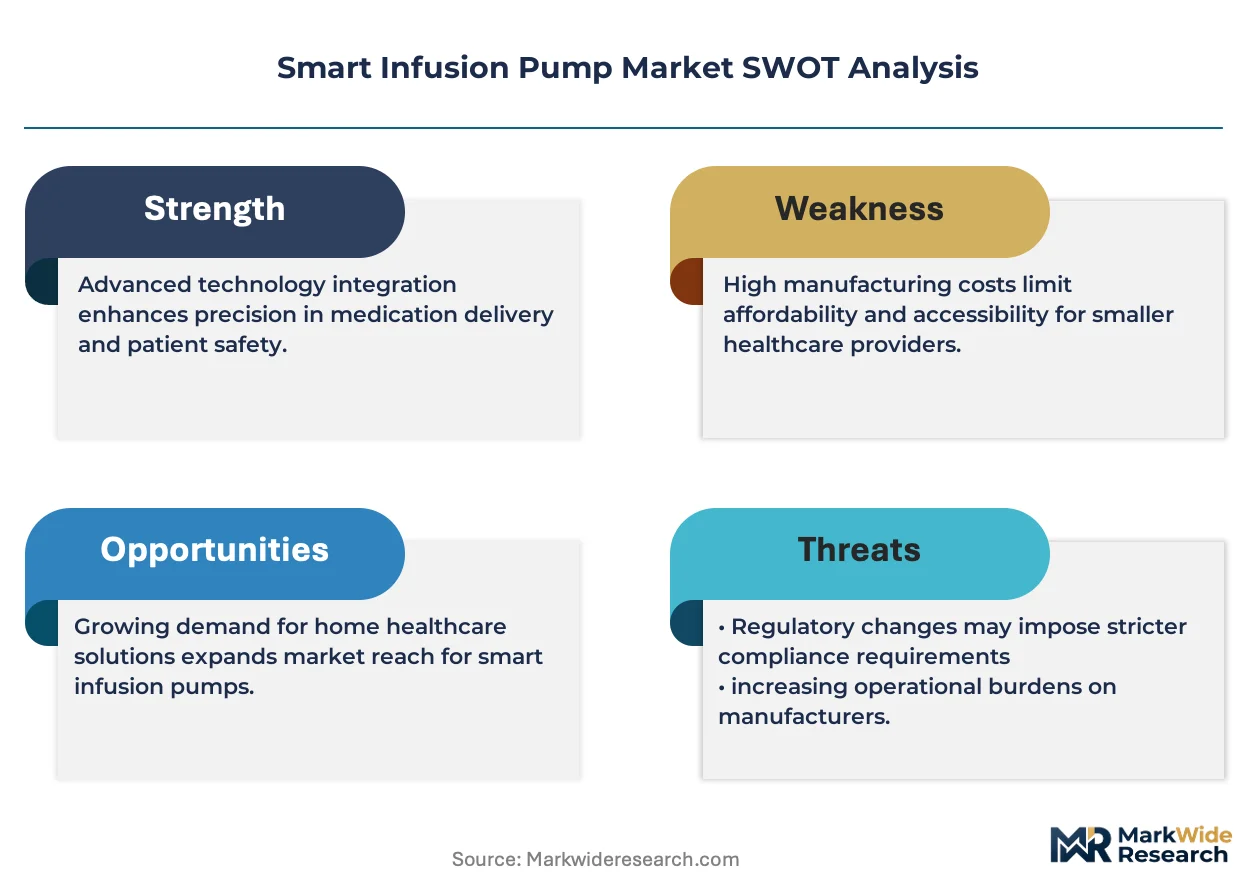
The FDA enforces 510(k) premarket notification and infusion pump improvement initiative requirements that mandate error-reduction design features and postmarket surveillance reporting, effectively raising engineering barriers for new entrants. The EU Medical Device Regulation imposes stricter clinical evidence standards and unique device identification traceability that extend certification timelines and compliance costs for manufacturers seeking CE marking. Stakeholders must monitor how FDA guidance on interoperability standards and EMA vigilance reporting requirements converge to reshape competitive positioning in connected care ecosystems.
Market Dynamics
Wireless communication protocols and dose-error reduction software mandates are compressing replacement cycles as hospitals face simultaneous pressure from FDA 510(k) enforcement and cybersecurity vulnerability disclosures.
Growth Catalysts
- FDA Infusion Pump Improvement Initiative:Postmarket surveillance requirements force legacy device retirement, creating replacement demand across acute care networks.
- Ambulatory chemotherapy protocols:Oncology centers in the United States deploy portable pumps for extended infusion regimens, extending therapy beyond inpatient settings.
- Germany's surgical volume expansion:Aging demographics sustain procurement of volumetric systems for perioperative fluid management in tertiary hospitals.
Market Restraints
- Semiconductor supply concentration:Microcontroller shortages from East Asian foundries delay pump manufacturing schedules and extend lead times.
- EU MDR certification timelines:Stricter clinical evidence standards extend CE marking processes by 12-18 months for new connectivity features.
- Manual infusion alternatives:Gravity drip systems persist in resource-constrained settings, limiting addressable market penetration.
Strategic Opportunities
- Japan's homecare infrastructure:METI reimbursement incentives for remote patient monitoring create entry points for connected ambulatory pumps.
- Interoperability standards convergence:IEEE 11073 and HL7 FHIR integration enables data monetization through quality analytics subscriptions.
- Pediatric drug library specialization:Weight-based dosing algorithms for neonatal intensive care represent underserved configuration demand.
Industry Challenges
- Biomedical engineering talent scarcity:Firmware security expertise shortages delay patch deployment for legacy installed bases.
- Legacy EMR integration complexity:Proprietary hospital information systems require custom middleware development for seamless pump connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Infusion Pump Market |
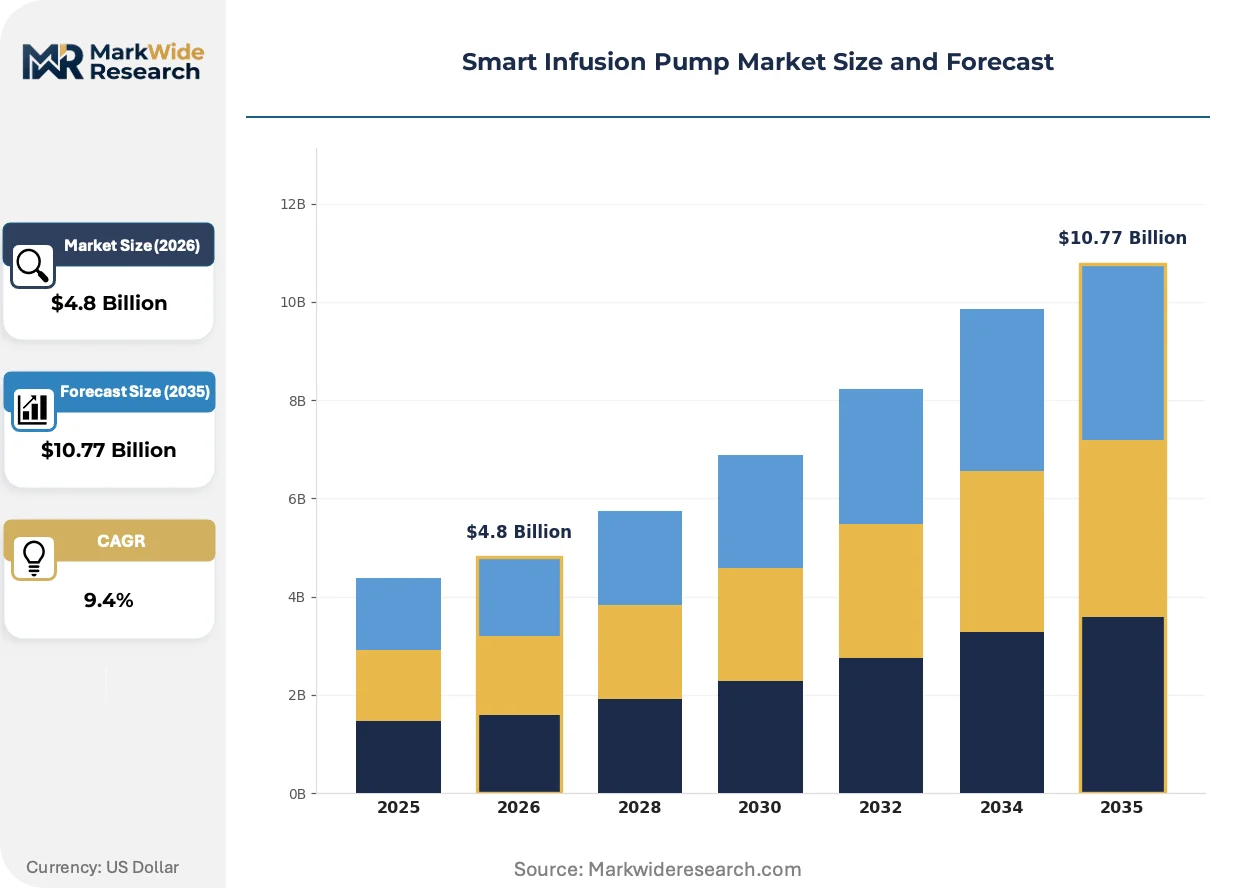
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.77 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Volumetric Pumps, Syringe Pumps, Elastomeric Pumps, Ambulatory Pumps End User: Hospitals, Homecare, Clinics, Long-term Care Facilities Technology: Smart Technology, Wireless Communication, Mobile Application, Software Integration Application: Pain Management, Chemotherapy, Anesthesia, Nutrition Delivery |
| Companies Covered | ICU Medical Inc, Medtronic plc, Becton Dickinson and Company, Mindray Medical International Limited, Terumo Corporation, Baxter International Inc, B Braun Melsungen AG, Q-Core Medical, Fresenius Kabi AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Infusion Pump Market Strategic Shifts
Cloud-native pump architectures and predictive maintenance algorithms are displacing reactive service models while regulatory pressure on cybersecurity postmarket management intensifies engineering resource allocation.
Closed-loop infusion systems with integrated physiological sensors are expanding into high-acuity anesthesia and insulin delivery applications. Academic medical centers in the United States pilot these configurations for glycemic control protocols. The technology is expanding into liability reduction strategies as automated response capabilities demonstrate adverse event suppression in peer-reviewed studies.
EMA's Medical Device Regulation vigilance reporting requirements for serious incidents mandate automated adverse event transmission within tight windows. Manufacturers must reconfigure postmarket surveillance infrastructure to capture field performance data continuously. Connectivity-enabled pumps face disproportionate compliance burden as software-as-medical-device classifications trigger additional notified body scrutiny.
Hospital procurement committees now unbundle hardware acquisition from service contracts, forcing pump vendors to compete on discrete software subscription pricing. Group purchasing organizations consolidate negotiating leverage across multi-hospital systems. This pattern concentrates in the United States where IDN consolidation has reduced the number of independent purchasing entities by half over the past decade.
Smart Infusion Pump Market Segmentation
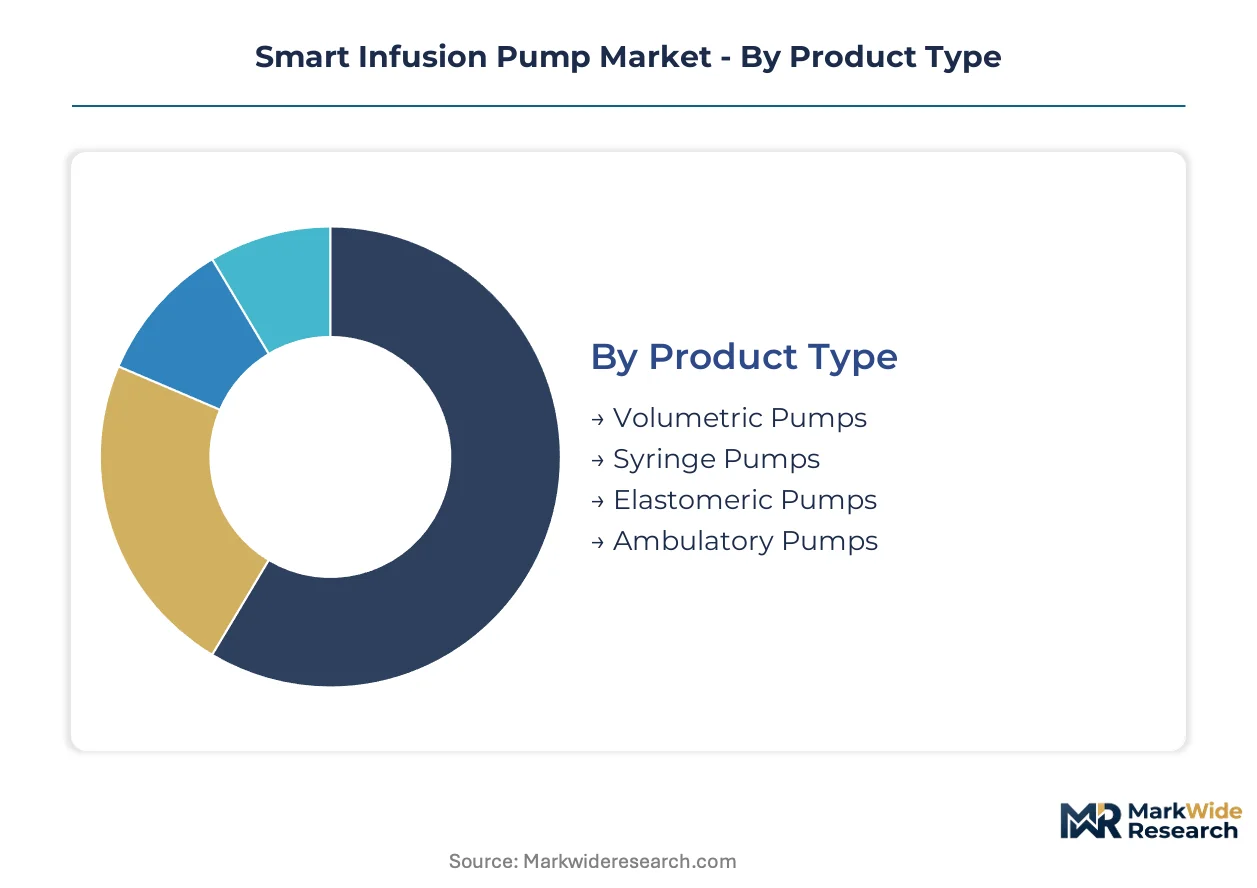
Smart infusion pump segmentation reveals how hardware versatility, connectivity sophistication, and care setting migration reshape procurement priorities. Understanding these divides exposes where margin concentrates and which configurations face replacement pressure from regulatory mandates.
Product Type:
Volumetric pumps anchor hospital installed bases through flow range flexibility, while ambulatory systems command premium pricing through portability engineering.
- Volumetric Pumps:These devices deliver large fluid volumes across broad flow rate ranges using peristaltic or cassette mechanisms, making them the default choice for general infusion therapy in acute care settings. Demand concentrates in tertiary hospitals across Germany and the United States where perioperative fluid management sustains procurement cycles despite longer replacement intervals.
- Ambulatory Pumps:Compact battery-powered devices enable continuous infusion outside clinical facilities through wearable designs with programmable basal and bolus delivery. Oncology centers in the United States deploy these systems for extended chemotherapy regimens as payors push reduced hospital length of stay, creating the steepest expansion trajectory among all product types.
- Syringe Pumps:Precision piston-driven mechanisms deliver small-volume medications with high accuracy for neonatal and pediatric applications requiring tight dosing control.
- Elastomeric Pumps:Disposable balloon reservoirs provide passive pressure-driven infusion for post-operative pain management and antibiotic delivery in homecare transitions.
Today's leader: Volumetric Pumps. Tomorrow's challenger: Ambulatory Pumps.
End User:
Procurement authority shifts from centralized hospital supply chains toward distributed homecare reimbursement frameworks.
- Hospitals:Acute care networks drive bulk purchasing through group purchasing organizations, with IDN consolidation in the United States reducing independent purchasing entities by half over the past decade. FDA 510(k) enforcement and cybersecurity vulnerability disclosures compress replacement cycles for legacy installed bases.
- Homecare:Reimbursement incentives from Japan's METI for remote patient monitoring create entry points for connected ambulatory pumps, expanding therapy beyond inpatient settings for chemotherapy and pain management protocols.
- Clinics:Outpatient infusion centers require mid-range volumetric systems with dose-error reduction software for same-day chemotherapy and biologic administration.
- Long-term Care Facilities:Skilled nursing facilities adopt simplified pump interfaces with reduced feature sets for stable patients transitioning from acute care.
Hospitals retain volume dominance. Homecare captures margin expansion.
Technology:
Software-enabled recurring revenue streams now exceed hardware margin profiles across connected pump portfolios.
- Software Integration:Drug library databases and dose-error reduction algorithms generate predictable subscription revenue through recurring license fees and institutional configuration updates, capturing disproportionate margin attention from manufacturers.
- Wireless Communication:IEEE 11073 and HL7 FHIR protocol integration enables real-time data transmission to electronic medical records and quality analytics platforms, though EU MDR certification timelines extend by 12-18 months for new connectivity features.
- Smart Technology:Closed-loop systems with integrated physiological sensors automate response capabilities for glycemic control and anesthesia delivery in academic medical centers.
- Mobile Application:Patient-facing interfaces for ambulatory pump monitoring and dose logging support remote adherence tracking in homecare settings.
Software Integration commands current margin pools. Wireless Communication faces regulatory bottlenecks.
Application:
High-risk medication categories drive premium pricing through liability-sensitive dosing requirements.
- Chemotherapy:Cytotoxic infusion protocols demand precise flow control and drug library cross-referencing to prevent dosing errors with narrow therapeutic indices, with portable pump adoption expanding regimens into home settings.
- Anesthesia:Target-controlled infusion systems with pharmacokinetic modeling integrate into operating room workflows for intravenous anesthetic delivery, with closed-loop configurations demonstrating adverse event suppression in peer-reviewed studies.
- Pain Management:Patient-controlled analgesia modules with lockout intervals and dose limits address opioid safety concerns in post-surgical recovery.
- Nutrition Delivery:Parenteral nutrition systems require specialized configurations for lipid emulsion compatibility and extended infusion durations in intestinal failure patients.
Chemotherapy anchors revenue concentration. Anesthesia enables technology premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are relocating final assembly and software development to jurisdictions with streamlined medical device certification pathways, exploiting gaps between FDA 510(k) timelines and EU MDR conformity assessment durations. This regulatory arbitrage is reshaping investment flows across North America, Europe, and Asia-Pacific.
United States
Hospital consolidation into integrated delivery networks has halved independent purchasing entities over the past decade, concentrating procurement leverage among fewer decision-makers. FDA infusion pump improvement initiative mandates accelerate legacy device retirement cycles. The Boston-Cambridge corridor anchors connected pump R&D, with academic medical centers piloting closed-loop anesthesia configurations.
Germany
Aging demographics sustain volumetric pump demand for perioperative fluid management in tertiary hospitals across Bavaria and North Rhine-Westphalia. EU MDR stricter clinical evidence standards extend CE marking timelines by 12-18 months for connectivity features. The Baden-Württemberg industrial cluster hosts precision manufacturing operations for cassette-based delivery mechanisms.
Japan
METI reimbursement incentives for remote patient monitoring create entry points for connected ambulatory pumps in homecare transitions. PMDA consultation procedures for software-as-medical-device classifications add notified body scrutiny layers. The Kanto region around Tokyo concentrates hospital procurement authority for high-acuity devices.
China
NMPA streamlined review pathways for innovative medical devices attract multinational localization investments despite import substitution policies. Domestic manufacturers capture mid-tier hospital segments through price-competitive volumetric systems. The Yangtze River Delta manufacturing belt supplies precision motors and microcontroller assemblies to global pump assemblers.
United Kingdom
NHS long-term plan targets for reduced hospital length of stay expand ambulatory pump procurement for chemotherapy and pain management protocols. MHRA post-Brexit regulatory autonomy creates divergence risk from EU MDR alignment timelines. London and the Southeast corridor concentrate private hospital demand for premium anesthesia delivery systems.
Smart Infusion Pump Market Competitive Environment
Strategic partnerships dominate the current landscape as vendors seek to unbundle hardware from software subscriptions and secure group purchasing organization access. The vendor base concentrates among diversified medical technology conglomerates with hospital supply chain integration capabilities, mid-cap specialists with drug library differentiation, and emerging connectivity-focused entrants. Three archetypes prevail: scale-driven full-line suppliers, software-centric platform builders, and regional manufacturing specialists. M&A activity and technology licensing arrangements represent the primary competitive vectors for capability acquisition.
Within the diversified conglomerate tier, ICU Medical Inc, Baxter International Inc, and Fresenius Kabi AG exemplify scale-driven positioning through integrated hardware-disposable offerings and long-term hospital supply agreements. These US and German entities anchor procurement relationships across acute care networks. B Braun Melsungen AG and Terumo Corporation occupy positions within the European and Japanese specialist fabricator categories, representing manufacturing depth in precision delivery mechanisms.
| Leading Market Players |
|---|
| ICU Medical Inc |
| Medtronic plc |
| Becton Dickinson and Company |
| Mindray Medical International Limited |
| Terumo Corporation |
| Baxter International Inc |
| B Braun Melsungen AG |
| Q-Core Medical |
| Fresenius Kabi AG |
| Others |
Value Chain & Pricing Dynamics
Backward integration into precision motor and microcontroller production anchors supply security for pump manufacturers while simultaneously defending margin pools against semiconductor cost volatility. This captive sourcing strategy concentrates among diversified conglomerates with German and Japanese industrial footprints, where long-term supply agreements bundle hardware with disposable sets to lock in pricing power across hospital procurement cycles.
Pricing Analysis
Distributor margins for volumetric systems compress under group purchasing organization consolidation, while software subscription tiers generate recurring revenue insulated from hardware price erosion. Three-tier pricing structure across premium connectivity-enabled, standard wireless-capable, and economy non-connected levels reflects FDA 510(k) certification burden and drug library sophistication. Pricing pressure stems from IDN procurement centralization demanding unbundled software contracts. Homecare segments exhibit highest price sensitivity due to reimbursement rate constraints, whereas academic medical centers absorb premium tiers for closed-loop anesthesia configurations.
Supply Chain Analysis
Microcontroller supply rests on Taiwanese and South Korean foundry capacity, with precision motor assemblies drawing from German and Japanese industrial clusters. Cassette-based delivery mechanisms depend on medical-grade polymer feedstock from US and European specialty chemical producers. Single-source vulnerability concentrates in advanced sensor modules for closed-loop systems. Distribution runs through hospital supply chain integrators and GPO-contracted channels, with direct-to-IDN relationships displacing traditional distributor tiers for high-volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between FDA 510(k) streamlined pathways and EU MDR extended certification timelines creates geographic cost differentials for manufacturers relocating final assembly and software development operations.
For Market Incumbents: Extend drug library specialization into pediatric weight-based dosing algorithms and neonatal intensive care configurations to defend against emerging connectivity-focused entrants. Deepen hospital supply agreement bundling with disposable set volume commitments to maintain channel control amid IDN procurement unbundling trends. Prioritize firmware security talent acquisition to accelerate patch deployment for legacy installed bases facing cybersecurity vulnerability disclosures. For New Entrants and Emerging Players: The premium-to-economy price-point gap in ambulatory pump connectivity features creates white-space entry for mid-tier wireless-enabled systems targeting Japan's METI-reimbursed homecare transitions. Target Germany's clinic segment for mid-range volumetric systems with simplified dose-error reduction software, bypassing tertiary hospital incumbent lock-in. Pursue software-as-medical-device regulatory pathways to monetize quality analytics subscriptions without full hardware certification burden. For Investors and Strategic Acquirers: Roll-up economics work for regional connectivity specialists because EU MDR certification bottlenecks and FDA cybersecurity mandates favor scaled postmarket surveillance infrastructure over fragmented compliance costs. Five-to-ten year viability hinges on platform consolidation around IEEE 11073 and HL7 FHIR interoperability standards. Watch FDA guidance convergence on software-as-medical-device classifications as inflection signal for valuation repricing of pure-play connectivity vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Drug Library Specialization | Pediatric dosing algorithms capture underserved NICU configuration demand with premium pricing. |
| Wireless Protocol Integration | IEEE 11073 and HL7 FHIR enable data monetization through quality analytics subscriptions. |
| CE Marking Pathway | EU MDR clinical evidence standards extend timelines but create regulatory moats for compliant entrants. |
| Hospital System Partnership | Long-term supply agreements bundle pumps with disposables to defend against procurement unbundling. |
| Software Companion Development | Patient-facing mobile interfaces support remote adherence tracking in METI-reimbursed homecare settings. |
Study Parameters
Coverage spans the United States, Germany, Japan, China, and the United Kingdom, with primary inputs from each market cluster combining interviews with hospital procurement committee members, biomedical engineering directors, GPO contracts managers, and regulatory affairs specialists with secondary validation against FDA 510(k) filings, EMA MDR submission databases, hospital procurement records, and CMS reimbursement schedules. Bottom-up pump shipment estimates triangulate with top-down healthcare capital expenditure projections across acute and post-acute settings.
Rate-of-change decomposition separates replacement cycle compression from net new installation demand across the projection horizon, modeling volumetric, ambulatory, syringe, and elastomeric pump segments alongside software integration, wireless communication, and closed-loop technology tiers. CAGRs derive from hospital bed expansion forecasts, surgical volume projections, and homecare reimbursement incentive trajectories, with sensitivity analysis around semiconductor supply recovery timelines and EU MDR certification duration assumptions.
Caveats apply where FDA cybersecurity guidance evolution or EMA vigilance reporting requirement tightening could materially shift the outlook for connectivity-enabled pump adoption curves. A small set of triggers—including PMDA software-as-medical-device reclassification, NMPA innovative device pathway expansion, and MHRA-EU MDR divergence—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Organ-On-A-Chip Systems Market
Medical Devices
Global Blood Warmer Devices Market
Medical Devices
Dosing Units Market
Medical Devices
Implantable Pump Catheter Market
Medical Devices
Tinnitus Maskers Market
Medical Devices
Enteral Feeding Devices Market
Medical Devices
Capnography Devices Market
Medical Devices
Unilateral Biportal Endoscopy Market
Medical Devices
Surgical Devices Market
Medical Devices
Hearing Loop Market
Medical Devices
Digital Phoropter Market
Medical Devices
North America General Surgical Devices Market
Medical Devices
Infant Radiant Warmer Market
Medical Devices
Global Centesis Catheters Market
Medical Devices
Cyberknife Market
Medical Devices
North America Organ-On-Chip Market