
 Venous Procedure Devices Market | 2026-2036
Venous Procedure Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Venous Procedure Devices Market Intelligence
Hospital procurement consolidation is realigning how venous device vendors secure long-term contracts. Abbott Laboratories leverages its integrated vascular portfolio to compete for multi-year supply agreements with consolidated health systems. Medtronic anchors its position through deep catheter manufacturing scale and cath lab relationships. Boston Scientific differentiates via specialized guidewire and filter technologies that address complex deep vein interventions.
Venous procedure devices encompass catheters, stents, guidewires, and filters engineered from biocompatible polymers and nitinol alloys, designed to restore or maintain venous patency through minimally invasive access. Catheters and stents dominate current revenue pools due to repeat utilization in thrombectomy and angioplasty workflows, while radiofrequency and laser technologies represent the fastest-expanding technology segment as outpatient clinics shift away from surgical vein stripping. Guidewires and filters occupy narrower but higher-margin niches where precision navigation and embolic protection command premium positioning.
FDA 510(k) clearance pathways and the EU MDR framework shape product development timelines and clinical evidence requirements for manufacturers seeking market access. The EPA and OSHA additionally influence sterilization process standards and workplace exposure limits in device production facilities. Stakeholders must monitor how evolving reimbursement codes for office-based venous procedures reshape site-of-care economics and technology procurement priorities.
Market Dynamics
Outpatient surgical centers are capturing venous procedures previously performed in hospitals, forcing device vendors to reconfigure pricing and service models around lower-acuity sites that prioritize disposable catheter systems and radiofrequency platforms over capital-intensive equipment.
Growth Catalysts
- EU MDR conformity requirements:Stricter clinical evidence mandates for stent and catheter platforms are accelerating consolidation among manufacturers with robust quality management systems, filtering out smaller competitors and expanding addressable share for compliant suppliers.
- Radiofrequency ablation technology:Thermal closure systems for varicose vein treatment are displacing surgical stripping across ambulatory surgery centers, creating repeat revenue streams from single-use catheter consumables.
- Germany's hospital procurement alliances:Bundled purchasing agreements for vascular devices are concentrating demand volume, enabling preferred vendors to secure multi-year supply commitments with guaranteed minimum order thresholds.
Market Restraints
- Nitinol alloy supply concentration:Shape-memory wire production concentrates among a limited set of specialty metal processors, exposing stent and guidewire manufacturers to input cost volatility and allocation risk during supply disruptions.
- FDA 510(k) evidentiary burden:Substantial equivalence demonstrations for modified catheter designs require expanded predicate comparisons, extending clearance timelines and deferring revenue recognition for iterative product improvements.
- Pharmacological thrombolysis alternatives:Systemic and catheter-directed drug protocols for deep vein thrombosis compete with mechanical thrombectomy devices, capping penetration in certain patient risk strata where conservative management prevails.
Strategic Opportunities
- India's underserved peripheral venous disease population:Diagnostic infrastructure expansion in tier-2 and tier-3 cities under CDSCO oversight creates first-mover positioning for catheter platforms adapted to cost-sensitive hospital procurement budgets.
- Japan's aging demographic and METI reimbursement reforms:Expanded national health insurance coverage for minimally invasive venous interventions is redirecting patient volume from conventional surgery toward outpatient thermal ablation procedures.
- Integrated disposable-filter-and-catheter kits:Procedure-specific bundled configurations reduce operating room setup complexity and inventory carrying costs, aligning with value-analysis committee preferences in consolidated US health systems.
Industry Challenges
- Interventional radiologist training pipeline constraints:Specialized credentialing requirements for complex venous access procedures limit procedure volume growth in markets where fellowship positions fail to match demand expansion.
- EU MDR notified body capacity bottlenecks:Extended technical documentation review queues delay CE marking renewals for legacy stent and filter products, forcing commercial teams to manage certificate gap risks across European markets.
- Legacy electronic health record integration:Proprietary data formats in hospital information systems complicate deployment of connected catheter technologies designed to capture and transmit procedural metrics for quality registries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Venous Procedure Devices Market |
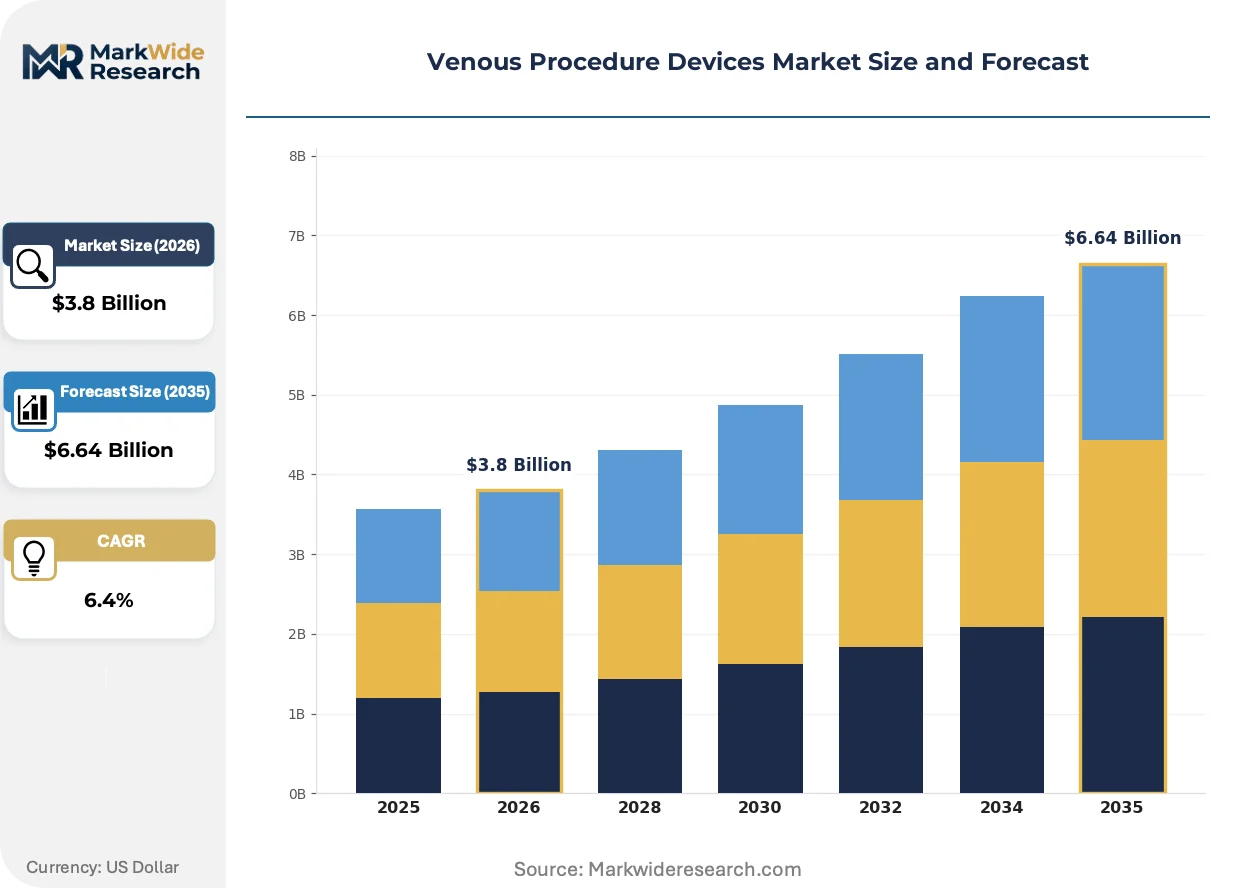
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Catheters, Stents, Guidewires, Filters Technology: Ultrasound, Laser, Radiofrequency, Electrode End User: Clinics, Hospitals, Surgical Centers, Diagnostic Labs Application: Thrombectomy, Angioplasty, Varicose Vein Treatment, Venous Access |
| Companies Covered | Teleflex Incorporated, Abbott Laboratories, Medtronic, LeMaitre Vascular, Terumo Corporation, Boston Scientific Corporation, Merit Medical Systems, B. Braun SE, AngioDynamics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Venous Procedure Devices Market Strategic Shifts & Innovations
Device architecture is converging around disposable-centric platforms that minimize capital expenditure for outpatient operators while maximizing per-procedure revenue capture through proprietary consumable ecosystems.
Mechanical thrombectomy catheter systems are consolidating market position in deep vein intervention workflows. These aspiration and maceration platforms enable single-session clot removal without lytic pharmacotherapy. Hospital-based interventional suites are adopting them at accelerated replacement cycles for legacy wire-based approaches. The technology is consolidating vendor relationships around integrated catheter-and-pump configurations that lock in recurring disposable purchases.
The EU Medical Device Regulation's post-market surveillance requirements are reshaping clinical evidence obligations for nitinol stent manufacturers. Annual safety update reports and periodic safety update reports now mandate active registry participation. Deep vein stent portfolios face the most pronounced compliance burden, with manufacturers expanding dedicated clinical affairs teams to manage notified body interactions and vigilance reporting across member states.
Health system value-analysis committees are compressing vendor evaluation cycles and unbundling historical service contracts from device pricing. Purchasing departments now separate technical training, field clinical support, and warranty provisions into line-item negotiations. This behavioral shift is most visible across US integrated delivery networks, where procurement standardization initiatives prioritize interchangeable catheter platforms over proprietary ecosystem lock-in.
Venous Procedure Devices Market Segmentation
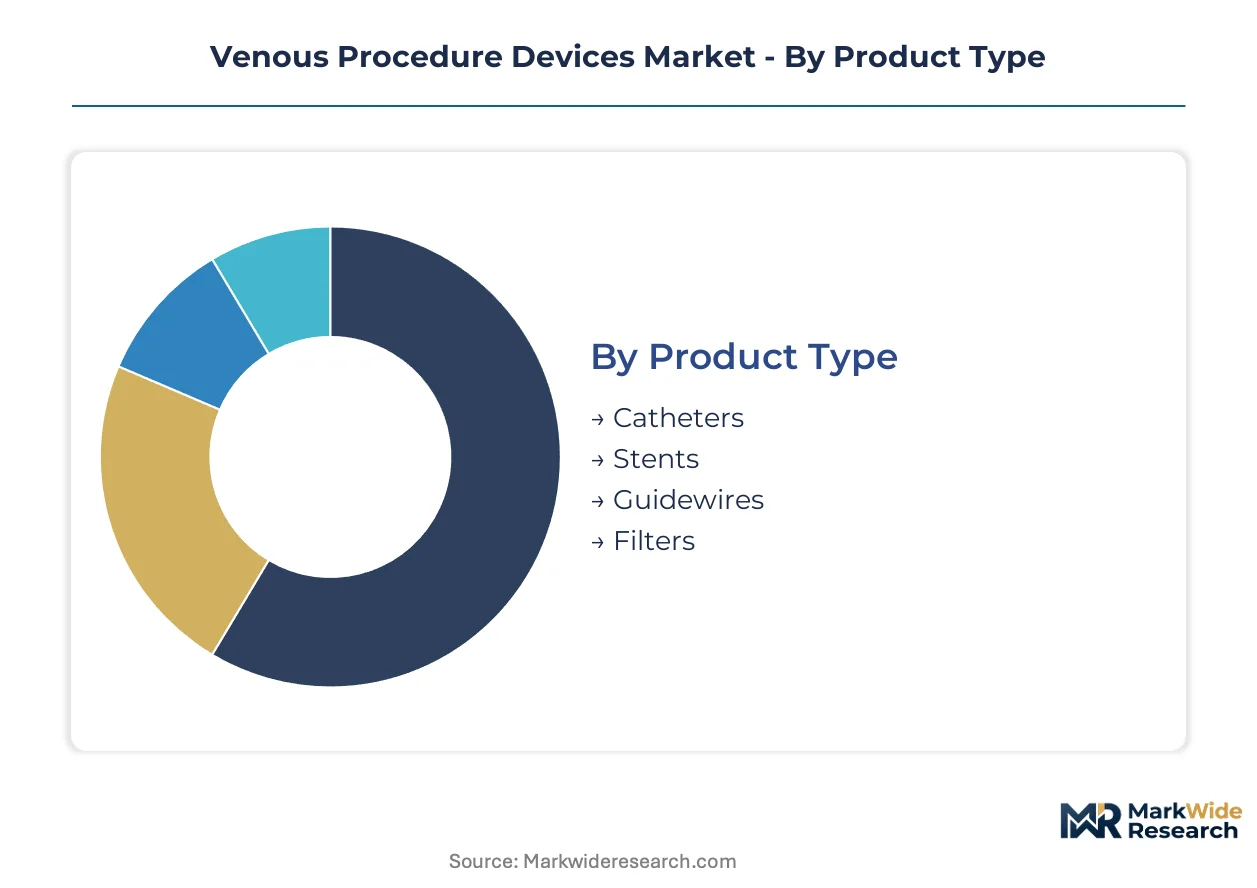
Venous procedure devices fragment across four dimensions that determine procurement patterns, reimbursement pathways, and vendor commercial strategy. Product type and technology choices dictate capital versus consumable economics, while end-user site and application define clinical workflow integration requirements.
Product Type:
Volume concentration sits with catheter and stent platforms deployed in high-frequency thrombectomy and angioplasty workflows. Premium positioning concentrates in guidewire and filter segments where precision engineering commands differentiated pricing.
- Catheters:Biocompatible polymer tubes engineered for vascular access, thrombus aspiration, and therapeutic delivery dominate procedure volumes across hospital interventional suites. Demand concentrates in mechanical thrombectomy configurations where single-use disposables generate recurring revenue streams from integrated pump systems.
- Stents:Nitinol alloy scaffolds providing radial force to maintain venous patency after angioplasty capture substantial value in chronic venous obstruction cases. Deployment concentrates in deep vein interventions where EU MDR post-market surveillance requirements now mandate active registry participation and annual safety reporting.
- Guidewires:Shape-memory nitinol core wires with hydrophilic coatings enable navigation through tortuous venous anatomy.
- Filters:Percutaneous devices for embolic protection during thrombectomy occupy narrow but defensible premium niches.
Mature deployment sits with catheters. Newer deployment is concentrated in stents facing intensified regulatory evidence requirements.
Technology:
Cost tiering separates capital-intensive laser platforms from disposable-centric radiofrequency systems preferred by outpatient operators managing constrained equipment budgets.
- Radiofrequency:Thermal ablation catheters delivering controlled heat to collapse varicose vein walls displace surgical stripping across US ambulatory surgery centers. Demand expansion tracks outpatient procedural volume migration from hospital-based operating rooms.
- Laser:Endovenous laser fiber systems achieving vein closure through photothermal energy conversion maintain position in premium clinic segments. Deployment concentrates in Germany's hospital procurement alliances where bundled purchasing agreements favor established thermal platform vendors.
- Ultrasound:Imaging guidance systems enabling real-time visualization during venous access and ablation procedures.
- Electrode:Bipolar and monopolar configurations for specialized coagulation applications in complex venous interventions.
Radiofrequency platforms are gaining share fastest in outpatient migration. Laser systems defend position in premium reimbursement environments.
End User:
Customer type determines service model requirements, with hospitals demanding comprehensive field support and surgical centers prioritizing streamlined disposable logistics.
- Surgical Centers:Ambulatory facilities performing office-based venous procedures drive radiofrequency catheter consumption through high turnover of single-use thermal devices. Procurement prioritizes disposable-centric platforms minimizing capital expenditure and inventory complexity.
- Hospitals:Acute care institutions with interventional radiology suites manage mixed device portfolios spanning thrombectomy, stenting, and complex access procedures. Demand concentrates in integrated catheter-and-pump configurations that lock in recurring disposable purchases from consolidated vendor relationships.
- Clinics:Specialized vein treatment centers and dermatology practices performing cosmetic and medical varicose vein interventions.
- Diagnostic Labs:Vascular imaging facilities supporting procedural planning and post-intervention surveillance workflows.
Volume leadership sits with hospitals. Fastest expansion is concentrated in surgical centers capturing procedure migration from acute care settings.
Application:
Margin structure varies sharply across applications, with thrombectomy commanding premium device pricing and varicose vein treatment driving high-volume consumable throughput.
- Thrombectomy:Mechanical clot removal procedures utilizing aspiration catheters and maceration platforms enable single-session deep vein thrombosis intervention without pharmacologic lysis. Hospital adoption accelerates as interventional suites replace legacy wire-based approaches with integrated catheter systems.
- Varicose Vein Treatment:Thermal ablation and sclerotherapy procedures for superficial venous insufficiency generate repeat catheter consumption in outpatient settings. Procedure volume expansion tracks patient preference for minimally invasive alternatives to surgical stripping.
- Angioplasty:Balloon dilation with adjunctive stent placement for chronic venous obstruction and post-thrombotic syndrome.
- Venous Access:Central line placement and dialysis catheter insertion supporting hemodialysis and long-term infusion therapy.
Revenue concentration sits with thrombectomy. Steepest volume trajectory is concentrated in varicose vein treatment as ambulatory sites expand thermal ablation capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement consolidation and outpatient procedure migration concentrate demand in the United States, Germany, and Japan, with emerging volume expansion in India and Brazil reshaping vendor prioritization.
United States
Ambulatory surgery centers capture varicose vein procedures from hospital operating rooms, driving radiofrequency catheter consumption. FDA 510(k) clearance pathways shape product development timelines for modified catheter designs. The Southeast region, particularly Florida and Georgia, hosts dense networks of vein treatment clinics deploying thermal ablation systems.
Germany
Hospital procurement alliances concentrate vascular device purchasing power among consolidated health systems. EU MDR conformity requirements tighten clinical evidence mandates for stent and catheter platforms. The Baden-Württemberg cluster anchors manufacturing scale for nitinol alloy processing and precision guidewire production.
Japan
Aging demographics expand the addressable patient population for minimally invasive venous interventions. METI reimbursement reforms redirect national health insurance coverage toward outpatient thermal ablation procedures. The Kansai region around Osaka maintains specialized interventional radiology training capacity for complex deep vein access techniques.
India
Peripheral venous disease remains underdiagnosed in tier-2 and tier-3 cities, creating first-mover positioning for cost-adapted catheter platforms. CDSCO oversight governs medical device registration and quality standards. Maharashtra's Mumbai-Pune corridor concentrates private hospital chains expanding interventional radiology suites.
Brazil
Private health insurance expansion supports adoption of minimally invasive alternatives to surgical vein stripping. ANVISA regulates medical device importation and manufacturing licensing. São Paulo's metropolitan area hosts the highest density of vascular surgery practices and catheterization laboratory infrastructure.
Venous Procedure Devices Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue disposable-centric platforms and integrated procedure kits. The vendor base stratifies across three tiers: diversified cardiovascular conglomerates with integrated vascular portfolios, mid-scale specialists concentrating on guidewire or filter niches, and regional fabricators serving cost-sensitive procurement channels. Dominant competitive moves include backward integration into nitinol alloy supply relationships and strategic partnerships with outpatient surgical center networks.
Among diversified cardiovascular conglomerates, Abbott Laboratories, Medtronic, and Boston Scientific occupy positions that exemplify distinct competitive archetypes. Abbott leverages integrated vascular portfolio breadth to secure multi-year supply agreements with consolidated health systems. Medtronic anchors manufacturing scale in catheter platforms and cath lab relationships. Boston Scientific represents the precision-specialist vector through differentiated guidewire and filter technologies for complex deep vein interventions.
| Leading Market Players |
|---|
| Teleflex Incorporated |
| Abbott Laboratories |
| Medtronic |
| LeMaitre Vascular |
| Terumo Corporation |
| Boston Scientific Corporation |
| Merit Medical Systems |
| B. Braun SE |
| AngioDynamics |
| Others |
Cost & Logistics Intelligence
Catheter-stent tier divergence against guidewire-filter premium positioning manifests in divergent supply chain configurations across the United States and Germany. Radiofrequency consumables command volume-driven contract pricing through GPO negotiations, while precision nitinol components anchor specialized foundry relationships in Baden-Württemberg.
Pricing Analysis
Volume concentration in catheters generates thin margins offset by pump-system lock-in, while filter and guidewire segments sustain premium positioning through precision engineering differentiation. Price differentiation rests on EU MDR certification tier and cath lab integration depth, with outpatient surgical centers exhibiting highest sensitivity to per-procedure disposable costs. Pricing pressure intensifies as hospital procurement alliances unbundle service contracts from device pricing, compressing vendor evaluation cycles.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and Japan coordinate hub-and-spoke deployment of sterile catheter inventories to ambulatory surgery centers. Nitinol alloy supply concentrates in Germany and Japan, with biocompatible polymer feedstocks sourced from United States and European chemical processors. Single-source vulnerability in shape-memory wire production exposes stent manufacturers to allocation risk during specialty metal disruptions. Distribution runs through consolidated health system warehouses and third-party logistics partners serving outpatient clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The venous procedure devices market sits in a technology-transition phase as radiofrequency thermal ablation displaces surgical vein stripping across outpatient settings, reshaping vendor economics around disposable-centric platforms.
For Market Incumbents: Anticipate margin compression from unbundled procurement contracts by deepening backward integration into nitinol alloy supply relationships and expanding dedicated clinical affairs teams to manage EU MDR post-market surveillance obligations for deep vein stent portfolios. For New Entrants and Emerging Players: Direct-to-outpatient-clinic digital channels offer lowest-friction market entry, targeting India's tier-2 and tier-3 cities with cost-adapted catheter platforms and bundled disposable-filter-and-catheter kits aligned with CDSCO quality standards. For Investors and Strategic Acquirers: Re-rating potential sits with disposable-centric platform specialists given outpatient procedure migration catalysts, with long-term viability hinging on regulatory compliance infrastructure; monitor EU MDR notified body capacity as inflection indicator for CE marking renewal timelines.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Compliance Investment | Accelerates market share capture as notified body bottlenecks filter non-compliant competitors from European stent markets. |
| Outpatient Surgical Center Partnership | Locks in recurring radiofrequency catheter revenue through exclusive disposable supply agreements with high-turnover clinics. |
| Nitinol Alloy Supply Integration | Reduces input cost volatility exposure for guidewire and stent manufacturers dependent on German and Japanese specialty metal processors. |
| Integrated Procedure Kit Development | Aligns with value-analysis committee preferences in consolidated US health systems seeking reduced OR setup complexity. |
| India Market Entry Strategy | Captures first-mover positioning in underdiagnosed peripheral venous disease populations across Maharashtra's hospital chains. |
Research Approach
Multi-period observation of catheter utilization rates, outpatient procedural volume migration, and regulatory submission timelines anchored the trend analysis, supplemented by interviews with interventional radiologists, hospital purchasing committee chairs, GPO contracts managers, and biomedical engineers. Secondary validation drew from FDA 510(k) clearance databases, EU MDR notified body registers, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up procedure volume modeling and top-down vendor revenue triangulation ensured cross-verification.
Input-output matrix framing connected segmentation dimensions—product type, technology platform, end-user site, and clinical application—to value and volume projections across the analysis window. CAGRs were derived from fitted growth curves applied to historical utilization trajectories, with explicit modeling of radiofrequency adoption rates and thrombectomy device replacement cycles as industry-specific forecast inputs.
Inputs from FDA submission tracking and EU MDR certificate renewal records were available through the study window; gaps in private outpatient clinic utilization data introduce uncertainty bands around ambulatory surgery center volume forecasts. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Contraceptive Rings Market
Medical Devices
Pathology Devices Market
Medical Devices
Saliva Collection Devices Market
Medical Devices
Asia-Pacific Single-Use Medical Device Reprocessing Market
Medical Devices
LASIK Eye Surgery Devices Market
Medical Devices
Double-Lumen Biliary Catheters Market
Medical Devices
Neurovascular Access Catheters Market
Medical Devices
Global Vaginal Sling Market
Medical Devices
Concentrator O2 Devices Market
Medical Devices
Non-Invasive Pulse Oximeter Market
Medical Devices
Global Automated Suturing Devices Market
Medical Devices
Acute External Ventricular Drain Market
Medical Devices
Global Vascular Embolization Devices Market
Medical Devices
Dental Implants and Prosthetics Contract Manufacturing Market
Medical Devices
Global Photomedicine Market
Medical Devices
Peripheral Micro Catheters Market