
 Tracheostomy Securement Tapes Market | 2026-2036
Tracheostomy Securement Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Tracheostomy Securement Tapes Market Analytics
Buyer concentration across long-term care facilities is recalibrating procurement patterns for tracheostomy securement tapes as hospital-at-home programs expand. Medtronic leverages its critical care portfolio to sustain institutional contracts across acute care networks. Smiths Group plc anchors European supply relationships through its airway management division. 3M Company differentiates via adhesive science leadership and direct clinician engagement programs.
Tracheostomy securement tapes are specialized adhesive devices engineered to stabilize tracheostomy tubes against patient movement, typically incorporating hypoallergenic acrylic or silicone adhesives with tensile strengths calibrated to prevent tube dislodgement without skin trauma. These tapes function primarily to reduce accidental decannulation events in ventilator-dependent patients across acute, sub-acute, and domiciliary settings. Silicone tapes command premium positioning due to gentler removal cycles suited to fragile geriatric skin, while foam tapes occupy high-volume acute care channels where moisture management governs selection. Hospital application segments retain the largest value pool though home care delivery mode is expanding fastest as reimbursement shifts favor outpatient respiratory management.
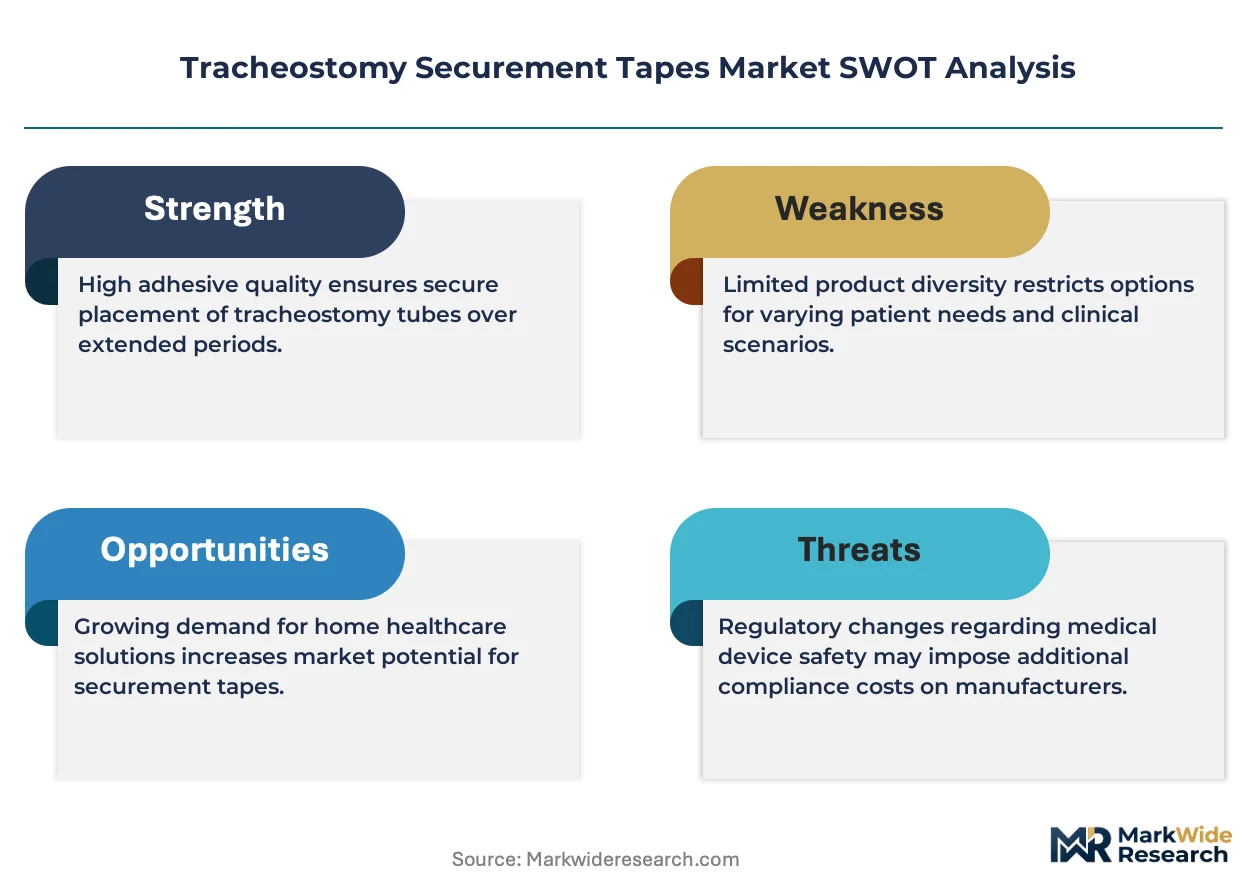
FDA biocompatibility standards under ISO 10993 govern adhesive composition and cytotoxicity testing for all tracheostomy securement tapes distributed in the United States, while CE marking under the EU MDR imposes equivalent clinical evaluation requirements for European market access. These frameworks elevate barriers for unvalidated material substitutions and compel documented skin-safety profiles. Stakeholders must monitor evolving home care reimbursement codes and adhesive material qualification timelines to align portfolio investments with shifting site-of-care economics.
Market Dynamics
Hospital-at-home reimbursement expansion is restructuring demand geography for tracheostomy securement tapes, pulling procurement decisions from centralized hospital supply chains toward distributed home health networks and patient-directed purchasing.
Growth Catalysts
- ISO 10993 biocompatibility frameworks:FDA adherence to these standards elevates material qualification barriers, filtering out low-grade adhesive suppliers and rewarding documented skin-safety profiles.
- Silicone adhesive chemistry:Gentler removal properties suited to geriatric skin fragility expand addressable patient populations in long-term ventilation management.
- United States respiratory disease burden:Chronic obstructive pulmonary disease prevalence and aging demographics sustain institutional and domiciliary consumption volumes.
Market Restraints
- Medical-grade silicone feedstock volatility:Petrochemical-linked raw material costs compress margin structures for tape manufacturers without backward integration.
- Adhesive validation timelines:FDA cytotoxicity testing protocols extend product development cycles and defer revenue recognition for formulation innovations.
- Tube-securing alternative devices:Foam-based tube holders and custom-fit neck collars capture price-sensitive acute care segments.
Strategic Opportunities
- Home care reimbursement codes:Medicare and Medicaid outpatient respiratory management expansions create direct-to-patient distribution channels outside hospital purchasing.
- EU MDR clinical evaluation pathways:Harmonized European market access standards enable portfolio scale across Germany, France, and Benelux through single conformity assessments.
- Antimicrobial adhesive integration:Convergence of infection control protocols with securement function addresses ventilator-associated pneumonia prevention priorities.
Industry Challenges
- Dermal toxicology expertise scarcity:Qualified adhesive biocompatibility assessors command premium compensation, constraining R&D throughput.
- Legacy hospital supply chain integration:Home health procurement platforms require ERP reconfiguration and logistics partnerships distinct from institutional distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tracheostomy Securement Tapes Market |
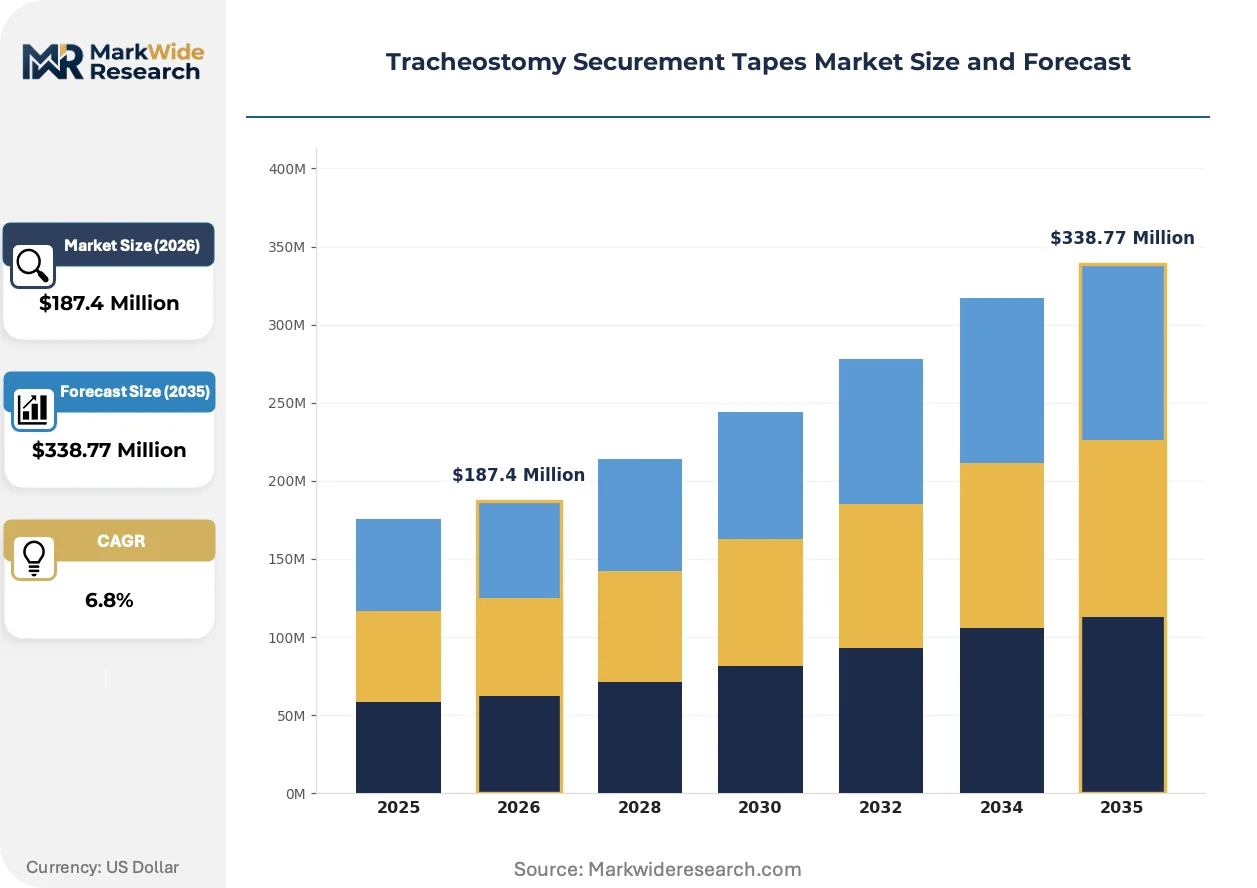
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Tapes, Foam Tapes, Polyester Tapes, Cotton Tapes Application: Hospitals, Home Care, Long-Term Care Facilities, Emergency Services End User: Healthcare Professionals, Patients, Caregivers, Medical Facilities Delivery Mode: Direct Sales, Online Sales, Distributors, Retail |
| Companies Covered | Medtronic, Smiths Group plc, 3M Company, Teleflex Incorporated, Avery Dennison Corporation, Mölnlycke Health Care AB, DeRoyal Industries Inc, Dale Medical Products, Medline Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tracheostomy Securement Tapes Market Evolving Landscape
Material science convergence with reimbursement geography is compressing product development cycles and redefining competitive differentiation around skin-interface performance rather than mechanical fixation alone.
Silicone-based securement tapes are consolidating market preference among geriatric and pediatric populations where epidermal integrity preservation governs clinical selection. Long-term acute care facilities and skilled nursing operators prioritize these formulations despite unit cost premiums. The technology is consolidating supplier positioning around documented gentler removal cycles and reduced medical adhesive-related skin injury incidence.
EU MDR clinical evaluation requirements are tightening post-market surveillance obligations for adhesive medical devices distributed in European Economic Area markets. Manufacturers must maintain systematic literature reviews and periodic safety update reports beyond initial CE marking. German and French notified bodies are enforcing these provisions most stringently, compressing timelines for legacy product recertification.
Home health agency procurement autonomy is displacing hospital supply chain intermediaries as site-of-care migration accelerates. Direct purchasing relationships between tape manufacturers and regional home care networks are replacing group purchasing organization contracts. This pattern concentrates in United States markets where Medicare Advantage plans and hospital-at-home pilots expand fastest.
Tracheostomy Securement Tapes Market Segmentation
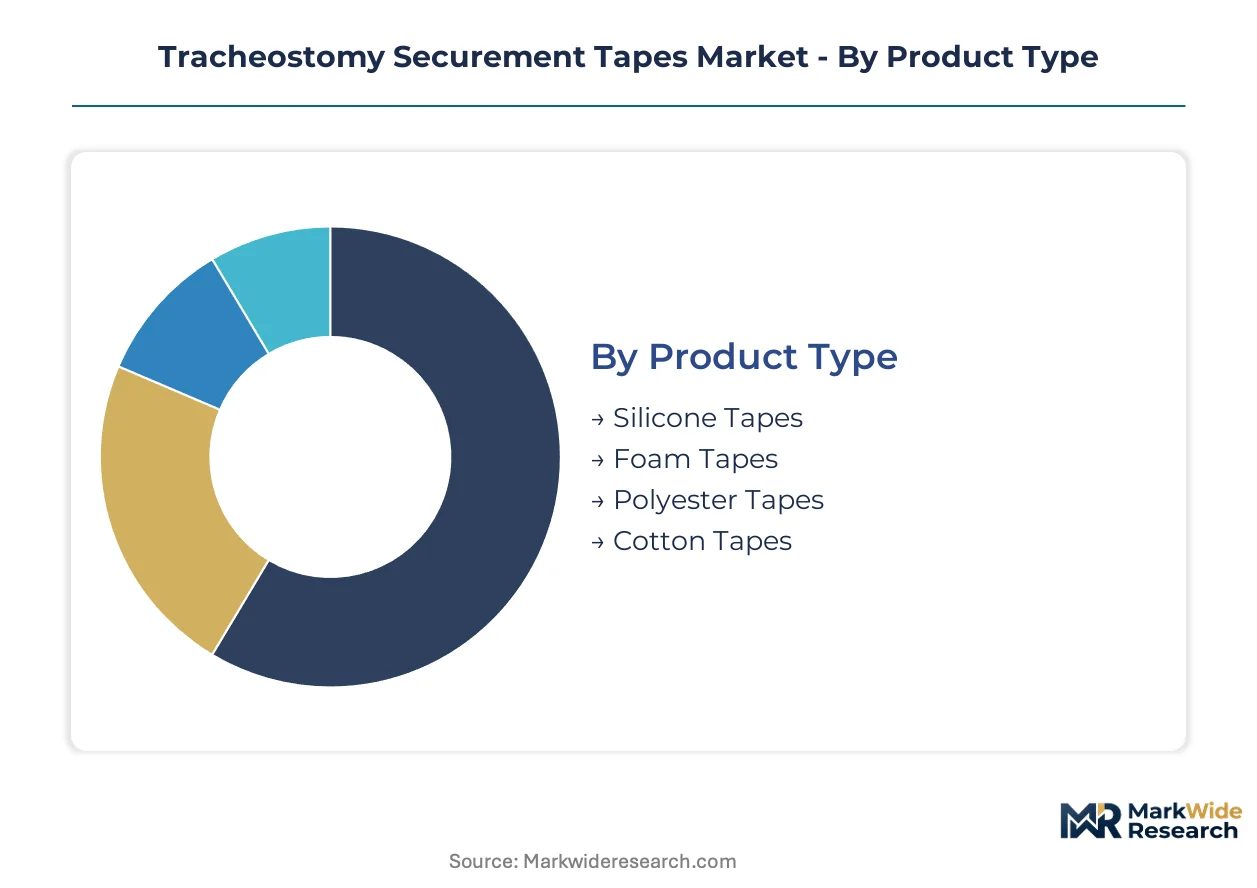
Tracheostomy securement tape segmentation reflects divergent regulatory burdens and site-of-care economics. Product chemistry determines FDA biocompatibility testing intensity, while application setting governs reimbursement pathways and procurement authority.
Product Type:
FDA ISO 10993 cytotoxicity testing requirements escalate with adhesive complexity, filtering supplier participation by formulation capability. Silicone formulations face extended validation timelines under skin-sensitivity protocols.
- Silicone Tapes:Medical-grade silicone adhesives deliver gentle removal cycles with reduced epidermal trauma. Long-term acute care facilities in the United States prioritize these formulations for geriatric ventilator populations despite unit cost premiums, driven by medical adhesive-related skin injury prevention protocols.
- Foam Tapes:Multi-layer polyurethane constructions manage moisture at the skin-tube interface. Hospital intensive care units concentrate procurement volumes here, constrained by shorter wear duration requirements and budget pressure from centralized supply chains.
- Polyester Tapes:Synthetic woven backings with acrylic adhesive systems balance tensile strength against cost. Standard institutional contracts specify these for general respiratory wards.
- Cotton Tapes:Natural fiber substrates with hypoallergenic coatings serve cost-sensitive markets and latex-allergy protocols. Limited to emergent or developing market applications.
Leading the category by volume: Foam Tapes. Growing fastest: Silicone Tapes.
Application:
Site-of-care migration is restructuring procurement authority and reimbursement eligibility across institutional and domiciliary settings.
- Hospitals:Acute care networks retain centralized purchasing power through group purchasing organizations. Volume concentration here reflects ventilator-dependent surgical and trauma populations.
- Home Care:Medicare Advantage and hospital-at-home pilots are expanding direct-to-patient distribution. Skilled nursing visits and family caregiver training programs drive tape consumption outside institutional settings.
- Long-Term Care Facilities:Skilled nursing operators balance skin integrity protocols against per-diem reimbursement constraints. Silicone preference is strongest in this channel.
- Emergency Services:Pre-hospital airway management requires rapid-apply formats with universal sizing. Ambulance services and emergency medical technician field kits specify compact packaging.
Dominant by procurement value: Hospitals. Expanding most quickly: Home Care.
End User:
Purchasing authority fragmentation is intensifying between clinical decision-makers and patient-directed acquisition.
- Healthcare Professionals:Respiratory therapists and wound care nurses specify tape chemistry based on epidermal assessment protocols. Institutional credentialing requirements govern selection authority.
- Patients:Domiciliary ventilator users with durable medical equipment coverage increasingly self-procure through direct-ship channels. Reimbursement navigation complexity limits this segment's expansion.
- Caregivers:Family members and home health aides execute application without clinical licensure. Training burden and error risk concentrate demand on pre-cut, color-coded formats.
- Medical Facilities:Supply chain managers negotiate multi-year contracts based on standardized product matrices. Formulary restrictions limit clinician discretion.
Highest decision influence: Healthcare Professionals. Fastest authority shift: Patients.
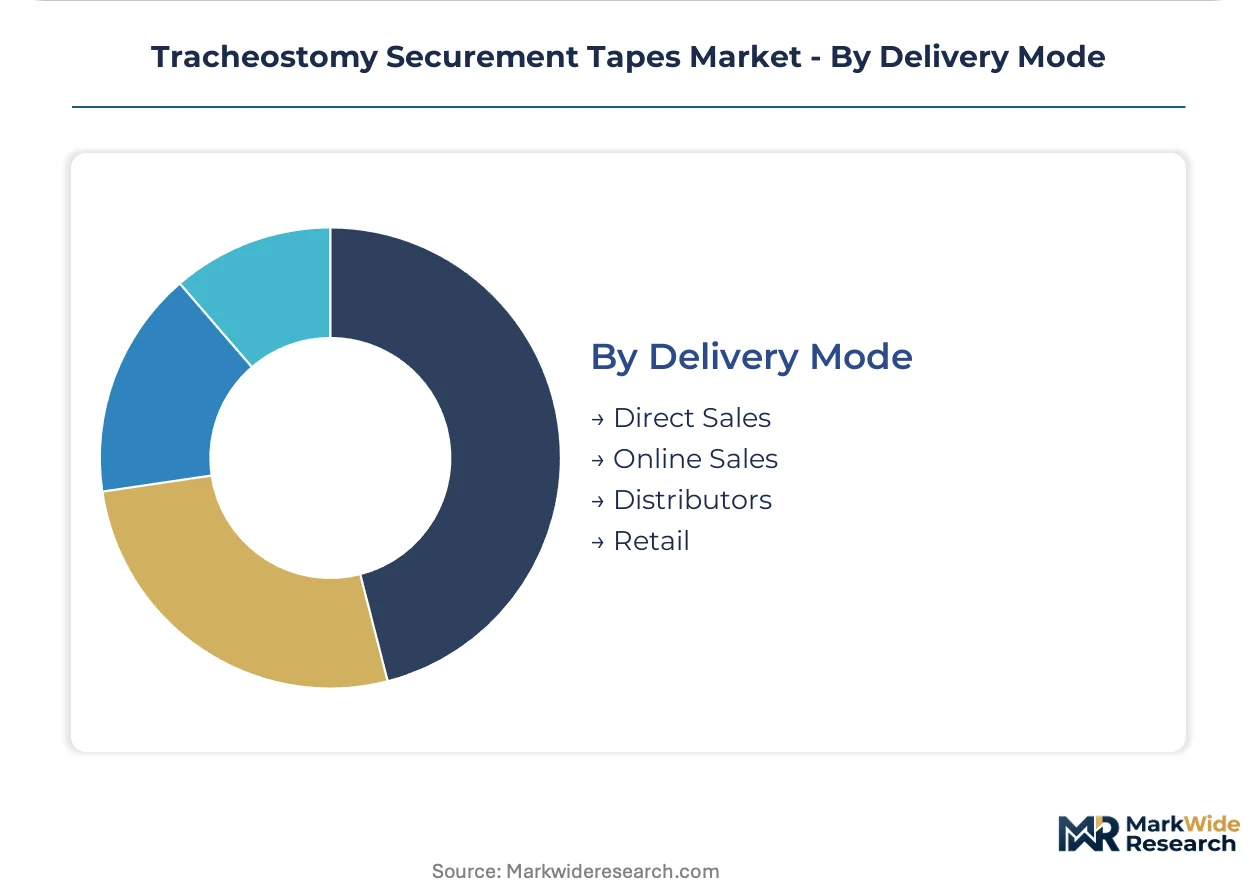
Delivery Mode:
Channel strategy divergence reflects institutional procurement legacy against direct-to-patient infrastructure buildout.
- Direct Sales:Manufacturer field representatives maintain relationships with hospital value analysis committees. Contract renewal cycles align with fiscal year planning.
- Online Sales:E-commerce platforms serve home care patients and small-practice purchasers. Regulatory compliance for medical device listings constrains marketplace participation.
- Distributors:Regional medical-surgical distributors hold inventory positions for same-day hospital fulfillment. Consolidation among distributors is compressing supplier margin structures.
- Retail:Pharmacy and durable medical equipment storefronts serve emergency replenishment and travel needs. Limited SKU depth restricts this channel to basic cotton and polyester formats.
Largest volume channel: Distributors. Steepest expansion trajectory: Online Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical-grade silicone feedstock availability in Germany and the United States anchors manufacturing capacity for tracheostomy securement tapes, with distribution networks radiating from these petrochemical hubs to serve acute care and home care channels worldwide.
United States
Chronic obstructive pulmonary disease prevalence and aging demographics sustain institutional consumption volumes across acute care networks. FDA biocompatibility standards under ISO 10993 govern adhesive composition and cytotoxicity testing for all distributed tapes. Hospital-at-home pilots in Medicare Advantage networks are restructuring procurement geography toward direct-to-patient channels.
Germany
Long-term acute care facilities prioritize silicone formulations for geriatric ventilator populations driven by medical adhesive-related skin injury prevention protocols. EU MDR clinical evaluation requirements impose systematic literature reviews and periodic safety update reports beyond initial CE marking. Notified bodies in Berlin and Munich enforce these provisions most stringently for legacy product recertification.
United Kingdom
Respiratory disease burden and National Health Service cost-containment pressures shape procurement patterns across hospital trusts. MHRA post-Brexit regulatory alignment maintains ISO 10993 adherence while streamlining conformity assessment timelines. London and Greater Manchester health systems concentrate demand for pre-cut, color-coded tape formats suited to caregiver training programs.
Japan
Geriatric skin fragility and long-term ventilation management expand addressable patient populations for gentle removal formulations. PMDA medical device regulations require documented skin-safety profiles and extended validation timelines for silicone adhesive innovations. Osaka-based medical device distributors maintain inventory positions for same-day hospital fulfillment across Kansai region acute care networks.
Australia
Home care delivery mode expansion accelerates as reimbursement shifts favor outpatient respiratory management. TGA medical device standards align with ISO 10993 frameworks while imposing additional post-market surveillance obligations. Sydney and Melbourne health districts concentrate procurement volumes through group purchasing organization contracts.
Tracheostomy Securement Tapes Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent spaces in antimicrobial adhesive integration and direct-to-patient distribution infrastructure. Market structure reflects consolidated institutional contracting alongside fragmented home health procurement autonomy. Three archetypes dominate: critical care portfolio holders leveraging airway management divisions, adhesive science specialists with clinician engagement programs, and regional fabricators serving cost-sensitive acute care segments. Competitive moves concentrate on strategic partnerships with home health networks and portfolio diversification into silicone-based formulations.
Among critical care portfolio holders, Medtronic and Smiths Group plc exemplify institutional contract defense through integrated airway management divisions. 3M Company anchors the adhesive science specialist archetype with documented material qualification capabilities. These three occupy positions across premium and standard tiers, with geographic origins spanning Minneapolis-based, London-headquartered, and St. Paul-rooted operations respectively.
| Leading Market Players |
|---|
| Medtronic |
| Smiths Group plc |
| 3M Company |
| Teleflex Incorporated |
| Avery Dennison Corporation |
| Mölnlycke Health Care AB |
| DeRoyal Industries Inc |
| Dale Medical Products |
| Medline Industries |
| Others |
Value Network & Pricing Analysis
Group purchasing organization concentration across United States acute care networks enforces contract-based long-term offtake pricing with standardized product matrices, compressing supplier margin structures while rewarding documented ISO 10993 certification tiers.
Pricing Analysis
Volume-mass foam tapes occupy high-turn acute care channels at compressed margins, while silicone formulations capture premium positioning through gentler removal cycles. Price differentiation separates medical-grade silicone tiers from standard acrylic adhesives, with FDA biocompatibility validation commanding measurable premiums. Cost compression in foam tape categories is intensifying as hospital supply chains consolidate procurement authority. Long-term acute care facilities demonstrate lowest price sensitivity, prioritizing skin-integrity protocols over unit economics.
Supply Chain Analysis
Specialized adhesive chemists and dermal toxicologists command premium compensation in Germany and the United States, constraining R&D throughput for formulation innovations. Manufacturing capacity draws from petrochemical hubs in these countries, with medical-grade silicone feedstock anchored in German industrial clusters. Single-source vulnerability concentrates in medical-grade silicone suppliers without backward integration. Distribution runs through regional medical-surgical distributors holding same-day inventory positions for hospital fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as EU MDR recertification timelines and FDA validation requirements force undercapitalized regional fabricators toward exit.
For Market Incumbents: To counter home health procurement autonomy displacing institutional contracts, defend positioning through backward integration into medical-grade silicone supply and accelerated CE marking under EU MDR clinical evaluation pathways. Prioritize direct relationships with Medicare Advantage hospital-at-home networks outside traditional GPO channels. For New Entrants and Emerging Players: Family caregivers executing tape application without clinical licensure represent the most penetrable buyer archetype, underserved by current pre-cut, color-coded format availability. Target domiciliary ventilator users with durable medical equipment coverage navigating reimbursement complexity. Pursue direct-to-patient e-commerce infrastructure with regulatory-compliant medical device listings. For Investors and Strategic Acquirers: The window for entry favors adhesive science specialists with documented ISO 10993 portfolios and existing clinician engagement programs. Long-term viability hinges on consolidation of fragmented home health distribution infrastructure. Monitor FDA cytotoxicity testing protocol revisions as inflection indicators for qualification timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Accelerates market access for silicone adhesive innovations against extended validation timelines. |
| CE Marking under EU MDR | Enables portfolio scale across German and French notified body jurisdictions through harmonized assessment. |
| Hospital System Partnership | Secures multi-year formulary positioning within consolidating acute care network supply chains. |
| Reimbursement Strategy Development | Aligns product coding with Medicare outpatient respiratory management expansion trajectories. |
| Antimicrobial Adhesive Integration | Addresses ventilator-associated pneumonia prevention priorities in long-term ventilation protocols. |
Research Methodology
Independent corroboration across respiratory therapists, wound care nurses, hospital purchasing committees, and GPO contracts managers underwrites the qualitative findings, validated against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR notified body documentation. Bottom-up demand modeling triangulates with top-down market sizing across adhesive chemistry tiers.
Rate-of-change decomposition separates volume expansion in home care delivery mode from value migration toward silicone formulations across the projection horizon. Segmentation dimensions span adhesive chemistry, application setting, end-user purchasing authority, and regional regulatory cluster. CAGRs derive from patient population epidemiology, site-of-care reimbursement shifts, and material substitution elasticity calibrated to ISO 10993 validation timelines.
Revisions become necessary when FDA biocompatibility testing protocols extend materially, EU MDR notified body capacity constraints intensify, or medical-grade silicone feedstock volatility disrupts manufacturing economics. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Combat Dressing Market
Medical Supplies
United Kingdom Hospital Supplies Market
Medical Supplies
Latin America Hypodermic Syringes and Needles Market
Medical Supplies
Laparoscopic Retrieval Bags Market
Medical Supplies
Ultrasound Gels Market
Medical Supplies
Drosophila Bottles Market
Medical Supplies
Global Medical Mask Market
Medical Supplies
Microcarrier Market
Medical Supplies
Lab Trays Market
Medical Supplies
Global Medical Foam Market
Medical Supplies
Medical Liners Market
Medical Supplies
Hospital Gowns Market
Medical Supplies
Global Disposable Urinary Drainage Bag Market
Medical Supplies
Europe Sharps Containers Market
Medical Supplies
Global IV Bags Market
Medical Supplies
Freeze Drying Masks Market