
 Oxygen Delivery Systems Market | 2026-2036
Oxygen Delivery Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Oxygen Delivery Systems Market Analytics
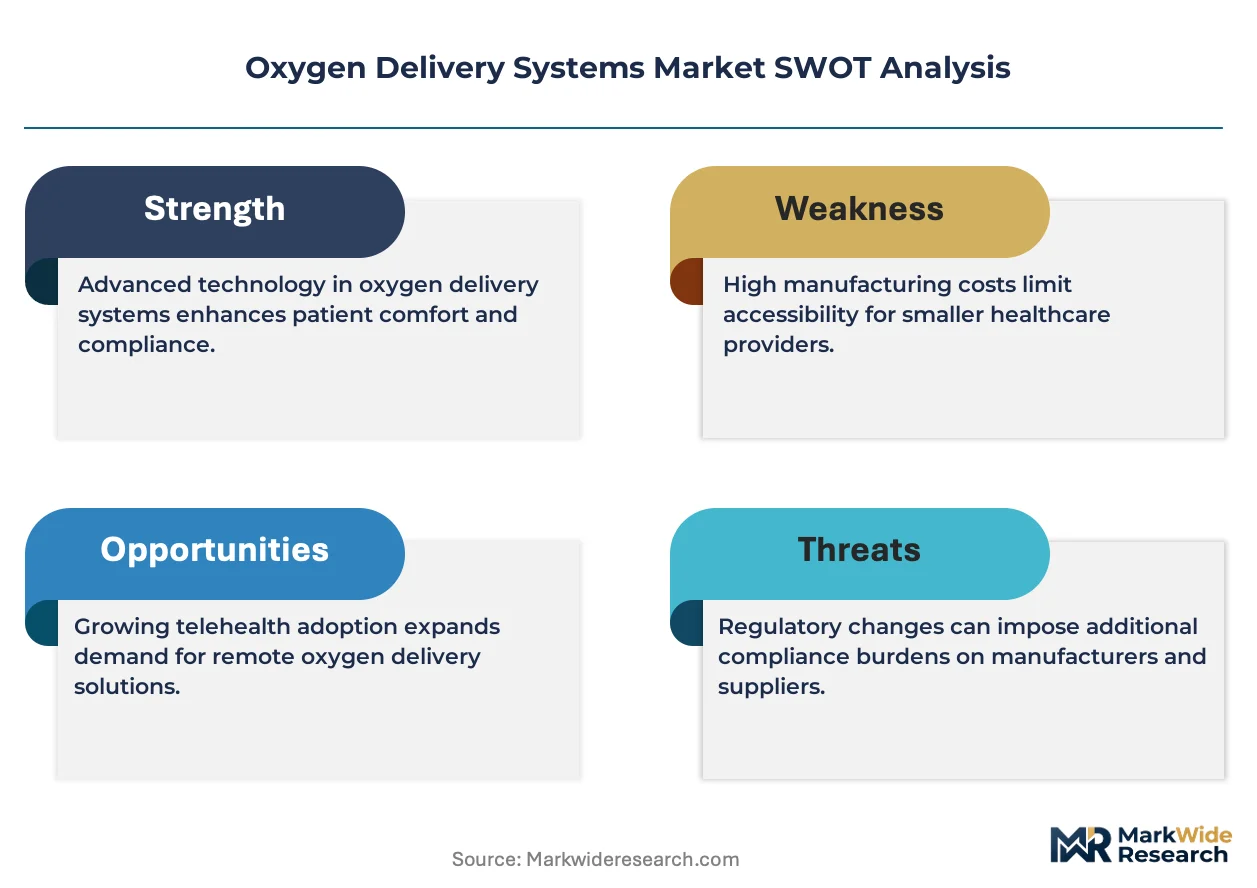
The oxygen delivery systems market is pivoting on a widening gap between premium connected devices and basic commodity concentrators. Linde plc leverages its industrial gas heritage to sustain leadership in liquid oxygen infrastructure for hospital networks. Fisher & Paykel Healthcare differentiates through humidification-integrated interfaces that anchor its position in acute care ventilation.
Oxygen delivery systems encompass devices that administer controlled oxygen concentrations to patients, typically ranging from 24% to 100% FiO2 through nasal cannulas, masks, or closed circuits with precision flow regulators. These systems serve critical therapeutic functions across respiratory failure, perioperative anesthesia, and hypoxic conditions in clinical and ambulatory settings. The concentrator segment leads in installed base volume, while portable technology commands the fastest expansion as lithium-ion power density improvements enable lighter ambulatory units. Homecare end users represent the margin-rich growth corridor, though hospitals still dominate absolute revenue throughput due to bulk procurement of ventilator-integrated systems.
The FDA governs 510(k) clearance pathways for oxygen concentrators in the United States, while the EU MDR imposes stricter clinical evidence requirements for respiratory devices sold across Europe. India's CDSCO aligns with BIS certification standards that mandate electrical safety and oxygen purity thresholds for imported concentrators. Stakeholders must monitor how evolving cybersecurity guidance for connected respiratory devices reshapes product development roadmaps and compliance budgets.
Market Dynamics
Homecare migration is compressing hospital oxygen procurement volumes while lithium-ion battery density gains unlock ambulatory portability, creating bifurcated demand between stationary concentrators and lightweight portable units.
Growth Catalysts
- India's PLI scheme for medical devices:Domestic manufacturing incentives reduce import dependency for concentrators while CDSCO fast-tracks approvals for locally assembled units targeting rural health infrastructure expansion.
- Hyperbaric oxygen therapy:Wound care centers and sports medicine clinics deploy high-flow systems for chronic diabetic ulcers and athletic recovery protocols, extending oxygen delivery beyond respiratory indications.
- Pulse-dose delivery algorithms:Microprocessor-controlled oxygen conservation reduces cylinder consumption by triggering flow synchronized with patient inhalation, lowering logistics burden for homecare providers.
Market Restraints
- Zeolite molecular sieve supply concentration:Three suppliers control premium lithium-grade zeolite production, creating input bottlenecks for concentrator manufacturers during demand surges.
- FDA 510(k) substantial equivalence barriers:Novel portable concentrator designs face extended review timelines when predicate devices lack comparable battery architectures or flow modulation capabilities.
- Liquid oxygen infrastructure decay:Hospital bulk tank installations require seven-figure capital commitments that rural facilities defer, perpetuating reliance on high-cost cylinder exchange programs.
Strategic Opportunities
- Veterans Affairs remote patient monitoring integration:Connected concentrator deployments at VA facilities create reference accounts for civilian payor coverage expansion of reimbursed home oxygen with telehealth oversight.
- EU MDR clinical evidence requirements:First-movers completing PMCF studies for humidification-integrated interfaces capture premium positioning ahead of 2027 certificate renewal deadlines.
- Direct-to-consumer e-commerce channels:Online concentrator sales bypass durable medical equipment intermediaries, capturing margin compression from traditional HME distributor networks.
Industry Challenges
- Battery thermal runaway certification:UN 38.3 lithium-ion testing protocols add six-month pre-market timelines for portable concentrator manufacturers targeting air travel portability claims.
- Biomedical technician training gaps:Homecare providers struggle to recruit personnel qualified for preventive maintenance of membrane-based oxygen generators and pressure swing adsorption valve assemblies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oxygen Delivery Systems Market |
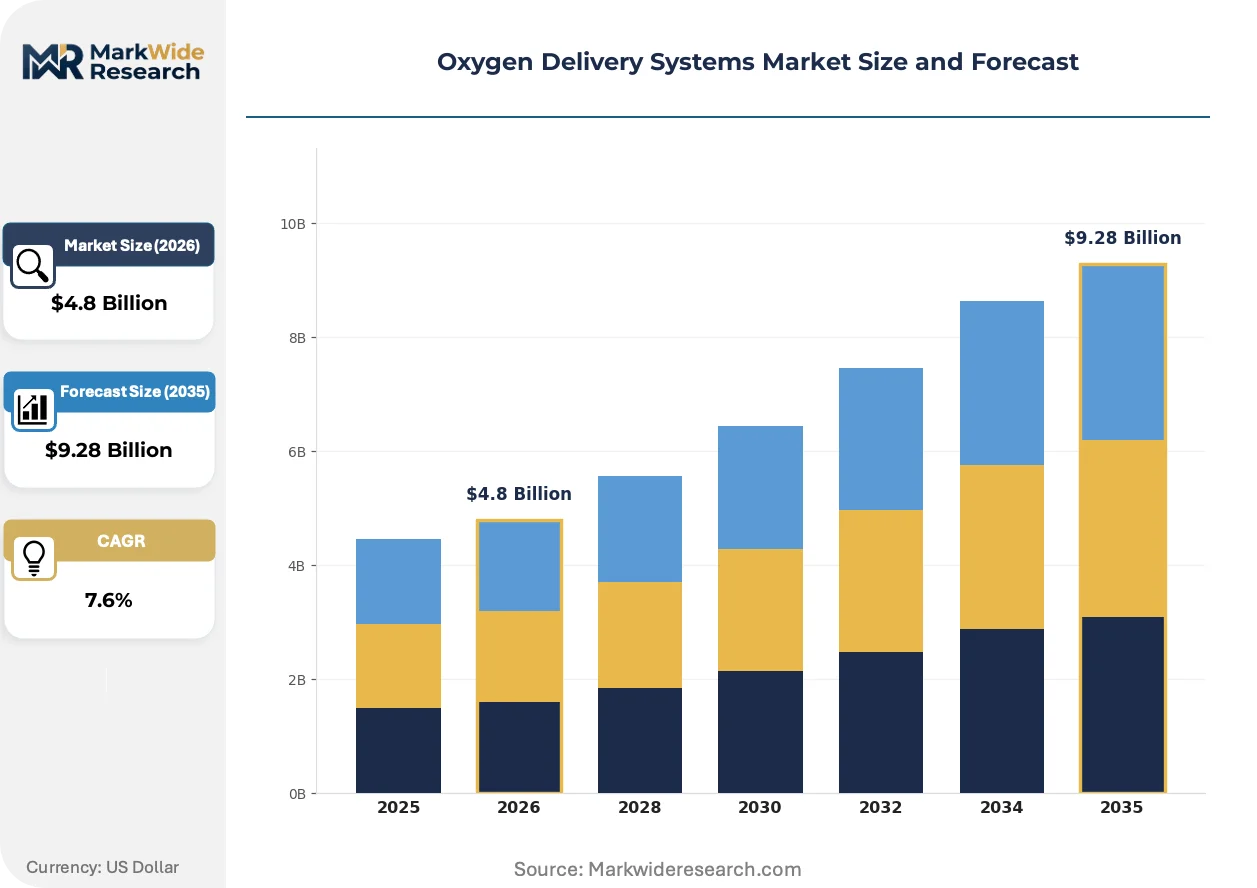
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
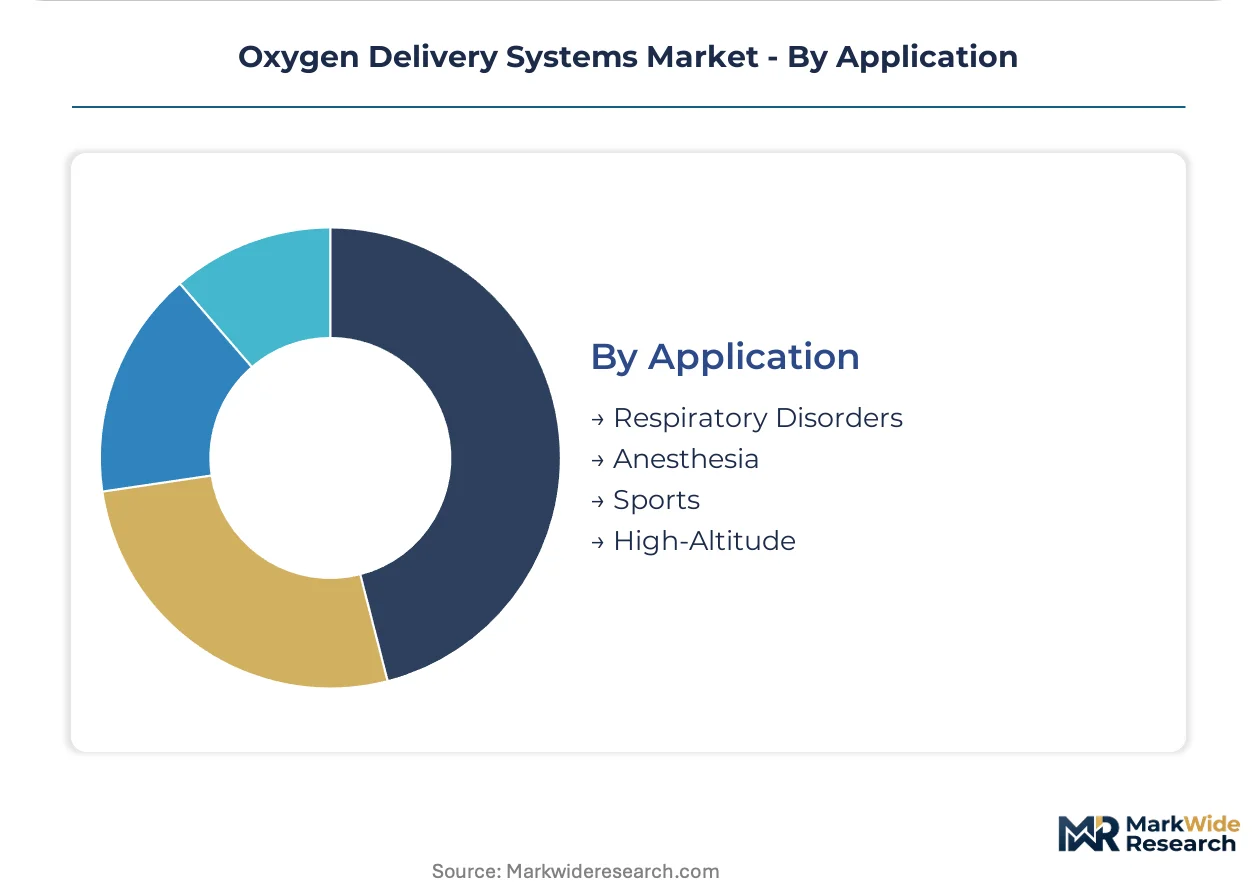
| Segmentation | Product Type: Cylinders, Concentrators, Masks, Ventilators End User: Hospitals, Homecare, Clinics, Emergency Services Technology: Portable, Stationary, Liquid Oxygen, Non-Rebreather Application: Respiratory Disorders, Anesthesia, Sports, High-Altitude |
| Companies Covered | Linde plc, Invacare Corporation, Koninklijke Philips N.V., Chart Industries, Inc., Teleflex Incorporated, Fisher & Paykel Healthcare Limited, Drägerwerk AG & Co. KGaA, Inogen, Inc., BD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oxygen Delivery Systems Market Evolving Landscape
Oxygen delivery architecture is fragmenting across three vectors: powertrain miniaturization, connectivity integration, and reimbursement-aligned service models that bundle device provision with remote clinical monitoring.
Closed-loop oxygen titration using transcutaneous SpO2 feedback is consolidating clinical workflow efficiency in acute care settings. Intensive care units at tertiary hospitals in Germany and Japan deploy these systems to reduce hyperoxia exposure and liberate nursing staff from manual flow adjustments. The technology is consolidating market share at the expense of conventional manual-dial concentrators in high-acuity segments.
The FDA's updated cybersecurity guidance for connected respiratory devices mandates pre-market submission of software bill of materials and vulnerability management protocols. Manufacturers must now embed over-the-air update capabilities and incident response procedures into 510(k) documentation. Portable concentrator developers with legacy Bluetooth architectures face retrofit costs that delay product launches by 8-12 months.
Payor preference for capitated respiratory therapy bundles is displacing fee-for-service oxygen equipment rentals in US Medicare Advantage plans. Managed care organizations in Florida and Arizona now contract directly with device manufacturers for multi-year outcomes-based agreements. This procurement compression squeezes independent HME distributors while favoring vertically integrated suppliers with captive clinical monitoring platforms.
Oxygen Delivery Systems Market Segmentation
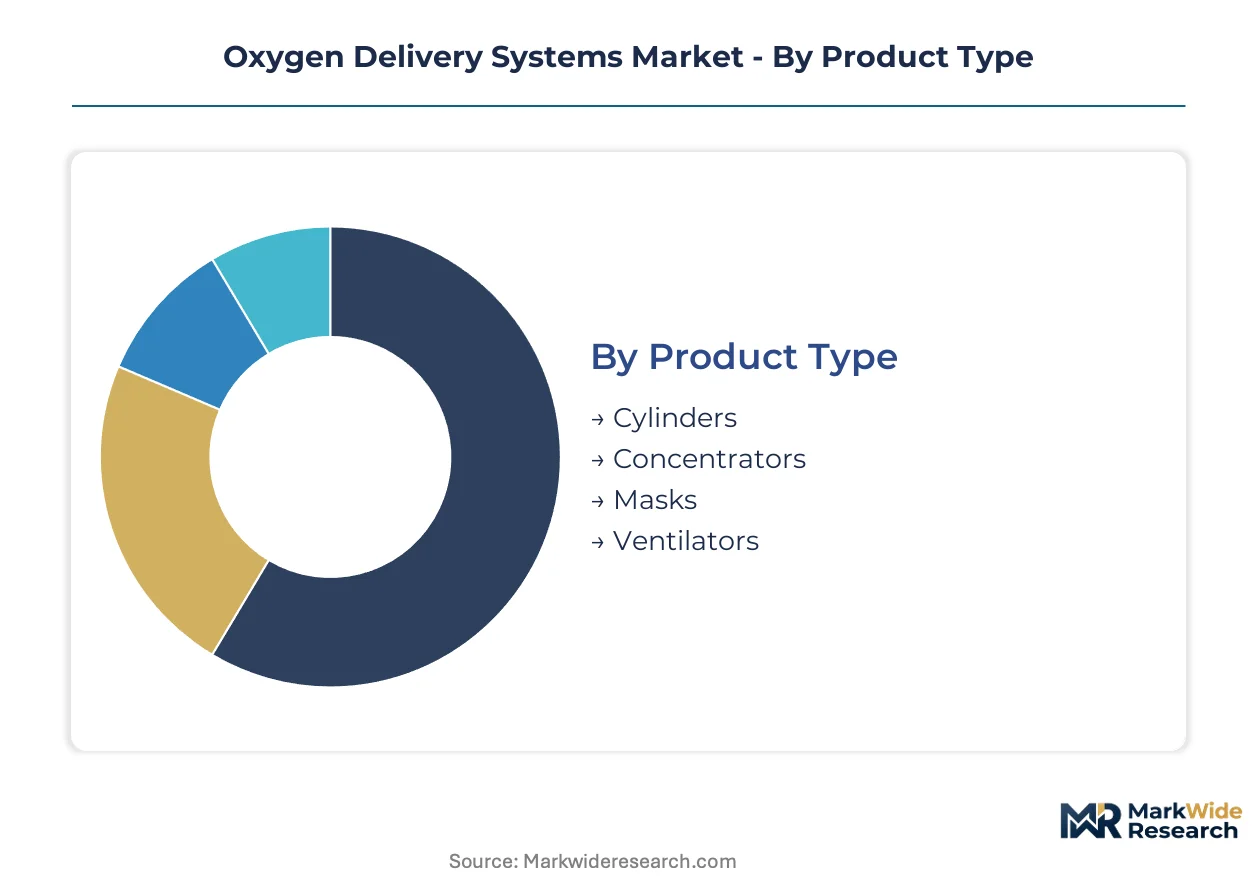
Oxygen delivery systems fragment across equipment physics, care setting workflows, and patient mobility requirements. Manufacturers optimize capital deployment differently across stationary infrastructure versus ambulatory platforms, creating divergent margin structures within each segment cluster.
Product Type:
Concentrators demand the heaviest upfront manufacturing investment, with pressure swing adsorption systems requiring precision zeolite assembly lines and automated sieve bed production.
- Concentrators:Pressure swing adsorption units separate nitrogen from ambient air through zeolite molecular sieves, delivering continuous flow oxygen at 1-10 LPM. India's CDSCO fast-tracks approvals for locally assembled concentrators under PLI scheme incentives, compressing time-to-market for domestic manufacturers targeting rural health infrastructure expansion.
- Cylinders:High-pressure aluminum or composite vessels store compressed medical-grade oxygen at pressures exceeding 2000 psi, requiring hydrostatic testing protocols and DOT/UN transport certification. Rural hospitals in the United States defer bulk tank capital commitments, perpetuating reliance on cylinder exchange logistics that inflate per-patient oxygen costs.
- Masks:Nasal cannulas and reservoir interfaces deliver controlled FiO2 concentrations through disposable polymer assemblies.
- Ventilators:Closed-circuit systems integrate oxygen blending with positive pressure ventilation for acute respiratory failure.
Most installed capacity flows through concentrators. Expansion is steepest in portable concentrator variants.
End User:
Hospital procurement concentrates volume through centralized purchasing consortia, while homecare channels fragment across durable medical equipment distributors and direct-to-consumer platforms.
- Hospitals:Tertiary care networks in Germany and Japan deploy closed-loop oxygen titration systems in intensive care units, automating SpO2 feedback to reduce hyperoxia exposure and liberate nursing staff from manual flow adjustments. Bulk procurement of ventilator-integrated systems sustains absolute revenue throughput despite compressing unit margins.
- Homecare:Medicare Advantage plans in Florida and Arizona displace fee-for-service rentals with capitated respiratory therapy bundles, forcing manufacturers to embed remote patient monitoring capabilities. Lithium-ion power density gains enable lightweight ambulatory units that unlock patient mobility while reducing logistics burden for providers.
- Clinics:Wound care and sports medicine facilities deploy high-flow systems for hyperbaric oxygen therapy protocols.
- Emergency Services:Pre-hospital responders prioritize pulse-dose delivery algorithms that conserve cylinder inventory through inhalation-synchronized flow triggering.
Hospital networks anchor absolute revenue volume. Homecare channels are climbing the fastest as aging populations shift treatment from institutional to residential settings.
Technology:
Powertrain architecture determines portability claims and regulatory pathway complexity, with lithium-ion systems facing extended UN 38.3 certification timelines.
- Portable:Microprocessor-controlled units weighing under five pounds deploy pulse-dose algorithms to extend battery endurance, though FDA 510(k) substantial equivalence barriers delay novel designs when predicate devices lack comparable battery architectures. UN 38.3 thermal runaway testing adds six-month pre-market timelines for manufacturers targeting air travel portability claims.
- Stationary:Fixed-installation concentrators serve 24/7 oxygen-dependent patients through continuous flow delivery, requiring minimal patient interface training but tethering users to power outlets. These systems dominate rural Indian health infrastructure programs where grid reliability exceeds battery logistics feasibility.
- Liquid Oxygen:Cryogenic storage systems deliver highest purity oxygen at lowest per-liter cost for high-flow patients.
- Non-Rebreather:Reservoir mask designs maximize inspired oxygen concentration during acute hypoxic episodes.
Stationary technology holds the largest installed base. Portable platforms are gaining share fastest as battery chemistry advances compress weight-to-duration ratios.
Application:
Clinical indication breadth shapes reimbursement coding complexity and payor prior authorization requirements.
- Respiratory Disorders:Chronic obstructive pulmonary disease and interstitial lung disease patients constitute the core addressable population, with Medicare coverage criteria mandating documented hypoxemia thresholds and arterial blood gas measurements. FDA oxygen concentrator standards govern device certification for these indications in the United States.
- Anesthesia:Perioperative oxygen delivery requires precise FiO2 blending with volatile anesthetic agents, integrating with hospital gas pipeline infrastructure. EU MDR clinical evidence requirements for humidification-integrated interfaces create premium positioning opportunities for first-movers completing PMCF studies ahead of certificate renewal deadlines.
- Sports:Athletic recovery protocols and altitude acclimation drive non-reimbursed consumer purchases.
- High-Altitude:Commercial aviation and mountaineering applications demand lightweight emergency oxygen deployment.
Respiratory disorders command the deepest reimbursement penetration. Sports applications are expanding most quickly as wellness consumers adopt oxygen for recovery optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biomedical engineering talent clusters in Germany, the United States, and Japan anchor oxygen delivery system innovation, while manufacturing scale concentrates in India and China where component assembly costs compress final unit economics.
United States
Medicare Advantage penetration in Florida and Arizona drives capitated respiratory therapy bundles that displace fee-for-service oxygen equipment rentals. The FDA's updated 510(k) clearance pathways for oxygen concentrators mandate pre-market submission of software bill of materials for connected devices. Manufacturing activity concentrates in Minnesota's Twin Cities corridor where medical device clusters supply humidification-integrated interfaces to hospital networks.
Germany
Intensive care units at tertiary hospitals deploy closed-loop oxygen titration systems that automate SpO2 feedback to reduce hyperoxia exposure. The EU MDR imposes stricter clinical evidence requirements for respiratory devices, with PMCF studies required ahead of 2027 certificate renewal deadlines. Industrial gas infrastructure in the Ruhr region sustains liquid oxygen distribution networks serving hospital bulk tank installations.
India
Government-backed rural health infrastructure programs expand access to concentrators and portable systems across district hospital networks. The CDSCO aligns with BIS certification standards that mandate electrical safety and oxygen purity thresholds for imported concentrators under PLI scheme incentives. Manufacturing investment clusters in Gujarat and Maharashtra where domestic assembly lines target time-to-market compression for locally produced units.
Japan
Aging demographics accelerate homecare migration from institutional settings, creating demand for lightweight ambulatory concentrators with lithium-ion powertrains. METI oversees medical device approval pathways that recognize JIS standards for electrical safety and electromagnetic compatibility. Tokyo-Osaka medical device corridors host development centers for pulse-dose delivery algorithms that synchronize flow with patient inhalation patterns.
China
Zeolite molecular sieve supply concentration creates input bottlenecks for concentrator manufacturers, with domestic producers scaling pressure swing adsorption assembly capacity. NMPA governs medical device registration requirements that align with GB standards for oxygen purity and electrical safety. Manufacturing scale concentrates in Jiangsu and Zhejiang provinces where component suppliers serve both domestic hospital procurement and export assembly contracts.
Oxygen Delivery Systems Market Competitive Landscape
Top-tier vendors anchor hospital and homecare channels with vertically integrated gas infrastructure and device portfolios, while mid-tier specialists concentrate on portable technology and regional distribution networks. The competitive structure fragments across industrial gas heritage players, dedicated respiratory device manufacturers, and emerging portable technology developers. Three archetypes dominate: infrastructure-integrated suppliers with captive liquid oxygen networks, device-centric specialists with humidification-integrated platforms, and battery-powered portable innovators targeting ambulatory mobility. Consolidation pressures intensify through strategic partnerships that combine gas distribution logistics with connected device telemetry capabilities.
Within the industrial gas heritage tier, Linde plc exemplifies infrastructure-anchored positioning through liquid oxygen network control. Among dedicated respiratory specialists, Fisher & Paykel Healthcare Limited and Koninklijke Philips N.V. occupy positions representing humidification-integrated and connected monitoring archetypes respectively. These three entities illustrate how competitive differentiation stratifies across gas logistics mastery, acute care interface integration, and homecare connectivity platforms.
| Leading Market Players |
|---|
| Linde plc |
| Invacare Corporation |
| Koninklijke Philips N.V. |
| Chart Industries, Inc. |
| Teleflex Incorporated |
| Fisher & Paykel Healthcare Limited |
| Drägerwerk AG & Co. KGaA |
| Inogen, Inc. |
| BD |
| Others |
Value Network & Pricing Analysis
Medicare Advantage capitation mandates in Florida and Arizona are compressing fee-for-service oxygen equipment margins, forcing manufacturers to absorb logistics costs within bundled reimbursement rates while shifting procurement volume toward vertically integrated suppliers with captive clinical monitoring platforms.
Pricing Analysis
The bundled-versus-unbundled service split defines pricing architecture across oxygen delivery systems. Capitated respiratory therapy bundles displace traditional fee-for-service rentals in US Medicare Advantage plans, while standalone device transactions persist in direct-to-consumer channels. Price differentiation rests on certification grade—FDA 510(k) clearance tier versus basic electrical safety compliance—and after-sales service bundling with remote patient monitoring. Pricing pressure stems from GPO procurement consolidation at tertiary hospital networks. Homecare channels exhibit highest price sensitivity due to fixed reimbursement ceilings, while acute care ventilation-integrated systems command premium tolerance.
Supply Chain Analysis
Freight cost volatility for compressed gas cylinders and cryogenic liquid oxygen tanks shapes regional sourcing strategies, with rural hospitals deferring bulk tank capital commitments in favor of higher-frequency cylinder exchange logistics. Manufacturing concentrates in India, China, and the United States. Zeolite molecular sieves, lithium-ion battery cells, and precision polymer mask assemblies constitute critical input dependencies. Single-source vulnerability concentrates in premium lithium-grade zeolite production. Distribution runs through durable medical equipment intermediaries, though direct-to-consumer e-commerce channels are gaining share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oxygen delivery systems constitute a late-cycle quality story as payor preference shifts toward FDA-cleared connected devices with embedded cybersecurity capabilities and over-the-air update architectures, displacing commodity concentrators from reimbursed channels.
For Market Incumbents: Acquire remote patient monitoring software platforms to anchor capitated bundle offerings. Integrate backward into zeolite sieve bed production to insulate against input bottlenecks during demand surges. Consolidate GPO contract positions at Veterans Affairs facilities to establish reference accounts for civilian payor expansion. Defend against portable technology entrants by accelerating UN 38.3 thermal runaway certification for air-travel-rated lithium-ion systems. For New Entrants and Emerging Players: The premium-to-economy price-point gap in humidification-integrated interfaces offers white-space entry for mid-tier specialists completing EU MDR PMCF studies ahead of certificate renewal deadlines. Target India's PLI scheme incentives for domestic concentrator assembly to compress CDSCO approval timelines for rural health infrastructure tenders. Pursue direct-to-consumer e-commerce positioning to bypass HME distributor margin compression. Emphasize pulse-dose algorithm differentiation for athletic recovery and wellness applications outside reimbursed respiratory indications. For Investors and Strategic Acquirers: Asymmetric upside sits with portable technology developers possessing UN 38.3-certified lithium-ion architectures and FDA 510(k) clearance for connected respiratory devices. Long-term viability favors vertically integrated suppliers combining gas distribution logistics with telehealth-enabled clinical monitoring platforms. Monitor FDA cybersecurity guidance enforcement as inflection indicator for retrofit cost burdens on legacy Bluetooth architectures.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Cybersecurity Compliance | Pre-market software bill of materials submission mandates reshape development roadmaps for connected concentrators. |
| EU MDR PMCF Study Completion | First-movers capturing humidification-integrated interface positioning ahead of certificate renewal deadlines secure premium pricing. |
| India PLI Scheme Manufacturing | Domestic assembly incentives compress CDSCO approval timelines for concentrators targeting rural health infrastructure. |
| VA Remote Patient Monitoring Integration | Connected concentrator deployments at Veterans Affairs facilities establish reference accounts for civilian payor expansion. |
| Direct-to-Consumer E-Commerce Launch | Online sales bypass durable medical equipment intermediaries to capture margin compression from traditional distributor networks. |
Research Methodology
Bottom-up homecare and hospital procurement modeling reconciled against top-down concentrator manufacturing capacity tracking forms the analytical core. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and durable medical equipment distributors combined with secondary validation from FDA 510(k) filings, CMS Medicare claims data, CDSCO approval registries, and EU MDR notified body certificates. Triangulation across stakeholder inputs and regulatory documentation ensures segmentation integrity.
Input-output matrices map zeolite molecular sieve supply through pressure swing adsorption assembly to end-use channel distribution across the projection horizon. Segmentation dimensions include product type, care setting, powertrain architecture, and clinical indication. CAGRs derive from installed base replacement cycles, lithium-ion battery chemistry advancement curves, and reimbursement policy trajectory assumptions. Forecast inputs incorporate PLI scheme manufacturing incentives and FDA cybersecurity guidance implementation timelines.
Caveats apply where zeolite supply concentration, FDA substantial equivalence review delays, or Medicare Advantage bundle penetration rates could materially shift the outlook. Forecasts reflect documented assumptions about battery energy density improvement curves and rural health infrastructure investment continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Digital Blood Pressure Monitors Market
Medical Devices
Global Insufflation Devices Market
Medical Devices
Global Coagulation-Hemostasis Analyzer Market
Medical Devices
Medical Device and Accessories Market
Medical Devices
Infusion Pump Market
Medical Devices
Dosing Units Market
Medical Devices
Global Neurovascular Thrombectomy Devices Market
Medical Devices
North America Cataract Surgery Devices Market
Medical Devices
Peripheral Nerve Stimulators Market
Medical Devices
Hysterectomy Devices Market
Medical Devices
Global Lenses for Myopia Control Market
Medical Devices
Face Mask Device Market
Medical Devices
South Korea Massage Equipment Market
Medical Devices
Pulse Electromagnetic Field (PEMF) Therapy Devices Market
Medical Devices
Medical LED Headlight Market
Medical Devices
Mobile Healthcare Devices Market