
 Global Industrial Battery Market | 2026-2036
Global Industrial Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Battery Market Outlook
Market Context
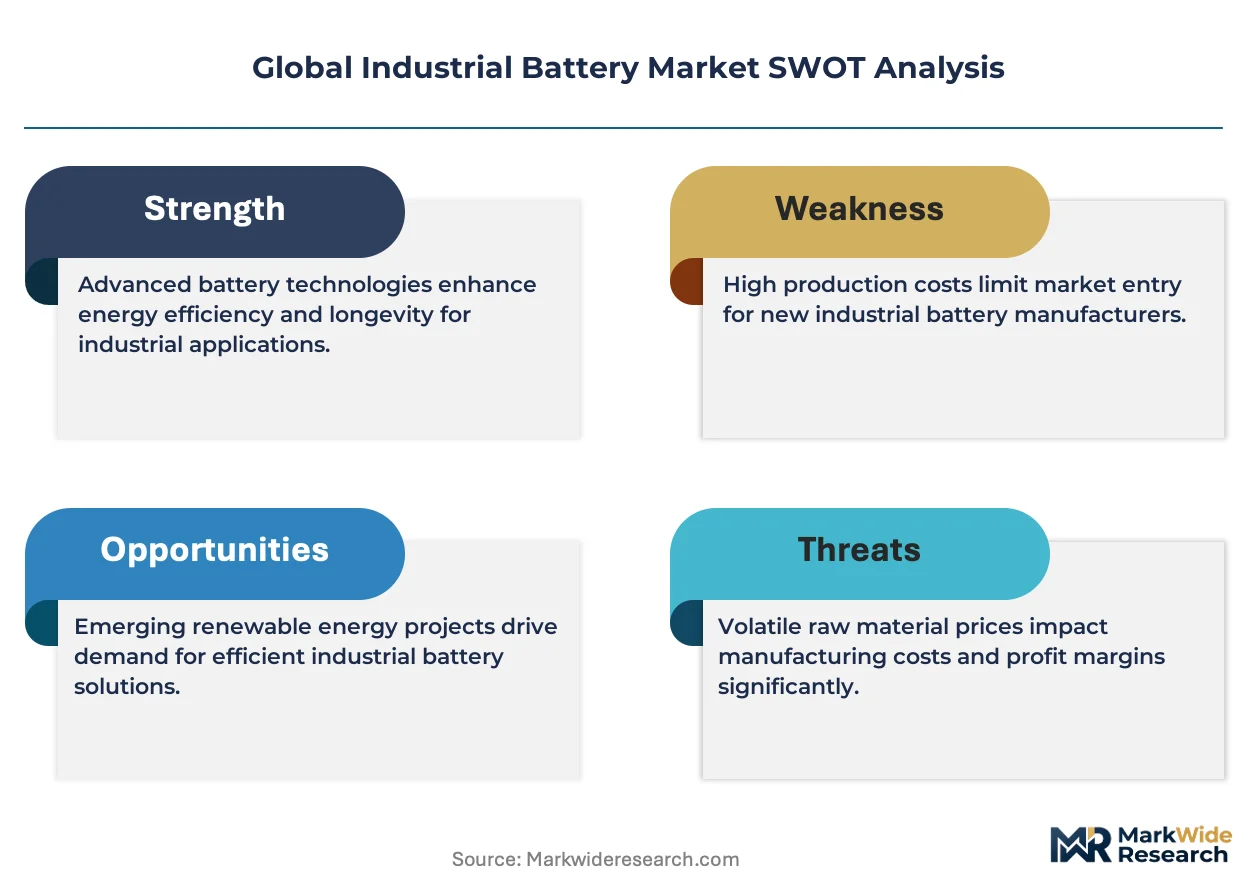
High-cycle-life lithium iron phosphate specifications are reorganizing procurement criteria for utility-scale buyers. Enersys, Inc. anchors North American motive power fleets with deep vertical integration into lead-acid recycling. CATL dominates cell supply for grid storage integrators through manufacturing scale in Fujian province. Saft Groupe S.A. specializes in nickel-cadmium backup systems for offshore oil platforms and Arctic telecommunications sites.
Technical Definition and Segments
An industrial battery is an electrochemical energy storage device engineered for heavy-duty cycling, typically rated above 20 kWh capacity with operational lifespans exceeding 3,000 cycles at 80% depth of discharge, designed to power forklifts, telecom towers, renewable farms, and grid stabilization assets. Lead-acid chemistry retains margin pools in motive power and telecommunications backup where capital constraints outweigh energy density requirements. Lithium-ion chemistry leads grid storage and electric vehicle applications where energy density and fast charging capabilities offset higher upfront costs. Flow batteries occupy long-duration storage niches above six hours discharge duration where cycling economics displace lithium-ion degradation curves.
Regulatory Environment
The EPA governs lead-acid recycling under the Battery Act while China's MEE enforces dual carbon goals that mandate cleaner cell manufacturing footprints. The EU's F-Gas Regulation and REACH chemical restrictions are reshaping electrolyte formulations and thermal management system designs. Stakeholders must monitor how ISO 26262 functional safety standards and IEC 62619 industrial lithium-ion certifications evolve as differentiators for market access rather than baseline compliance.
Market Dynamics
The industrial battery market is reconfiguring around lithium iron phosphate chemistry's erosion of lead-acid's total cost of ownership advantage in motive power fleets, forcing incumbent suppliers to accelerate recycling infrastructure investments or surrender margin to Chinese cell manufacturers with integrated cathode supply chains.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon-based thermal management fluids is compelling data center operators in Frankfurt and Amsterdam to specify liquid-cooled lithium-ion systems with lower global warming potential refrigerants.
- Grid-scale solar pairing:Texas ERCOT nodal pricing volatility is driving independent power producers to co-locate four-hour lithium-ion storage with photovoltaic arrays to capture price arbitrage and ancillary service revenues.
- Sodium-ion chemistry maturation:CATL's mass production of prismatic sodium-ion cells is creating a lower-cost alternative for stationary applications where energy density requirements are modest and raw material security concerns dominate procurement criteria.
Market Restraints
- Cathode material concentration:Over 70% of refined lithium hydroxide processing capacity resides in China, exposing non-Chinese integrators to export license risk and forced technology transfer pressures under MIIT industrial policy guidelines.
- Lead-acid residual value capture:Enersys and Exide Technologies control closed-loop recycling networks that recover 99% of lead content, creating a 30-40% cost advantage in forklift motive power that lithium-ion cannot match without scale.
- IEC 62619 certification timelines:Third-party testing for industrial lithium-ion safety verification requires 14-18 months, delaying product launches and freezing working capital in pre-certified inventory.
Strategic Opportunities
- India CEA storage mandates:The Central Electricity Authority's requirement for 27 GW of grid-connected battery storage by 2030 is opening procurement windows for integrators willing to localize assembly in Gujarat and Tamil Nadu manufacturing corridors.
- Vanadium flow battery hybridization:Six-to-twelve hour duration requirements in South Australian renewable integration projects are creating deployment opportunities for flow-lithium hybrid architectures that optimize cycling economics against capital efficiency.
- Direct-to-fleet leasing models:Battery-as-a-service contracts that unbundle cell ownership from forklift procurement are penetrating German automotive supplier logistics networks, converting capex-resistant mid-market buyers to lithium-ion adoption.
Industry Challenges
- Cell-to-pack thermal engineering:The transition from modular battery architectures to cell-to-pack designs requires scarce expertise in computational fluid dynamics and fire propagation modeling that incumbent lead-acid engineers rarely possess.
- UL 9540A test facility bottlenecks:Only twelve certified laboratories worldwide can execute large-scale fire safety validation for grid storage systems, creating 8-12 month queue delays that compress product development calendars.
- Legacy SCADA integration:Industrial battery management systems must communicate with decades-old facility automation protocols in manufacturing plants and telecommunications central offices, forcing expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Battery Market |
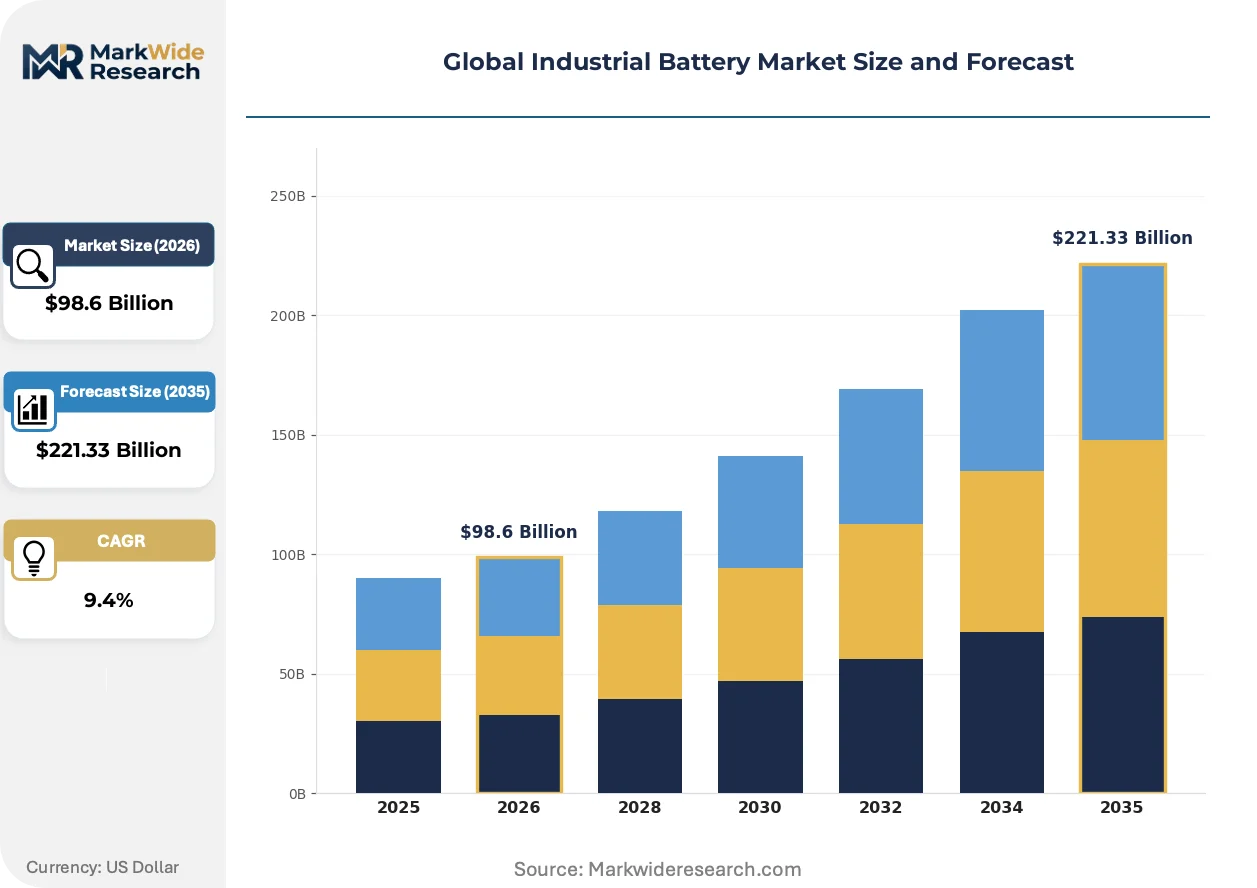
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $221.33 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-Ion, Lead-Acid, Nickel-Cadmium, Flow Batteries End User: Construction, Transportation, Renewable Energy, Telecommunications Application: Backup Power, Electric Vehicles, Grid Storage, Portable Devices Technology: Battery Management Systems, Energy Density, Fast Charging, Recycling Technologies |
| Companies Covered | Enersys, Inc., C&D Technologies, Inc., GS Yuasa Corp., Exide Technologies, Inc., Saft Groupe S.A., Johnson Controls, Inc., East Penn Manufacturing Co., Contemporary Amperex Technology Co., Limited (CATL), Robert Bosch GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Battery Market Strategic Shifts
Solid-state electrolyte development, regulatory chemistry restrictions, and procurement model fragmentation are converging to compress technology lifecycles and redistribute value capture across the industrial battery value chain.
Solid-state battery architectures with sulfide-based electrolytes are decomposing the conventional separator-electrolyte-liquid interface that has defined lithium-ion safety margins for three decades. Automotive-qualified solid-state cells from Toyota and QuantumScape are cascading technical validation data into industrial applications, enabling data center operators in Northern Virginia to specify systems with reduced thermal runaway propagation risk. The structural consequence is decomposing the fire suppression infrastructure cost premium that has slowed lithium-ion penetration in densely populated urban installations.
China's MEE enforcement of dual carbon goals is mandating 30% reductions in cell manufacturing carbon intensity by 2027, compelling Fujian and Jiangsu province facilities to convert electricity procurement to renewable sources and install closed-loop solvent recovery systems. This regulatory pressure is transmitting through supply contracts to European and North American integrators, who must now document Scope 3 emissions for EU CSRD reporting requirements. Grid storage projects in Germany are responding by specifying cells from manufacturing lines with verified renewable electricity certificates, accepting 8-12% cost premiums for compliance certainty.
Asset-light procurement through energy storage service agreements is displacing traditional equipment purchase-and-ownership models in commercial and industrial segments. Independent power producers in Texas and California are offering ten-year contracts that guarantee availability and performance, retaining residual value risk and cell replacement obligations. This shift is most visible in refrigerated warehouse applications in the US Southeast, where capital-constrained third-party logistics providers prefer operational expenditure treatment for battery backup systems over balance-sheet deployment.
Global Industrial Battery Market Segmentation
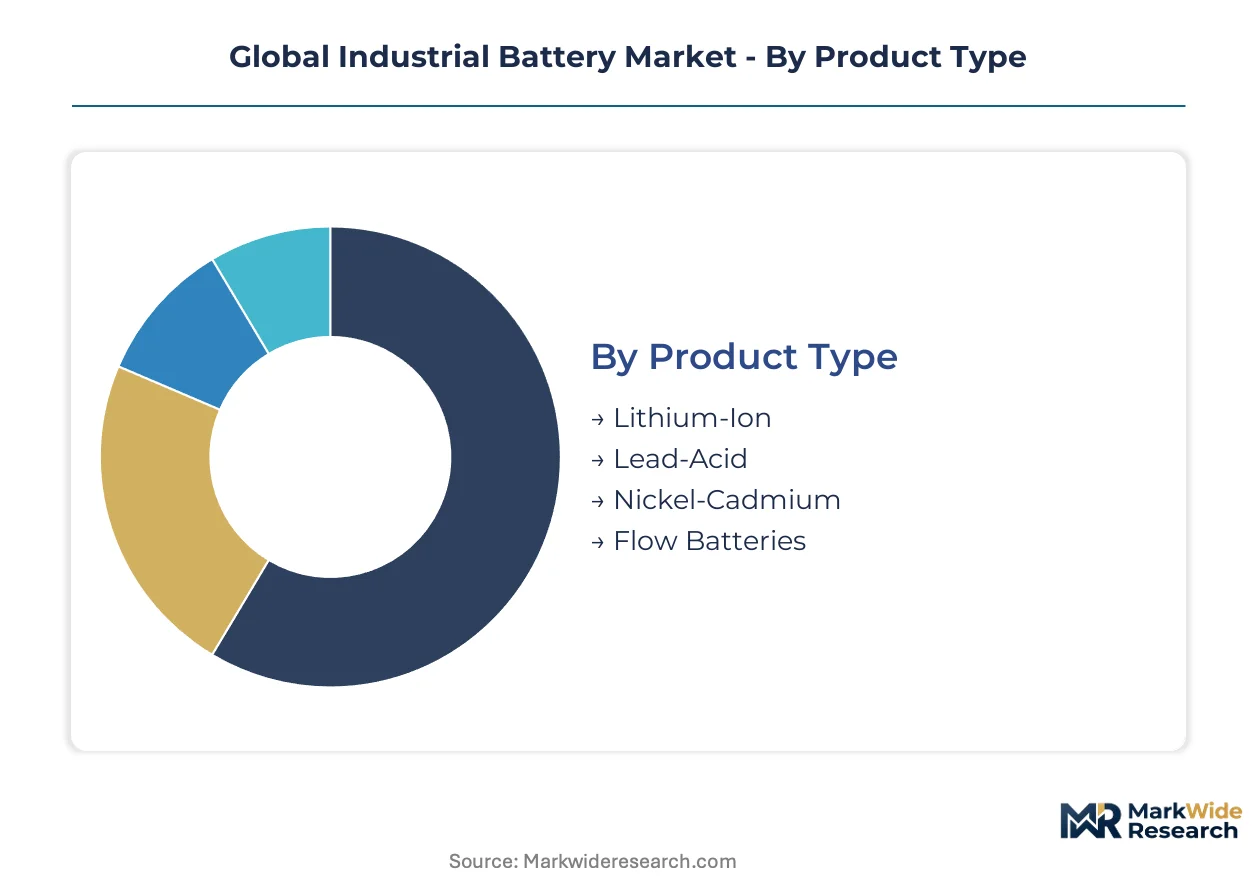
Industrial battery procurement decisions split across chemistry trade-offs, duty-cycle requirements, and regulatory exposure zones. Segment boundaries are blurring as lithium iron phosphate advances into motive power and flow batteries capture multi-hour grid applications.
Product Type:
Substitution pressure runs deepest against nickel-cadmium and lead-acid chemistries as lithium-ion manufacturing scale collapses cost premiums.
- Lithium-Ion:Lithium iron phosphate and nickel manganese cobalt cells dominate installations above 50 kWh. Grid-scale solar pairing in Texas and South Australia drives procurement for four-hour duration systems with cycle lives exceeding 6,000.
- Lead-Acid:Flooded and valve-regulated designs retain forklift motive power and telecommunications backup where recycling infrastructure delivers 30-40% cost advantages. Enersys and Exide Technologies control closed-loop recovery networks that preserve margin pools.
- Nickel-Cadmium:Sintered plate constructions survive Arctic telecommunications and offshore oil platforms where temperature extremes exceed lithium-ion thermal windows.
- Flow Batteries:Vanadium redox systems capture six-to-twelve hour grid storage in South Australian renewable integration projects where cycling economics displace lithium degradation curves.
Lead-acid anchors the volume base while lithium-ion gains share at the steepest rate.
End User:
Capital intensity and duty-cycle predictability separate volume buyers from price-sensitive adopters across industrial verticals.
- Construction:Electric excavators and aerial work platforms in German automotive supplier networks specify leased lithium-ion packs through battery-as-a-service contracts.
- Transportation:Forklift motive power fleets in Northern Virginia distribution centers face lithium iron phosphate conversion decisions as total cost of ownership parity arrives.
- Renewable Energy:Independent power producers co-locate storage with photovoltaic arrays to capture ERCOT nodal pricing volatility and ancillary service revenues.
- Telecommunications:Central offices and cell towers specify nickel-cadmium or valve-regulated lead-acid for backup durations under four hours where capital constraints dominate.
Transportation commands the largest installed base while renewable energy climbs the fastest.
Application:
Duty-cycle depth and discharge duration requirements fragment technology selection across use cases.
- Backup Power:Data centers in Frankfurt and Amsterdam specify liquid-cooled lithium-ion systems as EU F-Gas Regulation phases down hydrofluorocarbon thermal management fluids.
- Electric Vehicles:Industrial forklifts and automated guided vehicles transition from lead-acid to lithium-ion where fast-charging infrastructure supports multi-shift operations.
- Grid Storage:India's CEA mandates 27 GW of grid-connected battery storage, opening procurement windows for integrators localizing assembly in Gujarat and Tamil Nadu corridors.
- Portable Devices:Ruggedized field equipment for mining and military applications specifies energy-dense lithium-ion with MIL-STD-810G shock certification.
Backup power sustains the revenue core while grid storage expands most quickly.
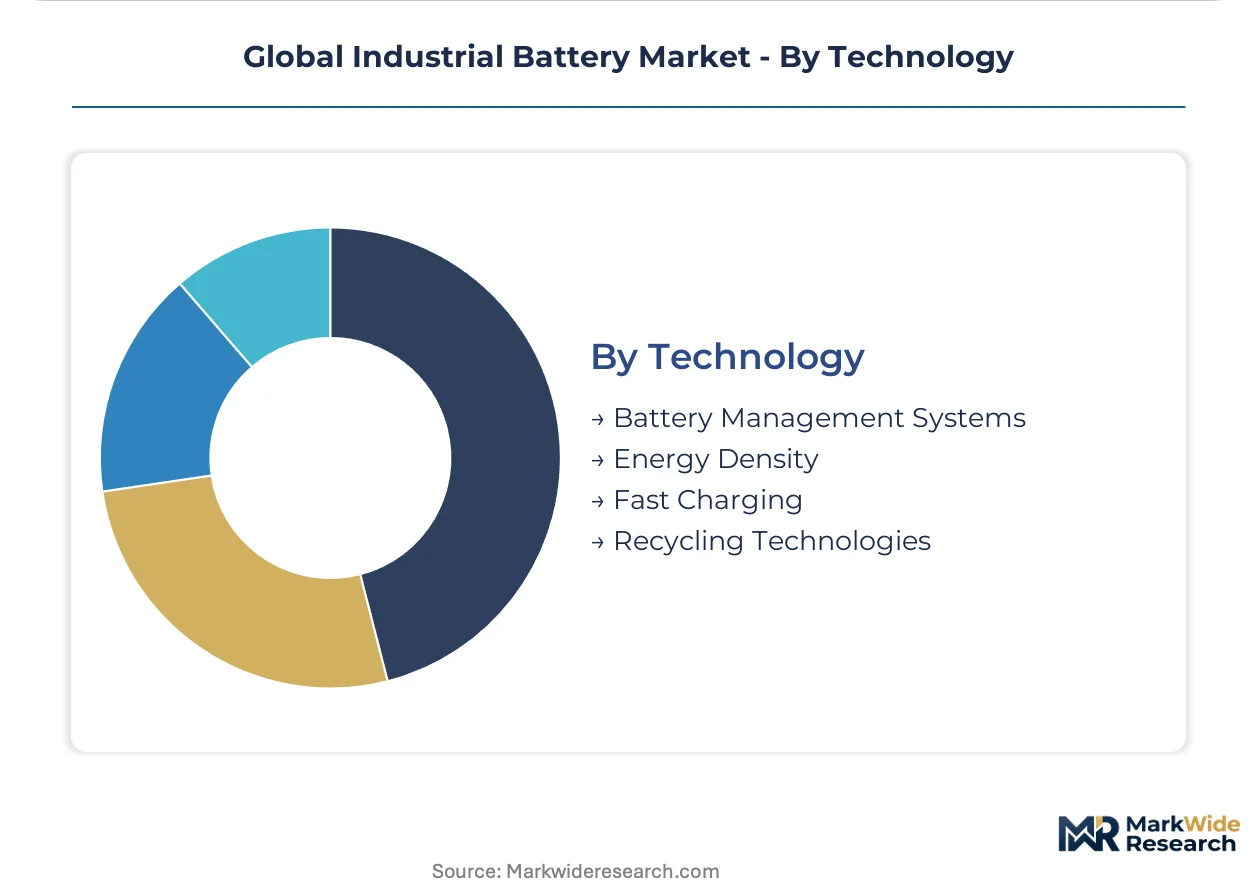
Technology:
Cell-to-pack thermal engineering and safety certification bottlenecks concentrate value capture among specialized subsystem suppliers.
- Battery Management Systems:Firmware stacks must bridge legacy SCADA protocols in decades-old manufacturing plants, forcing expensive middleware development.
- Energy Density:Solid-state sulfide electrolytes from automotive qualification programs cascade into data center specifications with reduced thermal runaway propagation risk.
- Fast Charging:Multi-crate charge rates above 3C enable opportunity charging for forklift fleets, though cell degradation curves require predictive algorithm compensation.
- Recycling Technologies:China's MEE dual carbon goals mandate closed-loop solvent recovery and renewable electricity procurement for cell manufacturing lines.
Energy density improvements command R&D priority while recycling technologies face regulatory acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cell manufacturing capacity clusters in China, Germany, and the United States, with regulatory divergence in carbon accounting and safety certification creating distinct procurement environments across major demand centers.
China
Grid-scale lithium-ion deployments in Fujian and Jiangsu provinces absorb the bulk of domestic cathode output. The MEE enforces dual carbon goals mandating 30% reductions in manufacturing carbon intensity by 2027. CATL's mass production lines in Ningde supply integrators across Texas, Germany, and South Australia with prismatic sodium-ion alternatives.
Germany
Data center operators in Frankfurt specify liquid-cooled systems as the EU F-Gas Regulation phases down hydrofluorocarbon thermal management fluids. The country's national industrial regulator enforces REACH chemical restrictions that reshape electrolyte formulations. Bavarian automotive supplier networks are adopting battery-as-a-service contracts for forklift fleet conversions.
United States
Independent power producers in Texas co-locate four-hour lithium-ion storage with photovoltaic arrays to capture ERCOT nodal pricing volatility. The EPA governs lead-acid recycling under the Battery Act while FERC rules enable storage participation in wholesale markets. Northern Virginia data center clusters are expanding uninterruptible power supply fleets with solid-state safety specifications.
India
The Central Electricity Authority mandates 27 GW of grid-connected battery storage by 2030, opening procurement windows for integrators localizing assembly. The BIS certifies industrial lithium-ion systems under evolving safety standards. Manufacturing corridors in Gujarat and Tamil Nadu are attracting module assembly investments from Chinese and Korean cell suppliers.
Australia
Six-to-twelve hour duration requirements in South Australian renewable integration projects create deployment opportunities for vanadium flow battery hybridization. The country's national energy regulator oversees grid connection standards for utility-scale storage. Mining operations in Western Australia specify ruggedized field equipment with MIL-STD-810G shock certification for remote site power.
Global Industrial Battery Market Competitive Environment
Concentration sits with integrated cell manufacturers and closed-loop recyclers, while the vendor base stratifies across three tiers defined by cathode supply chain control, recycling network density, and safety certification breadth. Tier-one positions are held by companies with captive lithium hydroxide processing or lead-acid recovery infrastructure. Tier-two players compete on regional assembly proximity and middleware integration capabilities. Tier-three specialists occupy nickel-cadmium niches in extreme temperature applications. Dominant competitive moves include backward integration into cathode materials and geographic expansion through joint ventures with local integrators.
Among US-based fabricators, East Penn Manufacturing Co. and Enersys, Inc. exemplify the recycling-anchored archetype with closed-loop lead recovery networks. Contemporary Amperex Technology Co., Limited (CATL) represents the scale-driven Asian cell manufacturer with integrated cathode supply chains. These three companies occupy positions that illustrate the structural divide between legacy chemistry recyclers and lithium-ion manufacturing scale players.
| Leading Market Players |
|---|
| Enersys, Inc. |
| C&D Technologies, Inc. |
| GS Yuasa Corp. |
| Exide Technologies, Inc. |
| Saft Groupe S.A. |
| Johnson Controls, Inc. |
| East Penn Manufacturing Co. |
| Contemporary Amperex Technology Co., Limited (CATL) |
| Robert Bosch GmbH |
| Others |
Value Chain & Pricing Dynamics
CATL's gigafactory utilization rates above 85% in Fujian province compress unit economics across prismatic cell output, concentrating pricing power among integrated cathode producers while forcing modular assemblers toward thin-margin contract manufacturing. This scale asymmetry propagates through procurement negotiations in Texas and Germany, where buyers face take-it-or-leave-it terms on lithium iron phosphate supply or accept 8-12 month lead times from second-tier sources.
Pricing Analysis
The EU F-Gas Regulation dictates the pricing tier structure for data center UPS systems, separating liquid-cooled lithium-ion premiums from air-cooled standard configurations as thermal management compliance costs stratify. Certification grade under IEC 62619 and UL 9540A creates the primary price differentiation driver, with fire-safety-validated systems commanding substantial premiums over pre-certified alternatives. Pricing pressure stems from sodium-ion chemistry maturation as CATL scales prismatic output for stationary applications. Capital-constrained third-party logistics providers in the US Southeast exhibit the highest price sensitivity, while Frankfurt data center operators prioritize compliance certainty over unit cost.
Supply Chain Analysis
Inventory cycles for refined lithium hydroxide now stretch 14-18 months as cathode precursor output concentrates in China, South Korea, and Japan. Cell manufacturing draws from spodumene concentrate sourced through Australian hard-rock mining and Chilean brine evaporation, with cobalt hydroxide dependencies anchored in the DRC and Indonesian nickel laterite processing. Single-source vulnerability concentrates in Chinese lithium hydroxide refining, where export license protocols under MIIT guidelines expose non-domestic integrators to supply interruption. Distribution runs through integrator-led EPC contracts for grid-scale projects and OEM-direct channels for motive power fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial battery market is recovering from cathode material oversupply and lead-acid capacity rationalization, with lithium iron phosphate cost parity in motive power fleets providing the cyclical impetus for margin expansion.
For Market Incumbents: Shield lead-acid recycling margins by accelerating closed-loop network densification in North American forklift corridors before lithium-ion TCO parity fully arrives. Invest in captive lithium hydroxide processing partnerships or surrender grid-scale procurement leverage to CATL and Korean cell suppliers. Prioritize IEC 62619 certification breadth as a moat against modular assemblers lacking fire-safety validation capabilities. For New Entrants and Emerging Players: Anchor in India's CEA-mandated storage procurement, where 27 GW of grid-connected battery requirements by 2030 outstrips domestic assembly capacity and rewards early localizers in Gujarat manufacturing corridors. Target vanadium flow battery hybridization for South Australian six-to-twelve hour duration projects where lithium-ion degradation economics falter. Pursue battery-as-a-service leasing models to bypass capex-resistant mid-market buyers in German automotive supplier networks. For Investors and Strategic Acquirers: Closed-loop lead-acid recyclers with dense North American collection networks present acquisition targets with durable margin pools and regulatory moats under EPA Battery Act enforcement. Long-term viability hinges on lithium-ion manufacturing scale or chemistry diversification beyond lithium iron phosphate. Watch sodium-ion mass production ramp rates as the inflection signal for stationary application cost structures.| Strategic Initiative | Industry Significance |
|---|---|
| Cathode Material Backward Integration | Captive lithium hydroxide processing insulates margins from Chinese export license volatility under MIIT guidelines. |
| Flow Battery Hybrid Deployment | Vanadium-lithium architectures capture South Australian renewable integration projects exceeding six-hour duration. |
| Battery-as-a-Service Leasing | Unbundled cell ownership converts capex-resistant German logistics buyers to lithium-ion forklift adoption. |
| Fire Safety Certification Investment | UL 9540A validation unlocks Frankfurt data center procurement as EU F-Gas Regulation tightens thermal standards. |
| India Manufacturing Localization | Gujarat and Tamil Nadu assembly investments qualify for CEA storage mandates requiring domestic content. |
Study Parameters
A spread of perspectives from grid storage integrators, motive power fleet managers, cathode material procurement leads, and EPC contractors converged on the working assumptions for chemistry substitution timelines and recycling economics. Primary fieldwork with data center operators in Northern Virginia and Frankfurt supplemented secondary validation through EIA storage deployment databases, IEA renewable integration reports, FERC wholesale market rulemakings, and SEC filings from listed cell manufacturers. Bottom-up project pipelines triangulated against top-down capacity buildout forecasts across the analysis window.
Segmentation dimensions modeled include chemistry type, discharge duration tier, end-use vertical, and regional regulatory cluster, with value outputs derived from equipment procurement contracts and service agreement pricing. CAGRs reflect weighted averages of substitution rates in motive power, grid-scale deployment velocities, and flow battery penetration in long-duration applications. Forecast inputs incorporated lithium carbonate price volatility bands, sodium-ion production ramp schedules, and lead-acid recycling capacity utilization thresholds.
Decision-makers should treat outputs as directional under assumptions of continued lithium iron phosphate cost reduction and stable Chinese export licensing protocols; material deviation in cathode material trade policy or solid-state commercialization timelines would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Europe Industrial Battery Market
Batteries
Modular Battery Pack Market
Batteries
Redox Flow Battery Market
Batteries
Indonesia Battery Market
Batteries
Battery Swapping Market
Batteries
Europe Automotive Lead-Acid Battery Market
Batteries
Nickel-Metal Hydride (Ni-MH) Battery Market
Batteries
Tubular Batteries Market
Batteries
China Electric Vehicle Vrla Batteries Market
Batteries
Romania Rechargeable Battery Market
Batteries
Vanadium Redox Batteries Market
Batteries
Battery Diagnostics and Repair Market
Batteries
Power Battery Sealant Market
Batteries
Mobile Battery Market
Batteries
East Europe Battery Market
Batteries
Sweden Rechargeable Battery Market