
 Modular Battery Pack Market | 2026-2036
Modular Battery Pack Market Size, Share, and Industry Trends Forecast 2026-2036
Modular Battery Pack Market Insights
Subscription-based battery health monitoring and performance optimization software is shifting how modular pack vendors monetize hardware relationships. LG Energy Solution leverages its manufacturing scale to anchor long-term service contracts with European automakers. BYD Company Limited sustains vertical integration across cell-to-pack production, controlling cost structures that competitors struggle to match. Samsung SDI specializes in high-nickel chemistry configurations, positioning its modular offerings for premium electric vehicle segments.
A modular battery pack comprises standardized electrochemical cells arranged in interchangeable sub-units, typically featuring voltage ranges from 48V to 800V and integrated battery management systems enabling hot-swappable replacement. These architectures serve commercial and industrial applications requiring continuous uptime, from electric bus depots to grid-scale storage installations. Lithium-ion chemistry dominates current shipments due to mature supply chains and declining cell costs, though solid-state configurations represent the fastest-growing segment as manufacturers resolve manufacturing yield challenges. Electric vehicle applications command the largest revenue pool, while renewable energy storage is emerging as the highest-margin end-use as utility procurement shifts toward duration-flexible assets.
China's SAMR enforces GB standards for battery safety and recycling traceability, compelling redesign of modular interfaces to accommodate cell recovery. The EU's Battery Regulation mandates carbon footprint declarations and recycled content thresholds, reshaping material sourcing for packs sold in Europe. EMA guidelines on transport of dangerous goods influence packaging and interconnection designs for modular systems crossing borders. Stakeholders must monitor how divergent regional compliance timelines affect platform standardization strategies.
Market Dynamics
Swap-compatible battery architectures are forcing a fundamental redesign of pack interfaces, thermal management systems, and connector geometries as fleet operators demand sub-five-minute replacement cycles for commercial electric vehicles.
Growth Catalysts
- China's GB Standards:SAMR-mandated recycling traceability requirements are compelling modular designs that enable cell recovery, accelerating standardization of pack interfaces across domestic manufacturers.
- Bus Depot Electrification:Municipal transit authorities in Germany and the Netherlands are procuring hot-swappable systems to eliminate route downtime, creating pull-through demand for 800V architectures.
- Cell-to-Pack Elimination:Structural battery designs are removing redundant module housings, reducing pack weight and enabling higher volumetric energy density for commercial applications.
Market Restraints
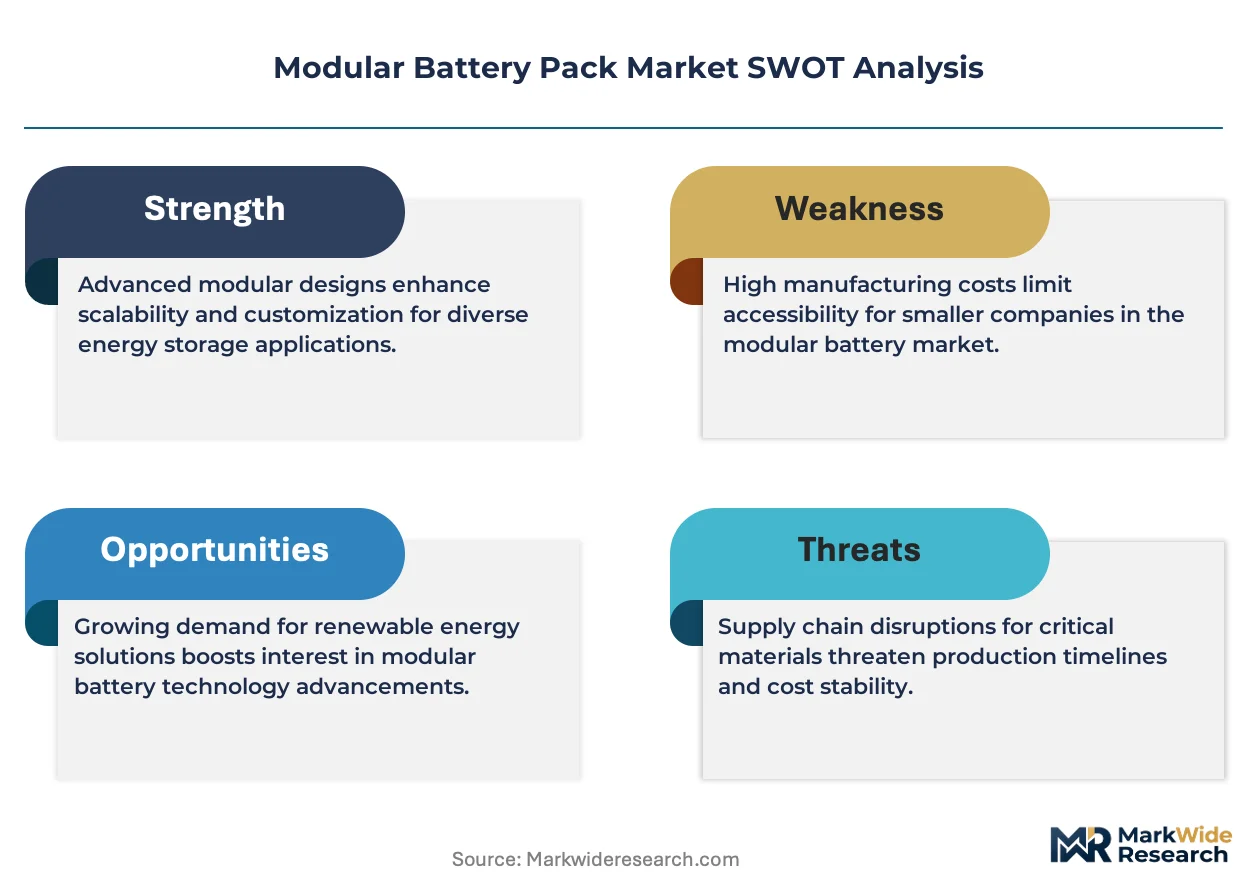
- Lithium Carbonate Volatility:Raw material price swings between Chinese spot markets and long-term Australian offtake contracts are compressing gross margins for pack assemblers lacking captive mining positions.
- Nickel Supply Concentration:Indonesian processing dominance and Philippine ore export restrictions are creating single-source vulnerability for high-nickel cathode chemistries favored in premium modular configurations.
- Solid-State Manufacturing Yields:Ceramic electrolyte sintering defects and dendrite suppression failures are limiting production scale, delaying commercial deployment of next-generation modular architectures.
Strategic Opportunities
- India's PLI Scheme:Production-linked incentives for advanced chemistry cell manufacturing are attracting modular pack investments targeting the country's two-wheeler and three-wheeler electrification wave.
- Grid-Scale Duration Flexibility:Utility procurement is shifting toward modular assets enabling 4-hour to 8-hour dispatch configurations, opening margin expansion beyond transportation applications.
- EU Battery Regulation:Carbon footprint declarations and recycled content mandates are creating first-mover advantage for pack vendors with established European recycling partnerships and low-carbon cell supply.
Industry Challenges
- Thermal Interface Standardization:Incompatible cooling plate geometries and coolant routing between OEM platforms are forcing pack vendors to maintain multiple SKUs, eroding scale economies.
- Functional Safety Certification:ISO 26262 ASIL-D compliance timelines for battery management systems are extending program schedules by 12-18 months, delaying platform launches.
- Legacy Fleet Retrofit Complexity:First-generation electric commercial vehicles with proprietary pack formats resist modular upgrades, stranding capital and slowing circular economy adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Modular Battery Pack Market |
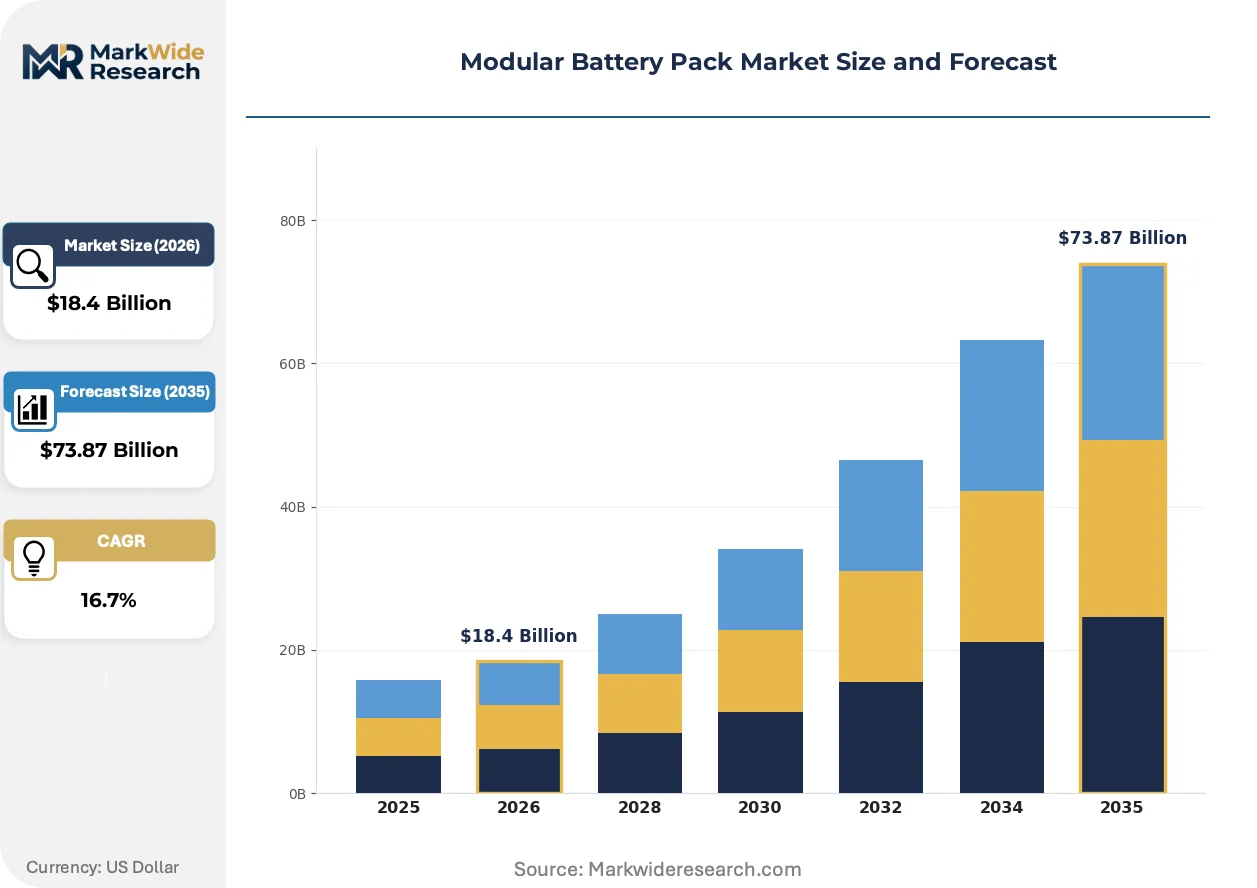
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $73.87 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Nickel Metal Hydride, Lead Acid, Solid-state Application: Electric Vehicles, Renewable Energy Storage, Consumer Electronics, Industrial Equipment End User: Aerospace, Automotive, Telecommunications, Residential Configuration: Stackable, Rack-mounted, Modular, Integrated |
| Companies Covered | Contemporary Amperex Technology Co., Limited (CATL), LG Energy Solution, BYD Company Limited, Panasonic Corporation, Samsung SDI, Tesla, A123 Systems LLC, EnerSys, Saft Groupe S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Modular Battery Pack Market Trends and Innovations
Wireless battery management systems and predictive degradation algorithms are eliminating physical wiring harnesses while enabling condition-based swap scheduling, fundamentally altering how modular packs interface with vehicle platforms.
Solid-state lithium-metal configurations with sulfide-based electrolytes are rewriting the energy density ceiling for modular architectures. Premium electric vehicle platforms from German and South Korean OEMs are piloting these cells in 2025 model year programs. The technology is compressing pack volume requirements by eliminating liquid electrolyte containment, enabling flatter floor pans and expanded cabin space.
The EU's Battery Regulation mandates carbon footprint declarations at the pack level, with recycled content thresholds escalating through 2031. Cell manufacturers must document supply chain emissions from mining through assembly, reshaping material sourcing for European-bound production. High-nickel cathode suppliers are accelerating Indonesian hydro-powered processing investments to meet incoming carbon intensity limits.
Fleet operators are unbundling hardware ownership from energy service, subscribing to battery-as-a-service models that transfer degradation risk to pack vendors. Commercial vehicle lessors in the Netherlands and California are piloting per-kilometer pricing structures, displacing upfront capital expenditure with operational expense treatment. This shift concentrates buyer power among large fleet aggregators, pressuring vendor margins and service capability requirements.
Modular Battery Pack Market Segmentation
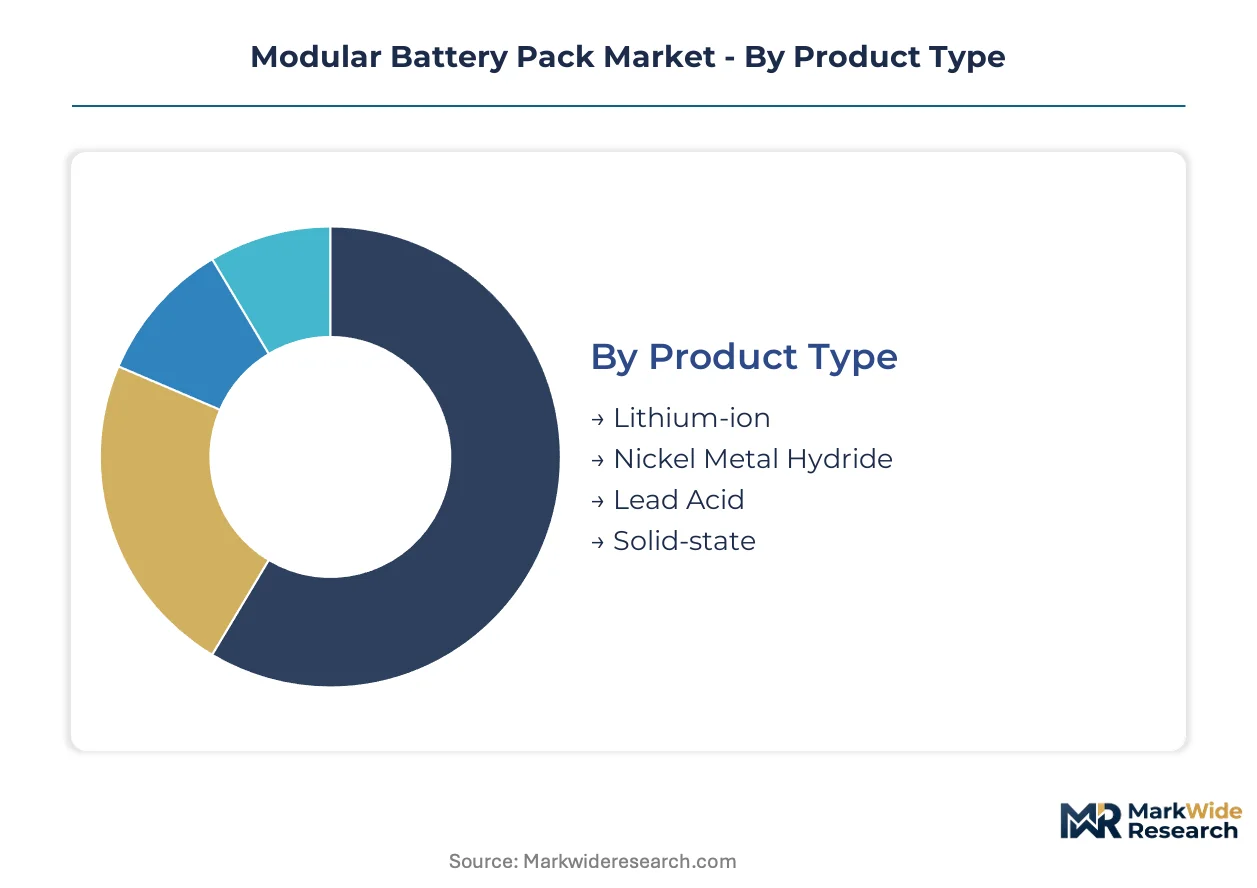
Modular battery pack architectures fragment across electrochemical technologies, deployment contexts, and physical integration depths. Each segmentation layer reveals distinct margin structures and standardization pressures that reshape vendor competitive positioning.
Product Type:
Integration depth varies sharply across chemistries, with standalone swap systems favoring mature formats while embedded platforms drive next-generation adoption.
- Lithium-ion:NMC and LFP cell configurations dominate current production volumes through established gigafactory supply chains. Fleet operators in Germany and the Netherlands specify these packs for 800V bus depot electrification programs where hot-swap compatibility eliminates route downtime.
- Solid-state:Sulfide-based electrolyte architectures eliminate liquid containment, enabling volumetric compression for premium electric vehicle floor pans. South Korean and German OEM pilot programs are validating ceramic sintering yields before commercial scaling.
- Nickel Metal Hydride:Toyota's hybrid vehicle programs sustain residual demand for NiMH modules in mild-hybrid configurations where cost sensitivity outweighs energy density requirements.
- Lead Acid:Stationary backup applications in telecommunications infrastructure retain lead-acid modularity where capital constraints override cycle life considerations.
Volume placements concentrate in Lithium-ion; the faster expansion belongs to Solid-state.
Application:
Cost tier stratification separates transportation hardware from stationary assets, with renewable storage commanding premium pricing for duration flexibility.
- Electric Vehicles:Commercial bus and truck fleets drive swap-compatible procurement, with California and Netherlands operators subscribing to battery-as-a-service models that transfer degradation risk to vendors.
- Renewable Energy Storage:Utility procurement shifts toward 4-hour to 8-hour dispatch configurations, opening margin expansion through modular duration stacking that transportation applications cannot match.
- Consumer Electronics:Power tool and e-bike segments demand standardized 48V-72V packs with cross-brand compatibility, pressuring interface standardization through China's GB standards enforcement.
- Industrial Equipment:Forklift and material handling fleets in German logistics hubs specify IP67-rated modular systems for continuous-shift operations without charging intervals.
Revenue pools concentrate in Electric Vehicles; margin expansion centers on Renewable Energy Storage.
End User:
Customer type fragmentation separates regulated safety-critical applications from price-sensitive mass markets, with certification requirements dictating vendor qualification barriers.
- Automotive:OEM platform integration demands ASIL-D functional safety compliance, extending battery management system development timelines by 12-18 months for modular architectures.
- Aerospace:FAA and EASA certification requirements for aviation battery systems impose cell-level traceability mandates that favor suppliers with established aerospace quality systems.
- Telecommunications:Tower operators in India prioritize total cost of ownership over energy density, attracting PLI-supported domestic pack assembly for backup power applications.
- Residential:Home energy storage systems in Germany couple with solar installations, where modular expansion capability addresses variable household consumption patterns.
Procurement scale concentrates in Automotive; qualification complexity peaks in Aerospace.
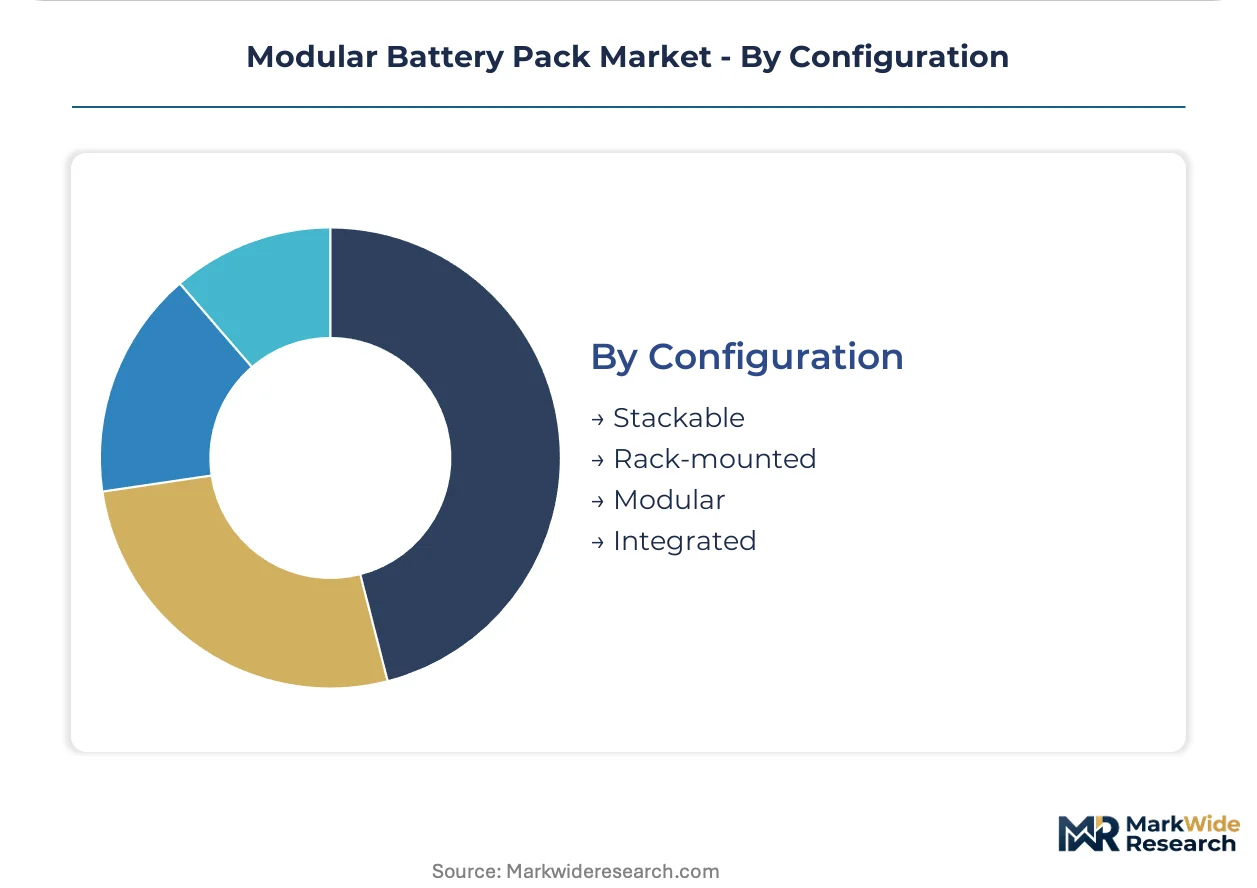
Configuration:
Physical form factor determines thermal management complexity and interchangeability economics, with rack-mounted systems dominating stationary applications.
- Stackable:Cube-shaped modules with standardized mechanical interfaces enable vertical scaling in containerized energy storage, prevalent in utility-scale deployments across Texas and Australian grid interconnection projects.
- Rack-mounted:19-inch industrial standard dimensions dominate data center and telecommunications backup installations, leveraging existing infrastructure footprints without structural modification.
- Modular:Vehicle-agnostic skateboard platforms with unified cooling plate geometries reduce SKU proliferation for pack vendors serving multiple OEM programs.
- Integrated:Structural battery designs eliminate module housings entirely, reducing pack weight for commercial vehicle applications where payload capacity directly determines operator economics.
Deployment density concentrates in Rack-mounted; structural innovation centers on Integrated.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of modular battery pack cells, while Germany and the United States absorb premium volumes for electric vehicle integration. This production-consumption divide shapes regional investment flows and regulatory responses.
China
CATL and BYD dominate cell production for swap-compatible bus and commercial vehicle fleets. SAMR-enforced GB standards for recycling traceability compel modular interface redesigns that accommodate cell recovery. Shenzhen and Ningbo industrial clusters host concentrated pack assembly operations serving domestic OEMs and export markets.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg integrate modular 800V architectures into next-generation electric platforms. KBA type-approval requirements for battery safety extend certification timelines for imported pack systems. Stuttgart and Munich anchor development partnerships between cell suppliers and vehicle manufacturers.
United States
California fleet operators pilot battery-as-a-service models for electric truck depots, transferring degradation risk to vendors. NHTSA safety standards and FERC grid interconnection rules influence pack designs for both transportation and stationary storage applications. Texas utility-scale projects drive demand for containerized modular systems.
South Korea
LG Energy Solution and Samsung SDI leverage domestic cathode and electrolyte supply chains for high-nickel modular configurations. MFDS industrial standards and METI-coordinated export protocols shape pack specifications for premium European automakers. Gyeonggi-do production complexes supply both domestic Hyundai-Kia platforms and external OEM programs.
India
PLI scheme incentives attract advanced chemistry cell investments targeting two-wheeler and three-wheeler electrification. CEA technical standards for battery storage safety create compliance barriers for imported modular systems. Tamil Nadu and Gujarat manufacturing corridors concentrate domestic pack assembly for telecom backup and electric mobility applications.
Modular Battery Pack Market Competitive Landscape
Top-tier vendors anchor high-volume cell-to-pack production, while mid-scale specialists occupy niche integration roles. The vendor base stratifies across three tiers: integrated cell manufacturers, independent pack assemblers, and software-enabled service providers. Dominant competitive moves include backward integration into cathode materials and strategic partnerships with fleet operators for battery-as-a-service deployment.
Within the integrated manufacturer tier, Contemporary Amperex Technology Co., Limited exemplifies scale-driven production archetypes, while LG Energy Solution occupies a position emphasizing long-term service contracting. BYD Company Limited anchors vertical control from mining through vehicle integration. These three entities represent divergent strategic postures: pure-play cell supply, hardware-service bundling, and captive consumption.
| Leading Market Players |
|---|
| Contemporary Amperex Technology Co., Limited (CATL) |
| LG Energy Solution |
| BYD Company Limited |
| Panasonic Corporation |
| Samsung SDI |
| Tesla |
| A123 Systems LLC |
| EnerSys |
| Saft Groupe S.A. |
| Others |
Pricing and Supply Chain Analysis
Lithium carbonate spot price volatility between Chinese commodity exchanges and Australian offtake contracts cascades through pack assembler margins, stratifying pricing tiers by captive mining access and contract duration.
Pricing Analysis
Margin tightening in standard lithium-ion configurations reflects raw material pass-through mechanics and contract renegotiation cycles. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D certified automotive programs from commercial fleet hardware and stationary backup systems. Cost compression accelerates in the commercial vehicle segment as battery-as-a-service models displace upfront procurement. Fleet aggregators in California and the Netherlands exhibit highest price sensitivity; aerospace qualification tiers demonstrate lowest.
Supply Chain Analysis
Single-source vulnerability sits with Indonesian nickel processing dominance for high-nickel cathode chemistries. Cell production concentrates in China, South Korea, and Japan; cathode active material draws from Indonesian hydro-powered facilities and Philippine ore exports. Raw material dependencies span lithium carbonate, nickel sulfate, and cobalt hydroxide. Tariff exposure on Chinese cell imports into Europe and the United States compounds logistics chokepoints through Red Sea routing. Distribution runs through OEM direct contracts, Tier 1 system integrators, and utility procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The modular battery pack market is consolidating around manufacturing scale and service capability, with GB standard compliance costs and solid-state R&D requirements forcing sub-scale assemblers toward exit.
For Market Incumbents: Acquire cathode material processing assets to secure nickel sulfate supply against Indonesian export restrictions. Lock in long-term offtake agreements with Australian spodumene producers before contract repricing cycles. Expand 800V platform certification capacity in Germany to capture KBA type-approval timelines that disadvantage import-dependent competitors. For New Entrants and Emerging Players: Solid-state electrolyte manufacturing yield improvement offers entry path around incumbent lithium-ion scale advantages. Target India's PLI-supported two-wheeler and three-wheeler electrification wave where domestic content requirements limit established Chinese suppliers. Pursue telecom tower backup power in Tamil Nadu and Gujarat through CEA compliance partnerships with local engineering firms. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale pack assemblers with established European recycling partnerships in Poland and Belgium. Long-term viability centers on carbon footprint declaration capability under escalating EU Battery Regulation thresholds. Watch solid-state ceramic sintering yield breakthroughs as inflection indicator for next-generation architecture deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Materials | Secures nickel sulfate supply against Indonesian processing concentration and export policy shifts. |
| Battery-as-a-Service Platform Launch | Transfers degradation risk to vendors while capturing recurring revenue from Netherlands and California fleet operators. |
| GB Standard Compliance Certification | Enables cell recovery interface designs mandatory for SAMR traceability requirements in Chinese markets. |
| Solid-State Manufacturing Scale-Up | Positions for premium electric vehicle programs from German and South Korean OEM pilot validation. |
| European Recycling Partnership Expansion | Meets EU Battery Regulation recycled content thresholds through established Polish and Belgian recovery networks. |
Research Methodology
Independent corroboration across OEM platform engineers, Tier 1 pack assembler procurement leads, and utility storage planners underwrites the qualitative findings. Primary fieldwork engaged battery management system developers, thermal interface designers, and fleet operator maintenance directors across Germany, China, and the United States. Secondary validation drew from SAMR GB standard filings, KBA type-approval documentation, EIA grid interconnection databases, and SEC disclosures from cell manufacturers. Bottom-up volume estimates triangulated against top-down addressable market calculations.
Historical reference periods anchored the projection horizon to pre-pandemic baselines and post-supply-shock recovery trajectories. The analytical framework modeled electrochemical technology, application segment, end-user certification tier, and physical configuration dimensions. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific inputs incorporated lithium carbonate price elasticity coefficients and solid-state manufacturing yield improvement curves.
Several conditions sit outside the modeled scope, including unannounced regulatory acceleration in carbon footprint thresholds and breakthrough ceramic electrolyte formulations. Forecasts reflect documented assumptions on raw material price stabilization and swap infrastructure deployment rates. Deviation in Indonesian nickel export policy or Chinese lithium carbonate spot market liquidity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Tubular Batteries Market
Batteries
Cylindrical Lithium Battery Winding Machine Market
Batteries
Iron Flow Battery Market
Batteries
United States SLI Battery Market
Batteries
Taiwan Battery Market
Batteries
Iron Salt Battery Market
Batteries
Bio Based Battery Market
Batteries
West Africa Battery Market
Batteries
Europe Battery Market
Batteries
PERC Battery Market
Batteries
High Voltage Air-cooled Battery Compartment Market
Batteries
AAA Battery Market
Batteries
Grid-Scale Lead-Acid Battery Market
Batteries
South America Battery Cell Market
Batteries
Europe Battery Cell Market
Batteries
Asia-Pacific Primary Battery Market