
 Industrial Lithium-Ion Batteries Market | 2026-2036
Industrial Lithium-Ion Batteries Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Lithium-Ion Batteries Market Insights
Grid energy storage operators is unwinding the long-standing dominance of telecommunications backup buyers in procurement priority. Contemporary Amperex Technology Co., Limited anchors its position through backward integration into cathode precursor production. LG Energy Solution differentiates via high-nickel NMC chemistry leadership for utility-scale installations. Samsung SDI competes on manufacturing scale across cylindrical and prismatic formats for industrial offtake.
Industrial lithium-ion batteries are rechargeable electrochemical cells employing lithium iron phosphate, nickel manganese cobalt, or lithium titanate oxide chemistries in formats ranging from 18650 cylindrical to large-format prismatic cells exceeding 200 Ah capacity, engineered for cycle lives above 4,000 charge-discharge events in temperatures from minus 20 to 55 degrees Celsius. These systems store and dispatch electrical energy for heavy-duty applications where lead-acid or nickel-metal hydride technologies fail on energy density or operational lifespan. Prismatic cells capture the dominant share of manufacturing and energy storage end-user demand due to superior volumetric efficiency in rack-mounted configurations. LFP chemistry leads technology segmentation on thermal stability and cost structure, though NMC retains margin concentration in premium automotive OEM supply agreements.
China's MIIT enforces GB standards for cell safety and recycling traceability that determine market access for domestic and imported battery systems. The EU Battery Regulation mandates carbon footprint disclosure and recycled content quotas that reshape supply chain qualification for European energy storage tenders. OSHA and NFPA codes in the United States govern thermal runaway containment in warehouse and utility installations, driving fire suppression integration in battery system design. Stakeholders must monitor chemistry-specific regulatory divergence across jurisdictions when configuring product portfolios for cross-border industrial sales.
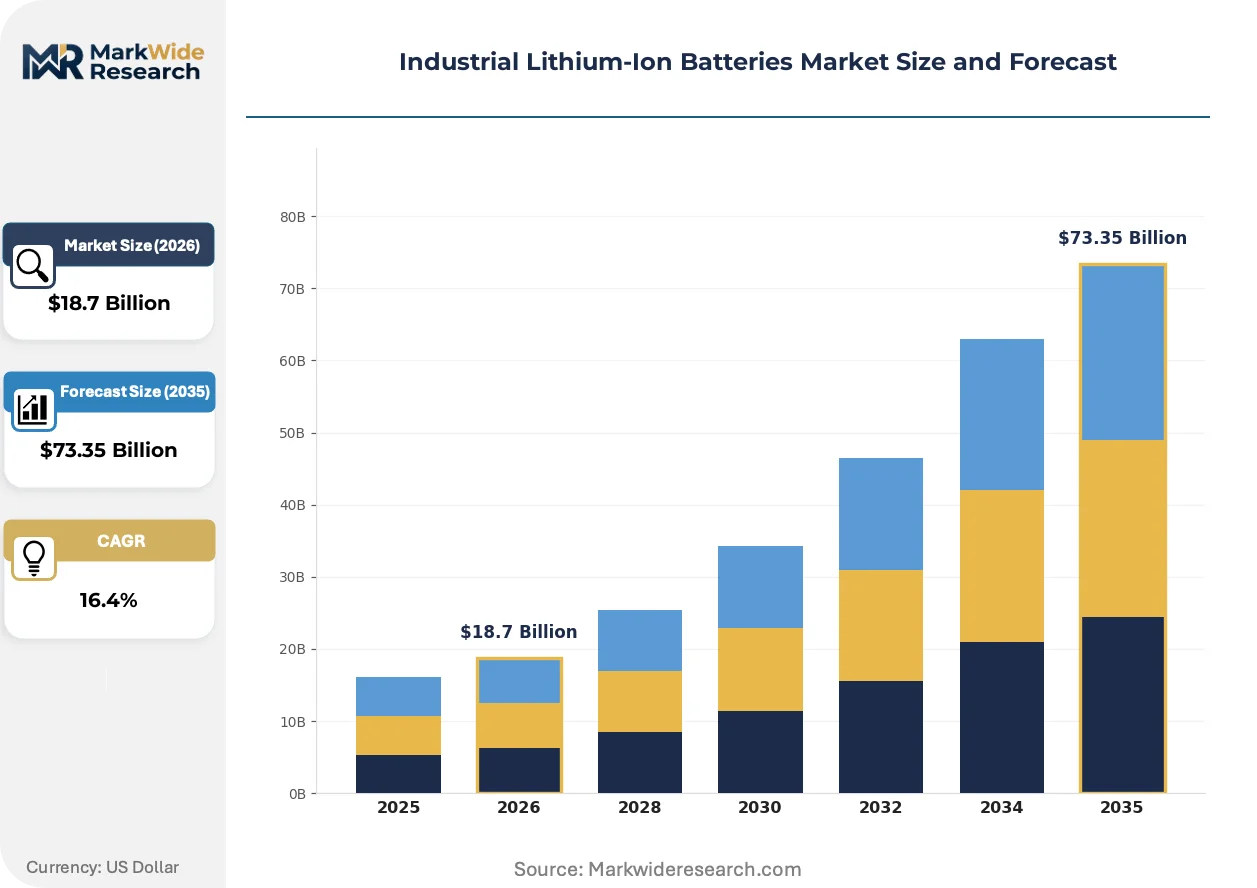
Market Dynamics
Grid energy storage operators are displacing telecommunications backup systems as the dominant procurement force, rewiring manufacturing priorities toward utility-scale cell formats and cycle-life specifications that diverge sharply from legacy backup power requirements.
Growth Catalysts
- EU Battery Regulation mandates:Carbon footprint disclosure and recycled content quotas are forcing supply chain requalification for European energy storage tenders, creating first-mover advantages for compliant producers.
- Jiangsu and Guangdong province clustering:Gigafactory concentration around CATL and BYD operations generates supplier ecosystem density that compresses procurement lead times and logistics costs for domestic offtake.
- LFP chemistry thermal stability:Lithium iron phosphate formulations eliminate thermal runaway risks that plague high-nickel alternatives, opening deployment in densely populated industrial zones with restrictive fire codes.
Market Restraints
- Cobalt and nickel price volatility:NMC cathode input costs swing with Indonesian nickel export policies and DRC cobalt supply disruptions, eroding margin predictability for chemistry-locked producers.
- Prismatic cell equipment concentration:Winding and stacking machinery for large-format cells sources primarily from German and Japanese equipment makers, creating capex bottlenecks for new entrants.
- GB standards compliance timelines:China's MIIT certification processes for cell-grade safety and recycling traceability extend qualification cycles by 8-14 months for non-domestic suppliers.
Strategic Opportunities
- India CEA storage mandates:Central Electricity Authority regulations requiring 4-hour battery backup for renewable integration create procurement pull from state distribution companies with limited incumbent supplier relationships.
- Second-life automotive pack repurposing:Retired EV batteries with 70-80% residual capacity are converging with industrial stationary storage applications, opening feedstock arbitrage for pack aggregators.
- Direct-to-utility channel development:Bypassing traditional distributor networks for grid-scale tenders captures margin pools previously allocated to electrical wholesale intermediaries.
Industry Challenges
- Battery management system firmware integration:Utility-scale deployments require proprietary communication protocols with SCADA and energy management platforms, extending commissioning timelines and technical support burdens.
- Thermal runaway containment engineering:NFPA 855 and OSHA warehouse installation codes mandate gas detection, suppression, and ventilation systems that add 12-18% to system-level bills of materials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Lithium-Ion Batteries Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prismatic, Cylindrical, Coin, Pouch End User: Manufacturing, Automotive OEMs, Energy Storage, Telecommunications Technology: LFP, NMC, NCA, LTO Application: Grid Energy Storage, Uninterruptible Power Supply, Electric Vehicles, Drones |
| Companies Covered | Contemporary Amperex Technology Co., Limited., LG Energy Solution, Panasonic Holdings Corporation, BYD Company Limited, Samsung SDI, SK On Co., Ltd., AESC, CALB Co., Ltd., Gotion High-Tech Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Lithium-Ion Batteries Market Trends and Innovations
Cell format standardization and chemistry diversification are compressing equipment amortization cycles while opening new application vectors beyond traditional industrial backup power.
Solid-state electrolyte development is miniaturizing thermal management hardware requirements. Grid operators in Germany and California are piloting sulfide-based cells that eliminate liquid electrolyte cooling loops. This architecture is compressing system footprint by 30-40% in containerized installations where space premiums dominate site economics.
China's GB standards for cell safety and recycling traceability are tightening product qualification thresholds. MIIT enforcement of batch-level serialization and end-of-life tracking is fragmenting supplier pools into certified and non-certified tiers. European energy storage tenders now exclude non-compliant bids, compressing addressable market share for uncertified producers.
Long-term service agreements are bundling cell replacement and performance guarantees into upfront pricing. Industrial offtakers in Texas and Australia are accepting 15-year all-in contracts that transfer degradation risk to manufacturers. This structure is displacing traditional equipment-plus-maintenance procurement in markets with high cost-of-capital for balance-sheet battery ownership.
Industrial Lithium-Ion Batteries Market Segmentation
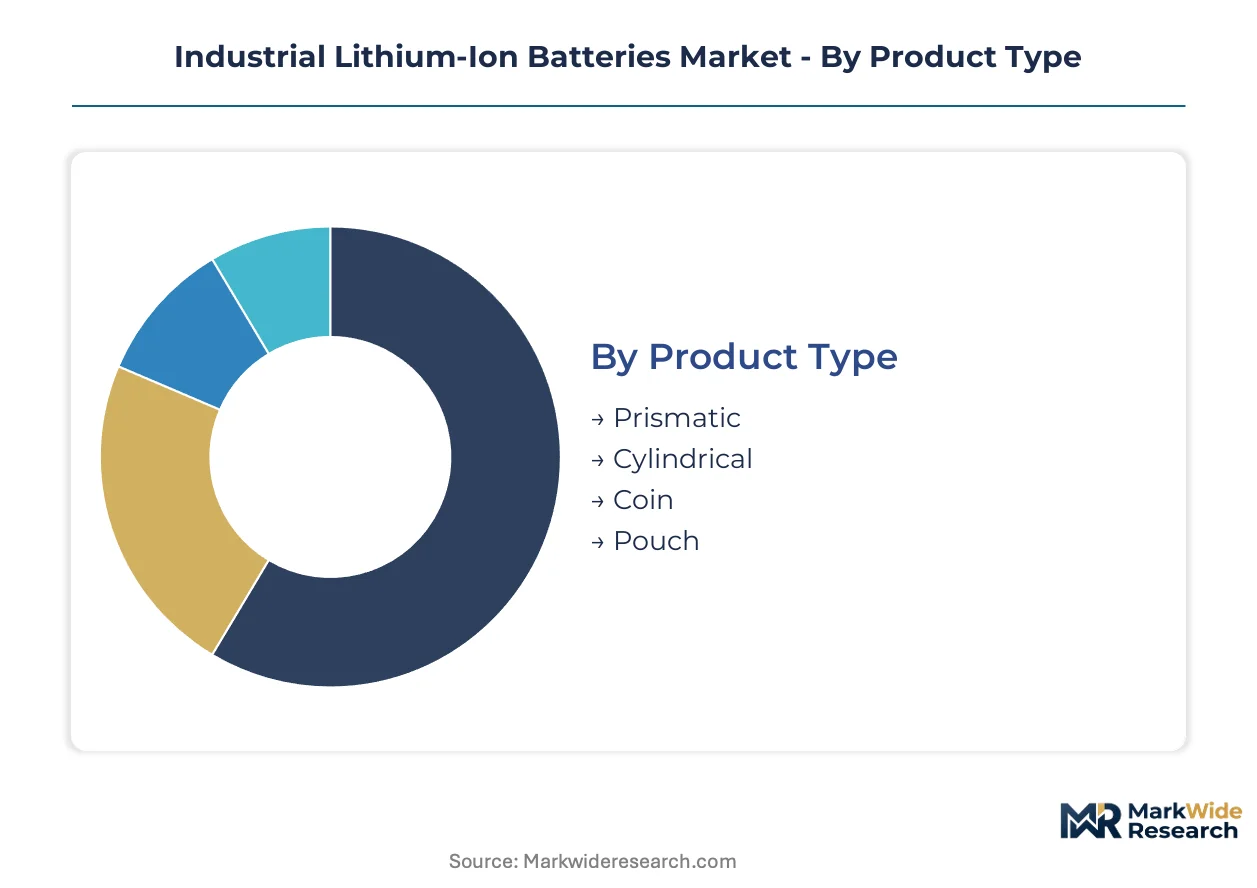
Industrial lithium-ion batteries fragment across four intersecting dimensions that determine procurement specifications, margin structures, and geographic addressability. Cell format and chemistry selection cascade through system design, while end-use applications impose divergent cycle-life and thermal tolerance requirements.
Product Type:
Prismatic cells dominate domestic Chinese procurement through CATL and BYD gigafactory output, while cylindrical formats retain export strength for industrial tool and drone applications.
- Prismatic:Stacked electrode architecture delivers volumetric efficiency above 90% in rack-mounted energy storage configurations. Jiangsu and Guangdong province demand concentrates here for grid-scale deployments requiring 200+ Ah single-cell capacity.
- Cylindrical:Wound jellyroll construction withstands mechanical stress in vibration-heavy industrial environments. German and Japanese equipment makers supply the winding machinery that constrains new entrant capacity expansion.
- Coin:Compact form factor suits embedded sensor networks and industrial IoT edge devices with sub-1 Ah capacity requirements.
- Pouch:Flexible aluminum-laminate housing enables custom footprint optimization for space-constrained drone and robotics applications.
Prismatic commands the established base. The steepest expansion runs through cylindrical formats for industrial mobility equipment.
End User:
Cost tier differentiation separates premium automotive OEM supply agreements from price-sensitive telecommunications backup procurement.
- Manufacturing:Forklift electrification and automated guided vehicle fleets drive 8-12 hour continuous discharge requirements. German industrial OEMs specify LFP chemistry for warehouse fire code compliance.
- Automotive OEMs:Cell-to-pack integration demands sub-2 mm thickness tolerance and 10-year warranty backing. NMC chemistry retains margin concentration despite raw material volatility from Indonesian nickel policy shifts.
- Energy Storage:Utility-scale tenders in Texas and Australia now accept 15-year all-in service contracts transferring degradation risk to manufacturers.
- Telecommunications:Legacy backup power applications face procurement priority displacement as grid operators capture manufacturing capacity.
Telecommunications commands the established base. The steepest expansion runs through energy storage operators.
Technology:
Application requirements dictate chemistry selection, with thermal stability and nickel price exposure driving divergent adoption patterns.
- LFP:Lithium iron phosphate eliminates cobalt dependency and thermal runaway risks. China's MIIT GB standards favor this chemistry for densely populated industrial zones with restrictive NFPA fire codes.
- NMC:Nickel manganese cobalt delivers energy density above 250 Wh/kg for premium automotive and aerospace applications. DRC cobalt supply disruptions and Indonesian nickel export policies erode margin predictability.
- NCA:Nickel cobalt aluminum serves high-discharge-rate power tools and performance electric vehicles.
- LTO:Lithium titanate oxide enables 10,000+ cycle life for frequency regulation and fast-charging industrial equipment.
LFP commands the established base. The steepest expansion runs through LTO for grid frequency regulation services.
Application:
Customer type segmentation reveals divergent procurement channels, with direct-to-utility tenders bypassing traditional electrical wholesale intermediaries.
- Grid Energy Storage:Containerized installations require SCADA protocol integration and 4-hour discharge duration. India's CEA mandates are creating procurement pull from state distribution companies with limited incumbent relationships.
- Uninterruptible Power Supply:Data center operators specify 15-minute to 2-hour backup duration with 99.999% availability guarantees.
- Electric Vehicles:Second-life automotive packs with 70-80% residual capacity are converging with stationary storage applications.
- Drones:Energy density optimization above 300 Wh/kg drives pouch and cylindrical cell selection for extended flight duration.
Uninterruptible Power Supply commands the established base. The steepest expansion runs through grid energy storage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese gigafactory output in Jiangsu and Guangdong provinces supplies the majority of prismatic cell capacity, while German equipment makers constrain winding machinery availability for new entrants worldwide.
United States
Texas and California utility-scale tenders drive procurement for 4-hour duration grid storage systems. OSHA and NFPA 855 codes mandate thermal runaway containment hardware that adds system-level cost. Houston and Austin clusters host containerized installation engineering for ERCOT frequency regulation services.
China
CATL and BYD gigafactory complexes in Jiangsu and Guangdong provinces dominate prismatic cell output for domestic energy storage. MIIT enforces GB standards for cell-grade safety certification and recycling traceability that extend qualification timelines. Ningde and Shenzhen anchor cathode precursor backward integration and pack assembly operations.
Germany
Grid operators pilot solid-state sulfide-based cells that eliminate liquid electrolyte cooling loops in containerized configurations. ECHA REACH compliance and EU Battery Regulation carbon footprint disclosure reshape supply chain qualification. Stuttgart and Munich industrial zones concentrate automotive OEM cell-to-pack integration engineering.
India
CEA mandates for 4-hour battery backup at renewable integration sites create procurement pull from state distribution companies. BIS certification requirements and PLI scheme incentives attract domestic manufacturing investment. Gujarat and Tamil Nadu states host emerging pack assembly operations for industrial and utility offtake.
Australia
Grid-scale tenders in Victoria and Queensland accept 15-year all-in service contracts transferring degradation risk to manufacturers. Frequency regulation and renewable firming applications drive LTO chemistry procurement for 10,000+ cycle life specifications. Melbourne and Sydney engineering clusters specialize in SCADA protocol integration for utility deployments.
Industrial Lithium-Ion Batteries Market Competitive Landscape
Concentration sits with vertically integrated cell manufacturers possessing captive cathode precursor supply and gigafactory scale. The vendor base stratifies into three tiers: integrated chemistry-to-system producers, format-specialized fabricators, and regional pack assemblers. Dominant competitive moves include backward integration into mining and precursor production, plus direct-to-utility channel development bypassing electrical wholesale intermediaries.
Among Asia-Pacific integrated producers, Contemporary Amperex Technology Co., Limited and BYD Company Limited exemplify the chemistry-to-system archetype through in-house cathode production and gigafactory concentration in Jiangsu and Guangdong provinces. LG Energy Solution and Samsung SDI represent the premium-tier format diversification strategy spanning cylindrical and prismatic configurations. These named entities anchor competitive positioning without constraining the addressable market for specialized entrants.
| Leading Market Players |
|---|
| Contemporary Amperex Technology Co., Limited. |
| LG Energy Solution |
| Panasonic Holdings Corporation |
| BYD Company Limited |
| Samsung SDI |
| SK On Co., Ltd. |
| AESC |
| CALB Co., Ltd. |
| Gotion High-Tech Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
LFP chemistry substitution for NMC formulations is compressing cathode input costs while redrawing supplier geography toward Jiangsu and Guangdong province producers with captive iron phosphate supply. This input shift simultaneously erodes nickel-cobalt price exposure and concentrates pricing power among vertically integrated domestic Chinese manufacturers.
Pricing Analysis
China's MIIT GB standards dictate the pricing tier structure across certified and non-certified supplier pools. Three-tier pricing structure across premium, standard, and economy levels separates UL-listed systems for US utility tenders from uncertified domestic Chinese offtake. Cost compression in standard-tier prismatic cells is intensifying because German and Japanese equipment makers constrain winding machinery availability. Telecommunications backup buyers exhibit highest price sensitivity; grid energy storage operators accept premium pricing for 15-year performance guarantees.
Supply Chain Analysis
Inventory cycles for prismatic cell winding equipment now stretch 14-18 months, compressing new entrant capacity timelines. Manufacturing gravity centers on China, South Korea, and Japan for electrode coating and cell assembly operations. The chain draws from Indonesian nickel, DRC cobalt, and Chilean lithium for NMC cathode precursors. Single-source vulnerability in German stacking machinery creates capex bottlenecks. Distribution runs through direct-to-utility channels for grid-scale tenders and electrical wholesale intermediaries for industrial backup applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of certified cell-grade production capability combined with extended MIIT qualification timelines is fragmenting competitive access. Manufacturers possessing in-house cathode precursor operations and gigafactory scale command disproportionate pricing leverage.
For Market Incumbents: Compound backward integration into lithium refining and cathode precursor production to defend against Indonesian nickel policy volatility. Secure direct-to-utility channel relationships in Texas and Australia to capture margin pools from electrical wholesale intermediaries. Lock in long-term offtake agreements with Jiangsu and Guangdong province equipment suppliers to constrain competitor capacity expansion. For New Entrants and Emerging Players: MIIT GB certification fast-track through joint venture partnerships with domestic Chinese pack assemblers opens procurement access to state distribution companies in India under CEA mandates. Target second-life automotive pack aggregation for stationary storage applications where residual capacity requirements lower technical barriers. Pursue cylindrical format specialization for industrial mobility equipment to bypass prismatic equipment bottlenecks. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale LFP specialists with pending UL certification and established relationships with German industrial OEMs. Five-to-ten-year viability hinges on chemistry diversification capability and regulatory compliance breadth across multiple jurisdictions. Watch for Indonesian nickel export policy shifts as inflection indicator for NMC margin compression and LFP acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Precursors | Captures margin from Indonesian nickel volatility and DRC cobalt supply disruptions. |
| Direct-to-Utility Channel Development | Bypasses electrical wholesale intermediaries in Texas and Australia grid-scale tenders. |
| MIIT GB Certification Investment | Opens procurement access to Chinese state distribution companies and European energy storage tenders. |
| Second-Life Pack Aggregation Capability | Sources retired EV batteries with 70-80% residual capacity for stationary storage arbitrage. |
| Solid-State Electrolyte Pilot Scale-Up | Eliminates liquid cooling loops for German and California grid operator containerized installations. |
Research Methodology
A standing panel of utility procurement officers, battery system integrators, cathode precursor plant managers, and MIIT certification consultants provided ongoing calibration across the analysis window. Primary interviews with grid operators in Texas and Australia, EPC contractors for containerized installations, and industrial OEM procurement teams in Germany were cross-referenced against customs data, SEC filings from listed battery producers, MIIT certification databases, and IEA energy storage deployment statistics. Bottom-up cell production estimates and top-down energy storage capacity installations were triangulated for consistency.
Outputs were validated against external benchmarks including IEA stationary storage deployment data and MIIT production statistics. The analytical framework modeled cell format, chemistry type, end-use application, and regional regulatory cluster across the projection horizon. CAGRs were derived from volume trajectory analysis incorporating gigafactory capacity announcements, equipment lead time constraints, and regulatory mandate implementation schedules. Industry-specific inputs included MIIT certification timeline data and Indonesian nickel export policy scenarios.
The analysis sits within stated boundaries; outcomes outside sustained LFP chemistry cost advantages or accelerated solid-state commercialization would require recalibration. Forecasts reflect documented assumptions regarding equipment availability, regulatory enforcement intensity, and raw material price trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Europe Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
High Temperature Lithium Battery Market
Lithium-ion Battery
Aluminium Ion Battery Market
Lithium-ion Battery
Lithium Battery Cells for Passenger Car Market
Lithium-ion Battery
Next-Generation Lithium Batteries Market
Lithium-ion Battery
Automotive 48V Lithium Battery Market
Lithium-ion Battery
21700 Lithium Battery Sales Market
Lithium-ion Battery
Manganese Dioxide Lithium Battery Market
Lithium-ion Battery
Lithium Battery Grade Lithium Carbonate Market
Lithium-ion Battery
Lithium-Ion Battery Anode Market
Lithium-ion Battery
Li-Ion Portable Battery Market
Lithium-ion Battery
Germany Electric Vehicle Battery Anode Market
Lithium-ion Battery
Global Rechargeable Poly Lithium-Ion Batteries Market
Lithium-ion Battery
Lithium Battery Wet Separator Market
Lithium-ion Battery
Cathode Material of Power Lithium Battery Market
Lithium-ion Battery
Automotive Lithium-Ion Battery Cell Market