
 Latin America Automotive Lead-Acid Battery Market | 2026-2036
Latin America Automotive Lead-Acid Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Automotive Lead-Acid Battery Market Intelligence
PROCONVE Phase L standards are restructuring the cost-of-entry calculus for battery suppliers serving Brazil's vehicle assembly sector. Exide Technologies leverages its regional manufacturing footprint to sustain pricing flexibility across Mercosur markets. Moura Accumulators anchors Brazilian aftermarket distribution through dense dealer networks. GS Yuasa Corporation competes on maintenance-free VRLA technology for premium passenger car fitments.
Latin America automotive lead-acid batteries are electrochemical storage devices employing lead dioxide positive plates, sponge lead negative plates, and sulfuric acid electrolyte, typically rated between 12V and 48V depending on vehicle class, designed to deliver cold cranking amperage for engine starting and stabilized voltage for onboard electronics. SLI products still dominate volume across the region, though AGM configurations capture margin pools from start-stop vehicle penetration in Mexico and Chile. Aftermarket Providers represent the largest end-user channel given fleet aging and tropical climate degradation rates, while OEM direct sales concentrate around Volkswagen, General Motors, and Nissan assembly plants.
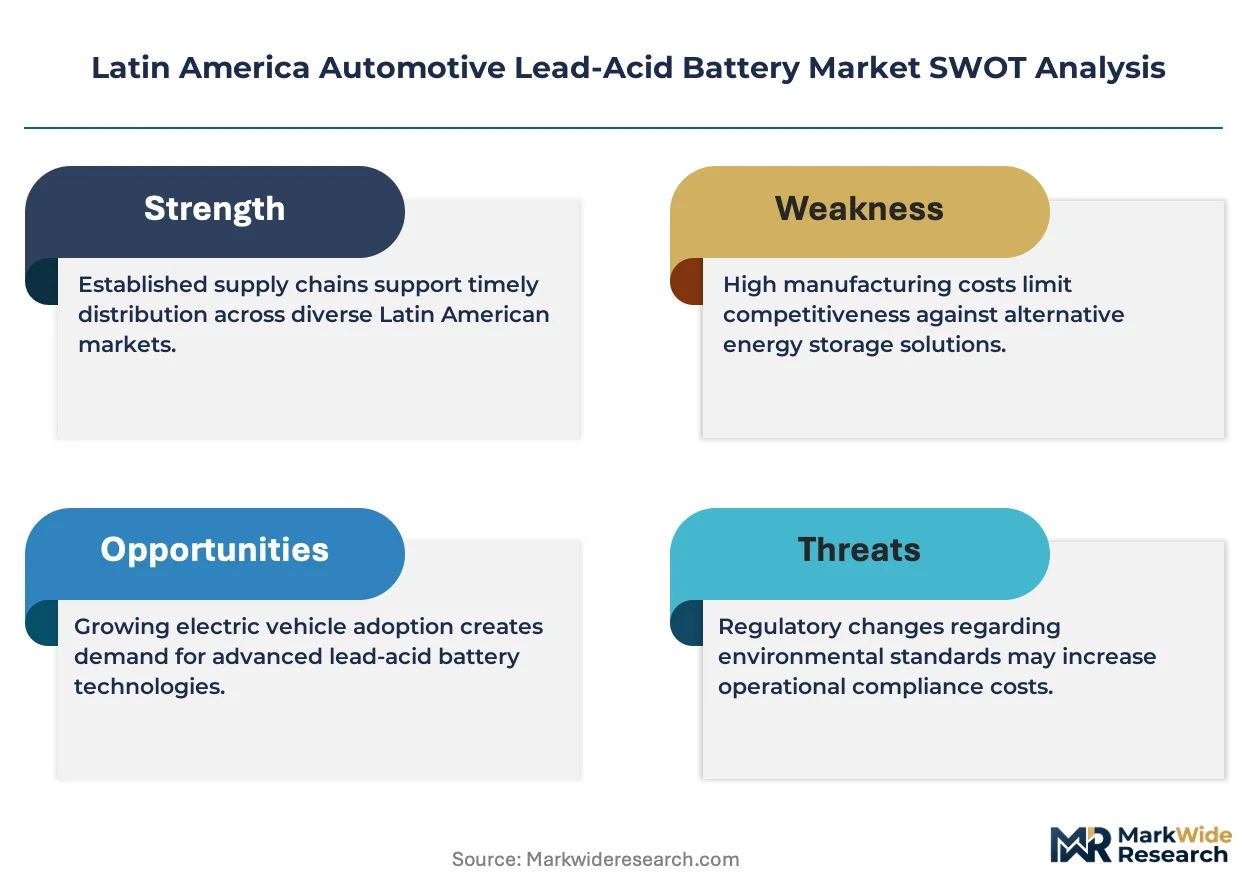
Brazil's PROCONVE framework and Mexico's NOM-163-SEMARNAT-2013 standards govern lead content thresholds and recycling obligations, forcing suppliers to certify closed-loop collection systems or face market exclusion. ANPACT commercial vehicle regulations in Mexico and Argentina's Secretariat of Environment and Sustainable Development battery directives further segment compliance requirements by country. Stakeholders must monitor divergence between Brazilian and Mexican regulatory timelines to avoid stranded inventory or duplicate certification investments.
Market Dynamics
Brazil's PROCONVE Phase L emission standards are forcing vehicle electrical system upgrades that expand battery capacity requirements across passenger and commercial fleets. This regulatory compression is accelerating replacement cycles and reshaping supplier qualification criteria.
Growth Catalysts
- PROCONVE Phase L Standards:Brazil's tightened emission framework mandates enhanced onboard electronics, expanding SLI battery specifications for cold cranking amperage and reserve capacity.
- Commercial Fleet Expansion:ANPACT-regulated heavy-duty vehicle operators across Mexico are compressing preventive maintenance intervals, driving aftermarket volume through authorized service channels.
- AGM Technology Penetration:Start-stop vehicle configurations in Mexico's automotive manufacturing corridor near Querétaro are absorbing maintenance-free VRLA batteries for vibration resistance and cycle durability.
Market Restraints
- Lead Price Volatility:Raw material input costs for lead dioxide and sponge lead plates fluctuate with London Metal Exchange pricing, compressing margin buffers for regional assemblers.
- Recycling Infrastructure Concentration:Closed-loop collection systems for sulfuric acid electrolyte recovery concentrate in São Paulo and Mexico City industrial zones, leaving peripheral markets underserved.
- Lithium-Ion Substitution Threat:Mild-hybrid vehicle architectures in Chilean and Argentine premium segments are piloting 48V lithium-ion systems for weight reduction and energy density gains.
Strategic Opportunities
- Colombian Aftermarket White Space:Bogotá and Medellín fleet operators lack dense authorized distributor networks, creating channel expansion potential for certified battery suppliers.
- Reverse Logistics Innovation:Digital tracking platforms for core battery returns are emerging in Brazil's Mercosur trade zone, enabling deposit-refund compliance with PROCONVE recycling mandates.
- Argentina Rural Electrification:Provincial agricultural machinery fleets in Córdoba and Santa Fe provinces remain underpenetrated by maintenance-free VRLA products designed for extreme temperature cycling.
Industry Challenges
- Certification Timeline Compression:Divergent PROCONVE and NOM-163-SEMARNAT-2013 testing protocols force duplicate laboratory investments for suppliers serving both Brazil and Mexico.
- Technical Workforce Scarcity:Battery diagnostics for start-stop system integration requires specialized training that regional vocational programs have not scaled to meet.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Automotive Lead-Acid Battery Market |
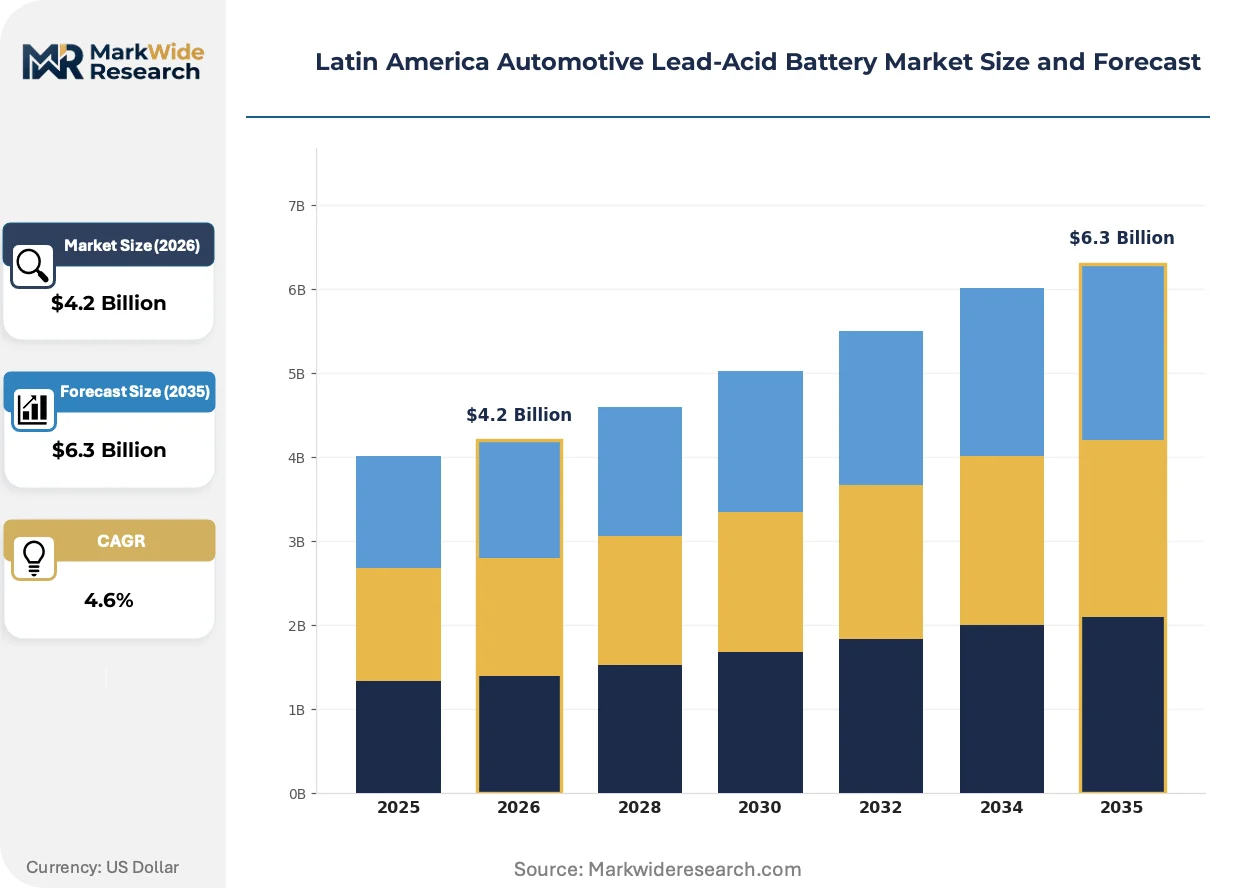
| Market Size in 2026 | $4.2 Billion |
| Market Size in 2035 | $6.3 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SLI, AGM, Gel, Deep Cycle End User: OEMs, Aftermarket Providers, Commercial Vehicles, Passenger Cars Technology: Flooded, VRLA, Maintenance-Free, Absorbent Glass Mat Sales Channel: Retail, Distributors, Online, Direct Sales |
| Companies Covered | East Penn Manufacturing Company, GS Yuasa Corporation, Exide Technologies, CSB Battery, C&D Technologies, Johnson Controls, Enersys, Hitachi Chemical Energy Technology, Moura Accumulators, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Automotive Lead-Acid Battery Market Strategic Shifts & Innovations
Electrification requirements are reshaping battery architecture across Latin American vehicle assembly. Suppliers are reconfiguring product portfolios around enhanced cycling performance and regulatory compliance automation.
Absorbent Glass Mat configurations are absorbing the technical demands of start-stop engine systems by delivering superior vibration resistance and deep-cycle durability. Mexican OEM assembly plants near Puebla are specifying AGM fitments for compact car platforms at accelerating rates. This technology is absorbing margin pools previously captured by conventional flooded lead-acid designs in the premium passenger segment.
ANVISA-equivalent environmental regulators across Brazil and Mexico are tightening lead content disclosure and end-of-life tracking requirements under harmonized Mercosur directives. Industrial consequence includes mandatory digital chain-of-custody documentation for smelter-bound battery cores. Aftermarket distributors in São Paulo industrial suburbs are deploying barcode-based collection systems to satisfy audit trails.
Fleet procurement teams are consolidating supplier relationships around single-source agreements with integrated recycling commitments. Authorized dealer networks are displacing fragmented independent retailers for commercial vehicle battery replacement. This concentration is most visible in Brazil's long-haul trucking corridors connecting Santos port facilities to interior agricultural processing centers.
Latin America Automotive Lead-Acid Battery Market Segmentation
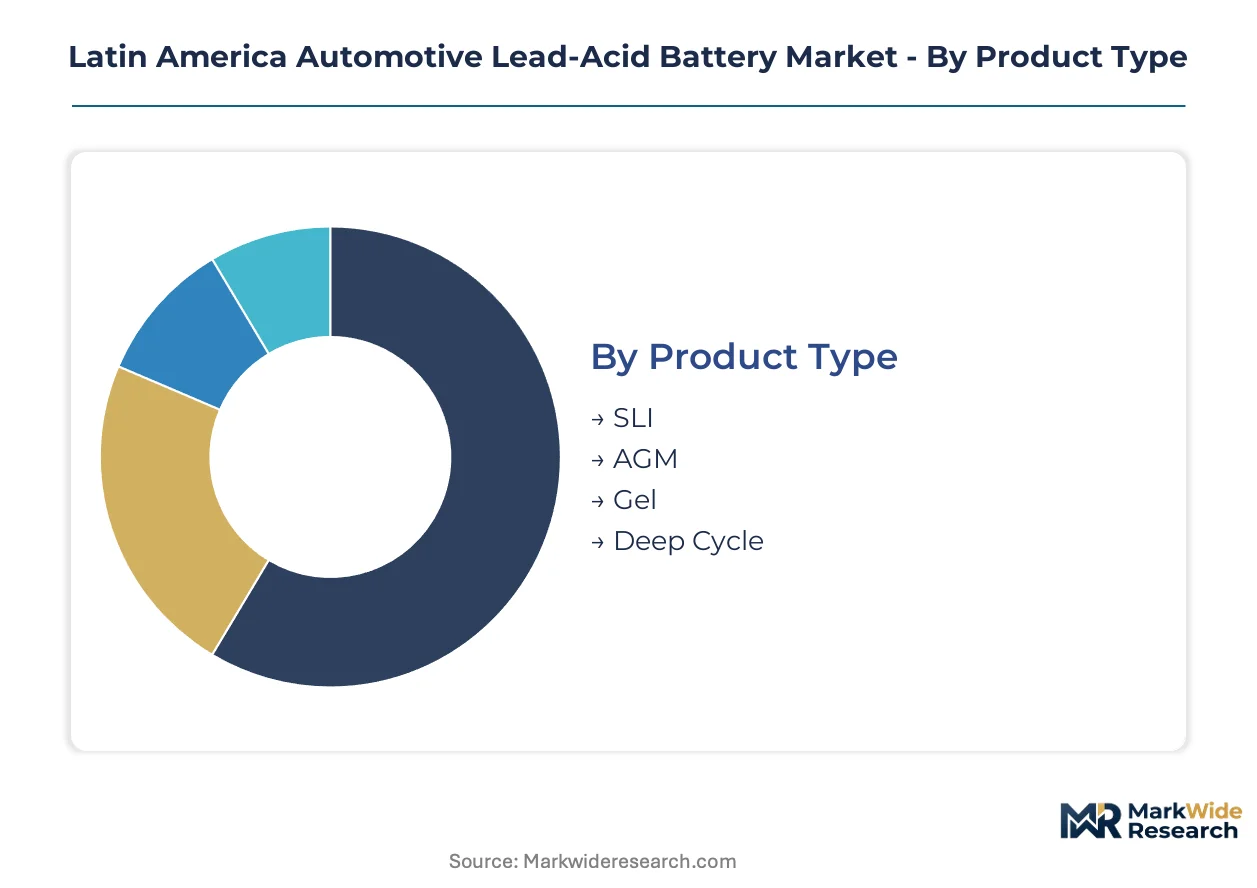
Segmentation across Latin America's automotive lead-acid battery market reveals how regulatory divergence and vehicle electrification reshape procurement priorities. Understanding these category boundaries exposes where margin pools concentrate and where suppliers must adapt technical specifications.
Product Type:
Standardization dominates entry-level fitments while customization intensifies for start-stop and heavy-duty cycling applications.
- SLI:Flooded lead-acid construction with calcium-calcium or calcium-silver grids delivers cold cranking amperage for conventional internal combustion engines. Brazilian passenger car assembly lines near São Paulo absorb the majority of regional SLI volume under PROCONVE Phase L electrical load requirements.
- AGM:Absorbent glass mat separators immobilize electrolyte for superior vibration resistance and deep-cycle recovery. Mexican OEM plants in Querétaro specify AGM configurations for compact car start-stop systems, capturing premium pricing over flooded alternatives.
- Gel:Silica-thickened electrolyte eliminates stratification for extreme temperature tolerance. Argentine agricultural machinery operators in Córdoba province specify gel batteries for seasonal equipment storage.
- Deep Cycle:Thicker lead plates sustain repeated discharge-recharge sequences without capacity degradation. Colombian commercial fleet operators deploy deep cycle units for auxiliary power in long-haul trucking refrigeration systems.
Leading the category by volume: SLI. Growing fastest: AGM.
End User:
Cost tier stratification separates price-sensitive aftermarket replacement from specification-locked OEM procurement.
- OEMs:Volkswagen, General Motors, and Nissan assembly plants in Puebla and São Paulo impose qualification protocols demanding traceable manufacturing documentation and warranty-backed cycle life guarantees.
- Aftermarket Providers:Dense authorized dealer networks across Brazil's Mercosur trade zone handle warranty replacements and preventive maintenance for aging fleet vehicles. Tropical climate degradation accelerates replacement frequency versus temperate markets.
- Commercial Vehicles:ANPACT-regulated heavy-duty operators compress maintenance intervals to minimize downtime across Mexico's freight corridors connecting Lázaro Cárdenas port to Mexico City industrial zones.
- Passenger Cars:Individual vehicle owners in Santiago and Buenos Aires prioritize maintenance-free configurations for reduced service complexity in urban stop-and-go traffic patterns.
Dominating revenue contribution: Aftermarket Providers. Expanding most quickly: Commercial Vehicles.
Technology:
Volume concentrates in mature flooded designs while margin migrates toward valve-regulated architectures.
- Flooded:Conventional liquid electrolyte systems with removable caps for periodic water replenishment. Brazilian budget passenger vehicle segments retain flooded fitments for initial cost minimization despite higher maintenance burden.
- VRLA:Valve-regulated designs recombine internal gases to eliminate electrolyte loss. Chilean mining fleet operators specify VRLA for sealed operation in dusty Atacama Desert conditions.
- Maintenance-Free:Calcium-alloy grids reduce water consumption to negligible levels over service life. Colombian urban taxi fleets in Bogotá adopt maintenance-free configurations to minimize downtime in high-utilization operating environments.
- Absorbent Glass Mat:Electrolyte saturation of glass fiber mats enables installation in any orientation without leakage. Premium passenger car platforms across Mexico's automotive manufacturing corridor specify AGM for start-stop compatibility.
Highest shipment volume: Flooded. Steepest expansion trajectory: Absorbent Glass Mat.
Sales Channel:
Geography determines channel efficiency, with dense industrial corridors favoring direct procurement and dispersed rural markets relying on intermediaries.
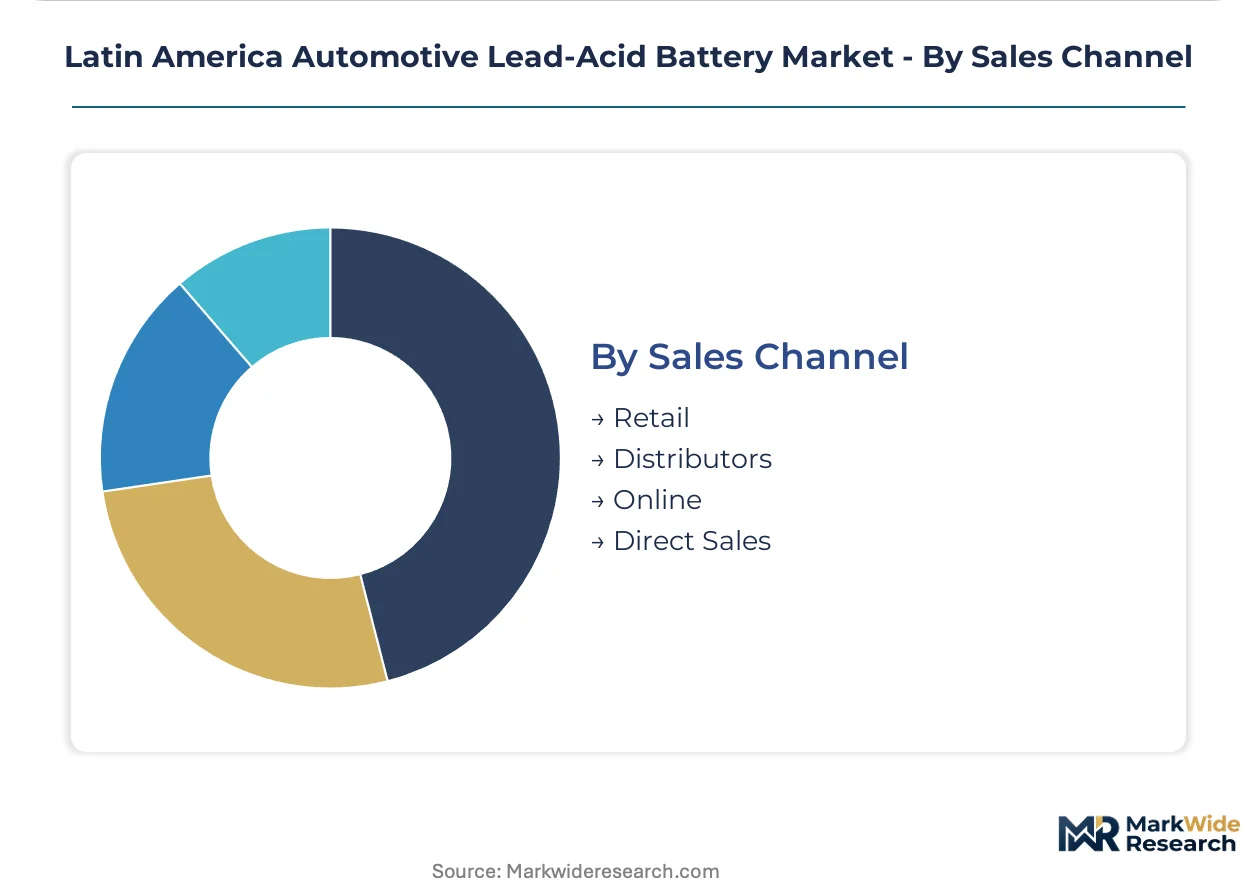
- Retail:Independent auto parts stores and service stations serve immediate replacement needs for individual vehicle owners. São Paulo's industrial suburbs host concentrated retail networks for same-day battery exchange.
- Distributors:Regional warehousing operations extend coverage to secondary cities and rural service centers. Moura Accumulators leverages distributor density to dominate Brazilian aftermarket penetration.
- Online:E-commerce platforms aggregate price comparison for technically confident buyers. Mexican fleet procurement teams increasingly pilot online channels for standardized commercial vehicle specifications.
- Direct Sales:Manufacturer-to-OEM contracts eliminate intermediary margins for high-volume assembly plant supply. Exide Technologies sustains direct relationships with Mercosur vehicle assemblers for just-in-sequence delivery.
Capturing largest transaction value: Distributors. Gaining share fastest: Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Brazil and Mexico's automotive manufacturing corridors, where emission standards and fleet expansion reshape battery procurement. Argentina, Chile, and Colombia present distinct aftermarket dynamics driven by climate conditions and infrastructure gaps.
Brazil
PROCONVE Phase L standards mandate enhanced electrical loads for emission control systems, expanding SLI battery specifications. ANVISA-equivalent environmental regulators enforce lead content disclosure and end-of-life tracking requirements. São Paulo's industrial suburbs host dense authorized dealer networks handling warranty replacements for aging Mercosur fleet vehicles.
Mexico
ANPACT-regulated commercial vehicle operators compress preventive maintenance intervals to minimize freight corridor downtime. NOM-163-SEMARNAT-2013 standards govern recycling obligations and closed-loop collection certification. Querétaro and Puebla assembly plants specify AGM configurations for compact car start-stop systems at accelerating rates.
Argentina
Agricultural machinery fleets in Córdoba and Santa Fe provinces drive seasonal demand for extreme temperature cycling tolerance. The Secretariat of Environment and Sustainable Development administers battery directives segmenting compliance by equipment category. Provincial markets remain underpenetrated by maintenance-free VRLA products designed for long storage periods.
Chile
Mining fleet operators in the Atacama Desert specify sealed VRLA configurations for dusty operating conditions. Mild-hybrid vehicle architectures in Santiago's premium segments pilot lithium-ion substitution for weight reduction. Urban taxi fleets prioritize maintenance-free calcium-alloy grids to minimize high-utilization downtime.
Colombia
Commercial fleet refrigeration systems in long-haul trucking deploy deep cycle units for auxiliary power demands. Bogotá and Medellín operators lack dense authorized distributor networks, creating channel expansion potential. E-commerce platforms aggregate price comparison for technically confident fleet procurement teams.
Latin America Automotive Lead-Acid Battery Market Key Industry Players
Brazilian producers anchor one tier; Japanese and U.S. specialists hold differentiated positions in technology-intensive segments. The supplier base organizes around three archetypes: integrated regional manufacturers with Mercosur distribution density, multinational technology licensors with AGM and VRLA portfolios, and aftermarket-focused accumulators with dense service networks. Consolidation pressures favor backward integration into lead smelting and captive recycling infrastructure.
Within the integrated regional tier, Moura Accumulators exemplifies dense Brazilian aftermarket penetration through authorized dealer networks. GS Yuasa Corporation occupies a position among technology-forward specialists supplying maintenance-free configurations. Exide Technologies anchors the multinational manufacturing footprint with direct OEM relationships across Mercosur assembly plants.
| Leading Market Players |
|---|
| East Penn Manufacturing Company |
| GS Yuasa Corporation |
| Exide Technologies |
| CSB Battery |
| C&D Technologies |
| Johnson Controls |
| Enersys |
| Hitachi Chemical Energy Technology |
| Moura Accumulators |
| Others |
Cost & Logistics Intelligence
London Metal Exchange lead pricing cascades through Latin American battery manufacturing, compressing margin buffers for regional assemblers while amplifying cost differentials between flooded SLI and premium AGM configurations. Brazilian PROCONVE Phase L certification requirements and Mexican NOM-163-SEMARNAT-2013 recycling mandates layer compliance premiums onto landed costs, stratifying procurement economics across Mercosur and North American trade zones.
Pricing Analysis
Volume concentrates in flooded SLI products at economy price points, while margin pools migrate toward AGM and maintenance-free VRLA configurations serving start-stop and commercial cycling applications. Price differentiation rests on certification grade—PROCONVE Phase L versus baseline Phase K—and vertical integration into captive lead smelting. Cost compression in economy flooded tiers is intensifying because of London Metal Exchange volatility, with aftermarket distributors in São Paulo's industrial suburbs exhibiting highest price sensitivity and OEM direct buyers least.
Supply Chain Analysis
Dual-sourcing requirements from Volkswagen, General Motors, and Nissan assembly plants in Puebla and São Paulo mandate multi-supplier qualification for lead dioxide and separator materials. Geographic supply concentration centers on Brazil, Mexico, and China for lead ingot, with polypropylene separators and sulfuric acid electrolyte drawing from domestic Mercosur production. Single-source vulnerability concentrates in specialty AGM glass mat imports. Distribution runs through Moura Accumulators' dense authorized dealer networks across Brazil's long-haul trucking corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin America's automotive lead-acid battery market is consolidating around integrated recyclers and AGM technology specialists, with PROCONVE Phase L compliance costs forcing sub-scale assemblers toward exit or acquisition.
For Market Incumbents: Lock in backward integration into lead smelting and closed-loop collection infrastructure to defend margin position against raw material volatility. Secure PROCONVE Phase L and NOM-163-SEMARNAT-2013 certification ahead of regulatory enforcement windows to disqualify import-dependent competitors from OEM qualification lists. For New Entrants and Emerging Players: Begin with Colombian aftermarket white space in Bogotá and Medellín fleet corridors, where authorized distributor density remains thin relative to Brazilian benchmarks. Pilot digital core-return tracking platforms to satisfy deposit-refund compliance without heavy physical infrastructure investment. For Investors and Strategic Acquirers: The window for entry favors mid-cap recyclers with captive smelter capacity and established Mercosur logistics networks. Monitor lithium-ion 48V pilot deployments in Santiago premium segments as the signal to watch for substitution inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lead Smelting | Captive supply of lead dioxide plates insulates margin from London Metal Exchange volatility. |
| AGM Technology Licensing Agreement | Absorbent glass mat separators unlock start-stop fitments at Querétaro OEM plants. |
| Digital Core-Return Platform Deployment | Barcode-based collection systems satisfy ANVISA-equivalent audit trail requirements. |
| Colombian Distributor Network Expansion | Authorized service density in Bogotá corridors captures fleet maintenance consolidation. |
| PROCONVE Phase L Certification Investment | Enhanced cold cranking amperage specifications qualify suppliers for Brazilian assembly contracts. |
Research Approach
Trade databases, vehicle production registries, and environmental regulatory filings formed the secondary backbone, cross-referenced with primary interviews involving OEM platform engineers, aftermarket distributor operations heads, lead smelter technical directors, and ANPACT fleet procurement managers. Bottom-up and top-down triangulation validated volume estimates across SLI, AGM, gel, and deep cycle product categories.
Bottom-up modeling aggregated country-level vehicle stock data, replacement frequency assumptions by climate zone, and content-per-vehicle specifications by propulsion architecture, while top-down analysis cross-checked against regional lead consumption trends and smelter capacity utilization. CAGRs were derived from regression analysis of historical production correlations with PROCONVE regulatory phase transitions and ANPACT commercial vehicle registration patterns.
Lead price volatility, regulatory timeline divergence between Brazil and Mexico, and lithium-ion substitution acceleration are the dominant revision risks. Deviation in PROCONVE Phase L enforcement timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Battery Binders Market
Batteries
Rear Rack Battery Market
Batteries
USA Forklift Battery Market
Batteries
Atomic Battery Market
Batteries
Smart Diagnostic Battery Charger Market
Batteries
India Lead-Acid Battery Separator for SLI Applications Market
Batteries
Second-Life EV Battery Module Qualification Test Systems Market
Batteries
Li-Ion Pouch Battery Market
Batteries
Battery Voltage Recorder Market
Batteries
Asia-Pacific Dual Carbon Battery Market
Batteries
HIT Battery Market
Batteries
South America Primary Battery Market
Batteries
High Voltage Air-cooled Battery Compartment Market
Batteries
Global Cylindrical Lithium Battery Pack Market
Batteries
Indonesia and Malaysia Lead Acid Battery Market
Batteries
Power Battery Sealant Market